
 Tree Transplanters Market | 2026-2036
Tree Transplanters Market Size, Share, and Industry Trends Forecast 2026-2036
Tree Transplanters Market Analytics
Equipment leasing and rental financing is reconfiguring competitive access in the tree transplanters market. Vermeer Corporation leverages its established dealer financing programs to sustain North American market presence. Big John Manufacturing Co. anchors its position through product specialization in heavy-duty hydraulic systems. Damcon B.V. differentiates via European channel control and technical service density.
Tree transplanters are mechanized implements engineered to extract, transport, and replant established trees with root balls typically ranging from 60 to 300 centimeters in diameter, utilizing curved blade spades or cone-shaped digging mechanisms mounted on skid-steer, tractor, or self-propelled chassis. Their primary commercial purpose centers on urban development mitigation, commercial landscaping, and municipal green infrastructure preservation where manual excavation would compromise root system viability. Hydraulic transplanters command the dominant product position due to lifting capacity requirements for mature specimen trees, while motorized transplanters represent the fastest-expanding category as battery-electric powertrains penetrate municipal and nursery fleets. Nurseries and municipalities constitute the deepest margin pools within end-user segmentation, driven by recurring procurement cycles and specification standardization.
EPA emissions standards for off-road diesel equipment and EU F-Gas Regulation governing hydraulic system refrigerants shape product engineering trajectories and market access conditions in their respective jurisdictions. OSHA tree care safety requirements and ISO 6682 machinery vibration standards further constrain design parameters and operator certification protocols. Stakeholders must monitor evolving electrification mandates and battery-charging infrastructure readiness across primary sales territories to align R&D allocation with forthcoming compliance thresholds.
Market Dynamics
Electrification mandates across municipal procurement departments are compressing diesel equipment replacement cycles and forcing manufacturers to reengineer hydraulic architectures for battery-electric compatibility.
Growth Catalysts
- EU Green Deal urban canopy targets:Municipalities in Germany, the Netherlands, and Belgium face binding tree-planting quotas that accelerate fleet renewal schedules and specification standardization.
- Battery-electric powertrain maturation:Lithium-ion energy density improvements now enable 8-hour operational cycles for municipal nursery operations, eliminating range anxiety barriers that previously constrained adoption.
- Urban heat island mitigation policies:Cities from Phoenix to Singapore mandate mature tree preservation during commercial development, creating recurring demand for large-diameter root ball extraction equipment.
Market Restraints
- Specialized steel alloy supply concentration:High-tensile blade materials depend on Swedish and Japanese metallurgical suppliers, exposing manufacturers to input cost volatility and extended lead times.
- EPA Tier 4 Final compliance costs:Diesel engine after-treatment systems add substantial unit cost premiums that compress margins on entry-level motorized transplanter configurations.
- Manual excavation substitution persistence:Labor-intensive hand-digging remains economically viable for specimens under 80 centimeters root ball diameter in low-wage horticultural regions.
Strategic Opportunities
- India urban greening infrastructure:Smart Cities Mission funding creates procurement pipelines for compact tractor-mounted transplanters suited to narrow streetscapes and tropical root structures.
- Telematics-integrated predictive maintenance:IoT sensor networks enable outcome-based service contracts that shift revenue from equipment sales to recurring platform fees.
- EU F-Gas Regulation phase-down:Hydraulic system refrigerant restrictions accelerate demand for sealed electro-hydraulic architectures that eliminate environmental compliance exposure.
Industry Challenges
- Certified arborist-operator shortage:OSHA tree care safety protocols require specialized training that outpaces vocational program output, constraining fleet utilization rates.
- ISO 6682 vibration standard compliance:Whole-body exposure limits force chassis redesign and damping system investments that extend engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tree Transplanters Market |
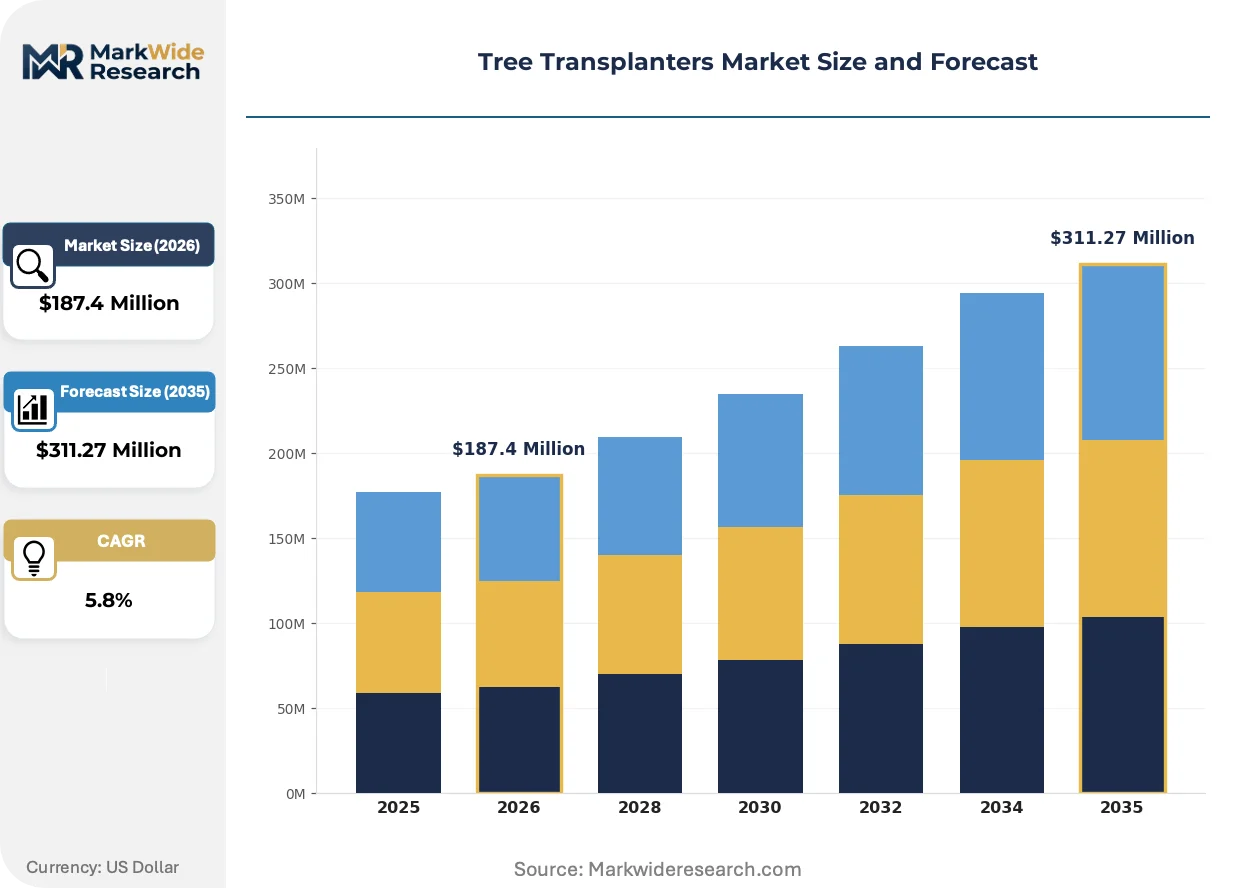
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Transplanters, Hydraulic Transplanters, Motorized Transplanters, Commercial Models End User: Landscapers, Arborists, Municipalities, Nurseries Functionality: Soil Preparation, Planting, Transportation, Maintenance Market Channel: Direct Sales, Online Retail, Distributors, Trade Shows |
| Companies Covered | The Davey Tree Expert Company, Big John Manufacturing Co., Damcon B.V., MPG Machinery Production Group Inc. Co., Xuzhou HCN Machinery Technology Co., Ltd, Bracke Forest AB, G K Machine, Inc., Vermeer Corporation, Dutchman Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tree Transplanters Market Evolving Landscape
Three intersecting forces are restructuring competitive advantage in tree transplanter manufacturing: real-time operational data integration, emissions compliance engineering, and municipal procurement model transformation.
Precision spade positioning systems incorporating LiDAR and machine vision are digitizing root ball geometry mapping. Municipal fleets in Copenhagen and Vancouver deploy these systems to minimize transplant shock and warranty claims. The technology is digitizing operator skill requirements, compressing training periods from months to weeks while standardizing extraction quality across variable terrain conditions.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down through 2030. Manufacturers must redesign hydraulic cooling circuits or transition to CO2-based alternatives. Dutch and German OEMs face the most compressed compliance timelines, accelerating R&D allocation toward fully electric actuator systems that eliminate refrigerant dependencies entirely.
Equipment-as-a-service contracting is displacing traditional capital purchase models among North American municipal buyers. Denver, Austin, and Toronto parks departments now specify operational availability guarantees rather than unit ownership. This restructuring concentrates vendor selection criteria on service network density and parts logistics rather than upfront equipment pricing.
Tree Transplanters Market Segmentation
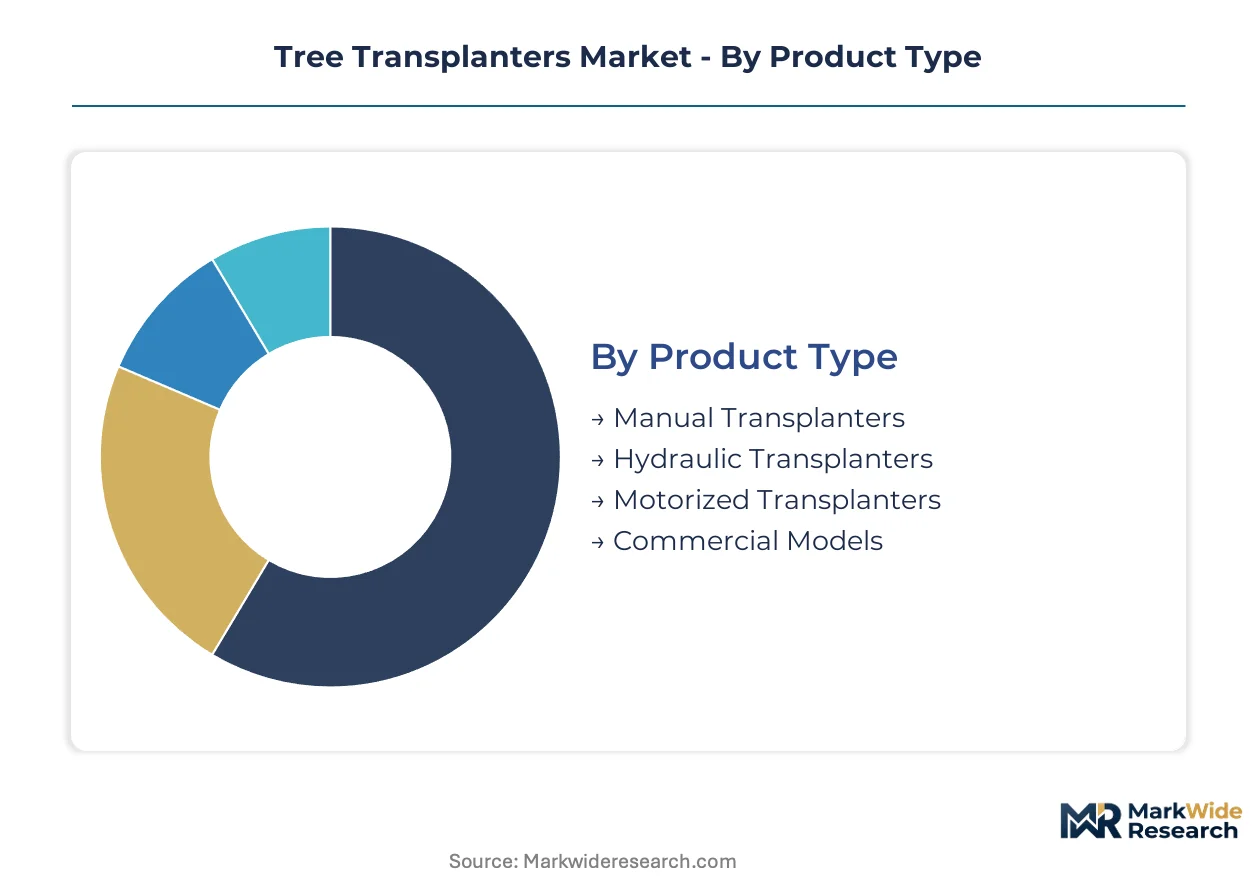
Tree transplanter procurement patterns diverge sharply across operational scales, from handheld tools for residential contractors to self-propelled systems for municipal canopy programs. Understanding these segment boundaries clarifies where specification standardization competes against customization requirements.
Product Type:
Use-case spectrum spans from manual leverage tools for specimen trees under 60 centimeters to hydraulic systems extracting 300-centimeter root balls for urban infrastructure preservation.
- Hydraulic Transplanters:Curved-blade spade systems mounted on skid-steer or dedicated chassis dominate mature-tree extraction for commercial development mitigation. Demand concentrates in the Netherlands where Damcon B.V. and Dutchman Industries anchor specialized manufacturing clusters serving EU Green Deal urban canopy targets.
- Motorized Transplanters:Battery-electric and compact diesel units are gaining procurement share fastest as lithium-ion energy density enables 8-hour operational cycles. Municipal fleets in Germany and Denmark specify these for recurring nursery operations where emissions compliance compresses replacement cycles.
- Manual Transplanters:Lever-operated digging tools for specimens under 80 centimeters root ball diameter remain economically viable in low-wage horticultural regions.
- Commercial Models:Heavy-duty configurations with integrated transportation beds serve large-scale landscaping contractors managing multiple site developments.
The dominant share belongs to Hydraulic Transplanters, while Motorized Transplanters are expanding most quickly as electrification mandates reconfigure municipal procurement specifications.
End User:
Customer type determines margin structure through recurring procurement frequency versus one-time capital expenditure patterns.
- Municipalities:Parks departments and urban forestry divisions generate the deepest margin pools through standardized fleet renewal schedules driven by binding tree-planting quotas. German municipalities under EU Green Deal targets are accelerating procurement timelines.
- Nurseries:Commercial growing operations demand equipment-as-a-service contracting with operational availability guarantees rather than unit ownership, shifting vendor selection toward service network density.
- Landscapers:Independent contractors and regional firms prioritize equipment leasing and rental financing to manage project-based cash flow variability.
- Arborists:Certified specialists require OSHA-compliant configurations with ISO 6682 vibration damping for operator safety certification.
Municipalities command the largest procurement volume, though Nurseries are climbing the fastest through subscription-based fleet management adoption.
Functionality:
Application focus separates integrated systems from point-solution attachments across the transplant workflow.
- Transportation:Integrated root ball containment and vehicle-mounted systems enable specimen viability over extended haul distances for urban heat island mitigation projects.
- Planting:Precision spade positioning with LiDAR and machine vision is digitizing extraction quality in Copenhagen and Vancouver municipal fleets.
- Soil Preparation:Pre-digging auger and conditioning attachments reduce transplant shock for tropical root structures in narrow streetscape applications.
- Maintenance:Post-transplant stabilization and irrigation integration systems support warranty claim reduction for commercial landscaping contracts.
Transportation functionality holds the dominant position, while Planting functionality is gaining share fastest through precision agriculture technology transfer.
Market Channel:
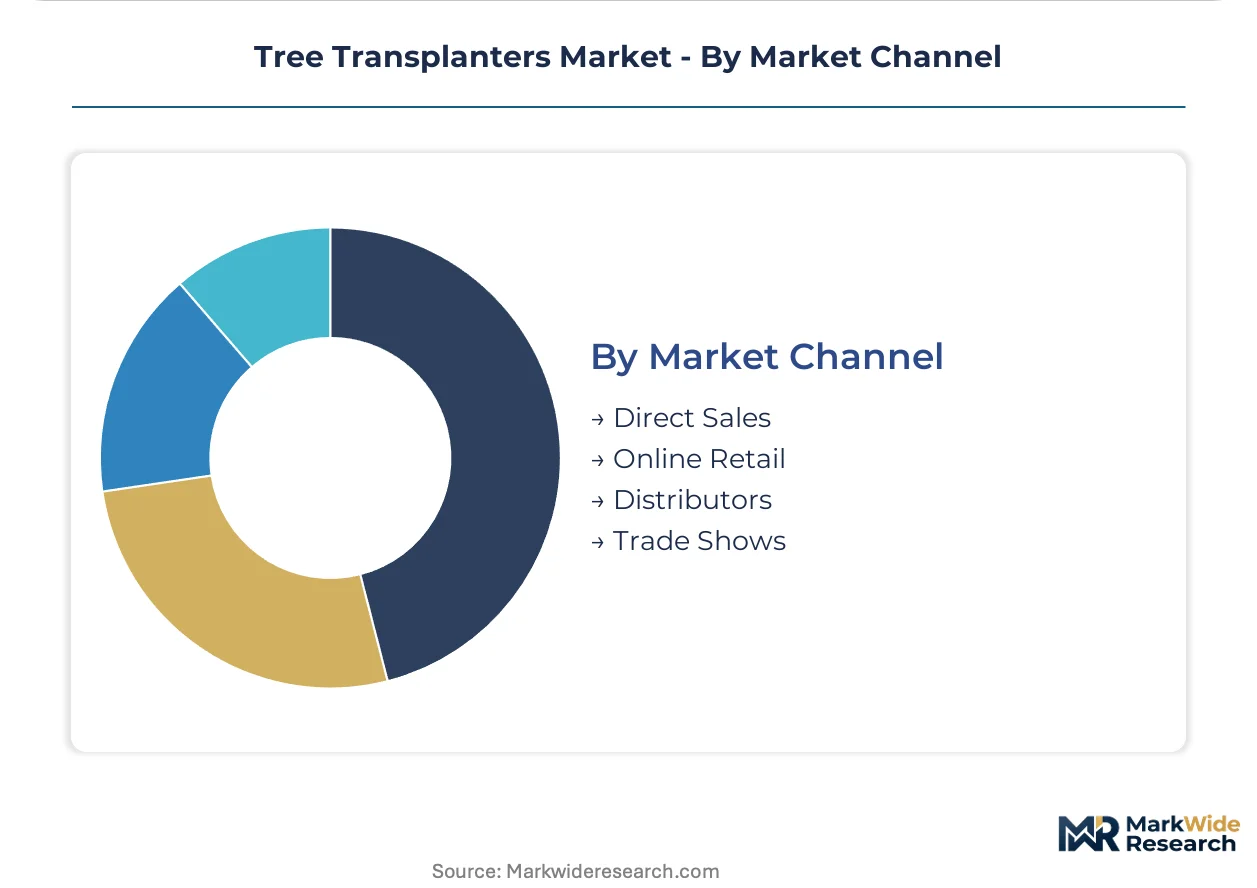
Channel selection reflects equipment complexity, service dependency, and buyer sophistication across transaction types.
- Distributors:Regional dealer networks with technical service density anchor European channel control for hydraulic system maintenance and parts logistics.
- Direct Sales:Manufacturer relationships dominate large municipal fleet procurement with specification customization and financing program integration.
- Trade Shows:Industry exhibitions serve initial vendor qualification and technology demonstration for arborist certification programs.
- Online Retail:E-commerce penetration concentrates in manual transplanter categories and replacement blade consumables.
Distributors maintain the dominant channel position, while Direct Sales are expanding fastest through equipment-as-a-service contracting restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal urban canopy targets are accelerating municipal fleet procurement across multiple jurisdictions. Binding tree-planting quotas in Germany, the Netherlands, and Belgium compress replacement cycles for diesel equipment. Battery-electric powertrain maturation now enables full operational cycles for municipal nursery applications.
Germany
Municipal parks departments in Bavaria and North Rhine-Westphalia face binding urban canopy restoration mandates under EU Green Deal implementation. KBA emissions certification requirements for off-road equipment compress diesel replacement timelines. Stuttgart and Munich anchor specialized dealer networks serving hydraulic system maintenance for municipal fleets.
Netherlands
Damcon B.V. and Dutchman Industries concentrate manufacturing in specialized clusters serving European demand for curved-blade spade systems. EU F-Gas Regulation phase-down through 2030 forces hydraulic cooling circuit redesign. Eindhoven and Randstad municipalities deploy precision spade positioning with LiDAR for root ball geometry mapping.
United States
Denver, Austin, and Toronto parks departments specify equipment-as-a-service contracting with operational availability guarantees. EPA Tier 4 Final compliance costs add substantial unit premiums for diesel engine after-treatment systems. Vermeer Corporation leverages established dealer financing programs across Midwest and Mountain West municipal procurement.
India
Smart Cities Mission funding creates procurement pipelines for compact tractor-mounted transplanters suited to narrow streetscapes. Central Pollution Control Board emissions norms for construction equipment shape import specifications. Maharashtra and Karnataka urban greening programs drive demand for tropical root structure conditioning attachments.
Canada
Vancouver municipal fleets deploy machine vision-integrated systems to minimize transplant shock and warranty claims. Health Canada and PMRA environmental standards govern hydraulic fluid specifications for urban forestry equipment. British Columbia and Ontario nurseries shift toward subscription-based fleet management with service network density as selection criteria.
Tree Transplanters Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans three tiers: established agricultural equipment conglomerates with financing integration, dedicated forestry machinery specialists with hydraulic engineering depth, and regional fabricators serving price-sensitive nursery segments. Two strategic archetypes dominate: integrated service-platform operators capturing municipal equipment-as-a-service contracts, and component-technology specialists licensing precision positioning systems. Competitive moves concentrate on telematics-integrated predictive maintenance offerings and sealed electro-hydraulic architectures eliminating F-Gas compliance exposure.
Among North American service-platform operators, Vermeer Corporation and Big John Manufacturing Co. occupy positions emphasizing dealer network density and heavy-duty hydraulic system specialization respectively. Within European channel control, Damcon B.V. anchors technical service density across Dutch and German municipal procurement. These three exemplify divergent archetype strategies: financing-integrated distribution, product engineering depth, and regional channel dominance.
| Leading Market Players |
|---|
| The Davey Tree Expert Company |
| Big John Manufacturing Co. |
| Damcon B.V. |
| MPG Machinery Production Group Inc. Co. |
| Xuzhou HCN Machinery Technology Co., Ltd |
| Bracke Forest AB |
| G K Machine, Inc. |
| Vermeer Corporation |
| Dutchman Industries Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Dutch hydraulic system manufacturing clusters is compressing supplier pricing power while simultaneously accelerating R&D migration toward battery-electric architectures. This utilization dynamic forces tier-one OEMs to absorb margin erosion on legacy diesel platforms while repositioning premium pricing around sealed electro-hydraulic compliance.
Pricing Analysis
Certification level (ISO 6682/CE marking tier) creates the primary spread between municipal fleet contracts and independent landscaping rentals. Three-tier pricing structure across premium electro-hydraulic, standard diesel-hydraulic, and economy manual-lever configurations dominates transaction architecture. Pricing pressure stems from EPA Tier 4 Final after-treatment cost pass-through on entry-level motorized units. Nurseries exhibit highest price sensitivity through equipment-as-a-service contracting, while municipalities prioritize operational availability guarantees over unit acquisition cost.
Supply Chain Analysis
Tariff exposure between Swedish metallurgical suppliers and Dutch-German manufacturing clusters dominates input cost volatility for high-tensile blade alloys. Component sourcing concentrates in the Netherlands for hydraulic system integration, Germany for precision machining, and Japan for specialized steel formulations. Supply chain risk hinges on single-source vulnerability for lithium-ion battery modules powering municipal electrification mandates. Distribution runs through regional dealer networks with technical service density anchoring European channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracting is reconfiguring this market toward platform-economics logic, where telematics-integrated predictive maintenance creates recurring revenue streams that displace transactional equipment sales.
For Market Incumbents: Pre-empt battery-electric specialist entrants by accelerating sealed electro-hydraulic R&D to eliminate EU F-Gas Regulation compliance exposure. Secure backward integration into lithium-ion battery module sourcing through captive supply agreements with Korean cell manufacturers. Channel control through dealer financing programs remains the priority defensive lever against municipal procurement model transformation. For New Entrants and Emerging Players: Establish a beachhead in India's Smart Cities Mission procurement pipelines for compact tractor-mounted transplanters. Target tropical root structure conditioning attachments as the least penetrated application segment. A telematics-native go-to-market angle bypasses incumbent service network advantages through outcome-based availability contracting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across battery-electric sub-segments as modular powertrain architectures reduce dedicated tooling requirements. Acquisition targets should display precision positioning technology stacks or municipal equipment-as-a-service contract portfolios. The signal to watch is lithium-ion energy density improvement curves enabling full-shift operational cycles without mid-day charging infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Electro-Hydraulic Architecture Development | Eliminates EU F-Gas Regulation refrigerant compliance exposure for Dutch and German OEMs. |
| Telematics-Integrated Predictive Maintenance Platform | Enables outcome-based service contracts with Denver and Toronto parks departments. |
| Compact Tractor-Mounted Product Line Expansion | Captures Smart Cities Mission funding for narrow streetscape applications in Maharashtra. |
| LiDAR-Enabled Precision Spade Positioning System | Reduces transplant shock warranty claims for Copenhagen municipal canopy programs. |
| Dealer Network Technical Service Density Investment | Defends channel control against direct sales equipment-as-a-service restructuring. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with municipal parks department procurement officers, nursery fleet managers, arborist certification program directors, and hydraulic system engineering leads. Secondary validation drew from EPA emissions filings, EU Green Deal implementation progress reports, KBA type-approval databases, and municipal budget appropriation records. Bottom-up equipment shipment tallies were triangulated against top-down canopy restoration investment flows.
Calibration against historical replacement cycle patterns and electrification mandate compliance timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-user category, functionality application, and regional regulatory cluster. CAGRs were derived from equipment procurement velocity indices and municipal fleet renewal schedule acceleration. Industry-specific forecast inputs incorporated lithium-ion energy density improvement curves and EU F-Gas Regulation phase-down compliance cost trajectories.
Stress conditions across steel alloy input cost volatility, certified arborist labor availability, and battery-charging infrastructure readiness were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding binding urban canopy targets and emissions standard enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
Rotavator Market
Agricultural Equipment
Industrial Potato Graders Market
Agricultural Equipment
Grafting Knives Market
Agricultural Equipment
Global Rice Transplanter Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Farm Implements Market
Agricultural Equipment
Pre-Harvest Equipment Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Global Precision Harvesting Market
Agricultural Equipment
Manure Separator Market
Agricultural Equipment
Plow Folding System Market
Agricultural Equipment
Global Fishing Equipments Market
Agricultural Equipment
Soil Mixer Market
Agricultural Equipment
India Color Sorter Market