
 Asia-Pacific Agricultural Tires Market | 2026-2036
Asia-Pacific Agricultural Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Tires Market Outlook
The performance gap between premium radial tires and commodity bias-ply products is expanding across Asia-Pacific farm fleets. Bridgestone Corporation leverages its Japanese manufacturing base to supply high-load radial designs for 200+ horsepower tractors. Balkrishna Industries Limited anchors the aftermarket through its dominant position in bias-ply replacement tires for cost-sensitive Indian and Southeast Asian growers. Apollo Tyres Ltd. competes by sustaining an extensive dealer network across rural Maharashtra and Karnataka.
Asia-Pacific agricultural tires are reinforced rubber structures engineered to carry axle loads exceeding 6,000 kilograms at inflation pressures below 1.5 bar, manufactured through calendering and vulcanization processes to resist soil compaction and stubble puncture in paddy and dryland fields. Radial tires capture the premium tier as farm mechanization shifts toward heavier four-wheel-drive tractors in India and China, while bias tires retain volume leadership among smallholder equipment fleets due to lower first cost and simpler repairability. Tubeless configurations gain traction in harvester and planter segments where downtime reduction justifies higher initial outlay.
India's BIS certification mandates minimum load ratings and tread-depth standards for agricultural radial tires sold domestically. China's GB standards and MIIT energy-efficiency guidelines shape local manufacturing specifications and cross-border trade compliance. Thailand's agricultural machinery subsidy schemes directly influence tire procurement volumes through approved equipment vendor lists. Stakeholders must monitor how Indonesia's emerging tractor-leasing programs redirect tire specification decisions from individual farmers toward centralized fleet operators.
Market Dynamics
India's BIS radial tire certification mandates and Thailand's tractor subsidy programs are compressing replacement cycles across smallholder cooperatives, while mechanization in rice cultivation concentrates demand in Vietnam's Mekong Delta and India's Punjab-Haryana belt.
Growth Catalysts
- Thailand's agricultural machinery subsidy schemes:Approved equipment vendor lists directly accelerate tire procurement volumes through centralized fleet purchasing. Cooperatives upgrade to heavier four-wheel-drive tractors under these programs.
- Mechanization in rice cultivation:Smallholder cooperatives across Vietnam's Mekong Delta and Indonesia's Java Plain drive replacement demand as hand-transplanting gives way to mechanized transplanting and harvesting.
- Radial tire performance advantages:High-load designs for 200+ horsepower tractors reduce soil compaction in paddy fields, justifying premium positioning despite higher first cost versus bias-ply alternatives.
Market Restraints
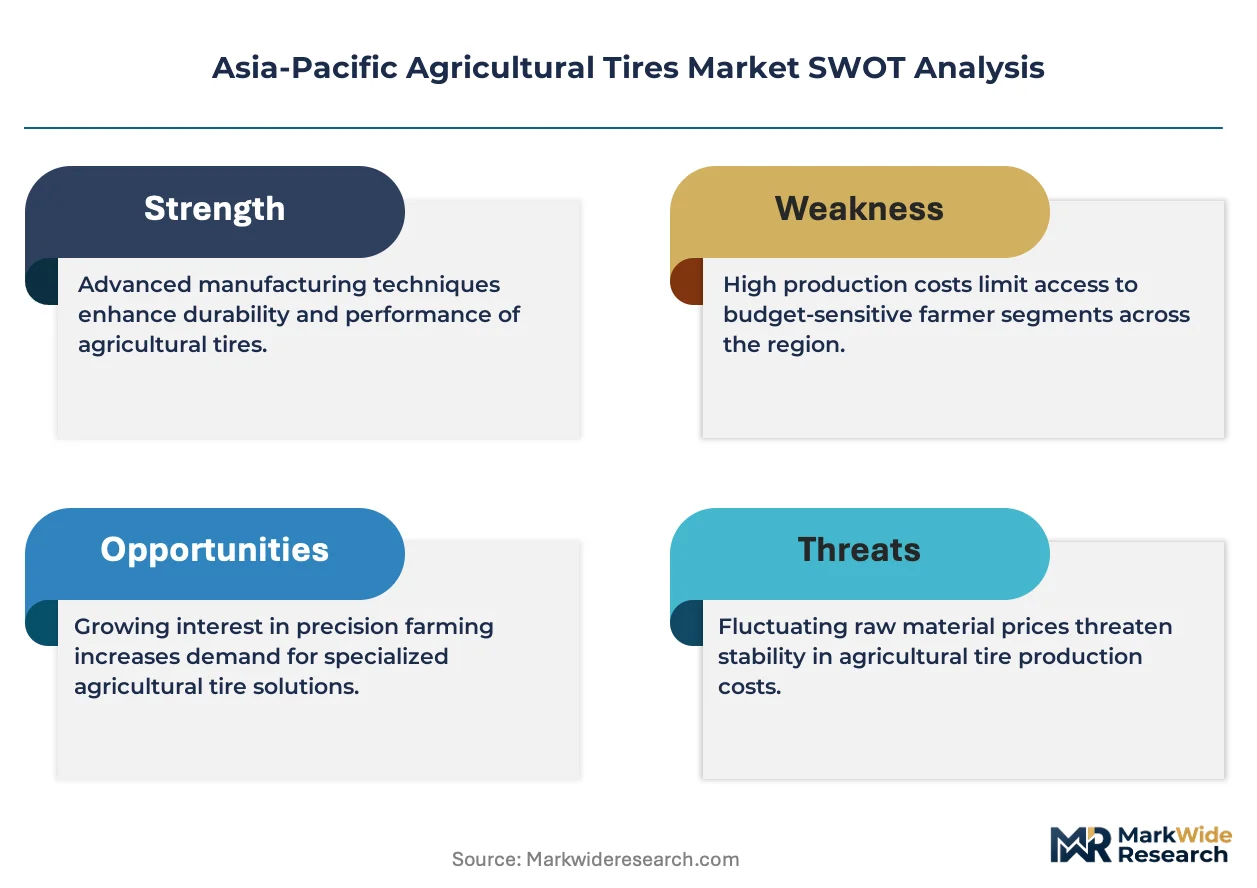
- Natural rubber price volatility:Thailand and Indonesia supply concentration exposes manufacturers to input cost swings that compress margin buffers on fixed-price contracts.
- Bias-ply repairability lock-in:Smallholder fleets retain volume preference for simpler, field-repairable bias constructions despite radial performance superiority.
- China's MIIT energy-efficiency guidelines:Cross-border compliance costs for imported radial tires create friction for non-domestic manufacturers serving Chinese farm equipment OEMs.
Strategic Opportunities
- Indonesia's emerging tractor-leasing programs:Centralized fleet operators redirect tire specification decisions from individual farmers toward professional procurement teams open to radial upgrades.
- Tubeless harvester configurations:Downtime reduction in planter and combine segments justifies higher initial outlay, creating premium aftermarket attach rates.
- India's PLI scheme for auto components:Domestic manufacturing incentives support capacity expansion for radial agricultural tire production serving export markets.
Industry Challenges
- Compound formulation expertise gaps:Stubble puncture resistance in paddy fields requires specialized rubber-silica blends that few regional compounders have mastered.
- BIS certification timeline compression:Load rating and tread-depth testing bottlenecks delay product launches for radial designs targeting India's replacement peak season.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Tires Market |
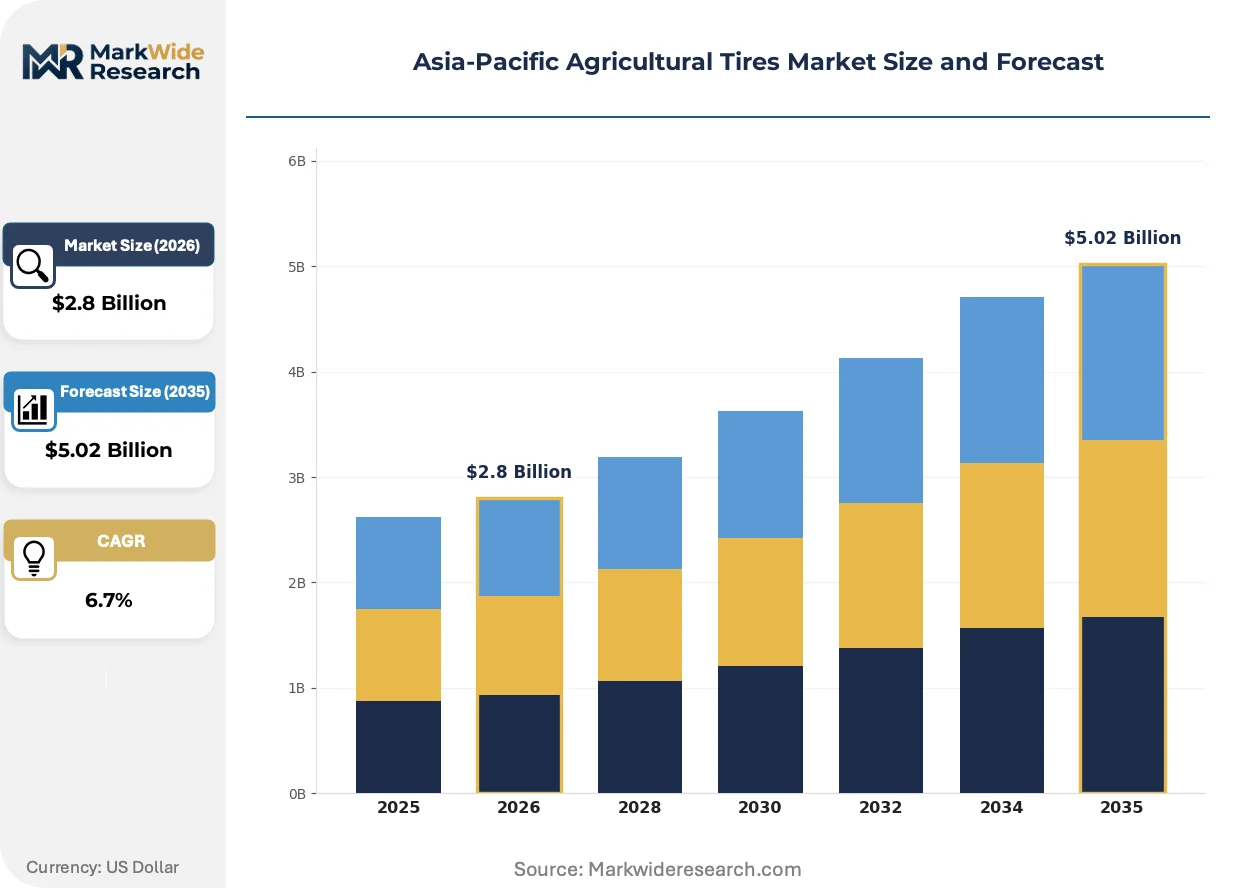
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Inner Tubes End Use: Tractors, Harvesters, Planters, Cultivators Terrain Type: Field, Road, Wetlands, Rocky Tire Size: Low Profile, Standard, Jumbo, Oversized |
| Companies Covered | Bridgestone Corporation, Continental AG, Balkrishna Industries Limited, Michelin, Trelleborg AB, JK Tyre & Industries, Apollo Tyres Ltd., CEAT Ltd., Titan International Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Tires Market Strategic Shifts
Material science advances and procurement centralization are restructuring how farm tires are specified, purchased, and serviced across Asia-Pacific rice and dryland belts.
Steel-belted radial carcasses with reinforced bead bundles are rewriting durability expectations for high-horsepower tractors in India's Punjab-Haryana belt. Large cooperative fleets are adopting these designs at accelerating pace as soil compaction penalties become measurable in yield data. The technology is compressing replacement intervals for premium segments while extending total cost-of-ownership advantages that bias-ply products cannot match.
India's BIS certification mandates for agricultural radial tires establish minimum load ratings and tread-depth standards that reshape domestic manufacturing specifications. Compliance requirements force importers and local producers to retest existing product lines, creating temporary supply tightness. India's replacement market absorbs these certification costs most acutely, with Punjab-Haryana distributors stocking certified inventory ahead of seasonal demand spikes.
Smallholder cooperatives are consolidating equipment procurement through centralized purchasing committees that negotiate fleet-scale tire contracts. Rural dealer networks in Maharashtra and Karnataka face disintermediation pressure as these committees bypass traditional retail channels. Vietnam's Mekong Delta farming corridors demonstrate this shift most visibly, with district-level cooperatives issuing annual tire tenders that specify radial construction for tractors above 100 horsepower.
Asia-Pacific Agricultural Tires Market Segmentation
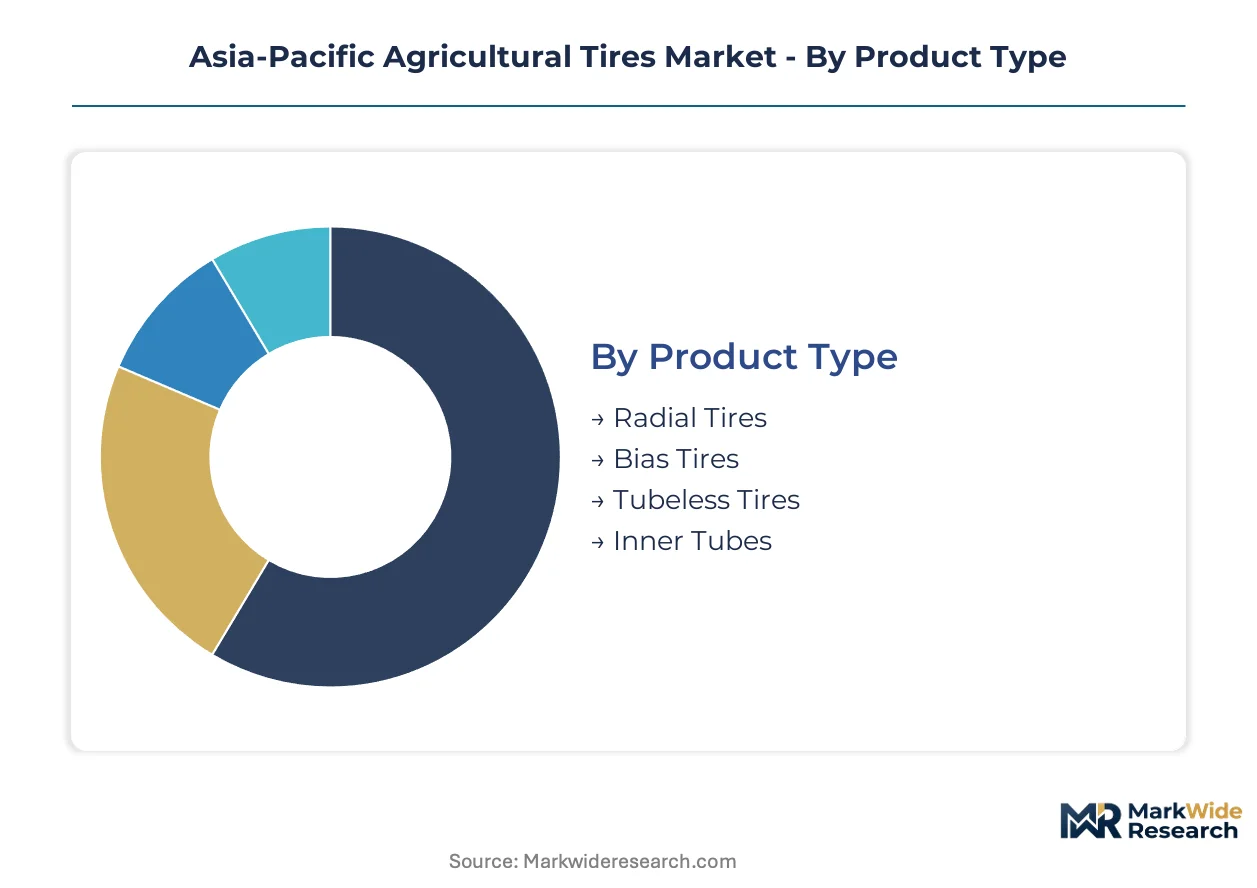
Segmentation in agricultural tires reveals how certification requirements, mechanization intensity, and terrain specificity fragment procurement decisions across Asia-Pacific farming corridors. Understanding these divides exposes where BIS radial mandates, cooperative purchasing power, and stubble-puncture resistance requirements concentrate margin capture.
Product Type:
India's BIS certification mandates minimum load ratings and tread-depth standards exclusively for radial tires, while bias and tubeless categories face lighter compliance burdens. Thailand's tractor subsidy programs specify approved radial designs for fleet procurement, creating tiered approval pathways across construction types.
- Radial Tires:Steel-belted carcasses with reinforced bead bundles carry axle loads exceeding 6,000 kilograms at sub-1.5 bar inflation. Demand concentrates in India's Punjab-Haryana belt where 200+ horsepower tractors face measurable soil compaction penalties in paddy fields. BIS testing bottlenecks compress launch timelines ahead of seasonal replacement peaks.
- Bias Tires:Cross-ply nylon or polyester cord constructions enable simpler field repairs using basic vulcanization kits. Smallholder fleets across Vietnam's Mekong Delta and Indonesia's Java Plain retain volume preference due to lower first cost and repairability lock-in, despite radial performance superiority.
- Tubeless Tires:Eliminate inner tube failure modes through airtight rim sealing and self-sealing liner compounds.
- Inner Tubes:Butyl rubber bladders sustain demand in legacy tractor populations and budget-constrained replacement cycles.
Bias tires sit at the top of the volume ranking, with radial tires climbing the fastest as cooperative procurement committees mandate certified constructions for horsepower thresholds above 100.
End Use:
Equipment type determines load-cycle intensity, downtime cost exposure, and whether centralized fleet operators or individual farmers control tire specification decisions.
- Tractors:Dominant axle-load category spanning 50-400 horsepower ranges with four-wheel-drive configurations driving radial adoption in India's upgrade cycle.
- Harvesters:Seasonal intensity and downtime sensitivity justify tubeless configurations where puncture-related field delays exceed premium tire cost premiums. Vietnam's Mekong Delta cooperatives specify radial harvester tires in annual procurement tenders.
- Planters:Precision seeding equipment demands flotation tires to minimize soil disturbance during critical planting windows.
- Cultivators:Secondary tillage implements tolerate bias-ply constructions due to lower speed requirements and reduced load severity.
Tractor applications command the deepest volume base, while harvester specifications are expanding most quickly as mechanized rice transplanting displaces hand labor.
Terrain Type:
Surface conditions dictate tread compound formulation, lug pattern geometry, and carcass reinforcement requirements across Asia-Pacific rice belts and dryland farming zones.
- Field:General agricultural surfaces requiring balanced traction and flotation characteristics.
- Road:Higher-speed transport between plots demands heat-resistant tread compounds and reinforced shoulders to combat shoulder wear.
- Wetlands:Paddy field operations in Vietnam's Mekong Delta and Indonesia's Java Plain require specialized rubber-silica blends for stubble puncture resistance. Compound formulation expertise gaps limit qualified regional suppliers.
- Rocky:Abrasive dryland conditions in India's Deccan Plateau necessitate cut-resistant tread compounds and thicker undertread gauges.
Field-rated tires maintain volume leadership, with wetland specifications gaining share fastest as mechanized rice cultivation penetrates previously manual transplanting zones.
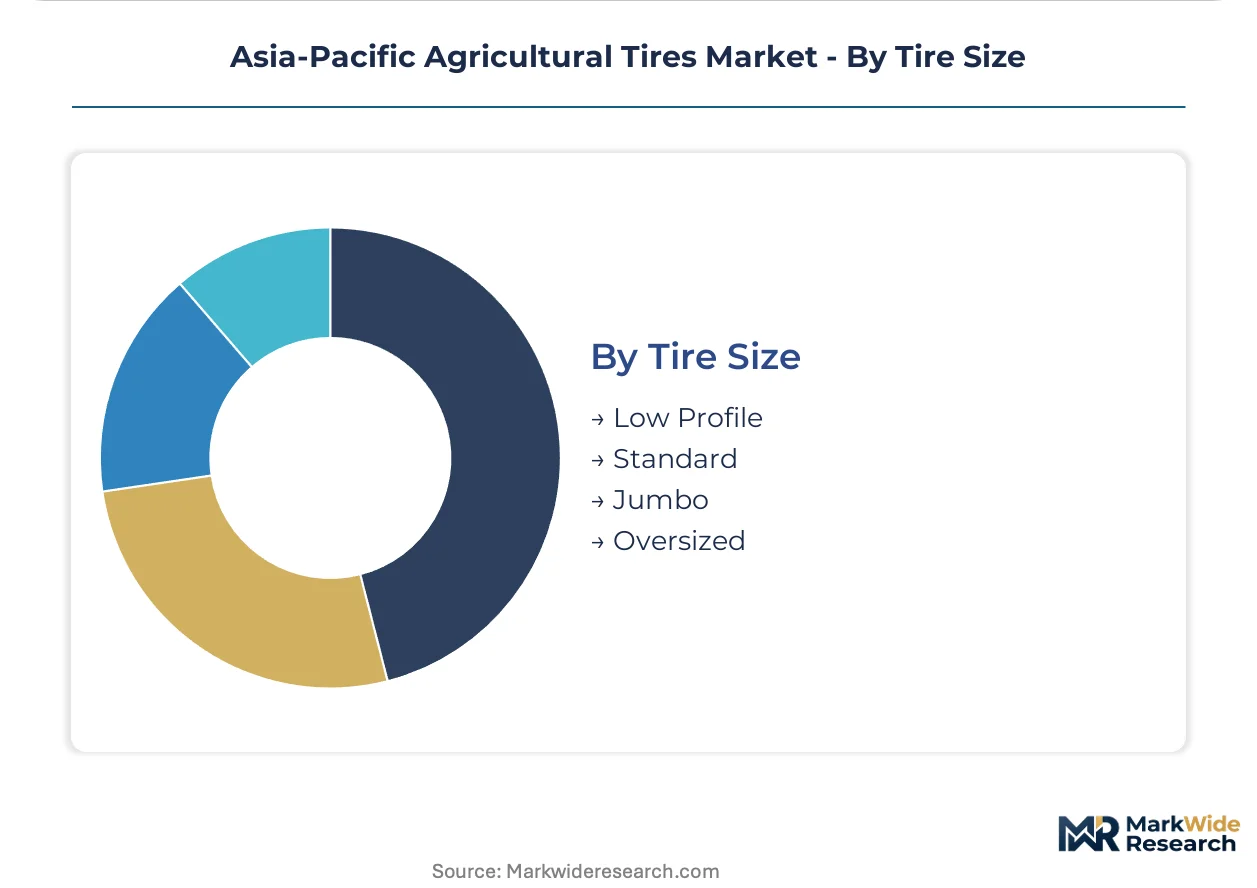
Tire Size:
Dimension categories align with horsepower class and equipment weight, with larger sizes correlating to radial construction mandates and cooperative fleet procurement.
- Low Profile:Reduced sidewall height improves stability on higher-speed transport applications and narrow-row cropping systems.
- Standard:Mid-range dimensions serve the bulk of smallholder equipment fleets across Maharashtra and Karnataka dealer networks.
- Jumbo:High-flotation designs for 200+ horsepower tractors reduce ground pressure in India's Punjab-Haryana paddy belt. BIS certification requirements apply most stringently to this size class.
- Oversized:Specialized harvester and heavy four-wheel-drive tractor fitments where downtime reduction justifies procurement through centralized cooperative tenders rather than individual farmer decisions.
Standard sizes anchor volume rankings, with jumbo dimensions showing the steepest expansion trajectory as heavier tractor fleets displace smaller equipment across Thai subsidy programs and Indonesian leasing schemes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized rubber compounders and tire engineers concentrate in Japan's industrial corridors, India's manufacturing belts, and Thailand's Eastern Economic Zone, anchoring regional production capacity for agricultural tire fabrication.
India
Punjab-Haryana farming cooperatives drive radial tire upgrades for 200+ horsepower tractor fleets. BIS certification mandates minimum load ratings and tread-depth standards, compressing product launch timelines ahead of seasonal peaks. Maharashtra and Karnataka dealer networks face disintermediation pressure as cooperative procurement committees consolidate purchasing power.
China
Four-wheel-drive tractor mechanization accelerates radial adoption across Shandong and Henan agricultural machinery manufacturing clusters. MIIT energy-efficiency guidelines shape cross-border compliance costs for imported radial tires serving domestic OEMs. GB standards for agricultural tires establish manufacturing specifications that influence regional trade patterns.
Thailand
Central Plains rice belt cooperatives upgrade tractor fleets through agricultural machinery subsidy schemes with approved equipment vendor lists. Eastern Economic Zone tire fabricators supply radial designs for subsidized four-wheel-drive configurations. Fleet procurement centralization redirects specification decisions from individual farmers toward professional procurement teams.
Vietnam
Mekong Delta mechanized transplanting displaces hand labor, driving replacement demand for harvester and planter tire configurations. District-level cooperatives issue annual procurement tenders specifying radial construction for tractors above 100 horsepower. Stubble puncture resistance requirements in paddy fields limit qualified regional compound suppliers.
Indonesia
Java Plain smallholder cooperatives transition from manual to mechanized rice cultivation, expanding tire replacement cycles. Emerging tractor-leasing programs redirect specification decisions toward centralized fleet operators open to radial upgrades. Compound formulation expertise gaps for wetland tread compounds constrain local supply options.
Asia-Pacific Agricultural Tires Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the Asia-Pacific agricultural tire market. Integrated rubber compounders with captive polymer supply chains face competition from tire specialists outsourcing carcass fabrication to contract manufacturers. The market structures around three archetypes: Japanese and European multinationals with radial technology leadership, Indian subcontinent manufacturers dominating bias-ply replacement volumes, and emerging Chinese producers scaling steel-belted capacity. Dominant competitive moves include backward integration into natural rubber processing and cooperative fleet tender participation.
Within the multinational tier, Bridgestone Corporation and Continental AG exemplify integrated producers with regional manufacturing footprints. Balkrishna Industries Limited occupies a position as the dominant bias-ply aftermarket supplier for cost-sensitive Indian and Southeast Asian grower fleets. Apollo Tyres Ltd. anchors a dealer-network-dependent archetype across rural Maharashtra and Karnataka distribution corridors.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Continental AG |
| Balkrishna Industries Limited |
| Michelin |
| Trelleborg AB |
| JK Tyre & Industries |
| Apollo Tyres Ltd. |
| CEAT Ltd. |
| Titan International Inc. |
| Others |
Value Chain & Pricing Dynamics
Thailand's tractor subsidy programs and India's BIS radial certification mandates are forcing supply chains to absorb compliance costs while pricing power concentrates with certified manufacturers serving cooperative procurement committees.
Pricing Analysis
Service bundling separates tire-plus-installation packages from bare-product transactions across rural dealer networks. Three-tier pricing structure across premium radial, standard bias-ply, and economy retread levels reflects BIS certification grade and after-sales service inclusion. Cost compression in the economy tier is intensifying because smallholder cooperatives negotiate fleet-scale volume discounts. Dealer-dependent farmers in Maharashtra and Karnataka exhibit highest price sensitivity, while centralized procurement committees in Vietnam's Mekong Delta prioritize total cost-of-ownership over first cost.
Supply Chain Analysis
Dual-sourcing requirements from cooperative procurement committees and OEM vendor qualification programs mandate multi-supplier rubber compound and carcass fabrication relationships. Manufacturing gravity centers on Thailand, India, and China, with natural rubber feedstock drawing from Indonesian and Thai plantations. Single-source vulnerability concentrates in specialized rubber-silica blend formulations for wetland stubble resistance. Distribution runs through cooperative procurement committees bypassing traditional retail channels, alongside authorized dealer networks serving individual smallholders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radial tire premiumization and input cost discipline are expanding margin capture for manufacturers serving cooperative fleet procurement, while bias-ply commoditization pressures require defensive positioning.
For Market Incumbents: Hedge against bias-ply margin erosion by accelerating BIS-certified radial capacity expansion in India's manufacturing belts. Secure captive natural rubber processing through backward integration into Thai and Indonesian plantation networks. Defensive patent positioning in stubble-puncture compound formulations limits emerging entrant replication.
For New Entrants and Emerging Players: Capture white-space in Indonesia's emerging tractor-leasing programs where centralized fleet operators redirect specification decisions toward professional procurement teams. Target tubeless harvester configurations in Vietnam's Mekong Delta cooperatives where downtime reduction justifies premium positioning. Pursue cooperative tender participation as primary go-to-market channel rather than dealer network buildout.
For Investors and Strategic Acquirers: Asymmetric upside sits with compound formulation specialists possessing rubber-silica blend expertise for wetland applications. Long-term viability favors manufacturers with demonstrated BIS certification throughput and cooperative fleet contract visibility. Monitor Indonesia's tractor-leasing program expansion rate as inflection indicator for procurement centralization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| BIS Certification Investment | Accelerates product launch timelines ahead of India's seasonal replacement peaks. |
| Backward Integration into Natural Rubber | Insulates margin buffers from Thai and Indonesian input cost volatility. |
| Cooperative Fleet Tender Participation | Bypasses dealer network disintermediation pressure in Maharashtra and Karnataka. |
| Tubeless Configuration Development | Captures premium attach rates in Vietnam's harvester and planter segments. |
| Wetland Compound R&D Partnership | Addresses expertise gaps limiting qualified regional stubble-puncture suppliers. |
Study Parameters
Direct dialogue with cooperative procurement managers, tire compound R&D directors, OEM agricultural machinery procurement leads, and rural dealer network operators grounded qualitative findings in operational realities. Secondary validation drew from BIS certification registries, Thailand's agricultural machinery subsidy scheme vendor lists, customs trade data for natural rubber flows, and MIIT energy-efficiency guideline disclosures. Bottom-up equipment fleet sizing and top-down macroeconomic indicators underwent triangulation to anchor volume estimates.
Bottom-up modeling segmented demand across radial, bias-ply, and tubeless construction types, horsepower class thresholds, and terrain-specific compound requirements. Value outputs reflect manufacturer pricing stratification across certified premium and uncertified economy tiers. CAGRs were derived from equipment mechanization penetration curves and replacement cycle compression effects. Key forecast inputs include BIS certification timeline bottlenecks and Indonesian tractor-leasing program rollout velocity.
Natural rubber price volatility, BIS testing capacity constraints, and subsidy program funding continuity are the dominant revision risks to the outlook. Deviation in Thai or Indonesian plantation output would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Smart Egg Incubators Market
Agricultural Equipment
Tree Trimmers Market
Agricultural Equipment
Indoor Farming Equipment Market
Agricultural Equipment
Commercial Vegetable Chopper Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Bucking Machine Market
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Battery Powered Cultivators Market
Agricultural Equipment
Aquatic Weed Harvester Market
Agricultural Equipment
Agricultural Ventilation Fans Market
Agricultural Equipment
Sheep Shearing Equipment Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Feller Buncher Market
Agricultural Equipment
Intelligent Milking Robot Market