
 Garden Tools Market | 2026-2036
Garden Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Garden Tools Market Analysis
Lithium-ion battery chemistry is repositioning cost structures across cordless equipment lines. Robert Bosch GmbH leverages its power-tool battery platform to extend runtime specifications in garden applications. Husqvarna AB anchors its commercial portfolio with professional-grade battery architecture. STIHL Holding AG & Co. KG differentiates through captive fuel-cell R&D alongside its electric transition.
Garden tools comprise manually operated and motorized implements designed for soil cultivation, vegetation management, and landscape maintenance, typically specified by blade hardness measured on the Rockwell C scale and motor displacement in cubic centimeters for combustion units. Power tools command the dominant revenue share as cordless motor platforms replace two-stroke engines. Hand tools retain stable margin pools in premium forged-steel segments where professional landscapers specify Swedish or Japanese blade metallurgy.
EPA emissions standards for small spark-ignition engines and the EU F-Gas Regulation constrain combustion-engine product lifecycles, redirecting manufacturer R&D budgets toward electrification compliance. OSHA noise-exposure limits in commercial landscaping additionally accelerate battery-equipment substitution in fleet procurement decisions. Stakeholders must weigh battery-platform interoperability against proprietary ecosystem lock-in when selecting supplier partnerships.
Market Dynamics
Battery-platform standardization across professional landscaping fleets is compressing product lifecycles and forcing manufacturers to choose between proprietary ecosystems and interoperable architectures. The EU F-Gas Regulation and OSHA noise-exposure limits are accelerating this transition away from two-stroke combustion engines.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants and combustion-engine restrictions in commercial landscaping creates compliance-driven replacement cycles for professional-grade equipment.
- Lithium-ion energy density improvements:Advances in cell chemistry are extending runtime specifications for cordless chainsaws and ride-on mowers, satisfying commercial duty-cycle requirements previously reserved for gasoline units.
- German commercial horticulture:Concentrated demand from landscape maintenance contractors in Baden-Württemberg and Bavaria is validating battery-platform economics at fleet scale.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs for battery packs create margin compression for mid-tier equipment manufacturers without captive cell supply.
- Semiconductor allocation constraints:Power electronics shortages for brushless motor controllers delay production ramps for new cordless platform launches.
- Rockwell C scale blade metallurgy:Premium forged-steel specifications from Swedish and Japanese suppliers concentrate high-performance hand tool sourcing in limited geographic corridors.
Strategic Opportunities
- India urban greening mandates:Municipal park expansion and highway median maintenance programs create entry points for battery-powered equipment in price-sensitive procurement environments.
- Battery-platform interoperability:Cross-brand battery compatibility standards enable aftermarket service ecosystems and reduce fleet operator total cost of ownership.
- Fuel-cell hybrid architectures:Hydrogen fuel-cell range extenders for commercial ride-on equipment address duty-cycle gaps that pure battery platforms cannot yet close.
Industry Challenges
- Brushless motor controller firmware:Embedded software development talent scarcity delays product certification timelines for smart power management features.
- ISO 11806 machinery safety:Harmonized international standards for portable handheld equipment require redesign cycles for blade guards and emergency stop systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Garden Tools Market |
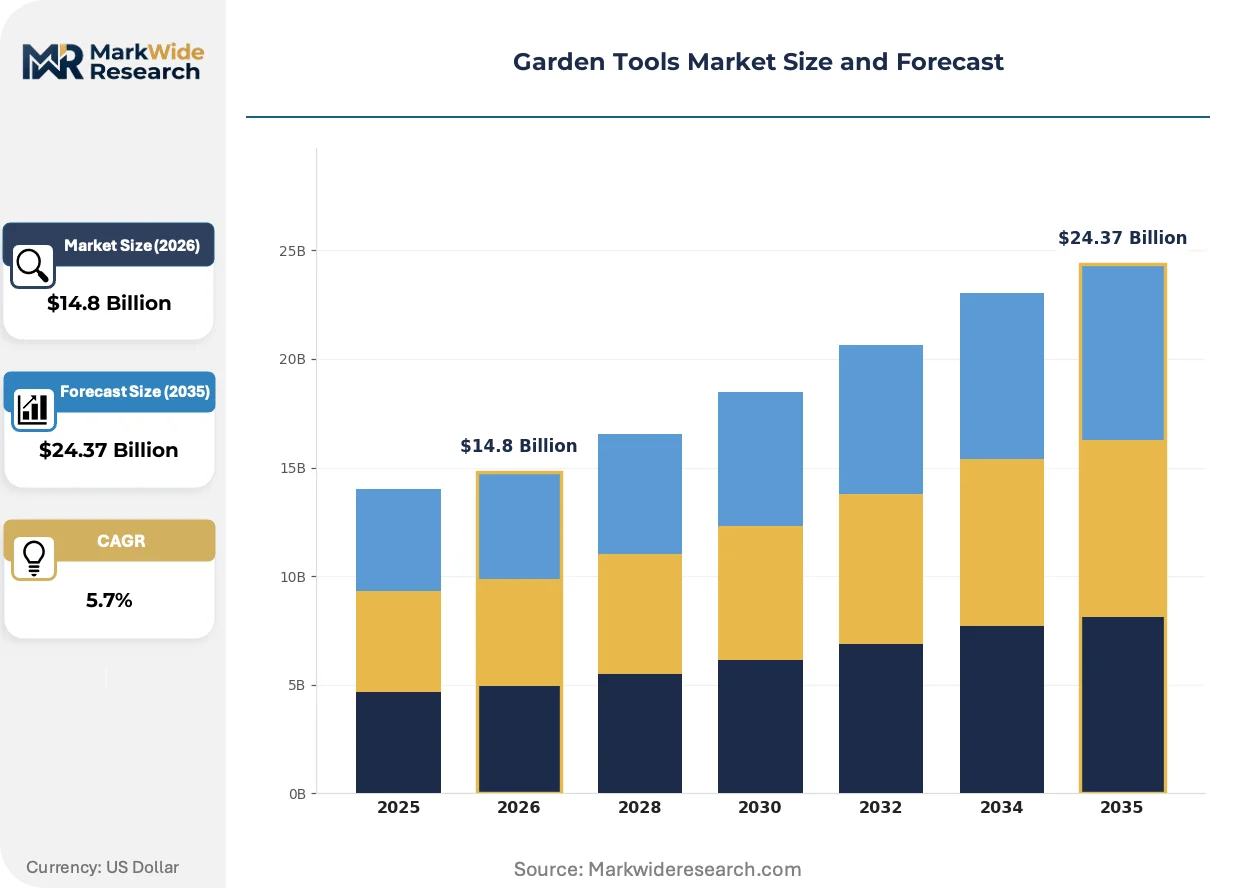
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Tools, Power Tools, Lawn Equipment, Watering Tools Material: Steel, Aluminum, Plastic, Wood End User: Professional Landscapers, Homeowners, Garden Centers, Agriculture Distribution Channel: Online Retail, Home Improvement Stores, Garden Supply Shops, Distributors |
| Companies Covered | Stanley Black & Decker, Husqvarna AB, The Toro Company, Deere & Company, Robert Bosch GmbH, American Honda Motor Co., Inc., Briggs & Stratton Corporation, KUBOTA Corporation, STIHL Holding AG & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Garden Tools Market Emerging Trajectories
Electrification is fragmenting competitive positioning between legacy engine manufacturers pivoting to batteries and power-tool specialists extending platforms into outdoor applications. Three converging developments are determining which architecture standards prevail.
Brushless DC motor platforms are consolidating control over professional equipment specifications. These motors eliminate commutator maintenance and enable software-defined torque curves. Commercial landscapers in Germany and the Netherlands are specifying brushless units for fleet standardization. The technology is consolidating runtime performance gaps between cordless and combustion alternatives.
The EU F-Gas Regulation and EPA small spark-ignition engine standards are compressing combustion-engine product lifecycles. Manufacturers must redirect R&D budgets toward electrification compliance or exit commercial segments. Professional-grade chainsaws and backpack blowers face the steepest certification hurdles, forcing portfolio rebalancing toward battery-native designs.
Equipment-as-a-service contracting is displacing capital purchase models in municipal and corporate groundskeeping. Landscape service providers in Scandinavia are bundling maintenance, battery swap logistics, and uptime guarantees into subscription pricing. This shifts buyer evaluation criteria from unit cost to total operating expenditure and residual value risk allocation.
Garden Tools Market Segmentation
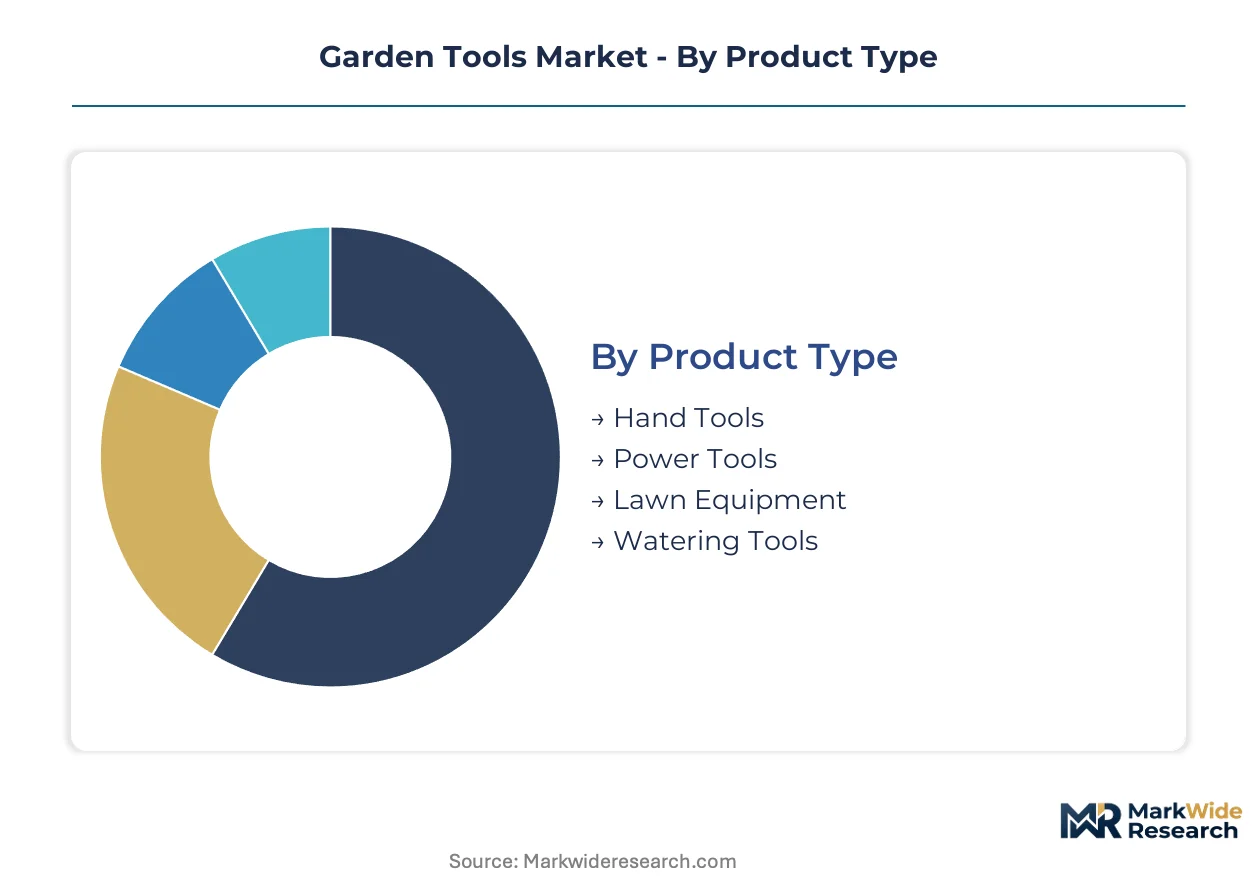
Segmentation in garden tools determines procurement economics, margin architecture, and compliance exposure across divergent user workflows. Professional-grade specifications diverge sharply from consumer tiers in metallurgy standards, battery-platform requirements, and service-life expectations. Understanding these divides enables precise positioning against regulatory deadlines and fleet-replacement cycles.
Product Type:
Supply concentration in motor controllers and forged-steel blade sourcing creates divergent margin structures across product categories, with cordless power platforms capturing disproportionate R&D allocation from manufacturers.
- Hand Tools:Implements including spades, shears, and rakes rely on Rockwell C-scale blade hardness specifications, typically 54-58 HRC for professional-grade Swedish or Japanese steel. German commercial horticulture contractors specify these for precision tasks where motorized equipment risks root damage, though sourcing concentrates in limited metallurgical corridors.
- Power Tools:Cordless chainsaws, string trimmers, and hedge cutters run on lithium-ion platforms with brushless DC motors eliminating commutator maintenance. Professional landscapers in the Netherlands and Germany are standardizing these for OSHA noise-compliance and EU F-Gas Regulation alignment, compressing two-stroke engine replacement cycles.
- Lawn Equipment:Ride-on mowers and robotic units address sustained-duty vegetation management.
- Watering Tools:Hoses, sprinklers, and irrigation controllers serve residential and municipal greening programs.
Today's leader: Power Tools. Tomorrow's challenger: Lawn Equipment.
Material:
Cost tier stratification in raw materials maps directly to end-user price sensitivity and replacement-frequency expectations across professional and consumer segments.
- Steel:Carbon and alloy grades dominate blade production, with forged variants commanding premium positioning in professional channels. The EU F-Gas Regulation's engine-phaseout timeline is redirecting steel-alloy R&D toward battery-housing durability specifications rather than combustion-engine component thermal tolerance.
- Aluminum:Die-cast and extruded forms reduce chassis weight for handheld cordless equipment, enabling extended operator duty cycles. Scandinavian equipment-as-a-service providers specify aluminum-framed units for subscription-fleet weight optimization and residual value retention.
- Plastic:Glass-reinforced polymers substitute for metal in housings and handles across economy-tier consumer lines.
- Wood:Hardwood handles persist in premium hand-tool segments for ergonomic preference and aesthetic differentiation.
Steel retains volume leadership. Aluminum is gaining share fastest in cordless-platform chassis applications.
End User:
Application-specific duty cycles and compliance exposure create four distinct procurement behaviors with divergent vendor-selection criteria.
- Professional Landscapers:Fleet operators in Baden-Württemberg and Bavaria validate battery-platform economics at scale, specifying brushless motor architectures and interchangeable battery systems across tool categories. OSHA noise-exposure limits and municipal emissions restrictions in German cities are accelerating combustion-engine retirement timelines.
- Homeowners:Residential purchasers prioritize unit cost over runtime specifications, though cordless penetration is rising in suburban markets with noise-ordinance constraints.
- Garden Centers:Retail and nursery operations require durable hand tools for daily maintenance tasks.
- Agriculture:Vineyard and orchard operators specify specialized pruning and cultivation implements.
Professional Landscapers anchor current revenue. Homeowners present the steepest expansion trajectory as cordless price-performance ratios improve.
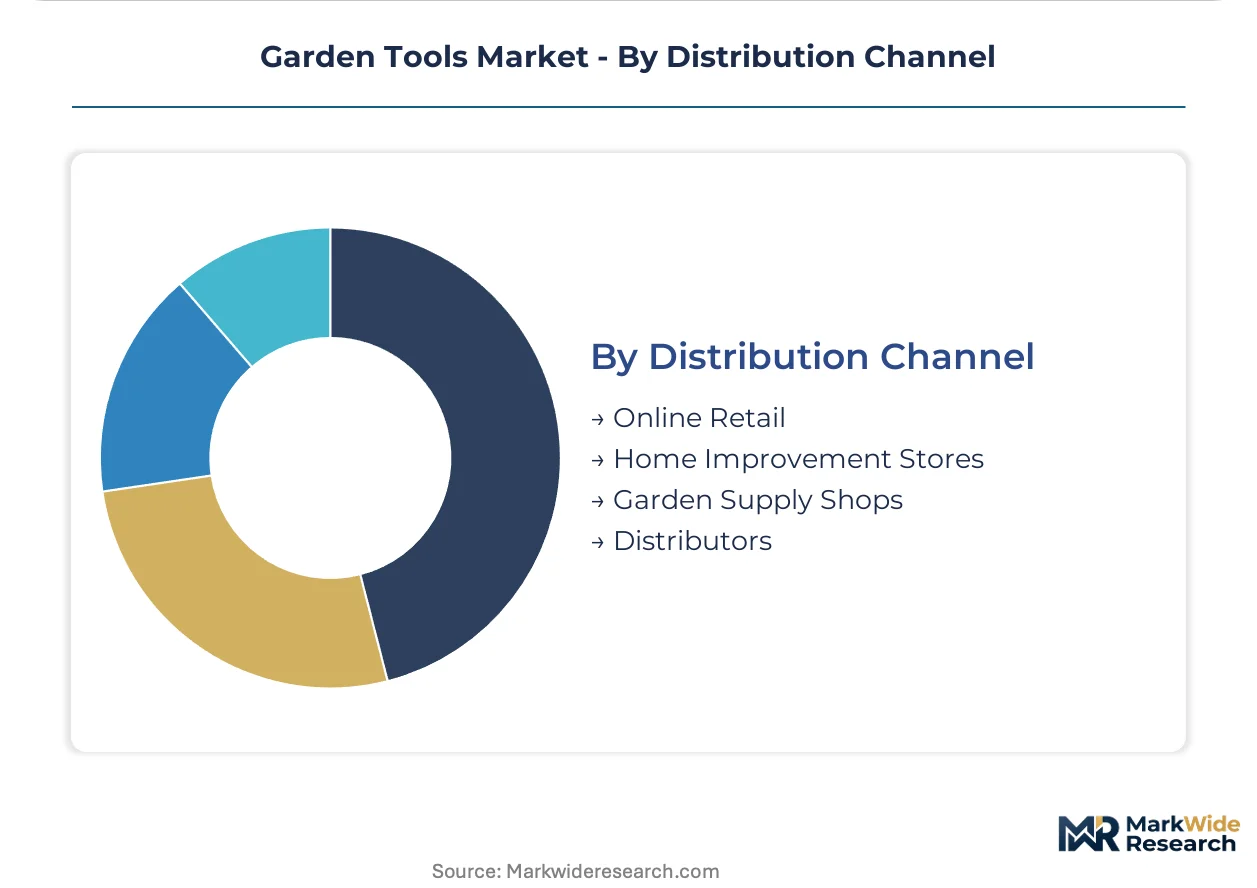
Distribution Channel:
Customer-type and geography variables determine channel economics, with fleet procurement favoring direct relationships and residential sales fragmenting across digital and physical touchpoints.
- Online Retail:E-commerce platforms capture consumer replacement-cycle purchases and accessory replenishment, with battery-platform compatibility search terms driving conversion. Professional fleet buyers in Germany increasingly use B2B portals for standardized requisitioning across multi-site operations.
- Home Improvement Stores:Big-box retailers serve homeowner project-based demand and small-landscaper emergency replacement needs.
- Garden Supply Shops:Independent dealers provide specialist advice and premium hand-tool curation.
- Distributors:Wholesale channels manage fleet-scale procurement and service contracts for municipal and corporate groundskeeping.
Home Improvement Stores hold present volume. Online Retail is climbing the fastest in battery-platform accessory replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's commercial horticulture cluster anchors European demand validation for battery-platform fleet economics, with professional landscapers in Stuttgart and Karlsruhe specifying interchangeable lithium-ion architectures across tool categories.
Germany
Landscape maintenance contractors in Bavaria and Baden-Württemberg validate cordless platform economics at fleet scale, specifying brushless motor systems for OSHA-aligned noise compliance. The EU F-Gas Regulation's combustion-engine phaseout redirects municipal procurement in Berlin and Hamburg toward battery-native equipment. Stuttgart's industrial corridor concentrates battery-pack assembly for professional-grade chainsaw and mower platforms.
United States
EPA small spark-ignition engine standards compress product lifecycles for gasoline-powered handheld equipment, accelerating fleet turnover in commercial landscaping. OSHA noise-exposure limits in California and New York metropolitan areas drive battery-equipment substitution in corporate groundskeeping contracts. The Pacific Northwest's municipal park systems specify zero-emission maintenance protocols for urban greening programs.
Netherlands
Equipment-as-a-service contracting displaces capital purchases among Scandinavian-influenced landscape service providers, bundling maintenance and battery logistics into subscription pricing. REACH compliance requirements for chemical handling in greenhouse operations align procurement with sustainable equipment specifications. Amsterdam's metropolitan green infrastructure maintenance validates battery-platform interoperability standards at fleet scale.
China
MIIT battery-industry development guidelines support domestic cell manufacturing scale for export-oriented garden equipment assembly. Dual carbon goals redirect municipal procurement in Yangtze River Delta cities toward electrified maintenance fleets. Zhejiang and Jiangsu provinces concentrate die-cast aluminum chassis production for cordless-platform weight optimization.
India
Urban greening mandates in Delhi-NCR and Bengaluru municipal jurisdictions create procurement entry points for price-sensitive battery-powered equipment. The PLI scheme for advanced chemistry cell manufacturing builds domestic battery-pack assembly capacity for landscaping applications. Maharashtra's highway median maintenance programs specify cordless equipment for noise-restricted urban corridors.
Garden Tools Market Vendor Landscape
Global majors compete with regional champions across battery-platform standardization and metallurgy sourcing dimensions. The vendor base stratifies between legacy engine manufacturers pivoting to electrification and power-tool specialists extending motor platforms into outdoor applications. Three archetypes dominate: diversified industrial conglomerates with captive battery ecosystems, pure-play outdoor equipment specialists with fuel-cell R&D pipelines, and power-tool platform extenders leveraging existing lithium-ion architectures. Competitive moves concentrate on M&A for battery-cell supply security and strategic partnerships for brushless motor controller firmware development.
Within the diversified industrial tier, Robert Bosch GmbH and Stanley Black & Decker represent archetypes of power-tool platform extension into garden applications. Husqvarna AB occupies a position exemplifying pure-play outdoor equipment specialization with professional-grade battery architecture development. STIHL Holding AG & Co. KG anchors the specialist manufacturer category with captive alternative-fuel research alongside electric transition portfolios. These three entities collectively illustrate the strategic tension between proprietary ecosystem lock-in and interoperable battery-platform architectures that defines supplier selection criteria for fleet operators.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Husqvarna AB |
| The Toro Company |
| Deere & Company |
| Robert Bosch GmbH |
| American Honda Motor Co., Inc. |
| Briggs & Stratton Corporation |
| KUBOTA Corporation |
| STIHL Holding AG & Co. KG |
| Others |
Supply Flow & Price Mechanics
German commercial horticulture contractors in Baden-Württemberg and Bavaria concentrate procurement volume for professional-grade battery platforms, locking in contract-based long-term offtake pricing that favors fleet-scale buyers over fragmented residential channels. This buyer-archetype concentration compresses margin pools for mid-tier manufacturers lacking captive cell supply or interchangeable battery architectures.
Pricing Analysis
Lithium carbonate and power electronics input-cost pass-through dominates cordless equipment pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by brushless motor certification grade and battery-platform interoperability. Price compression runs through the economy tier as Chinese cell manufacturers expand export capacity, while professional landscapers show least price sensitivity due to total-cost-of-ownership fleet calculations. Residential homeowners exhibit highest price sensitivity, prioritizing unit acquisition cost over runtime specifications or warranty depth.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese producers, with brushless motor controllers sourcing from Taiwanese semiconductor fabricators and forged-steel blade metallurgy anchored in Swedish and Japanese specialty forges. Raw material dependencies span lithium carbonate, neodymium rare-earth magnets, and high-carbon alloy steel. Single-source vulnerability concentrates in Japanese Rockwell C-scale blade suppliers for professional hand-tool specifications. Distribution runs through German distributors for fleet procurement and big-box retailers for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Garden tools represents a late-cycle quality story as EU F-Gas Regulation deadlines redirect municipal procurement toward premium battery-native specifications with extended service-life guarantees. Professional landscapers now specify Swedish and Japanese metallurgy alongside interchangeable lithium-ion architectures, elevating quality thresholds above commoditized two-stroke replacement cycles.
For Market Incumbents: Anchor fleet-scale service contracts in Baden-Württemberg and Bavaria through captive battery-platform ecosystems that lock out interoperable competitors. Defend against power-tool specialists extending outdoor platforms by deepening in-house production of brushless motor controller firmware, addressing talent scarcity that delays smart power management certification. Prioritize ISO 11806 machinery safety compliance investment ahead of harmonized international redesign deadlines for blade guards and emergency stop systems. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for battery-platform interoperability standards that reduce fleet operator total cost of ownership and enable aftermarket service ecosystems. Target India's urban greening mandates in Delhi-NCR and Bengaluru municipal jurisdictions for price-sensitive cordless equipment entry, leveraging PLI scheme domestic cell assembly capacity. Pursue equipment-as-a-service contracting models bundling maintenance and battery swap logistics, displacing capital purchase models in Scandinavian-influenced landscape service providers. For Investors and Strategic Acquirers: Power-tool conglomerates with existing lithium-ion architectures are the most active acquirer in this space, seeking battery-cell supply security through specialist manufacturer targets. Long-term viability over the next decade hinges on fuel-cell hybrid R&D pipelines addressing commercial ride-on duty-cycle gaps that pure battery platforms cannot yet close. Watch for lithium carbonate price stabilization as the inflection signal enabling margin recovery in cordless equipment manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Platform Standardization | Interoperable architectures reduce fleet operator total cost of ownership and unlock aftermarket service ecosystems. |
| Backward Integration into Cells | Captive lithium-ion supply secures margin pools against raw material volatility and semiconductor allocation constraints. |
| Fuel-Cell Hybrid Development | Hydrogen range extenders address commercial ride-on duty-cycle gaps beyond pure battery runtime specifications. |
| Equipment-as-a-Service Launch | Subscription bundling of maintenance and battery logistics displaces capital purchases in municipal groundskeeping procurement. |
| ISO 11806 Compliance Investment | Harmonized machinery safety certification ahead of redesign deadlines secures professional-grade market access. |
Methodological Framework
Coverage spans Germany, the United States, the Netherlands, China, and India, with primary inputs from each market through structured interviews with landscape maintenance contractors, municipal procurement officers, battery-pack assembly plant managers, and brushless motor controller firmware developers. Secondary validation draws from EPA small spark-ignition engine filings, EU F-Gas Regulation compliance databases, MIIT battery-industry development guidelines, and OSHA noise-exposure enforcement records. Bottom-up segment sizing triangulates against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling addresses product type, material specification, end-user archetype, and distribution channel dimensions, with additional disaggregation by battery-platform voltage tier and Rockwell C-scale blade hardness grade. CAGRs derive from regression analysis of replacement-cycle timing, regulatory deadline alignment, and fleet-scale adoption curves. Industry-specific forecast inputs include lithium-ion energy density improvement trajectories and professional landscaper brushless motor standardization rates in German commercial horticulture clusters.
Revisions become necessary when lithium carbonate price volatility exceeds historical bands, semiconductor allocation constraints extend brushless motor controller lead times, or EU F-Gas Regulation enforcement timelines accelerate beyond baseline assumptions. A small set of named triggers warrants ongoing watch: raw material input cost spikes, power electronics shortage duration, and municipal procurement budget reallocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Global Drip Emitters Market
Agricultural Equipment
Global Grain Bin Management Solution Market
Agricultural Equipment
Harrows Market
Agricultural Equipment
Solar Insect Trap Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Hay and Forage Rakes Market
Agricultural Equipment
Square Silos Market
Agricultural Equipment
Global Feeding Systems Market
Agricultural Equipment
Feeding Hopper Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Compost Turning Machine Market
Agricultural Equipment
OWD Moisture Meter Market
Agricultural Equipment
Pond Aeration System Market
Agricultural Equipment
Smart Rice Transplanter Market