
 Powder Feed Center Market | 2026-2036
Powder Feed Center Market Size, Share, and Industry Trends Forecast 2026-2036
Powder Feed Center Market Analytics
Commercial farming is shifting toward automated powder feed centers as livestock operations scale in North America and Western Europe. Bühler Group leverages its milling heritage to dominate turnkey feed processing installations. GEA Group competes through hygienic design engineering that sustains biosecurity compliance in swine and poultry facilities. Nordson Corporation specializes in precision powder coating transfer technologies that extend into feed handling equipment applications.
A powder feed center is an integrated material handling system that meters, conveys, and dispenses dry feed ingredients or complete rations into production or research environments, typically operating with batch accuracy within one percent and containment specifications that prevent cross-contamination between nutritional formulations. The unit serves commercial farming, nutritional studies, and animal breeding operations that require repeatable feed delivery. Premix and concentrates categories lead product type demand because margin pools concentrate in high-value additive formulations where formulation precision determines livestock performance outcomes. Direct sales and wholesaler channels control distribution for large farming integrators, while online sales represent the fastest-growing channel among mid-tier research facilities and independent breeders seeking configurable equipment.
USDA feed safety protocols and FDA hazard analysis requirements shape equipment design standards for domestic installations, while China's SAMR and GB standards enforce material contact surface certifications for imported systems. The EU's feed hygiene regulations and CE marking directives govern market access for European poultry and swine operations. Stakeholders must monitor how evolving national feed safety frameworks alter equipment validation protocols and sourcing requirements across their installed base.
Market Dynamics
Precision livestock farming mandates from Germany's KBA-equivalent agricultural regulators are compressing batch tolerance requirements below one percent, forcing equipment retrofits across European swine integrators and accelerating replacement cycles for legacy pneumatic conveyors.
Growth Catalysts
- EU Feed Hygiene Regulations:Material traceability requirements under EFSA frameworks are compelling poultry operations to install automated powder feed centers with full batch logging capabilities.
- Commercial Farming Consolidation:Large-scale swine integrators in Iowa and North Carolina are standardizing on centralized feed delivery architectures to reduce labor dependency.
- Precision Dosing Technology:Gravimetric loss-in-weight feeders are replacing volumetric systems in premix applications where additive accuracy directly impacts feed conversion ratios.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L contact surface requirements under FDA hazard analysis protocols expose equipment margins to nickel price swings from Indonesian and Philippine suppliers.
- Certification Timeline Friction:China's SAMR material contact surface approvals for imported systems extend delivery schedules by eight to fourteen months for European manufacturers.
- Technical Integration Limits:Legacy mill automation protocols from the 1990s lack the data bandwidth to support real-time formulation tracking demanded by modern biosecurity audits.
Strategic Opportunities
- Research Facility Channel:Mid-tier nutritional study centers in Denmark and the Netherlands are migrating from manual batching to configurable powder feed centers purchased through direct online sales channels.
- CE Marking Tailwinds:Updated EU machinery directives are accelerating replacement demand among German and Polish poultry operations seeking compliant equipment for export-qualified production.
- IoT-Converged Monitoring:Cloud-connected feed consumption sensors are unifying with powder feed center controllers to enable predictive maintenance contracts in commercial breeding operations.
Industry Challenges
- Automation Engineering Talent Scarcity:Controls programmers familiar with both pneumatic conveying and FDA-validated batch software command premium compensation, constraining OEM expansion.
- Legacy System Integration Complexity:Retrofitting powder feed centers into existing mill architectures without disrupting continuous production requires custom mechanical adapters that extend project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powder Feed Center Market |
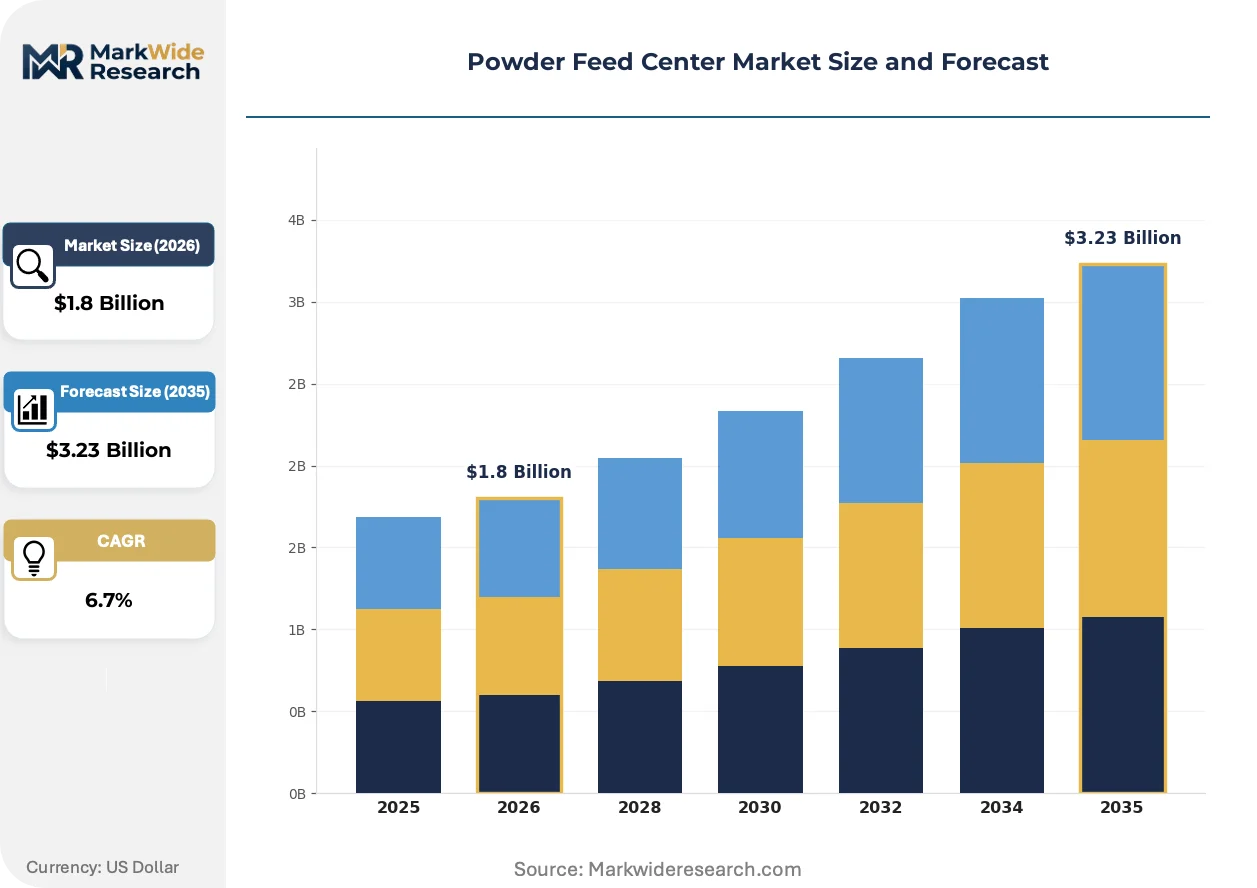
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Premix, Concentrates, Supplements, Complete Feeds End User: Poultry, Swine, Ruminants, Aquaculture Application: Commercial Farming, Research, Nutritional Studies, Animal Breeding Distribution Channel: Online Sales, Wholesalers, Retail Stores, Direct Sales |
| Companies Covered | Bühler Group, GEA Group, KSE Process Technology, Nordson Corporation, Gema Switzerland GmbH, WAGNER, ANEST IWATA Corporation, Carlisle, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powder Feed Center Market Evolving Landscape
Digital thread technologies are threading through feed handling equipment, compressing the gap between formulation design and floor execution while regulatory pressure on material traceability intensifies hardware refresh cycles.
Gravimetric blending with real-time moisture compensation is unifying formulation accuracy across multi-ingredient powder streams. Large poultry integrators in Germany and the Netherlands are adopting these systems at replacement-cycle pace rather than greenfield rates. The technology is unifying previously separate weighing and mixing stages into single-vessel architectures that reduce cross-contamination risk.
REACH-compliant surface coatings for material contact zones are reshaping equipment specifications for European swine facilities. The industrial consequence is extended qualification timelines for new supplier onboarding as ECHA substance restrictions tighten. Poultry operations in France and Spain are responding by consolidating purchases around established vendors with pre-validated coating chemistries.
After-sales service unbundling is fragmenting traditional equipment procurement in North American research facilities. Mid-tier breeders now acquire powder feed centers through capital expenditure while contracting preventive maintenance separately to specialized third-party technicians. This pattern is most visible among independent swine genetic improvement centers in Iowa and Minnesota seeking to preserve internal engineering capacity for core breeding operations.
Powder Feed Center Market Segmentation
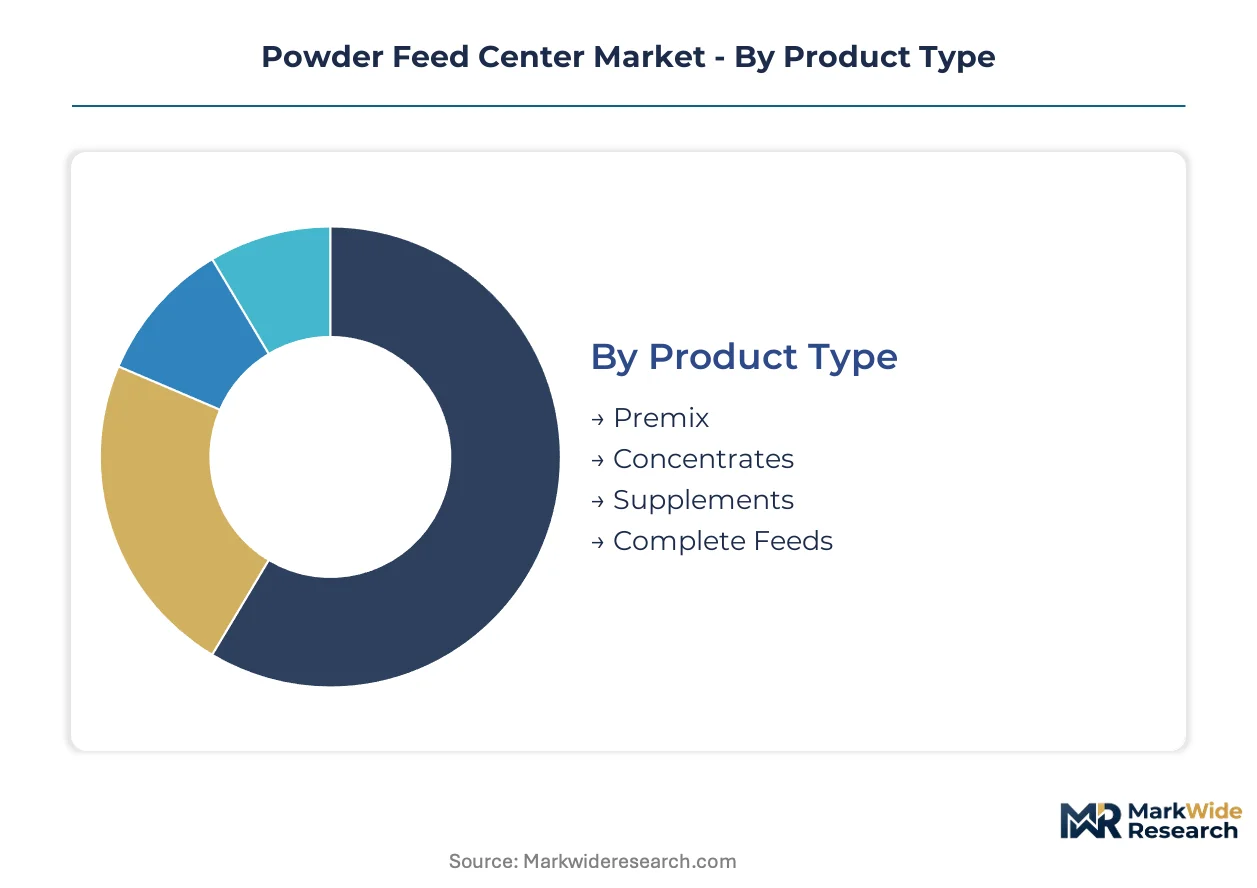
Segmentation in powder feed centers reveals how regulatory requirements, precision demands, and operational scale fragment equipment specifications across livestock sectors. Certification burdens vary sharply by end-use intensity and geographic jurisdiction, forcing OEMs to maintain parallel product lines.
Product Type:
Premix and concentrate systems carry the heaviest certification load under FDA hazard analysis protocols and EFSA material traceability frameworks, while complete feed installations face lighter validation requirements in domestic markets.
- Premix:High-precision gravimetric feeders handle micro-ingredient dosing down to 50-gram increments for vitamin and mineral additives. Iowa-based swine integrators and North Carolina poultry operations are standardizing on these systems to meet USDA batch logging mandates for medicated feed.
- Concentrates:Intermediate blending systems process protein-rich base mixes requiring moisture compensation and real-time NIR analysis. German large-scale integrators under KBA-equivalent agricultural oversight are retrofitting legacy pneumatic lines with these units to compress tolerance below one percent.
- Supplements:Compact skid-mounted units serve mid-tier breeders with limited footprint.
- Complete Feeds:High-throughput systems for total mixed ration delivery in ruminant operations.
Premix sits at the top of the volume ranking, with concentrates climbing the fastest.
End User:
Cost tier differentiation separates biosecurity-intensive poultry and swine installations from ruminant and aquaculture systems with lighter regulatory overhead.
- Poultry:Layer and broiler houses in Germany and the Netherlands demand REACH-compliant surface coatings and full batch genealogy tracking. France and Spain operations are consolidating purchases around established vendors with pre-validated coating chemistries to avoid extended ECHA qualification timelines.
- Swine:Farrow-to-finish integrators in Iowa and Minnesota require stainless steel 316L contact surfaces and cloud-connected consumption sensors for predictive maintenance contracts. Denmark's research-oriented breeding centers are migrating from manual batching to configurable systems.
- Ruminants:Dairy and beef feedlots prioritize throughput over precision dosing.
- Aquaculture:Marine and freshwater operations in Norway and Chile drive specialized waterproofing specifications.
Swine captures the largest installed base, while aquaculture shows the steepest expansion trajectory.
Application:
Volume concentration favors continuous-production commercial farming, though research and breeding applications command premium pricing for configurability.
- Commercial Farming:Centralized feed delivery architectures serving 10,000-plus head operations dominate capital deployment. Large-scale integrators are standardizing on these systems to reduce labor dependency and satisfy biosecurity audit requirements.
- Research:Mid-tier nutritional study centers in Denmark and the Netherlands are migrating from manual batching to configurable powder feed centers. These facilities prioritize batch repeatability over throughput.
- Nutritional Studies:University and private trial facilities require rapid formulation changeover capabilities.
- Animal Breeding:Genetic improvement centers demand pedigree-linked feed consumption tracking.
Commercial farming holds the dominant volume position, with research gaining share fastest.
Distribution Channel:
Customer type splits procurement patterns between capital-intensive integrators and mid-tier facilities seeking financing flexibility.
- Direct Sales:Turnkey installations for large farming integrators involve extended engineering validation and post-commissioning support contracts. Bühler Group and GEA Group dominate this channel through milling heritage and hygienic design expertise.
- Online Sales:Mid-tier research facilities and independent breeders are purchasing configurable equipment through digital channels. This pattern is most visible among Iowa and Minnesota swine genetic improvement centers preserving internal engineering capacity.
- Wholesalers:Regional distributors serve secondary markets with standardized configurations.
- Retail Stores:Limited presence for small-scale hobby farming and pilot operations.
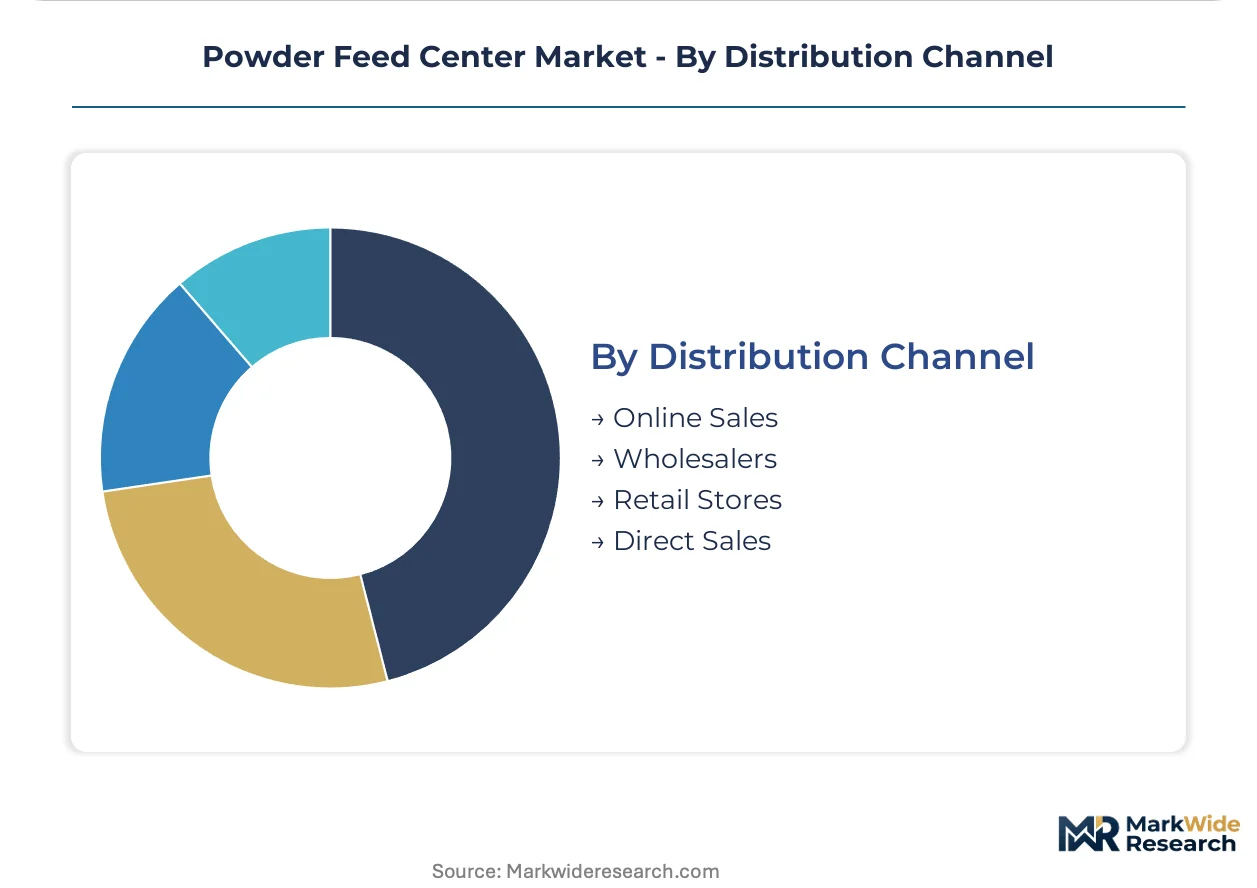
Direct sales commands the highest transaction value, with online sales expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement patterns as compliance cost differentials widen between jurisdictions with stringent feed safety mandates and those with emerging enforcement frameworks.
United States
Large-scale swine integrators in Iowa and North Carolina are consolidating around centralized feed delivery architectures to reduce labor dependency. FDA hazard analysis protocols and USDA feed safety standards mandate stainless steel 316L contact surfaces and full batch logging for medicated feed applications. The Iowa-Minnesota corridor anchors demand from independent genetic improvement centers migrating toward configurable systems.
Germany
Precision livestock farming mandates from agricultural regulators are compressing batch tolerance requirements below one percent across European swine integrators. REACH-compliant surface coatings and CE marking directives under updated EU machinery frameworks govern equipment validation. The Lower Saxony poultry cluster is retrofitting legacy pneumatic conveyors with gravimetric loss-in-weight feeders to satisfy biosecurity audit requirements.
China
Commercial farming operations in poultry and swine sectors are expanding automated powder feed delivery systems as domestic protein production scales. SAMR material contact surface approvals and GB standards for feed safety enforce extended qualification timelines for imported equipment. The Yangtze River Delta concentration of large-scale integrators is driving standardization on turnkey processing installations.
Netherlands
Mid-tier nutritional study centers are migrating from manual batching to configurable powder feed centers purchased through direct online sales channels. EFSA material traceability frameworks and EU feed hygiene regulations compel full batch genealogy tracking capabilities. The Wageningen research corridor is consolidating procurement around established vendors with pre-validated coating chemistries.
Brazil
Swine and poultry operations are adopting automated feed handling systems as export-oriented production expands under sanitary compliance pressures. ANVISA feed safety protocols and agricultural ministry oversight shape equipment specifications for integrated producers. The Santa Catarina poultry cluster is standardizing on centralized architectures to satisfy international market access requirements.
Powder Feed Center Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with turnkey system integrators commanding premium positioning in large-scale commercial farming while component suppliers capture recurring revenue in aftermarket services. The market exhibits moderate concentration where heritage milling equipment manufacturers leverage installed base relationships against specialized hygienic design engineering firms. Three archetypes dominate: full-system turnkey providers, precision dosing technology specialists, and surface coating material innovators. Competitive intensity centers on M&A activity consolidating regional fabrication capabilities and strategic partnerships bridging automation software with mechanical handling expertise.
Within the full-system turnkey tier, Bühler Group and GEA Group exemplify heritage-driven market positioning, with the former representing Swiss milling lineage and the latter embodying German hygienic design engineering. Nordson Corporation occupies a position among precision technology specialists, anchoring the precision powder handling segment through its coating and dispensing heritage. These three companies collectively illustrate how equipment origin and technical specialization map to distinct customer procurement criteria across poultry, swine, and research facility end uses.
| Leading Market Players |
|---|
| Bühler Group |
| GEA Group |
| KSE Process Technology |
| Nordson Corporation |
| Gema Switzerland GmbH |
| WAGNER |
| ANEST IWATA Corporation |
| Carlisle |
| Akzo Nobel N.V. |
| Others |
Value Network & Pricing Analysis
Large-scale swine integrators in Iowa and North Carolina are consolidating procurement around centralized feed delivery architectures, forcing equipment OEMs to absorb stainless steel 316L certification costs while maintaining direct sales channel margins. This buyer consolidation compresses pricing power upstream and reshapes how suppliers configure regional distribution networks.
Pricing Analysis
Distributor margins in the wholesaler channel absorb 12-18 point markups over direct sales, creating a three-tier pricing structure across premium, standard, and economy levels based on certification grade and after-sales bundling. FDA-validated batch software and CE marking tiers command 25-35 point premiums over domestic-only configurations. Pricing pressure stems from nickel price volatility on Grade 316L contact surfaces sourced from Indonesian suppliers. Mid-tier research facilities in Denmark and the Netherlands exhibit highest price sensitivity, while German large-scale integrators under KBA-equivalent oversight show lowest elasticity due to compliance-driven replacement cycles.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the Netherlands anchor hub-and-spoke patterns serving European poultry clusters, with secondary nodes in Iowa and Minnesota for North American swine operations. Component sourcing draws from Chinese stainless steel fabricators, German precision dosing technology suppliers, and Swiss automation controls specialists. Single-source vulnerability concentrates in nickel alloy supply chains exposed to Indonesian export restrictions. Distribution runs through direct OEM engineering teams for large integrators and specialized agricultural equipment distributors for mid-tier facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where China's SAMR approval timelines stretch 8-14 months versus the EU's CE marking pathways, creating cost differentials that favor European OEMs in Asian procurement cycles.
For Market Incumbents: Cement installed base relationships through backward integration into precision dosing technology and predictive maintenance software stacks. Bühler Group and GEA Group should defend against emerging IoT-native entrants by locking multi-year service contracts with Iowa and North Carolina integrators before replacement cycles peak. Certification investment in REACH-compliant surface coatings preserves access to German and Dutch poultry clusters where ECHA substance restrictions tighten. For New Entrants and Emerging Players: Begin with configurable skid-mounted units for mid-tier nutritional study centers in Denmark and the Netherlands migrating from manual batching. Online sales channels offer the most penetrable go-to-market angle, bypassing entrenched direct sales relationships held by heritage milling equipment manufacturers. Target research facilities with rapid formulation changeover capabilities and cloud-connected consumption sensors as differentiation anchors. For Investors and Strategic Acquirers: Asymmetric upside sits with precision dosing technology specialists possessing FDA-validated batch software and established SAMR material contact surface approvals. Long-term viability hinges on consolidation plays bridging automation software with pneumatic conveying mechanical expertise. Watch for inflection signals in China's GB standards enforcement tightening on imported equipment, which would accelerate domestic substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Dosing Technology | Captures margin pools in gravimetric loss-in-weight feeders where additive accuracy determines livestock performance outcomes. |
| REACH-Compliant Surface Coating Certification | Preserves market access to German poultry clusters under ECHA substance restriction tightening. |
| Cloud-Connected Predictive Maintenance Contracts | Unifies feed consumption sensors with powder feed center controllers in Iowa and Minnesota breeding operations. |
| Online Sales Channel Expansion | Captures mid-tier research facilities in Denmark and Netherlands seeking configurable equipment without direct sales overhead. |
| SAMR Material Contact Surface Pre-Approval | Compresses 8-14 month delivery schedules for European manufacturers targeting China's Yangtze River Delta integrators. |
Research Methodology
Direct dialogue with plant engineers at large-scale swine integrators, OEM procurement teams, aftermarket service heads, and agricultural regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from USDA feed safety protocols, FDA hazard analysis filings, EU feed hygiene regulation updates, and Chinese SAMR approval databases. Bottom-up equipment shipment tallies by product type and end-use segment triangulated against top-down market sizing through agricultural census data and livestock inventory projections.
Bottom-up modeling segmented volume and value across premix, concentrates, supplements, and complete feed product types, intersecting with poultry, swine, ruminant, and aquaculture end uses. Deployment models distinguished direct sales, online channels, wholesaler, and retail store distribution patterns. CAGRs were derived from regression analysis of historical replacement cycles, regulatory mandate timelines, and livestock operation consolidation trajectories. Gravimetric technology adoption curves and IoT sensor penetration rates in commercial breeding operations informed projection mechanics across the analysis window.
Caveats apply where nickel price volatility, Chinese SAMR approval timeline extensions, or EU machinery directive updates could materially shift the outlook. Forecasts reflect documented assumptions around livestock herd expansion, precision farming mandate enforcement intensity, and stainless steel input cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Smart Rice Transplanter Market
Agricultural Equipment
Crop Spraying Drone Market
Agricultural Equipment
Fishing Net Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Food Bucket Elevators Market
Agricultural Equipment
Cordless Sprayer Market
Agricultural Equipment
Livestock Grow Lights Market
Agricultural Equipment
Pump Feeder Market
Agricultural Equipment
Belt Feeders Market
Agricultural Equipment
Bird Scarer and Repellent Market
Agricultural Equipment
Pistol Grip Sprayer Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Air Seeder Market
Agricultural Equipment
Australia Bird Feeder Market
Agricultural Equipment
Planter Market
Agricultural Equipment
Agricultural Ventilation Fans Market