
 Arthrogryposis Management Market | 2026-2036
Arthrogryposis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Arthrogryposis Management Market Outlook
Postoperative rehabilitation services is rewriting margin allocation across the arthrogryposis care continuum. Johnson & Johnson Services Inc. anchors its position through orthopedic device portfolios that span surgical correction to long-term mobility support. Stryker competes in robotic-assisted surgical platforms that reduce revision rates in complex joint contracture cases. Zimmer Biomet specializes in custom orthotic and prosthetic solutions tailored to pediatric arthrogryposis presentations.
Arthrogryposis management encompasses the coordinated clinical interventions addressing congenital joint contractures across multiple body regions, typically involving serial casting, tendon transfer procedures, and adaptive equipment fitting with specifications calibrated to pediatric growth trajectories. The primary purpose centers on preserving functional independence and preventing secondary musculoskeletal deterioration across the lifespan. Therapeutic devices and mobility aids command the dominant revenue share as first-line interventions for nearly all diagnosed cases, while robotic assistance and augmented reality applications in surgical correction represent the fastest-expanding technology segments where procedure volumes and reimbursement rates are both climbing. Hospitals and rehabilitation centers absorb the majority of product flow, though home care channels are extending reach as remote monitoring and telehealth-integrated device dispensing gain traction.
FDA orphan drug designation and EMA's European Reference Networks for rare diseases shape therapeutic development incentives and cross-border patient access pathways for arthrogryposis interventions. ISO 13485 quality management standards and national medical device registration requirements in Japan and South Korea govern market entry for orthopedic and rehabilitation equipment manufacturers. Stakeholders must monitor evolving reimbursement frameworks for minimally invasive surgical technologies and track how regulatory harmonization across major markets influences clinical trial placement and product launch sequencing.
Market Dynamics
Postoperative rehabilitation services are capturing margin share across the arthrogryposis care continuum as multidisciplinary care models consolidate previously fragmented service delivery. This structural shift pressures device manufacturers to bundle hardware with outcome-based support contracts rather than standalone product sales.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway compresses development timelines for rare disease therapeutics targeting arthrogryposis subtypes. Biologics developers leverage this framework to access priority review vouchers.
- Robotic-Assisted Surgical Platforms:These systems reduce revision rates in complex joint contracture procedures. Academic medical centers in the United States and Germany are standardizing their use for pediatric orthopedic cases.
- European Reference Networks:EMA-coordinated cross-border patient access pathways enable centralized expertise pooling for rare musculoskeletal conditions. This framework funnels complex cases to designated reference centers in France, Italy, and the Netherlands.
Market Restraints
- Custom Orthotic Fabrication Costs:Labor-intensive production of pediatric growth-adjustable devices limits economies of scale. Raw material volatility in medical-grade thermoplastics further compresses margins for manufacturers.
- Specialized Surgical Workforce Concentration:Pediatric orthopedic surgeons with arthrogryposis expertise cluster in urban academic centers. Rural and secondary markets face persistent access gaps that constrain addressable procedure volumes.
- Reimbursement Fragmentation:Divergent coding for serial casting versus surgical intervention across US Medicare, Medicaid, and commercial payers creates administrative burden. Prior authorization requirements delay care initiation.
Strategic Opportunities
- Telehealth-Integrated Home Care:Remote monitoring platforms enable orthotic adjustment and therapy supervision outside clinical settings. This channel extension reaches patients in underserved US states and Canadian provinces.
- 3D-Printed Patient-Specific Implants:Additive manufacturing convergence with digital surgical planning allows intraoperative customization. Japanese and South Korean hospitals are piloting point-of-care production for complex foot and ankle reconstructions.
- EMA Cross-Border Healthcare Directive:This framework permits patients to seek arthrogryposis treatment in any EU member state with home-country reimbursement. Specialized centers in Switzerland and Austria are building service lines around medical tourism flows.
Industry Challenges
- Pediatric Orthopedic Fellowship Pipeline:Training program capacity constraints limit annual specialist output. Academic medical centers compete for scarce clinical faculty to precept emerging surgeons.
- ISO 13485 Certification Burden:Quality management system maintenance for multi-site manufacturing requires sustained audit readiness. Small and mid-sized orthotic device producers face disproportionate compliance costs relative to revenue scale.
- Legacy EMR Integration:Surgical planning software and robotic platforms must interface with heterogeneous hospital information systems. Interface development delays extend implementation timelines at mid-tier institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthrogryposis Management Market |
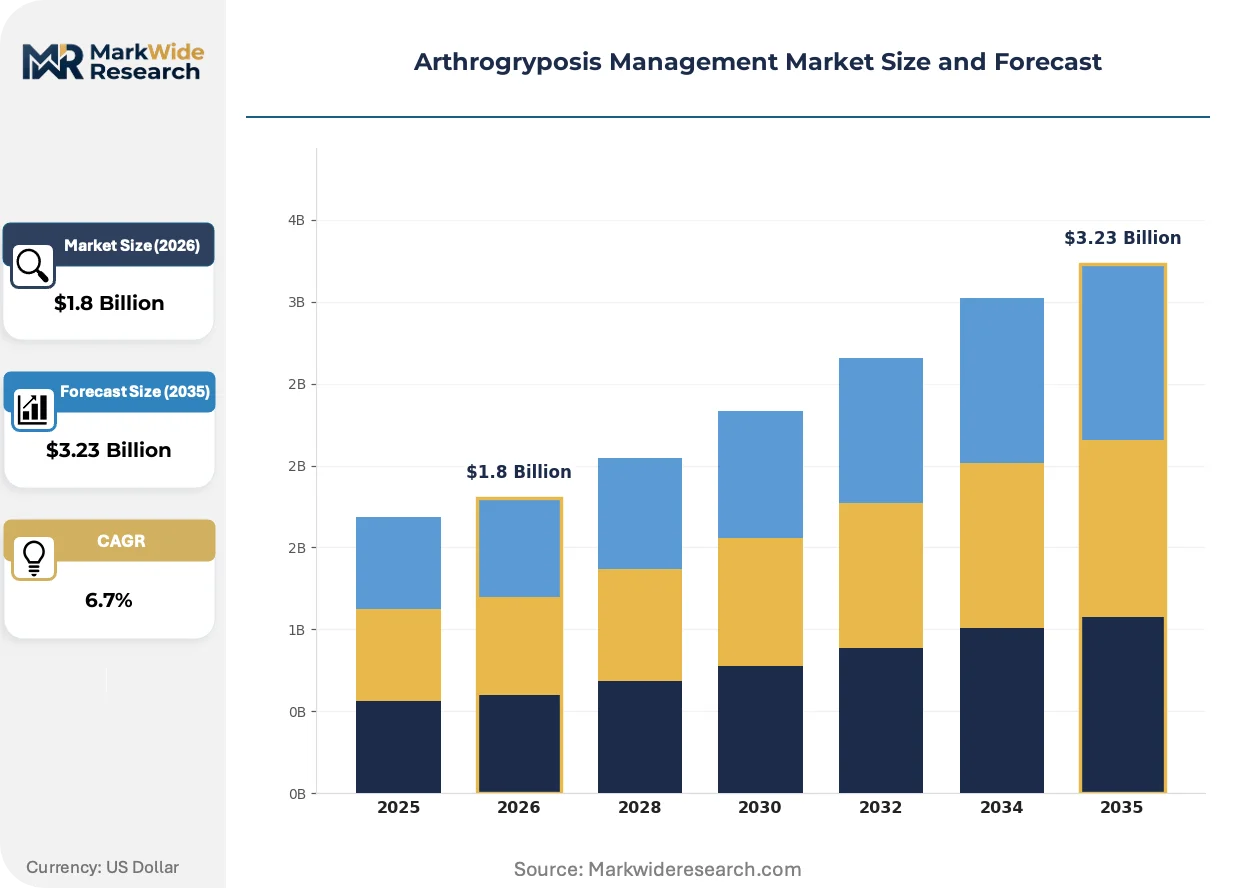
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutic Devices, Mobility Aids, Surgical Instruments, Rehabilitation Equipment Application: Physiotherapy, Surgical Correction, Pain Management, Genetic Counseling End User: Hospitals, Rehabilitation Centers, Home Care, Clinics Technology: Orthotic Solutions, Minimally Invasive, Augmented Reality, Robotic Assistance |
| Companies Covered | Johnson & Johnson Services Inc., Biochem Pharmaceutical Industries Limited, GSK Plc, Stryker, F. Hoffmann-La Roche Ltd., Pfizer Inc., Zydus Cadila, Zimmer Biomet, Sanofi S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthrogryposis Management Market Strategic Shifts
Augmented reality applications are compressing the learning curve for complex tendon transfer procedures while digital twin technologies enable preoperative simulation of pediatric growth trajectories. These converging capabilities reshape how surgical teams prepare for and execute interventions.
Spatial computing platforms are virtualizing preoperative planning workflows for multi-joint contracture release procedures. Pediatric orthopedic departments at Johns Hopkins and Hospital for Special Surgery deploy these systems for resident training and patient-family education. The technology is virtualizing traditional cadaveric workshops, reducing institutional biospecimen costs while standardizing exposure to rare anatomical presentations.
EMA's Medical Device Regulation (MDR) implementation is recalibrating conformity assessment requirements for custom-made orthotic devices. Manufacturers serving European markets must maintain technical documentation and clinical evidence portfolios previously exempt under the Medical Device Directive. Small-scale producers in Italy and Poland are consolidating or exiting as notified body capacity constraints extend certification timelines.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases for robotic surgical platforms. Buyers negotiate discrete pricing for maintenance, software updates, and training credits rather than accepting bundled ten-year agreements. This pattern is most pronounced in German and French hospital systems where centralized purchasing cooperatives wield aggregated volume leverage.
Arthrogryposis Management Market Segmentation
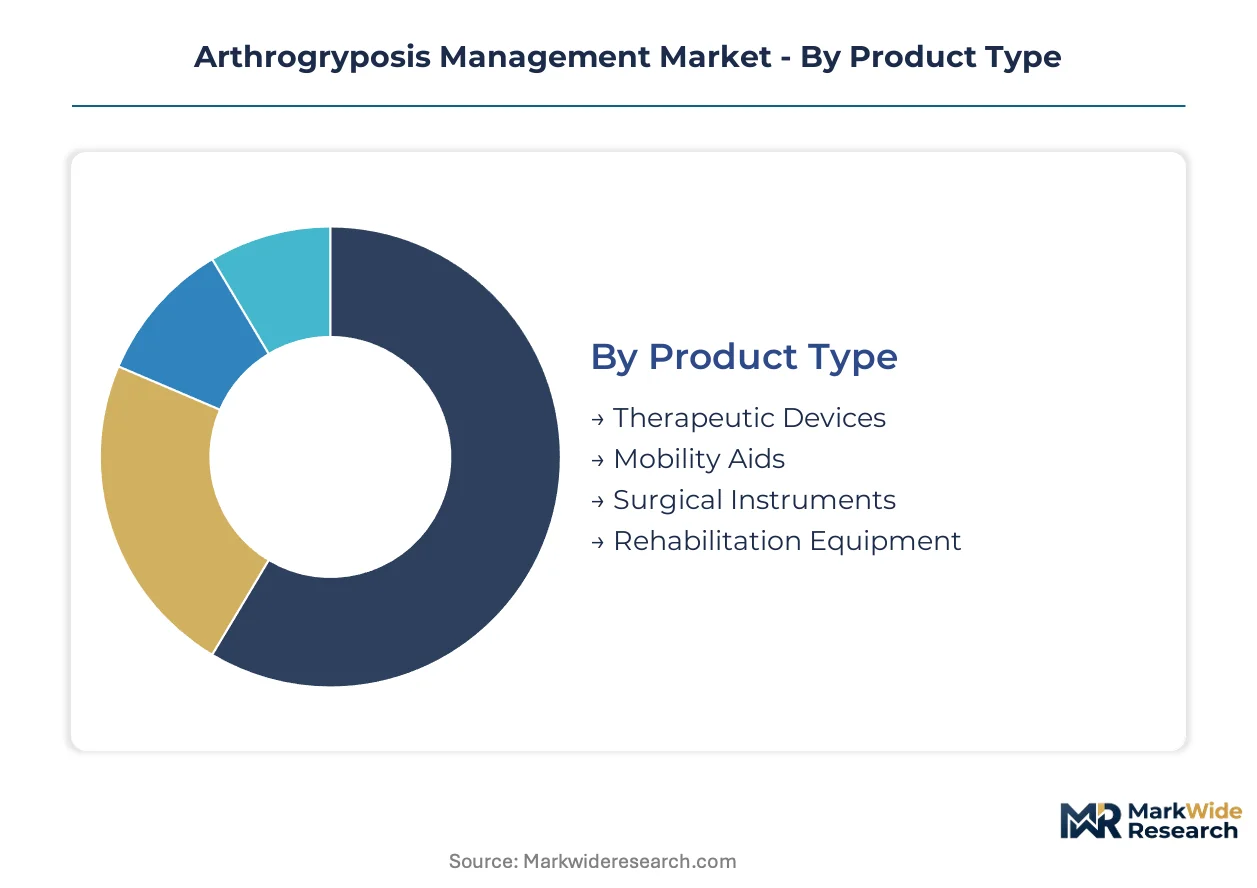
Segmentation in arthrogryposis management reveals how service intensity varies dramatically across intervention modalities. Product configuration, clinical setting, and technology sophistication each reshape margin structures and vendor engagement models differently.
Product Type:
After-sales service intensity varies sharply across hardware categories, with mobility aids requiring continuous fitting adjustments and surgical instruments demanding sterilization protocol support.
- Therapeutic Devices:Serial casting systems and dynamic splinting equipment dominate pediatric first-line intervention. Demand clusters in United States children's hospitals and German university clinics where multidisciplinary teams standardize casting protocols. Custom fabrication requirements sustain high-touch service relationships.
- Mobility Aids:Adaptive wheelchairs, gait trainers, and standing frames accommodate progressive functional needs across developmental stages. German and Japanese reimbursement frameworks favor premium positioning for growth-adjustable designs. Raw material volatility in aluminum and carbon fiber compresses manufacturer margins.
- Surgical Instruments:Specialized retractors and tendon transfer instrumentation serve low-volume, high-complexity procedures.
- Rehabilitation Equipment:Continuous passive motion devices and functional electrical stimulation systems support postoperative protocols.
By volume, mobility aids lead. By growth pace, therapeutic devices are ahead.
Application:
Cost tier stratification separates acute surgical episodes from chronic management modalities, with reimbursement rates diverging threefold across these clinical purposes.
- Physiotherapy:Serial manipulation and neurodevelopmental therapy constitute the foundational intervention for nearly all diagnosed cases. United States pediatric therapy networks and Australian early intervention programs drive standardization of functional outcome metrics. Workforce shortages in specialized pediatric physiotherapy constrain service expansion.
- Surgical Correction:Tendon transfers, osteotomies, and joint releases address contractures refractory to conservative management. Academic medical centers in Baltimore, Philadelphia, and London concentrate surgical volume for complex multi-joint presentations. Robotic platform adoption is climbing fastest in this application.
- Pain Management:Neuropathic and musculoskeletal pain protocols address secondary complications in adolescent and adult patients.
- Genetic Counseling:Preconception and family planning services support recurrence risk assessment for heritable subtypes.
Physiotherapy commands the largest patient volume. Surgical correction is climbing fastest in per-procedure value.
End User:
Customer type determines procurement sophistication, with hospital purchasing cooperatives wielding aggregated leverage unavailable to individual home care providers.
- Hospitals:Tertiary pediatric centers absorb complex surgical cases and coordinate multidisciplinary care. United States children's hospitals in Boston, Cincinnati, and Houston anchor referral networks. Bundled payment pilots for arthrogryposis episodes are reshaping vendor contracting terms.
- Rehabilitation Centers:Dedicated pediatric facilities provide intensive postoperative therapy and long-term functional training. German Medizinische Rehabilitationszentren and Japanese rehabilitation hospitals specialize in congenital musculoskeletal conditions. Outcome-based reimbursement is gaining traction in these settings.
- Home Care:Remote monitoring and telehealth-integrated dispensing extend reach to underserved geographies.
- Clinics:Community-based orthopedic and therapy practices manage stable patients between hospital episodes.
Hospitals dominate absolute spending. Home care is expanding most quickly as channel economics improve.
Technology:
Supply concentration in robotic platforms and augmented reality systems favors vendors with integrated software-hardware capabilities over pure device manufacturers.
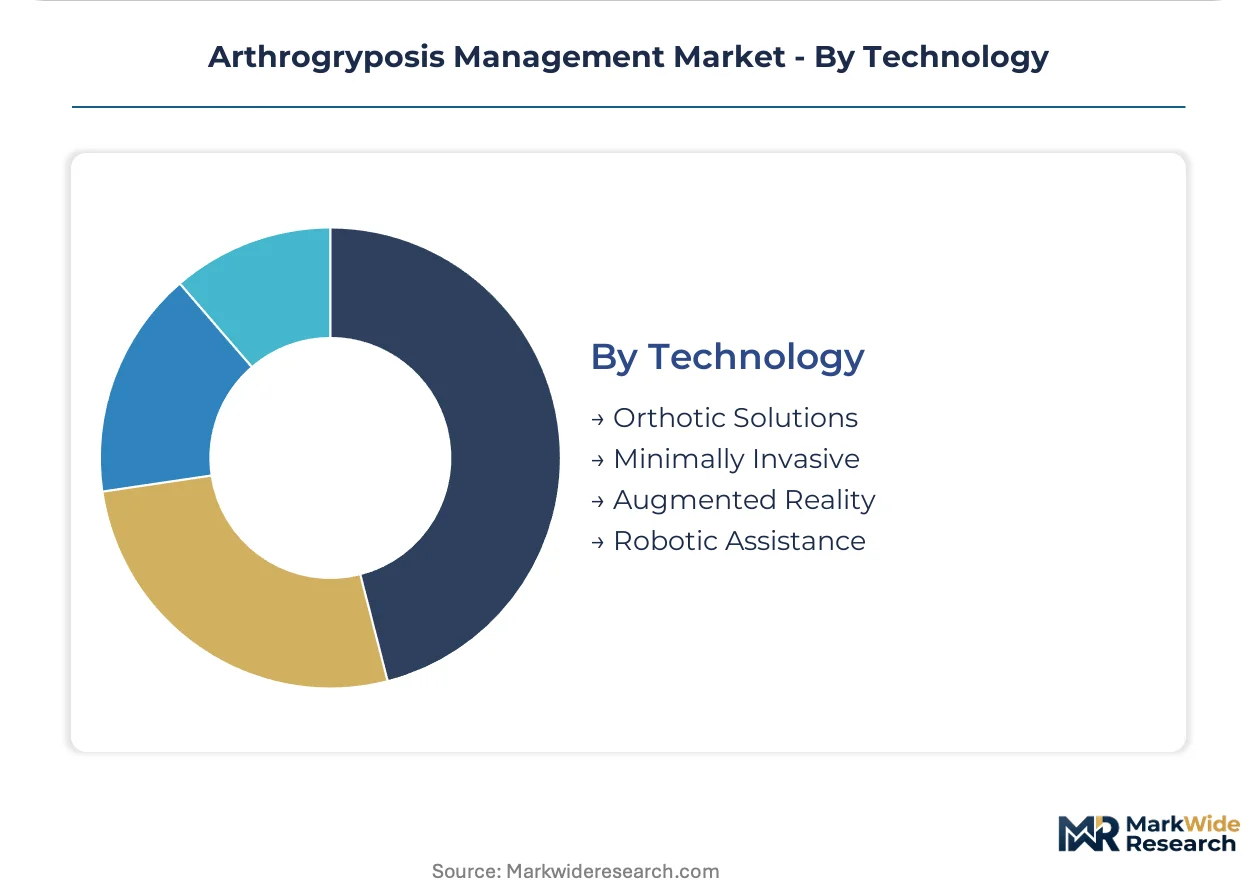
- Orthotic Solutions:Custom-molded and modular orthoses address joint positioning across the lifespan. Italian and Polish producers face EMA MDR consolidation pressures. 3D printing adoption is accelerating point-of-care production in Japanese and South Korean hospitals.
- Minimally Invasive:Arthroscopic and percutaneous techniques reduce recovery time in selective contracture releases. United States and German academic centers publish outcomes data driving technique diffusion. Training curriculum standardization lags behind instrument availability.
- Augmented Reality:Surgical planning and resident education applications compress learning curves for rare anatomical presentations.
- Robotic Assistance:Platform precision reduces revision rates in complex joint reconstruction.
Orthotic solutions lead by installed base. Robotic assistance is gaining share fastest as capital acquisition cycles shorten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States hospitals prioritize surgical intervention and robotic platforms, while German and Japanese systems emphasize conservative management and custom orthotic fabrication. Emerging markets concentrate on basic mobility aids and physiotherapy access.
United States
Pediatric orthopedic centers in Baltimore, Philadelphia, and Houston drive demand for complex multi-joint surgical procedures and robotic-assisted platforms. FDA orphan drug designation accelerates therapeutic development timelines for arthrogryposis subtypes. Bundled payment pilots at tertiary children's hospitals reshape vendor contracting toward outcome-based arrangements.
Germany
Medizinische Rehabilitationszentren specialize in intensive postoperative therapy and long-term functional training for congenital musculoskeletal conditions. EMA-coordinated European Reference Networks funnel complex cases to designated centers in Berlin and Munich. Centralized purchasing cooperatives unbundle service contracts from capital equipment acquisitions.
Japan
PMDA medical device registration requirements govern market entry for orthopedic and rehabilitation equipment manufacturers. Academic medical centers in Tokyo and Osaka pilot point-of-care 3D printing for patient-specific implants in foot and ankle reconstruction. Reimbursement frameworks favor premium positioning for growth-adjustable mobility designs.
United Kingdom
NHS specialized commissioning frameworks concentrate arthrogryposis surgical expertise at London teaching hospitals and regional pediatric networks. MHRA conformity assessment aligns with EMA MDR implementation for custom orthotic devices. Patient referral pathways increasingly leverage telehealth-integrated home care for rural access gaps.
South Korea
MFDS quality standards and medical device registration govern orthotic and surgical instrument imports. Seoul-based academic hospitals adopt digital surgical planning and additive manufacturing for complex contracture releases. Government-funded rare disease programs expand multidisciplinary center capacity for pediatric musculoskeletal conditions.
Arthrogryposis Management Market Competitive Environment
Capability concentration sits with specialized orthopedic device manufacturers; scale advantage sits with diversified health conglomerates. The market structures around three tiers: multinational conglomerates with full-care-continuum portfolios, mid-cap specialists in robotic platforms or custom fabrication, and regional orthotic producers facing regulatory consolidation. Dominant competitive moves include outcome-based service bundling and point-of-care manufacturing partnerships.
Within the diversified health conglomerate tier, Johnson & Johnson Services Inc. and Stryker exemplify integrated positioning across surgical correction to long-term mobility support. Zimmer Biomet occupies a specialist position in custom orthotic and prosthetic solutions calibrated to pediatric growth trajectories. These three anchors represent contrasting strategic postures: full-spectrum care continuum coverage, robotic-assisted surgical platform focus, and pediatric-specific customization expertise.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Biochem Pharmaceutical Industries Limited |
| GSK Plc |
| Stryker |
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Zydus Cadila |
| Zimmer Biomet |
| Sanofi S.A. |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor carries medical-grade thermoplastics and carbon fiber composites for orthotic fabrication, with freight cost volatility compressing margins for Italian and Polish producers while amplifying price spreads between premium custom-molded devices and standard prefabricated alternatives.
Pricing Analysis
Long-term service contracts dominate capital equipment transactions, with German hospital purchasing cooperatives unbundling robotic platform acquisitions from maintenance and training packages. Price differentiation rests on ISO 13485 certification tier and after-sales service intensity. Cost compression in custom orthotic fabrication is intensifying because raw material volatility in medical-grade thermoplastics outpaces reimbursement adjustments. Pediatric orthopedic clinics demonstrate highest price sensitivity; academic medical centers with bundled payment pilots show lowest.
Supply Chain Analysis
Medical-grade thermoplastic resin feedstock concentrates in Germany, Japan, and South Korea, with specialized polymer grades for pediatric growth-adjustable devices drawing from petrochemical complexes near Rotterdam and Singapore. Carbon fiber prepregs and aluminum alloys for mobility aids hinge on Taiwanese and Chinese suppliers. Single-source vulnerability in notified body capacity for EMA MDR certification extends lead times for European market entry. Distribution runs through hospital procurement cooperatives and specialized durable medical equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pediatric orthopedic surgeon training program bottlenecks constrain annual specialist output below replacement demand, creating durable scarcity premiums for centers with established arthrogryposis expertise and amplifying acquisition multiples for robotic platform operators with proven outcome data.
For Market Incumbents: Harden service bundling capabilities to capture postoperative rehabilitation margins as hospitals unbundle capital equipment contracts. Deepen backward integration into medical-grade thermoplastic compounding to offset raw material volatility. Prioritize ISO 13485 certification maintenance across multi-site manufacturing footprints against notified body capacity constraints. For New Entrants and Emerging Players: Pursue telehealth-integrated home care channels in underserved US states and Canadian provinces where geographic access gaps concentrate demand. Target outcome-based reimbursement pilots at German Medizinische Rehabilitationszentren as the most penetrable entry point. Lead with remote orthotic adjustment platforms rather than hardware-centric positioning. For Investors and Strategic Acquirers: Mid-cap robotic surgical platform specialists with pediatric orthopedic validation data represent the priority acquisition archetype. Long-term viability over a 5-10 year window depends on securing reference center relationships that generate procedure volume and outcome evidence. Watch FDA orphan drug designation grants to biologics developers as inflection signal for therapeutic modality competition.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Zimmer Biomet anchor referral networks at Boston Children's and Cincinnati Children's through co-developed outcome protocols. |
| CE Marking Pathway | EMA MDR technical documentation requirements for custom orthotic devices are consolidating Italian and Polish producer bases. |
| Software Companion Development | Augmented reality surgical planning platforms at Johns Hopkins and Hospital for Special Surgery virtualize resident training workflows. |
| Reimbursement Strategy | Bundled payment pilots for arthrogryposis episodes at US tertiary children's hospitals reshape vendor contracting terms toward risk-sharing. |
| FDA Submission | Orphan drug designation compresses development timelines for rare disease therapeutics targeting arthrogryposis subtypes with priority review vouchers. |
Study Parameters
A standing panel of pediatric orthopedic surgeons, hospital purchasing committee chairs, biomedical engineers at academic medical centers, and GPO contracts managers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement contract registries, and CMS Medicare durable medical equipment claims data. Bottom-up procedure volume estimates and top-down expenditure flows were triangulated against manufacturer revenue disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeled by intervention modality, technology sophistication tier, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical procedure volumes and reimbursement rate trajectories. Forecast inputs incorporated pediatric orthopedic fellowship pipeline capacity constraints and EMA notified body certification timeline assumptions.
Macroeconomic conditions sit as an overlay; deviation in medical device reimbursement rates, freight cost indices for Asia-Europe routes, or rare disease research funding allocations would shift the trajectory. Cross-checking against hospital capital expenditure surveys and orthopedic surgeon workforce census data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Kounis Syndrome Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Europe Down Syndrome Market
Rare Diseases
Pure Red Cell Aplasia Market
Rare Diseases
Lesch-Nyhan Syndrome Market
Rare Diseases
Methylmalonic Acidemia Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Metachromatic Leukodystrophy Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Byler Disease Market