
 Clipless Vertical Pouches Market | 2026-2036
Clipless Vertical Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Clipless Vertical Pouches Market Outlook
Mono-material polyethylene structures are displacing multi-layer laminates and is realigning cost structures across the value chain. Amcor Ltd leverages its global film manufacturing footprint to supply compatible substrates for clipless vertical formats. Sealed Air Corporation sustains technology leadership through proprietary barrier coating systems that eliminate clip hardware. Gruber-Folien GmbH & Co. KG anchors European supply with specialized high-clarity films engineered for vertical form-fill-seal lines.
Clipless vertical pouches are flexible packaging formats that stand upright without external closure hardware, typically constructed from heat-sealable films with integrated gusseted bases and precision die-cut dispensing features; they serve primary functions in shelf-stable food, beverage, and personal care distribution where retail visibility and consumer convenience converge. Plastic substrates dominate current volume given seal integrity and barrier performance, though biodegradable alternatives represent the fastest-expanding material category as converter R&D shifts toward compostable seal layers. Heat seal closure methods command the largest installed base of converting equipment, while ziplock resealable variants capture premium margin pools in pet food and snack applications where repeat-use functionality commands price premiums.
The FDA regulates direct food-contact materials under 21 CFR 177, requiring migration testing for all pouch substrates intended for edible contents. ECHA's REACH framework governs chemical substance registration across European supply chains, affecting adhesive and coating selections in laminated structures. The EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that reshape material specifications toward recyclable mono-polymer designs. Stakeholders must monitor evolving state-level packaging EPR legislation in California and New York while evaluating substrate transitions that maintain barrier performance without clip hardware.
Market Dynamics
Mono-material polyethylene structures are compressing converter margins while forcing rapid equipment retooling across the flexible packaging value chain, as heat-seal integrity requirements intensify without clip hardware fallback.
Growth Catalysts
- EuPPWR Recyclability Mandates:The EU Packaging and Packaging Waste Regulation's mono-material thresholds are pulling confectionery and snack producers toward compatible pouch formats. German packaging innovation clusters are accelerating substrate qualification timelines.
- Logistics Cost Arbitrage:Food processors in the United States are collapsing cube utilization ratios by converting rigid containers to flexible formats. Dimensional weight freight pricing is amplifying savings from collapsed empty pouch shipping.
- Barrier Coating Maturation:Proprietary vapor-deposited oxide layers are eliminating aluminum foil requirements while maintaining oxygen transmission specifications. High-clarity film suppliers are scaling compatible substrate production.
Market Restraints
- Resin Price Volatility:Ethylene and propylene feedstock swings are destabilizing polyethylene film cost structures. Converters lack pass-through mechanisms with long-term CPG contracts.
- Equipment Capex Concentration:Vertical form-fill-seal line retrofits for clipless formats require concentrated investment with limited secondary machinery markets. German and Italian OEMs control critical retrofit component supply.
- Seal Integrity Failure Modes:Heat-seal delamination in high-fat food contact applications creates liability exposure absent mechanical clip redundancy. Insurance underwriters are tightening product recall coverage terms.
Strategic Opportunities
- Compostable Seal Layer R&D:Biodegradable alternatives represent white space as converter research pivots toward home-compostable certification. PLA and PHA blend development is attracting venture funding.
- Pet Food Premiumization:Ziplock resealable variants command price premiums in repeat-use applications where freshness retention drives brand switching. Specialty pet food brands are specifying custom die-cut dispensing features.
- California EPR Alignment:State-level extended producer responsibility legislation is creating first-mover advantage for mono-material pouch suppliers. Compliance-ready substrate portfolios are differentiating converter bids.
Industry Challenges
- Migration Testing Bottlenecks:FDA 21 CFR 177 compliance timelines for novel substrate combinations are extending go-to-market schedules. Third-party laboratory capacity constraints are amplifying delays.
- Legacy Line Integration:Retrofitting existing VFFS equipment for precision gusset formation without clip hardware requires mechanical engineering expertise scarce in regional converter workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clipless Vertical Pouches Market |
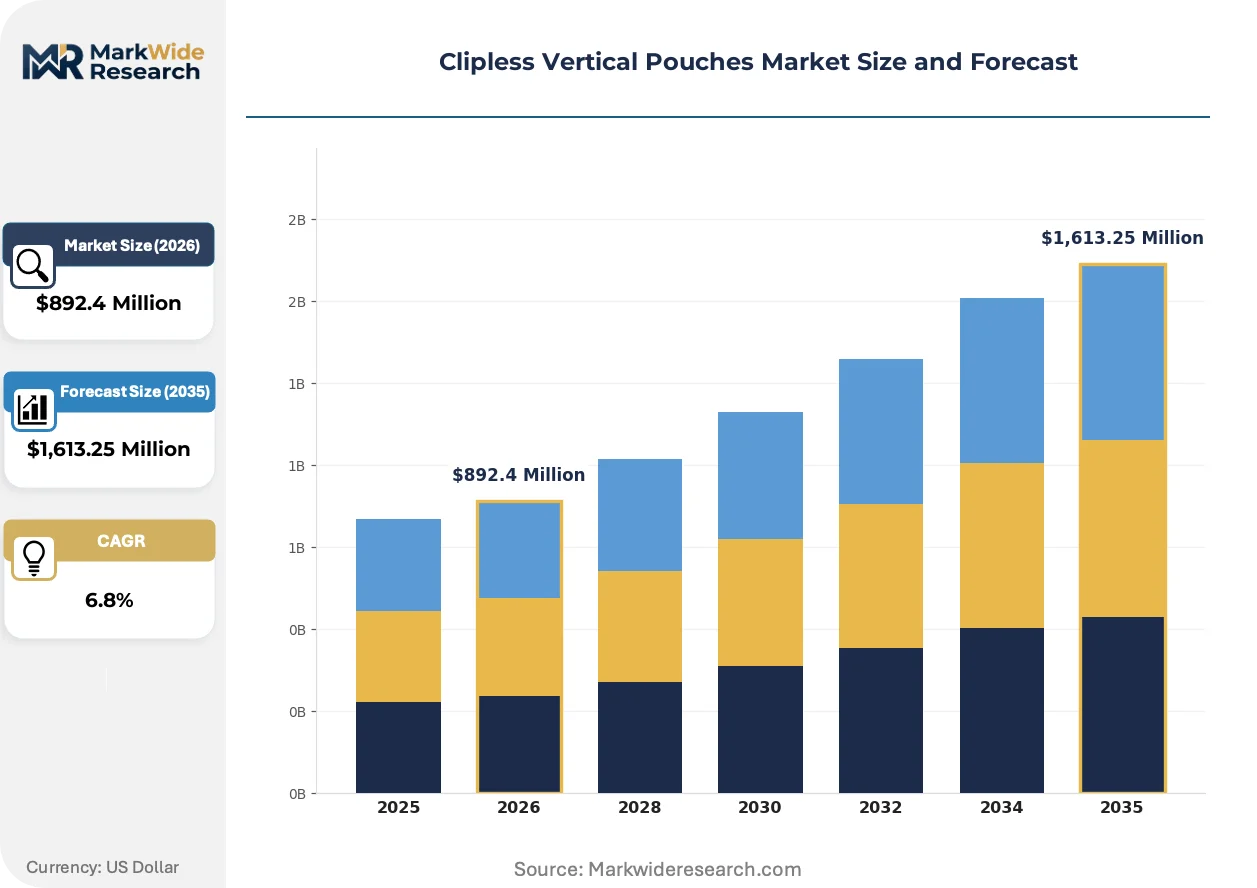
| Market Size in 2026 | $892.4 Million |
| Market Size in 2035 | $1,613.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Foil, Biodegradable Closure Method: Ziplock, Heat Seal, Snap Closure, Tear Notch Application: Snacks, Beverages, Pet Food, Personal Care Size Range: Small, Medium, Large, Custom |
| Companies Covered | Amcor Ltd, Sealed Air Corporation, Astrapak Limited, Velteko, Deve Pack, Gruber-Folien GmbH & Co. KG, Stone Paper Products GmbH, Winpak Ltd, Clondalkin Group Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clipless Vertical Pouches Market Strategic Shifts
Active developments across material science, regulatory compliance frameworks, and procurement behavior are restructuring competitive positioning in clipless vertical pouch supply. Three forces merit particular attention.
Laser-scored easy-open features are electrifying consumer convenience expectations in shelf-stable food applications. Snack producers are specifying integrated tear-notches and directional peel initiation to eliminate scissors dependency. This functionality is compressing competitive differentiation toward dispensing precision rather than closure hardware sophistication.
REACH framework revisions governing adhesive and coating substance registrations are forcing laminated structure redesigns across European supply chains. ECHA's expanded authorization requirements are accelerating mono-material polyethylene adoption by eliminating complex adhesive layers. German confectionery packagers are qualifying alternative heat-seal technologies ahead of 2025 substance restriction deadlines.
Direct converter relationships are displacing traditional distribution intermediaries in substrate procurement for mid-size food brands. Volume consolidation among regional co-packers is enabling collective purchasing agreements with film manufacturers. This channel compression is most visible in the Northeastern United States where private-label snack production clusters are forming captive supply arrangements.
Clipless Vertical Pouches Market Segmentation
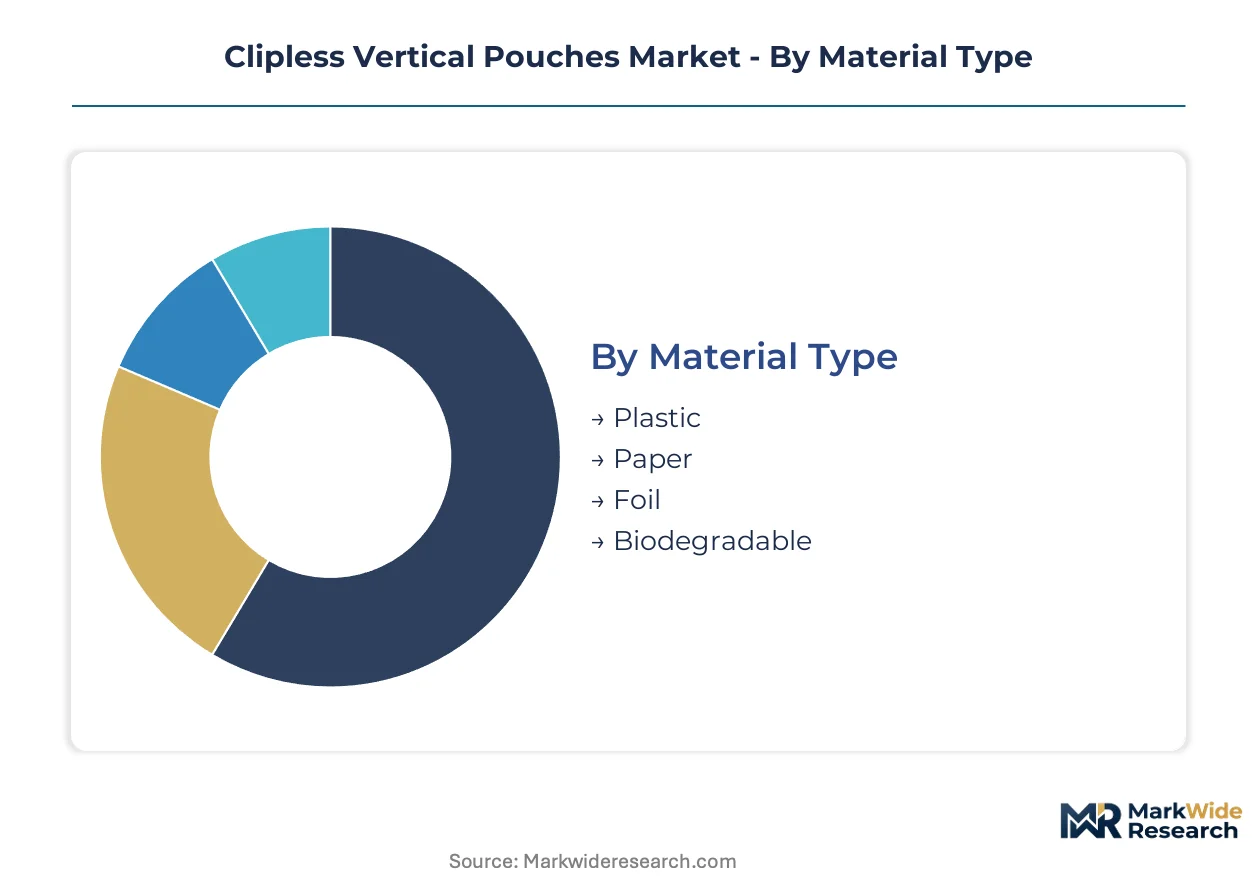
Clipless vertical pouch specifications diverge sharply across material substrates, closure mechanisms, and end-use applications. Each segmentation dimension carries distinct equipment requirements, regulatory obligations, and margin profiles that reshape supplier selection criteria.
Material Type:
Substrate transitions follow equipment upgrade cycles as converters retool lines for mono-material compatibility and heat-seal integrity without clip hardware reinforcement.
- Plastic:Polyethylene and polypropylene films dominate current installed capacity, offering seal strength and barrier performance through multi-layer coextrusion or vapor-deposited oxide coatings. Food processors in the United States are specifying these substrates to collapse dimensional weight in freight pricing.
- Biodegradable:PLA and PHA blends attract venture funding as converters pursue home-compostable certification. German packaging innovation clusters are accelerating qualification timelines for these alternatives ahead of EU Packaging and Packaging Waste Regulation thresholds.
- Paper:Fiber-based substrates with heat-seal coatings serve premium confectionery applications demanding tactile differentiation and recyclability signaling.
- Foil:Aluminum-laminate structures persist in oxygen-sensitive applications though proprietary barrier coatings are displacing foil in mid-barrier use cases.
Volume placements concentrate in Plastic; the faster expansion belongs to Biodegradable.
Closure Method:
Closure technology selection maps directly to end-use repeat-access requirements and price-tier positioning across consumer categories.
- Heat Seal:The largest installed base of converting equipment relies on precision temperature control for permanent closure without mechanical hardware. This method commands cost-sensitive snack and shelf-stable food applications where single-use consumption dominates.
- Ziplock:Interlocking profile strips enable resealability for pet food and premium snack brands where freshness retention drives repeat purchase. Specialty pet food producers are specifying custom die-cut dispensing features alongside ziplock functionality.
- Tear Notch:Laser-scored easy-open features eliminate scissors dependency in shelf-stable food applications, compressing competitive differentiation toward dispensing precision.
- Snap Closure:Rigid interlocking mechanisms serve personal care and beverage applications requiring positive tactile feedback and visible seal confirmation.
Equipment utilization clusters around Heat Seal; margin expansion follows Ziplock specifications.
Application:
End-use category requirements dictate barrier specifications, dispensing geometry, and regulatory compliance pathways.
- Snacks:Shelf-stable savory and sweet snack producers drive volume demand for high-clarity films with directional peel initiation and integrated tear-notches. North American private-label production clusters are forming captive supply arrangements with film manufacturers.
- Pet Food:Premiumization trends in specialty pet nutrition command ziplock resealable formats with custom die-cut dispensing. Repeat-use functionality supports price premiums in this category.
- Beverages:Liquid and semi-liquid contents require enhanced seal integrity and spout integration, with FDA 21 CFR 177 migration testing extending go-to-market timelines for novel substrate combinations.
- Personal Care:Cosmetic and hygiene applications prioritize tactile differentiation and premium shelf presence through snap closure and specialized surface finishes.
Demand concentrates in Snacks; steepest expansion trajectory appears in Pet Food.
Size Range:
Format dimensions align with retail channel requirements, consumption occasions, and line efficiency optimization.
- Medium:Standard pouch dimensions optimize vertical form-fill-seal line throughput for mainstream retail SKUs. This format captures the majority of current volume across snack and pet food applications.
- Custom:Brand-differentiated geometries and proprietary dispensing features enable shelf-blocking and consumer convenience innovation. Converters with precision gusset formation capability capture premium positioning.
- Small:Single-serve and sample formats serve convenience store and direct-to-consumer subscription channels with compressed cube utilization.
- Large:Club store and institutional formats prioritize cost-per-ounce efficiency with reinforced seal areas for heavier fill weights.
Throughput efficiency favors Medium; differentiation value accumulates in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Germany's Rhineland and Mexico's northern border states concentrate flexible packaging investment through accelerated depreciation schemes and duty-free resin import programs.
United States
Food processors in the Midwest and Southeast are collapsing dimensional weight ratios by converting rigid containers to flexible formats. FDA 21 CFR 177 migration testing requirements extend qualification timelines for novel substrate combinations. Private-label snack production clusters in the Northeast are forming captive supply arrangements with film manufacturers.
Germany
Confectionery and snack producers in Bavaria and North Rhine-Westphalia operate dense packaging innovation clusters accelerating mono-material polyethylene adoption. ECHA's REACH framework revisions force laminated structure redesigns ahead of 2025 substance restriction deadlines. The country's vertical form-fill-seal machinery OEMs control critical retrofit component supply for clipless format transitions.
China
Domestic converters in the Yangtze River Delta are scaling high-clarity film production for export-oriented food brands. SAMR's national standards for food-contact materials impose migration testing protocols similar to FDA frameworks. Zhejiang and Jiangsu provinces host concentrated equipment manufacturing zones supplying regional VFFS line retrofits.
Mexico
Maquiladora operations in Nuevo León and Baja California serve North American CPG brands seeking tariff-advantaged pouch converting. The country's proximity to Texas resin supply chains compresses polyethylene film logistics costs. Monterrey-based co-packers are qualifying mono-material substrates for California-bound exports facing state-level EPR compliance requirements.
India
Mid-size snack brands in Maharashtra and Gujarat are bypassing distribution intermediaries through direct converter relationships for substrate procurement. FSSAI's food-contact material regulations mandate compliance documentation increasingly harmonized with Codex Alimentarius standards. Ahmedabad and Mumbai packaging corridors are consolidating volume for collective purchasing agreements with global film suppliers.
Clipless Vertical Pouches Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated film suppliers commanding premium positioning in mono-material substrate supply while regional converters capture mid-market volume through equipment retrofit services. The vendor base organizes around three archetypes: global substrate suppliers with captive polymer production, specialized machinery OEMs controlling precision gusset formation technology, and regional co-packers consolidating demand for collective procurement. Dominant competitive moves include backward integration into resin compounding and strategic partnerships between film manufacturers and vertical form-fill-seal equipment providers.
Within the global substrate tier, Amcor Ltd and Sealed Air Corporation exemplify integrated supply structures spanning polymer production through finished film conversion. Gruber-Folien GmbH & Co. KG anchors European supply positioning as a specialized high-clarity film fabricator. These three entities occupy distinct competitive spaces: the Australian-registered multinational with broad geographic manufacturing footprint, the US-based packaging conglomerate with proprietary barrier coating systems, and the German limited partnership focused on regional vertical form-fill-seal line compatibility.
| Leading Market Players |
|---|
| Amcor Ltd |
| Sealed Air Corporation |
| Astrapak Limited |
| Velteko |
| Deve Pack |
| Gruber-Folien GmbH & Co. KG |
| Stone Paper Products GmbH |
| Winpak Ltd |
| Clondalkin Group Holdings B.V. |
| Others |
Value Chain & Pricing Dynamics
EU Packaging and Packaging Waste Regulation recyclability thresholds are compelling CPG brands to specify mono-material polyethylene substrates, forcing converters to absorb equipment retooling costs and compressing margin structures across mid-tier supply tiers.
Pricing Analysis
Short lead-time premiums for ziplock resealable formats run 15-25% above standard heat-seal variants due to interlocking profile strip sourcing constraints. Contract-based long-term offtake agreements dominate volume procurement, with price differentiation anchored in certification grade and volume scale. Cost compression in mid-tier snack applications is intensifying because resin pass-through mechanisms remain incomplete under annual CPG contracting cycles. Private-label brands exhibit highest price sensitivity; premium pet food labels demonstrate lowest.
Supply Chain Analysis
Direct-to-converter channels handle mid-size food brand demand as collective purchasing agreements displace traditional distribution intermediaries. Geographic supply concentration centers on Germany, the United States, and China for high-clarity film fabrication and VFFS equipment manufacturing. Raw material dependencies draw from ethylene feedstock, vapor-deposited oxide coatings, and precision gusset formation components. Single-source vulnerability in German and Italian OEM retrofit component supply creates structural risk. Distribution runs through regional co-packer networks consolidating volume for captive film supply arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mono-material polyethylene structures are displacing multi-layer laminates in a technology-transition phase, with proprietary barrier coating systems eliminating aluminum foil requirements and legacy clip hardware.
For Market Incumbents: Acquire specialized high-clarity film fabrication assets to secure substrate qualification timelines ahead of EU substance restriction deadlines. Deepen backward integration into resin compounding to offset ethylene price volatility and defend margin position against emerging regional converters.
For New Entrants and Emerging Players: Mid-size Indian snack brands bypassing distribution intermediaries represent the most penetrable buyer archetype. Target direct converter relationships in Maharashtra and Gujarat packaging corridors. Pursue home-compostable certification for PLA-PHA blend substrates to capture biodegradable white space.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized machinery OEMs controlling precision gusset formation technology given accelerating VFFS line retrofit demand. Long-term viability favors suppliers with captive polymer production and California EPR compliance-ready portfolios. Monitor state-level extended producer responsibility legislation passage as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene supply insulates converters from feedstock volatility under annual CPG contracts. |
| Proprietary Barrier Coating Development | Vapor-deposited oxide layers eliminate aluminum foil while maintaining oxygen transmission specifications. |
| Home-Compostable Certification Pursuit | PLA-PHA blend qualification captures fastest-expanding material category in converter R&D pipelines. |
| VFFS Equipment Retrofit Partnership | Precision gusset formation capability without clip hardware captures premium positioning in custom formats. |
| California EPR Compliance Alignment | Mono-material substrate portfolios differentiate converter bids for state-bound export volumes. |
Study Parameters
Document review covered FDA 21 CFR 177 filings, ECHA REACH substance registrations, EU Packaging and Packaging Waste Regulation drafts, and customs trade data, complemented by interviews with flexible packaging plant managers, CPG procurement leads, VFFS equipment OEM technical directors, and film distributor channel partners. Secondary validation drew from SEC 10-K disclosures, industry association reports, and food-contact material compliance databases. Bottom-up volume modeling and top-down value triangulation cross-referenced substrate production estimates with end-use consumption patterns.
Historical shipment data cross-referenced against expert panel input across material type, closure method, application, and size range dimensions. CAGRs were derived from segmented growth trajectory analysis over the projection horizon. Industry-specific forecast inputs included equipment retooling cycle timing, regulatory compliance deadline clustering, and resin price elasticity assumptions.
Revisions become necessary when EPR legislation timelines accelerate, barrier coating technology breakthroughs displace incumbent substrates, or VFFS equipment OEM consolidation alters retrofit component availability. Forecasts reflect documented assumptions regarding mono-material adoption curves and logistics cost arbitrage sustainability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Russia Pouch Packaging Market
Pouch
Thailand Pouch Packaging Market
Pouch
Peel Pouches Market
Pouch
Wrap-Around Packers Market
Pouch
Fin Seal Pouches Market
Pouch
Flexible Plastic Pouches Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Portion Control Packs Market
Pouch
Foam Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Feed Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Retort Pouch Market
Pouch
Brazil Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Poland Pouch Packaging Market