
 Slider Pouches Market | 2026-2036
Slider Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Slider Pouches Market Analytics
Asian flexible packaging capacity is decoupling from European converter dependence as regional resin integration deepens. Amcor Plc leverages its multi-continent extrusion network to supply food-grade slider films with consistent melt-index specifications. Mondi Group plc anchors its European pouch operations through integrated kraft paper and barrier film production. Berry Global Group, Inc. competes on scale in North American press-seal formats for frozen food applications.
Slider pouches are resealable flexible containers incorporating interlocking closure rails heat-sealed to laminated film webs, typically constructed from polyethylene, polypropylene, or bio-based polymers with oxygen transmission rates below 0.5 cc/m²/day for protein preservation. The closure type dimension shows zip-lock configurations dominating food retail due to audible seal confirmation, while press-seal variants lead in travel and organization use cases where hermetic integrity matters less than tactile speed. Biodegradable product types are capturing R&D investment as compostability certifications become a procurement gate for European retailers, though plastic retains cost advantages in e-commerce fulfillment where unit economics override sustainability premiums.
FDA food contact substance regulations govern resin approvals and migration limits for US-bound slider pouches, while EU REACH and the Packaging and Packaging Waste Regulation enforce recyclability labeling and extended producer fee structures. These frameworks elevate compliance costs for imported films but create structural advantages for converters with in-house regulatory affairs teams and certified laboratory testing. Stakeholders must track evolving state-level extended producer responsibility laws in the US and pending EU methodology changes for recycled content claims to avoid stranded inventory or label redesign cycles.
Market Dynamics
Material substitution pressures are fragmenting the slider pouch supply base as converters split capacity between fossil-based films and certified compostable alternatives to satisfy divergent retailer procurement mandates.
Growth Catalysts
- EU Single-Use Plastics Directive:The framework accelerates transitions toward biodegradable substrates by banning certain conventional plastic formats and mandating extended producer responsibility fees across member states.
- Portion-controlled food storage:Residential kitchen applications are expanding as consumers prioritize waste reduction and meal-prepping convenience in urban households.
- German retail private-label penetration:High concentration of store-brand packaging demand concentrates order volumes with converters capable of rapid format switching and short-run customization.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with crude oil indices, compressing converter margins on fixed-price annual contracts with retailers.
- Barrier film supply concentration:Oxygen transmission rate specifications below 0.5 cc/m²/day require specialized coextrusion capacity concentrated among integrated petrochemical-to-film producers.
- Compostable performance gaps:Bio-based polymers exhibit inferior moisture barrier properties versus conventional multi-layer structures, limiting protein preservation applications.
Strategic Opportunities
- Indian organized retail expansion:Modern grocery and e-commerce fulfillment growth creates first-mover positioning for converters establishing local lamination and zipper-track assembly.
- Pharmaceutical compliance packaging:Child-resistant slider mechanisms represent an emerging application segment with stringent testing protocols and premium pricing potential.
- US state-level extended producer responsibility laws:Pending legislation in California, Oregon, and Maine will mandate recycled content minimums, advantaging converters with pre-qualified post-consumer resin streams.
Industry Challenges
- Migration testing laboratory capacity:FDA food contact substance approvals require specialized analytical chemistry expertise that resides in limited third-party facilities, extending new product qualification timelines.
- Legacy heat-seal equipment retrofitting:Converters face capital expenditure burdens to adapt existing lines for bio-based films with distinct melt-flow characteristics and sealing temperature windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slider Pouches Market |
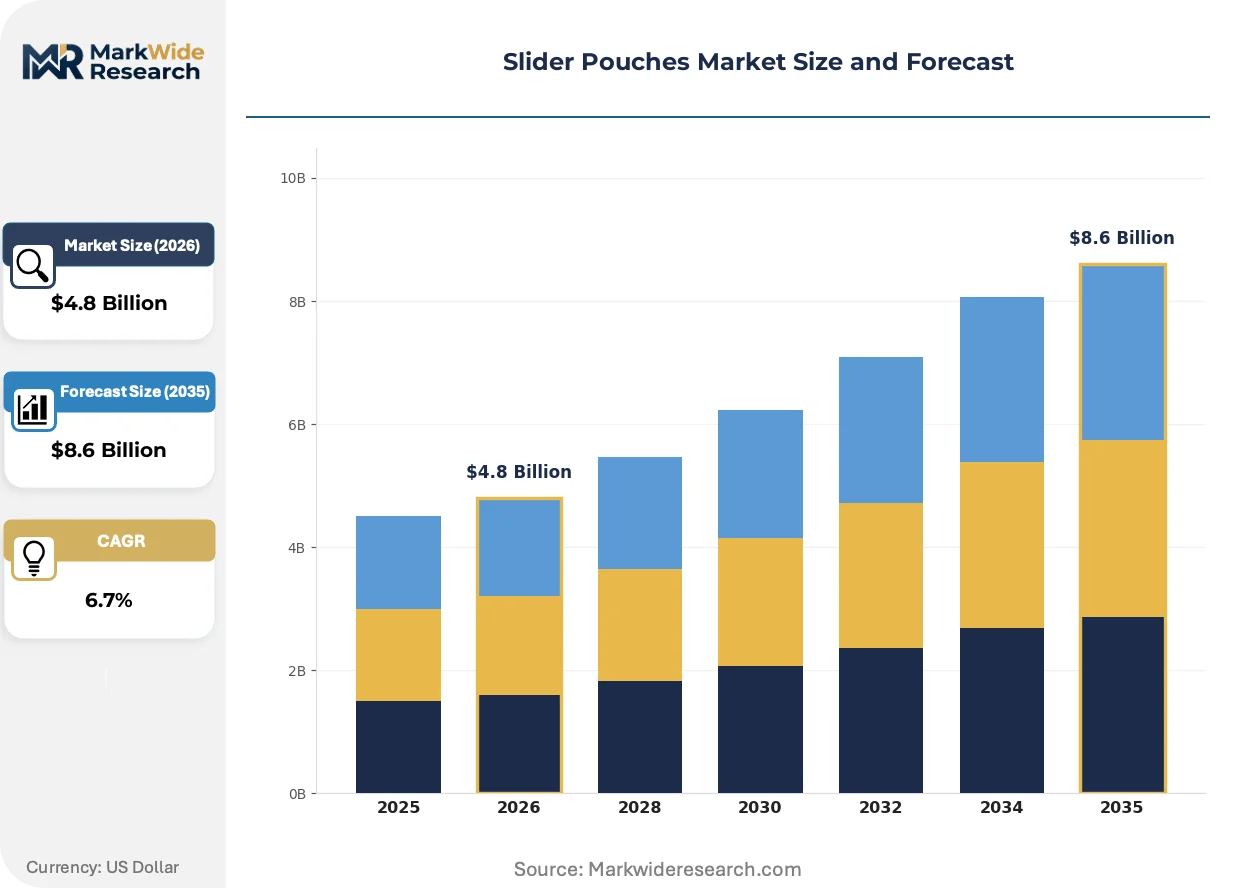
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Paper, Biodegradable, Reusable Closure Type: Zip-Lock, Press-Seal, Velcro, Adhesive Use Case: Food Storage, Packaging, Travel, Organization End User: Households, Retailers, Manufacturers, E-commerce |
| Companies Covered | Amcor Plc, Mondi Group plc, Berry Global Group, Inc., Sealed Air Corporation, Sonoco Products Company, Winpak Ltd., Printpack, Inc., Proampac LLC, Constantia Flexibles Group GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slider Pouches Market Evolving Landscape
Digital printing integration and mono-material structural designs are converging to transform how slider pouches are specified, produced, and recovered at end-of-life across retail supply chains.
Mono-material polyethylene slider pouches are decentralizing recycling infrastructure requirements by eliminating aluminum oxide or ethylene vinyl alcohol barrier layers that contaminate mechanical reprocessing streams. European retailers including Ahold Delhaize and Carrefour are accelerating adoption to meet 2025 recyclability labeling mandates. The structural consequence is compressing demand for complex multi-layer laminates while elevating converter investments in metallized PE alternatives and plasma-enhanced barrier coatings.
EU REACH substance restrictions and the Packaging and Packaging Waste Regulation are forcing systematic substitution of per- and polyfluoroalkyl substances in grease-resistant slider pouch applications. Industrial consequence includes accelerated R&D spending on silicone-based and bio-wax barrier coatings by film suppliers. The frozen food and pet treat segments are most affected, with German and Dutch converters already retrofitting lines to handle reformulated sealant webs.
Direct-to-retailer specification platforms are compressing traditional distributor channels for standard-format slider pouches. Brand owners now upload dimensional and artwork requirements to converter portals, bypassing regional packaging distributors that previously managed inventory and logistics. This pattern is most visible in North American e-commerce fulfillment and European discount grocery private-label sourcing, where order fragmentation and shorter lead times reward responsive manufacturing networks over stocked distribution.
Slider Pouches Market Segmentation
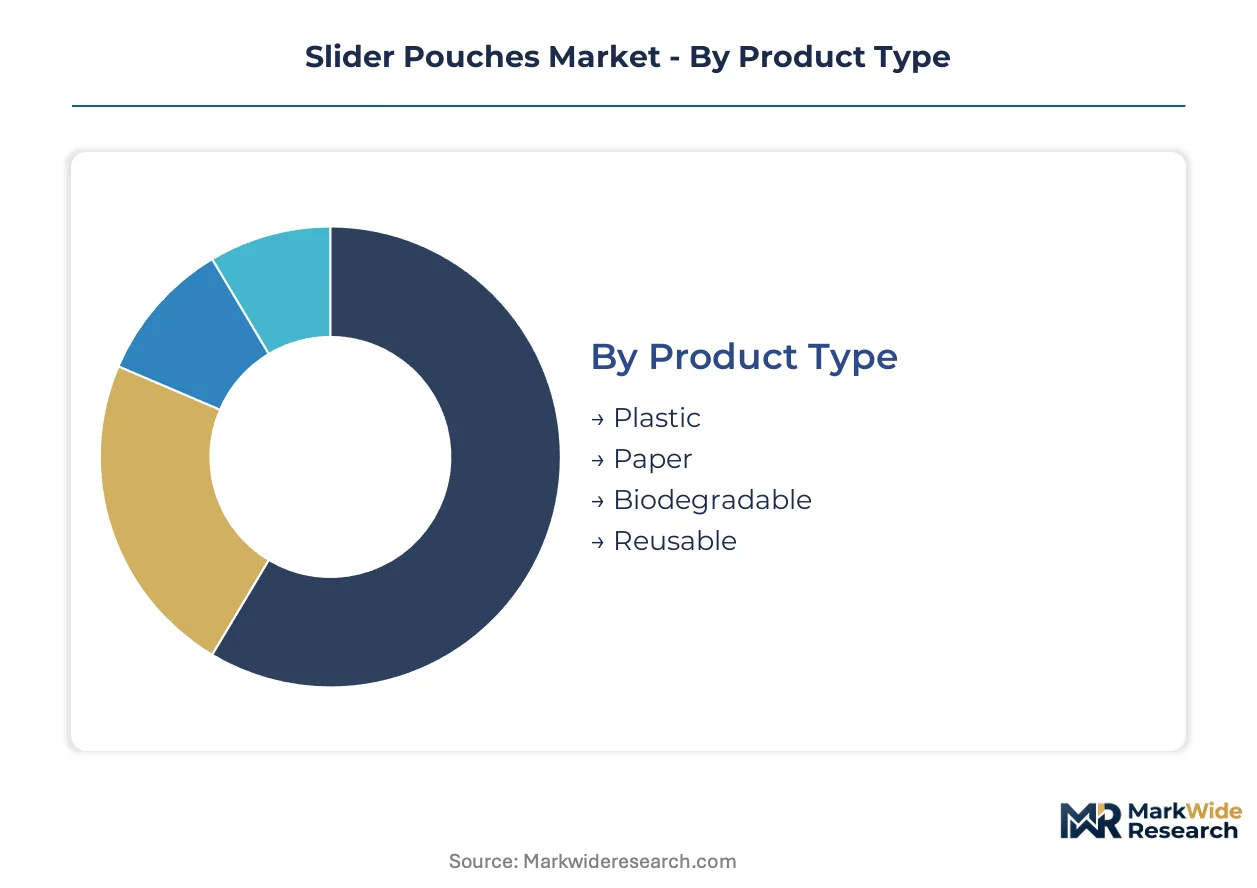
Slider pouch specifications diverge sharply across end-use contexts, with barrier requirements, regulatory compliance, and reseal frequency dictating material and closure selections. Converters align extrusion capacity against these segment-specific performance thresholds rather than pursuing universal formats.
Product Type:
Supply concentration in fossil-based resin streams dominates converter capacity allocation, though certified compostable lines are capturing dedicated investment to satisfy divergent retailer procurement mandates.
- Plastic:Multi-layer polyethylene and polypropylene structures with ethylene vinyl alcohol or aluminum oxide barriers achieve oxygen transmission rates below 0.5 cc/m²/day for protein preservation. German discount grocery chains and US frozen food brands concentrate order volumes here due to cost efficiency and established recycling infrastructure.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations certified to EN 13432 or ASTM D6400 standards serve EU retailers facing Packaging and Packaging Waste Regulation compliance deadlines. Dutch and French supermarket private-label programs are accelerating volume commitments despite moisture barrier performance gaps versus conventional films.
- Paper:Kraft-based substrates with silicone or bio-wax grease resistance target frozen food and pet treat segments replacing per- and polyfluoroalkyl substance coatings under REACH restrictions.
- Reusable:Heavy-gauge silicone or PEVA constructions emphasize dishwasher durability for meal-prep and lunch-portioning applications in urban US and UK households.
Plastic absorbs the bulk of installed capacity; biodegradable is expanding most quickly.
Closure Type:
Application-specific reseal mechanics create distinct equipment and tooling requirements across converter operations, with audible confirmation features commanding premium positioning in food retail.
- Zip-Lock:Interlocking polyethylene or polypropylene rails with tactile engagement confirmation dominate supermarket protein and produce packaging. Ahold Delhaize and Carrefour specifications require mono-material compatibility for 2025 recyclability labeling compliance.
- Press-Seal:Grooved track designs optimize for speed of access in travel organization and office supply applications where hermetic integrity matters less than single-motion opening. North American e-commerce fulfillment centers favor this format for reduced per-unit handling time.
- Velcro:Hook-and-loop systems appear in heavy-use reusable pouch designs for crafting and hardware storage segments.
- Adhesive:Strip-seal constructions serve single-use pharmaceutical and diagnostic kit packaging with contamination-sensitive opening protocols.
Zip-lock claims the largest share of food-contact regulatory approvals; press-seal is climbing the fastest in non-food e-commerce channels.
Use Case:
End-use performance specifications fragment demand across barrier requirements, reseal cycle durability, and print surface requirements for retail shelf presence.
- Food Storage:Residential kitchen applications emphasize portion control and waste reduction with oxygen barrier preservation for meal-prepped proteins. Urban household penetration in Germany and the UK is deepening as private-label assortments expand.
- Packaging:Frozen food and pet treat converters face systematic per- and polyfluoroalkyl substance substitution under EU REACH, accelerating silicone-based barrier coating adoption.
- Travel:TSA-compliant liquid containment and compression-packing efficiency drive demand for leak-tested press-seal formats in US and UK outbound tourism recovery.
- Organization:Craft, hardware, and document storage applications prioritize clarity and reseal cycle longevity over barrier performance.
Food storage commands the deepest converter technical investment; packaging is gaining share fastest from regulatory-driven material transitions.
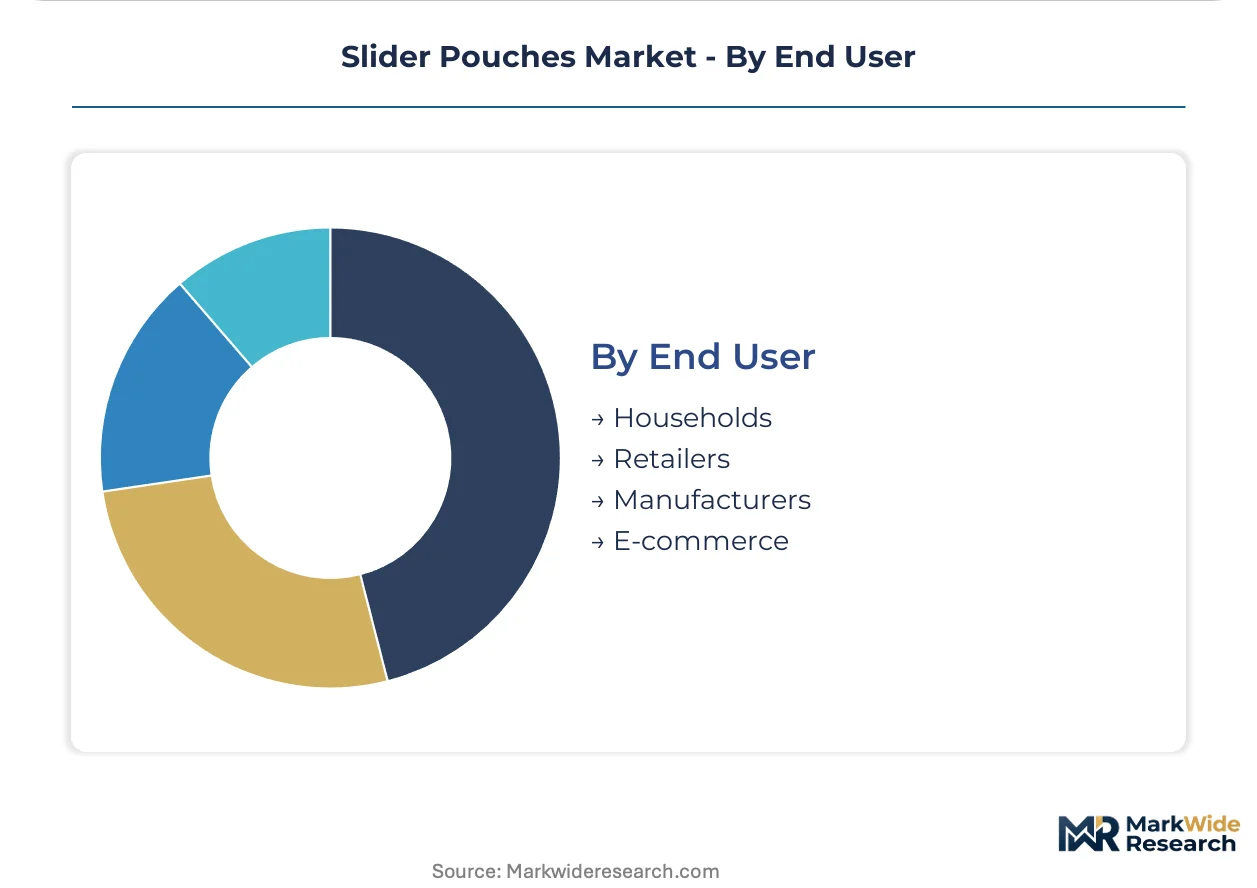
End User:
Procurement scale and specification authority concentrate differently across household, retail, manufacturing, and logistics channels, shaping converter sales organization structures.
- Households:Individual consumers select based on unit price and shelf visibility in mass retail environments, with German and UK shoppers demonstrating strongest willingness to pay compostability premiums.
- Retailers:Private-label specification authority in Germany concentrates volume with converters capable of rapid format switching and short-run customization for store-brand differentiation.
- Manufacturers:CPG brand owners require FDA food contact substance documentation and migration testing for US-bound protein packaging, extending qualification timelines.
- E-commerce:Fulfillment operators prioritize dimensional efficiency and damage resistance over print quality, with Indian organized retail expansion creating first-mover positioning opportunities.
Retailers control the largest committed volumes; e-commerce is expanding most quickly in Asia-Pacific fulfillment infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German polyethylene resin clusters anchor European converter supply chains for slider pouch lamination and zipper-track assembly. Regional demand concentrates in industrial zones with integrated extrusion and converting capacity.
Germany
Private-label penetration in discount grocery chains drives format-switching demands on converter capacity. The EU Packaging and Packaging Waste Regulation enforces recyclability labeling deadlines that elevate mono-material specifications. The Rhine-Ruhr industrial corridor hosts integrated film extrusion and pouch converting operations serving Ahold Delhaize and Carrefour procurement networks.
United States
Frozen food brands and e-commerce fulfillment operators concentrate order volumes for press-seal and zip-lock configurations. FDA food contact substance regulations govern migration testing protocols for protein preservation applications. The Midwest manufacturing belt around Chicago and Milwaukee anchors multi-layer barrier film production with oxygen transmission specifications below 0.5 cc/m²/day.
China
Flexible packaging capacity expansion decouples domestic supply from European converter dependence as regional resin integration deepens. GB standards and SAMR oversight govern food-contact material approvals for export-bound production. The Yangtze River Delta cluster around Shanghai concentrates lamination equipment manufacturing and zipper-track component assembly for Asian retail supply chains.
India
Organized retail and e-commerce fulfillment infrastructure buildout creates first-mover positioning for local lamination and slider assembly investments. FSSAI packaging regulations establish food-contact compliance frameworks for domestic and export markets. The Maharashtra-Gujarat industrial corridor near Mumbai and Ahmedabad attracts converter capacity targeting modern grocery private-label programs.
Netherlands
Compostability certification procurement gates for European retailers accelerate biodegradable slider pouch adoption despite performance gaps. REACH substance restrictions force systematic substitution of per- and polyfluoroalkyl substances in grease-resistant applications. The Rotterdam-Antwerp petrochemical hub supplies bio-based polymer feedstocks to Dutch converters retrofitting lines for certified compostable production.
Slider Pouches Market Competitive Landscape
Global majors compete with regional champions across extrusion network coverage and regulatory compliance infrastructure. The vendor base splits between integrated petrochemical-to-film producers and specialized pouch converters. Three archetypes dominate: multi-continent extrusion networks, integrated kraft-paper and barrier operations, and scale-driven North American press-seal specialists. Capacity expansion and mono-material portfolio diversification represent the dominant competitive moves as recyclability mandates compress demand for complex multi-layer structures.
Within the integrated packaging tier, Amcor Plc and Mondi Group plc exemplify archetypes with captive resin and film production capabilities. Berry Global Group, Inc. occupies a position among scale-focused converters competing on volume throughput for standardized formats. These three entities represent distinct strategic postures: global extrusion network deployment, European kraft-paper integration, and North American press-seal scale concentration.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group plc |
| Berry Global Group, Inc. |
| Sealed Air Corporation |
| Sonoco Products Company |
| Winpak Ltd. |
| Printpack, Inc. |
| Proampac LLC |
| Constantia Flexibles Group GmbH |
| Others |
Value Network & Pricing Analysis
Mono-material polyethylene transitions are simultaneously compressing barrier film costs and redistributing converter margins toward certified recyclability tiers. This production-method shift concentrates pricing power with extrusion-integrated suppliers capable of metallized PE alternatives while forcing multi-layer laminate specialists into cost-passing negotiations with German and Dutch retailers.
Pricing Analysis
Migration testing documentation and compostability certification bundling separate premium converter tiers from unbundled commodity suppliers. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA food contact substance approval status and EN 13432 certification. Cost compression in standard-tier fossil-based films is intensifying because fixed-price annual contracts with retailers cannot absorb polyethylene feedstock volatility. E-commerce fulfillment operators demonstrate highest price sensitivity due to unit economics pressures, while pharmaceutical brand owners show lowest sensitivity given qualification timeline risks.
Supply Chain Analysis
Specialized coextrusion capacity for oxygen barrier films rests on integrated petrochemical-to-film producers in Germany, the United States, and China. Raw material dependencies center on polyethylene and polypropylene resins, ethylene vinyl alcohol barrier polymers, and bio-based polylactic acid feedstocks. Single-source vulnerability concentrates in aluminum oxide deposition equipment for high-barrier specifications. Distribution runs through direct-to-retailer specification platforms that bypass traditional regional packaging distributors for standard-format orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH substance restrictions and the Packaging and Packaging Waste Regulation construct a cost-of-compliance barrier that advantages converters with in-house regulatory affairs teams and certified laboratory testing infrastructure.
For Market Incumbents: Lock in mono-material polyethylene capacity ahead of recyclability labeling deadlines to defend against Asian flexible packaging decoupling. Prioritize backward integration into zipper-track component assembly to control format-switching responsiveness for German private-label programs. Pre-qualify post-consumer resin streams before US state-level extended producer responsibility laws activate recycled content minimums. For New Entrants and Emerging Players: Capture Indian organized retail expansion through local lamination investments targeting modern grocery private-label programs. Penetrate pharmaceutical compliance packaging segments with child-resistant slider mechanisms where testing protocol barriers limit incumbent replication. Pursue joint venture structures with established European converters for technology transfer rather than greenfield certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap converters with captive extrusion networks and pre-qualified regulatory documentation. Long-term viability favors entities with diversified substrate portfolios spanning fossil-based and certified compostable lines. Watch EU methodology changes for recycled content claims as an inflection indicator for stranded inventory risk among single-substrate specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Portfolio Diversification | Amcor Plc and Mondi Group plc accelerate metallized PE alternatives to meet Ahold Delhaize recyclability mandates. |
| Backward Integration into Resin Production | Captive polyethylene supply insulates German converters from crude oil-indexed margin compression on fixed-price retail contracts. |
| Compostability Certification Investment | EN 13432 and ASTM D6400 procurement gates unlock Dutch and French supermarket private-label volume commitments. |
| Direct-to-Retailer Platform Development | Bypassing regional distributors captures North American e-commerce fulfillment demand with shorter lead time responsiveness. |
| Pharmaceutical Compliance Packaging Entry | Child-resistant slider mechanisms access premium pricing tiers with stringent FDA testing protocol barriers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this slider pouches market assessment. Primary interviews with extrusion plant managers, retail category buyers, regulatory affairs directors, and flexible packaging procurement leads combined with FDA food contact substance databases, EU ECHA substance restriction registers, and FSSAI packaging compliance frameworks. Bottom-up shipment analysis and top-down resin consumption estimates underwent triangulation validation.
Data-stream reconciliation across product type, closure mechanism, use case, and end-user procurement channel dimensions generated volume and value outputs. CAGRs derived from segment-level growth rate blending and macroeconomic elasticity adjustments incorporated oxygen transmission rate specification trends and mono-material adoption curves throughout the forecast period.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Packaging and Packaging Waste Regulation enforcement timing and bio-based polymer moisture barrier performance breakthroughs. Forecasts reflect documented assumptions on retailer procurement mandate acceleration and resin price volatility persistence. A small set of named triggers—US state EPR law implementation, REACH substance restriction expansion, and Indian organized retail infrastructure buildout—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pillow Pouch Packaging Market
Pouch
Russia Pouch Packaging Market
Pouch
Child Resistant Pouches Market
Pouch
OPP Pouches Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Poland Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
Monodose Packs Market
Pouch
Retort Pouch Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Doyen Style Pouches Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Kraft Pouch Market