
 Global Automotive Damper Pulley Market | 2026-2036
Global Automotive Damper Pulley Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Damper Pulley Market Analysis
Light commercial vehicle electrification is recalibrating damper pulley specifications across global supply chains. NTN Corporation leverages its bearing-to-pulley integration expertise to dominate precision manufacturing for hybrid drivetrains. Gates Corporation sustains channel control through captive distribution to North American OEM service networks. JTEKT Corporation anchors Asian supply with localized forging and machining operations in Thailand and India.
An automotive damper pulley is a torsional vibration damper mounted on the crankshaft nose, typically comprising a cast iron or steel hub, an elastomeric rubber damping ring, and an outer steel or aluminum inertia ring bonded through vulcanization or press-fit assembly, engineered to attenuate harmonic vibrations across engine speed ranges and protect accessory drive components from fatigue failure. Serpentine belt configurations occupy the largest volume share due to their consolidation of multiple accessories onto a single drive path, while electronic damping technologies represent the fastest-growing technology segment as torque-based adaptive control displaces passive rubber-inertia designs. Steel material grades retain margin concentration in heavy-duty commercial applications where thermal cycling demands exceed aluminum fatigue limits.
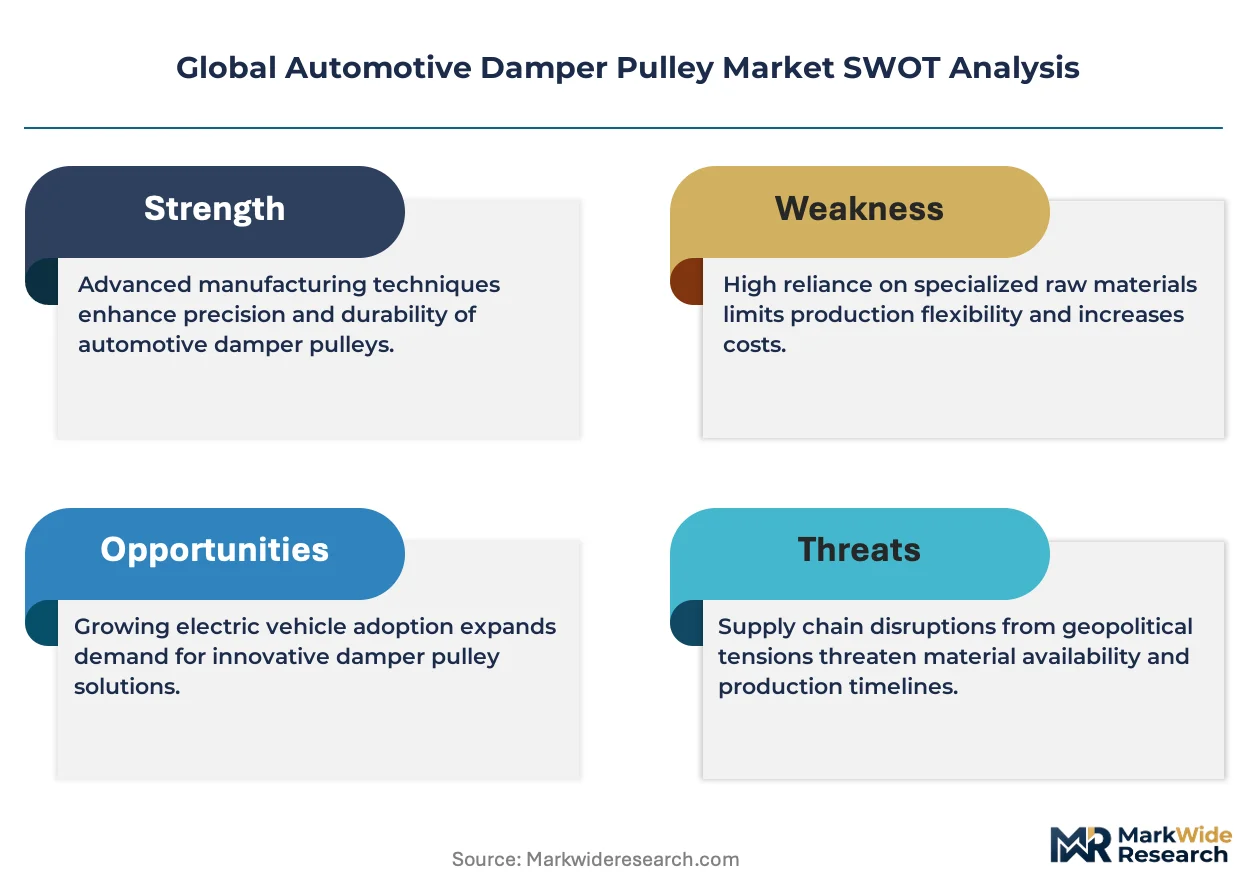
The EPA enforces tailpipe and evaporative emissions standards that indirectly mandate crankshaft damper precision to maintain engine mapping stability, while the EU Green Deal and REACH constrain elastomer compound formulations and restrict certain curing agents in rubber-to-metal bonding processes. China's MIIT enforces GB standards for passenger vehicle NVH that specify maximum permissible torsional amplitude at idle and rated speed conditions. Stakeholders must monitor how evolving Euro 7 emissions protocols and corresponding EPA Tier 4 harmonization efforts recalibrate damping tolerance specifications across export-bound powertrain platforms.
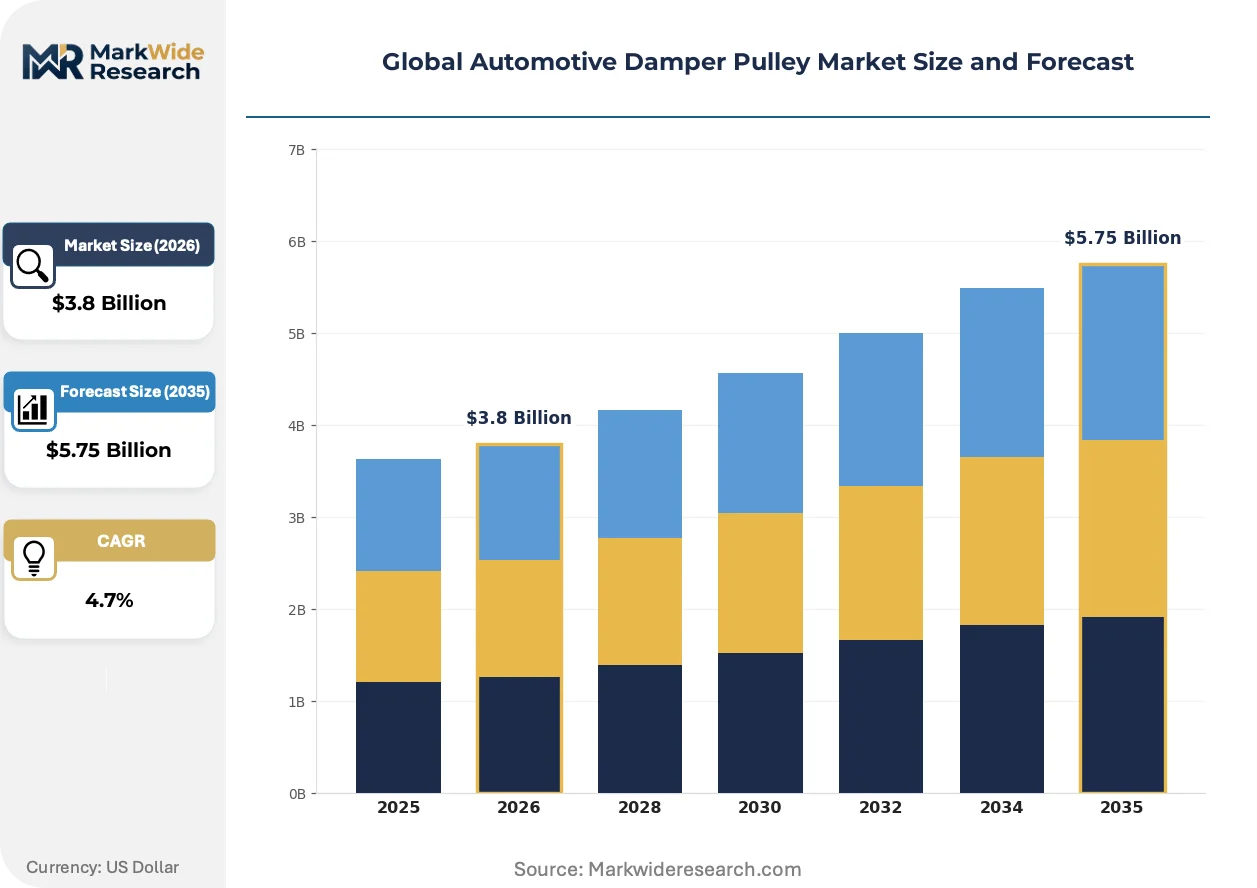
Market Dynamics
Electronic damping architectures are displacing passive rubber-inertia assemblies across hybrid and battery-electric powertrains, forcing suppliers to requalify bonding chemistries and recalibrate forging tolerances for torque-adaptive control modules.
Growth Catalysts
- EU F-Gas Regulation:Tightened vibration control standards for climate-relevant refrigerant compressors mandate precision crankshaft dampers in light commercial vehicle HVAC systems.
- Thailand forging clusters:Localized machining operations serving ASEAN assembly plants reduce logistics friction for Japanese and Korean OEM supply programs.
- Serpentine belt consolidation:Single-path accessory drive architectures multiply damper pulley duty cycles per vehicle, expanding unit volume per powertrain platform.
Market Restraints
- Natural rubber compound volatility:Elastomer input costs fluctuate with Southeast Asian weather patterns and plantation labor availability, compressing margin predictability for vulcanized bonding processes.
- Stuttgart-Wolfsburg supplier concentration:German automotive manufacturing corridors dominate precision forging capacity, creating geographic vulnerability for export-bound OEM programs.
- Aluminum fatigue limits:Thermal cycling demands in heavy-duty commercial applications constrain material substitution away from steel grades, limiting lightweighting pathways.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced automotive components attract forging investments to serve domestic passenger vehicle NVH compliance.
- Electronic-mechanical convergence:Integration of torque sensors with inertia rings enables real-time adaptive damping for plug-in hybrid transient loads.
- North American OEM service networks:Captive distribution channels for replacement pulleys capture aftermarket margin pools as vehicle aging extends service intervals.
Industry Challenges
- Elastomer-to-metal bonding certification:REACH-constrained curing agent approvals delay new compound qualification timelines for European export platforms.
- Dual carbon alignment:China's MEE enforcement of carbon intensity benchmarks requires foundry energy audits that complicate forging supply base consolidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Damper Pulley Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serpentine Belt, V-Belt, Chain, Accessory Drive Material: Steel, Aluminum, Plastic, Rubber End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Fleet Operators Technology: Mechanical, Hydraulic, Electronic, Hybrid |
| Companies Covered | NTN Corporation, Zhejiang Dongxing Auto Parts, Dayco, GT Automotive, Sintercom India, JTEKT Corporation, Vibracoustic, Breda Lorett, Gates Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Damper Pulley Market Emerging Trajectories
Adaptive damping systems are compressing development cycles for bonded elastomer assemblies as torque-based control displaces fixed-inertia designs across electrified powertrains.
Magnetorheological fluid damping is consolidating precision manufacturing expertise around Stuttgart suppliers who already command crankshaft sensor integration capabilities. European OEMs are adopting these modules for 48V mild-hybrid architectures at accelerated validation paces. The technology is consolidating supplier tiers by merging damper, sensor, and controller competencies into single-source procurement relationships.
China's MIIT GB standards for passenger vehicle NVH specify maximum torsional amplitude thresholds that force recalibration of idle-speed damping maps. Domestic OEMs must revalidate pulley specifications for compliance testing at certified facilities in Shanghai and Tianjin. Export-bound powertrain platforms face dual-certification burdens as Euro 7 protocols harmonize with EPA Tier 4 tolerance specifications.
Fleet operators now specify dampers through total-cost-of-ownership frameworks rather than unit procurement metrics, unbundling after-sales vibration monitoring from initial component supply. This compresses traditional parts-distributor margins while expanding service-contract revenue pools for integrated system providers. The shift is most visible in German commercial vehicle leasing programs where predictive maintenance clauses mandate real-time torsional telemetry.
Global Automotive Damper Pulley Market Segmentation
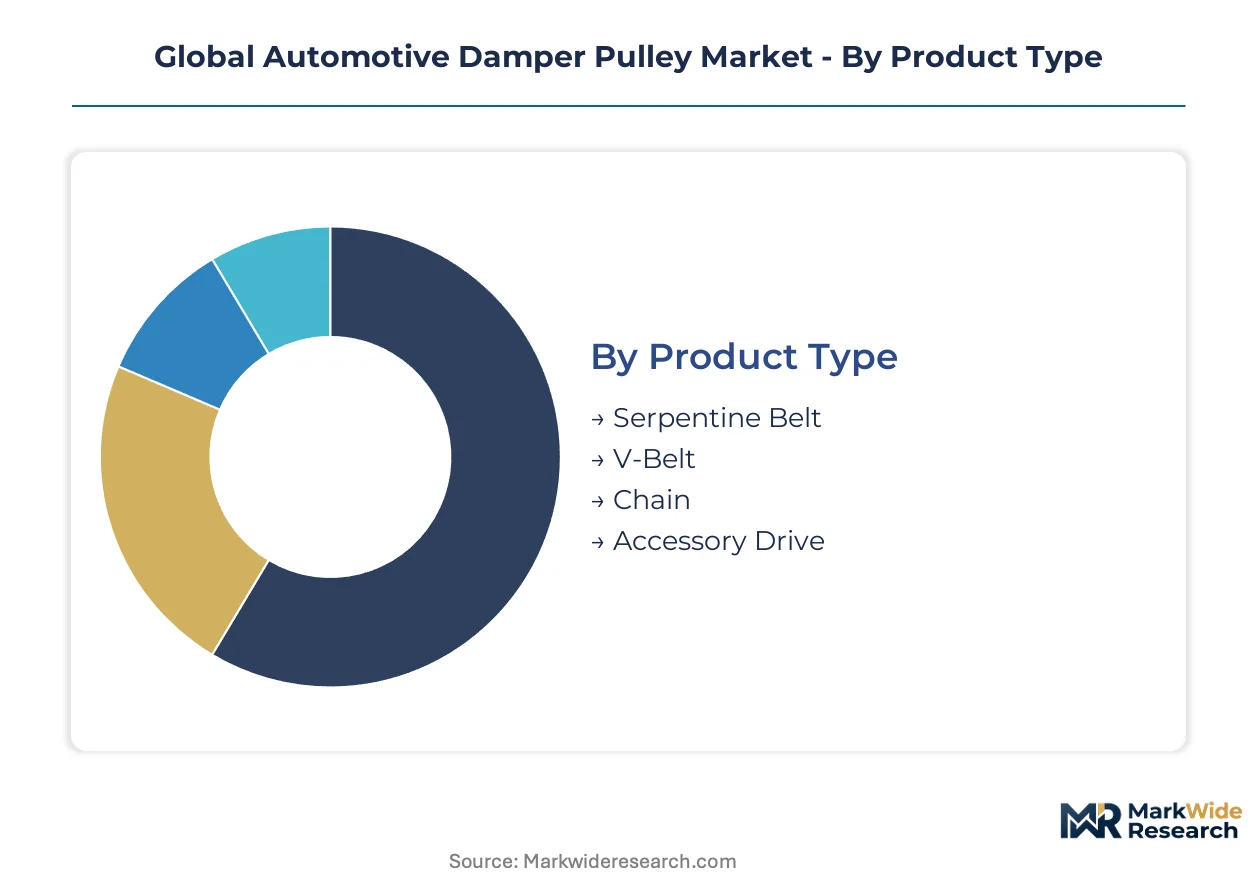
Segmentation in the damper pulley market reflects divergent engineering requirements across powertrain architectures. Material selection and damping technology choices determine compliance margins against tightening NVH regulations in China, Germany, and the United States.
Product Type:
Serpentine belt configurations dominate unit volumes while V-belt and chain alternatives serve specialized duty cycles in commercial and performance applications.
- Serpentine Belt:Consolidates multiple accessories onto a single drive path, multiplying damper pulley duty cycles per vehicle. Demand concentrates in light commercial vehicle electrification programs across Thailand and India where Japanese OEMs specify extended service intervals.
- V-Belt:Retains niche deployment in heavy-duty commercial fleets where individual accessory isolation matters. Procurement concentrates in North American aftermarket channels serving aging medium-duty truck populations.
- Chain:High-torque transfer applications in performance and commercial segments specify chain-driven layouts. German OEMs retain this architecture for specific inline-six configurations.
- Accessory Drive:Modular integration with starter-generator units in 48V mild-hybrid systems. China's MIIT GB compliance testing drives specification updates for idle-speed damping maps.
Mature deployment sits with serpentine belt architectures. Newer deployment is concentrated in accessory drive integration for electrified powertrains.
Material:
Cost tiers separate forged steel grades from aluminum castings and polymer alternatives, with thermal cycling limits dictating substitution boundaries.
- Steel:Forged grades retain margin concentration in heavy-duty commercial applications where thermal cycling demands exceed aluminum fatigue limits. Stuttgart forging clusters supply European export programs facing REACH-constrained bonding certification timelines.
- Aluminum:Die-cast and forged variants enable rotational mass reduction for passenger vehicle fuel economy targets. India's PLI scheme attracts machining investments to serve domestic NVH compliance requirements.
- Plastic:Glass-reinforced polymer pulleys serve auxiliary applications in cost-optimized vehicle platforms. Thai assembly plants specify these for ASEAN-market compact vehicles.
- Rubber:Elastomeric damping rings function as bonded composite elements rather than standalone pulley materials. Southeast Asian natural rubber volatility compresses margin predictability for vulcanized bonding processes.
Steel grades anchor heavy-duty commercial supply. Aluminum castings are expanding most quickly in passenger hybrid architectures.
End User:
Procurement authority separates captive OEM programs from fragmented aftermarket channels, with fleet operators emerging as specification influencers.
- OEMs:Powertrain divisions at Volkswagen, Toyota, and Stellantis specify damper pulleys at platform development gates. Dual-certification burdens for Euro 7 and EPA Tier 4 tolerance specifications extend validation cycles.
- Aftermarket Providers:Independent distributors serve replacement demand as vehicle aging extends service intervals. Gates Corporation sustains channel control through captive distribution to North American OEM service networks.
- Vehicle Assemblers:Contract manufacturers in Thailand and India procure pulleys as part of localized engine assembly programs. ASEAN trade flows reduce logistics friction for Japanese and Korean OEM supply chains.
- Fleet Operators:German commercial vehicle leasing programs now specify dampers through total-cost-of-ownership frameworks. Predictive maintenance clauses mandate real-time torsional telemetry, unbundling after-sales vibration monitoring from initial component supply.
OEM procurement governs new vehicle specification. Fleet operator influence is climbing the fastest in commercial vehicle service contracts.
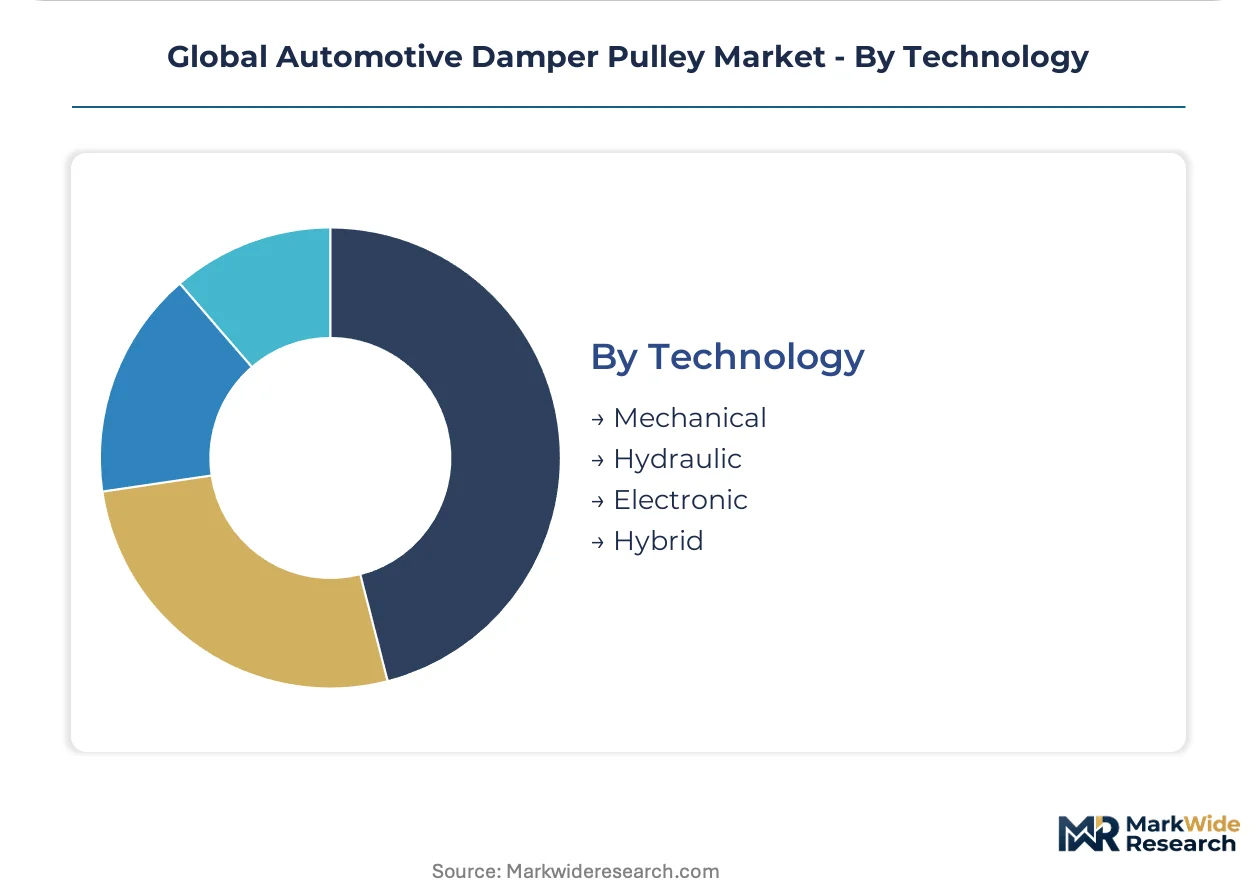
Technology:
Passive mechanical designs yield to adaptive architectures as torque-based control displaces fixed-inertia damping across electrified powertrains.
- Mechanical:Rubber-inertia assemblies bonded through vulcanization dominate current production volumes. Elastomer-to-metal bonding certification delays under REACH constrain European export platform timelines.
- Hydraulic:Fluid-filled damping chambers serve specific high-amplitude commercial applications. Deployment remains limited to heavy-duty segments in North America.
- Electronic:Torque-adaptive control modules integrate sensors with modified inertia rings. Stuttgart suppliers command this segment through existing crankshaft sensor integration capabilities, consolidating damper, sensor, and controller competencies into single-source procurement relationships.
- Hybrid:Combined mechanical-electronic architectures bridge cost and performance requirements for plug-in hybrid transient loads. China's NMPA tightening of vibration control standards accelerates adoption in domestic OEM programs.
Mechanical damping retains volume leadership. Electronic architectures are gaining share fastest in 48V mild-hybrid and full hybrid powertrains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany forges precision components for export-bound powertrain platforms while China scales domestic NVH compliance testing. Thailand anchors ASEAN supply chains through localized machining operations.
Germany
Stuttgart and Wolfsburg manufacturing corridors concentrate forging capacity for European OEM programs. The EU F-Gas Regulation tightens vibration control standards for climate-relevant refrigerant compressors. REACH-constrained curing agent approvals delay new elastomer compound qualification timelines for export platforms.
China
Domestic OEMs expand electronic damping adoption for plug-in hybrid transient loads. MIIT enforces GB standards for passenger vehicle NVH that specify maximum permissible torsional amplitude at idle and rated speed conditions. Shanghai and Tianjin certified facilities handle compliance testing for dual-certification burdens with Euro 7 protocols.
United States
North American OEM service networks sustain captive distribution channels for replacement pulleys. The EPA enforces tailpipe and evaporative emissions standards that indirectly mandate crankshaft damper precision for engine mapping stability. Detroit-area powertrain engineering centers specify damping tolerance requirements for Tier 4 harmonization efforts.
Thailand
Japanese and Korean OEM supply programs source from localized forging and machining operations serving ASEAN assembly plants. Trade flows through Thailand reduce logistics friction for regional engine assembly procurement. Bangkok-adjacent industrial zones house vulcanized bonding facilities for rubber-to-metal damper assemblies.
India
The PLI scheme for advanced automotive components attracts forging investments to serve domestic passenger vehicle production. BIS standards align with MIIT GB thresholds for torsional amplitude compliance. Tamil Nadu and Maharashtra assembly plants integrate damper pulleys into localized engine manufacturing for Japanese OEM platforms.
Global Automotive Damper Pulley Market Vendor Landscape
Top-tier vendors anchor precision forging and sensor integration capabilities, while mid-scale specialists occupy regional supply niches through bonding chemistry expertise. Japanese and German fabricators dominate torque-adaptive control architectures. Strategic moves concentrate on electronic-mechanical convergence partnerships and ASEAN capacity expansion to capture hybrid powertrain procurement.
Within the bearing-to-pulley integration tier, NTN Corporation and JTEKT Corporation exemplify Japanese multi-technology conglomerates that span precision manufacturing competencies. Gates Corporation occupies a position among North American channel controllers with captive distribution infrastructure. These three entities represent distinct archetypes: integrated motion-control specialists, rubber-bonding process experts, and aftermarket network operators.
| Leading Market Players |
|---|
| NTN Corporation |
| Zhejiang Dongxing Auto Parts |
| Dayco |
| GT Automotive |
| Sintercom India |
| JTEKT Corporation |
| Vibracoustic |
| Breda Lorett |
| Gates Corporation |
| Others |
Supply Flow & Price Mechanics
Natural rubber futures volatility cascades through vulcanized bonding operations into three-tier pricing structures across premium, standard, and economy levels, with Stuttgart forging clusters commanding premium tiers while Thai assembly plants absorb cost swings in economy-grade polymer alternatives.
Pricing Analysis
Margin tightening in electronic damping tiers reflects sensor integration premiums and REACH-constrained curing agent scarcity. Three-tier pricing structure across premium, standard, and economy levels separates torque-adaptive control modules from passive rubber-inertia assemblies and glass-reinforced polymer alternatives. Cost compression accelerates in steel-forged heavy-duty segments as India's PLI scheme attracts capacity expansion. Fleet operators exhibit lowest price sensitivity through total-cost-of-ownership frameworks, while independent aftermarket distributors face acute margin pressure from captive OEM service networks.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Wolfsburg, and Bangkok-adjacent industrial zones orchestrate hub-and-spoke patterns for European and ASEAN assembly programs. Supply concentrates in Germany, Thailand, and India for forging and machining operations. Raw material flows draw from Southeast Asian natural rubber plantations, Chinese aluminum die-casting facilities, and Japanese bearing-grade steel mills. Single-source vulnerability concentrates in Stuttgart-Wolfsburg precision forging capacity for export-bound Euro 7 platforms. Distribution runs through captive OEM service networks and Tier 1 supplier direct-ship arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into sensor manufacturing and elastomer compounding is reshaping competitive positioning as electronic-mechanical convergence demands unified torque-adaptive control capabilities.
For Market Incumbents: Lock in sensor integration competencies through backward integration into crankshaft position sensing technologies, defending against Stuttgart suppliers consolidating damper-controller single-source procurement relationships. Add bonding chemistry certification capacity in Germany to circumvent REACH-constrained curing agent delays. For New Entrants and Emerging Players: Capture India's PLI scheme incentives for advanced automotive component forging to serve domestic NVH compliance requirements, leveraging Tamil Nadu and Maharashtra assembly plant proximity. Target fleet operator service contracts with predictive maintenance telemetry bundling. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Thai forging specialists with Japanese OEM supply program relationships and existing vulcanized bonding facilities. Watch for MIIT GB standard enforcement acceleration as inflection indicator for electronic damping technology substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Damper Integration Partnership | Stuttgart suppliers merge torque sensing with inertia rings for 48V mild-hybrid architectures. |
| Thailand Forging Capacity Expansion | Bangkok-adjacent industrial zones reduce logistics friction for ASEAN Japanese OEM supply chains. |
| India PLI Scheme Utilization | Tamil Nadu and Maharashtra investments capture domestic passenger vehicle NVH compliance demand. |
| REACH-Compliant Bonding Chemistry Certification | European export platforms require accelerated curing agent qualification timelines. |
| Fleet Telemetry Service Contract Bundling | German commercial vehicle leasing programs mandate real-time torsional vibration monitoring. |
Methodological Framework
OEM platform engineering specifications, MIIT GB standard compliance filings, and ASEAN customs trade records formed the secondary backbone, supplemented by primary interviews with Tier 1 supplier procurement leads, OEM powertrain platform engineers, aftermarket distributor operations heads, and elastomer compounding technical directors. Bottom-up and top-down triangulation validated volume estimates across forging capacity utilization rates and vehicle production registration databases.
Bottom-up modeling anchored forecasts in content-per-vehicle assumptions across propulsion architectures, while top-down cross-checks applied macroeconomic filters to regional production cluster outputs. Segmentation dimensions included vehicle class, damping technology type, material grade tier, and regional regulatory compliance cluster. CAGRs derived from regression analysis of historical forging capacity expansion against electrification program announcements. Industry-specific inputs incorporated Euro 7-EPA Tier 4 harmonization tolerance specifications and China's dual carbon intensity benchmark enforcement trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to natural rubber commodity volatility, REACH curing agent approval timelines, and electronic damping technology substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Camless Engine Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Europe Turbocharger Market
Powertrain
Global Automotive Clutch Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Engine Cylinder Liners Market
Powertrain
Internal Combustion Engine Market
Powertrain
Reciprocating Engine Market
Powertrain
Clutch Friction Plate Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Car Oil Filter Market