
 Europe High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market Foresight
Germany is narrowing its HVDC manufacturing gap through domestic converter station investments. Siemens Energy AG leverages extensive offshore grid connection experience in the North Sea. Prysmian Group anchors subsea cable supply across multiple European interconnector projects. NKT A/S specializes in high-capacity extruded cables for long-distance submarine routes.
High-voltage direct current transmission systems transfer electrical power using direct current at voltages typically exceeding 100 kV, employing line commutated converters or voltage source converters to rectify alternating current at the source and invert it back at the destination. These systems enable efficient bulk power transfer across distances exceeding 600 kilometers with lower losses than comparable alternating current lines. Voltage source converter technology dominates new project awards due to superior grid stability services and black-start capability. Offshore installation types command premium pricing given specialized vessel requirements and marine environmental compliance. Grid interconnection applications absorb the largest share of capital deployment as nations seek to balance renewable generation across borders.
The EU Green Deal and REPowerEU framework shape project timelines through accelerated permitting for cross-border infrastructure. CE marking and the F-Gas Regulation constrain insulation gas choices in converter stations, pushing manufacturers toward synthetic alternatives. ECHA chemical restrictions affect cable compound formulations for submarine installations. Stakeholders must monitor how the EU AI Act influences automated grid control systems in next-generation multiterminal DC networks.
Market Dynamics
Voltage source converter technology is compressing project timelines across European offshore wind corridors, while the EU Green Deal's accelerated permitting mechanisms compress decade-long approval cycles into single-digit years for cross-border interconnectors.
Growth Catalysts
- REPowerEU framework:The plan mandates streamlined permitting for energy infrastructure, cutting interconnector approval timelines by half in member states bordering the North Sea.
- Offshore wind capacity targets:Germany, Denmark and the United Kingdom collectively drive demand for subsea cable systems as developers race to connect gigawatt-scale arrays.
- Voltage source converter dominance:Superior grid stability services and black-start capability make this technology the default choice for new multiterminal DC networks.
Market Restraints
- Specialized vessel scarcity:Cable-laying ships command day rates exceeding EUR 200,000, concentrating installation capacity among Nordic and Dutch operators.
- F-Gas Regulation constraints:CE marking requirements limit insulation gas choices in converter stations, forcing costly synthetic alternative adoption.
- ECHA chemical restrictions:Cable compound formulations for submarine installations face reformulation mandates, extending qualification timelines.
Strategic Opportunities
- Baltic Sea expansion:Poland and the Baltic states present underpenetrated offshore wind zones with minimal existing HVDC infrastructure.
- EU AI Act integration:Automated grid control systems in next-generation networks create compliance-driven upgrade cycles for existing converter stations.
- Hybrid interconnector-windfarm models:Combined financing structures reduce offtake risk by bundling generation and transmission assets under single procurement.
Industry Challenges
- Marine survey and route clearance:Unexploded ordnance and archaeological deposits on North Sea seabeds delay cable laying schedules unpredictably.
- Multiterminal control complexity:Protection coordination across three or more converter stations requires proprietary communication protocols that resist standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe High-Voltage Direct Current (HVDC) Transmission Systems Market |
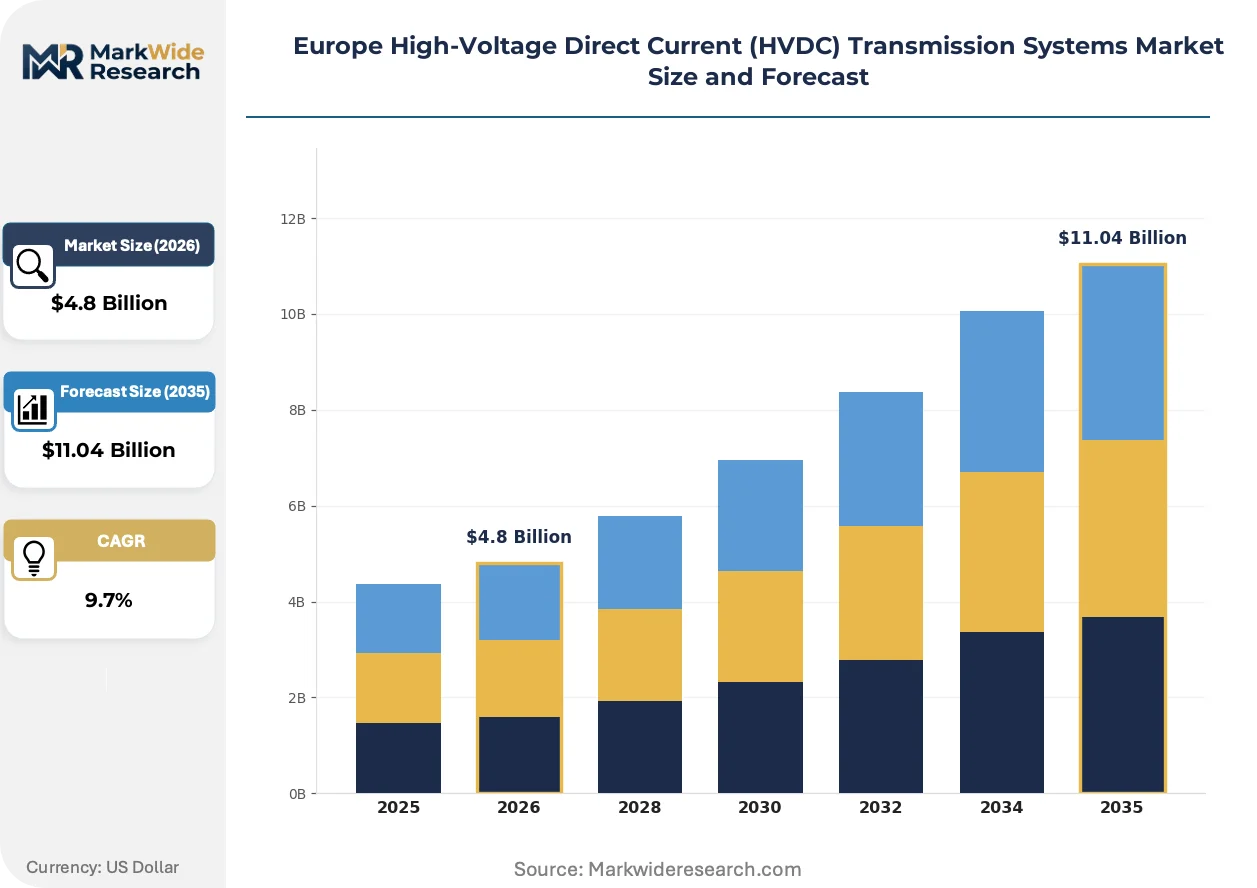
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voltage Source Converter, Line Commutated Converter, Hybrid Converter, Multiterminal DC End User: Utilities, Industrial, Renewable Energy, Aerospace Installation Type: Onshore, Offshore, Underground, Overhead Application: Grid Interconnection, Power Supply, Energy Storage, Renewable Integration |
| Companies Covered | Siemens Energy AG, Hitachi Energy Ltd, General Electric Company, Toshiba Corporation, Mitsubishi Electric Corporation, Eaton Corporation PLC, Prysmian Group, NKT A/S, Nexans S.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market Shifts & Advancements
Modular converter station designs are collapsing construction schedules from years to months, while synthetic insulation gases and AI-enabled predictive maintenance rewrite equipment specifications across the supply chain.
Modular containerized converter platforms are rendering obsolete traditional brick-and-mortar station builds. Offshore wind developers in the North Sea specify these prefabricated units for serial deployment across multiple arrays. The shift compresses on-site civil works from eighteen months to under ninety days, eliminating weather-window risks that plague conventional construction.
CE marking combined with the F-Gas Regulation is forcing insulation gas transitions across converter station portfolios. Manufacturers must reformulate switchgear designs around synthetic alternatives with lower global warming potential. German and Danish projects face the tightest compliance deadlines, driving joint development agreements between station builders and chemical suppliers.
Long-term availability contracts now dominate cable procurement for subsea interconnectors. TSOs in Germany and the United Kingdom are abandoning spot-market purchases in favor of ten-year supply agreements with extruded cable specialists. The model transfers inventory risk to manufacturers while locking in capacity for planned offshore wind connections through 2035.
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
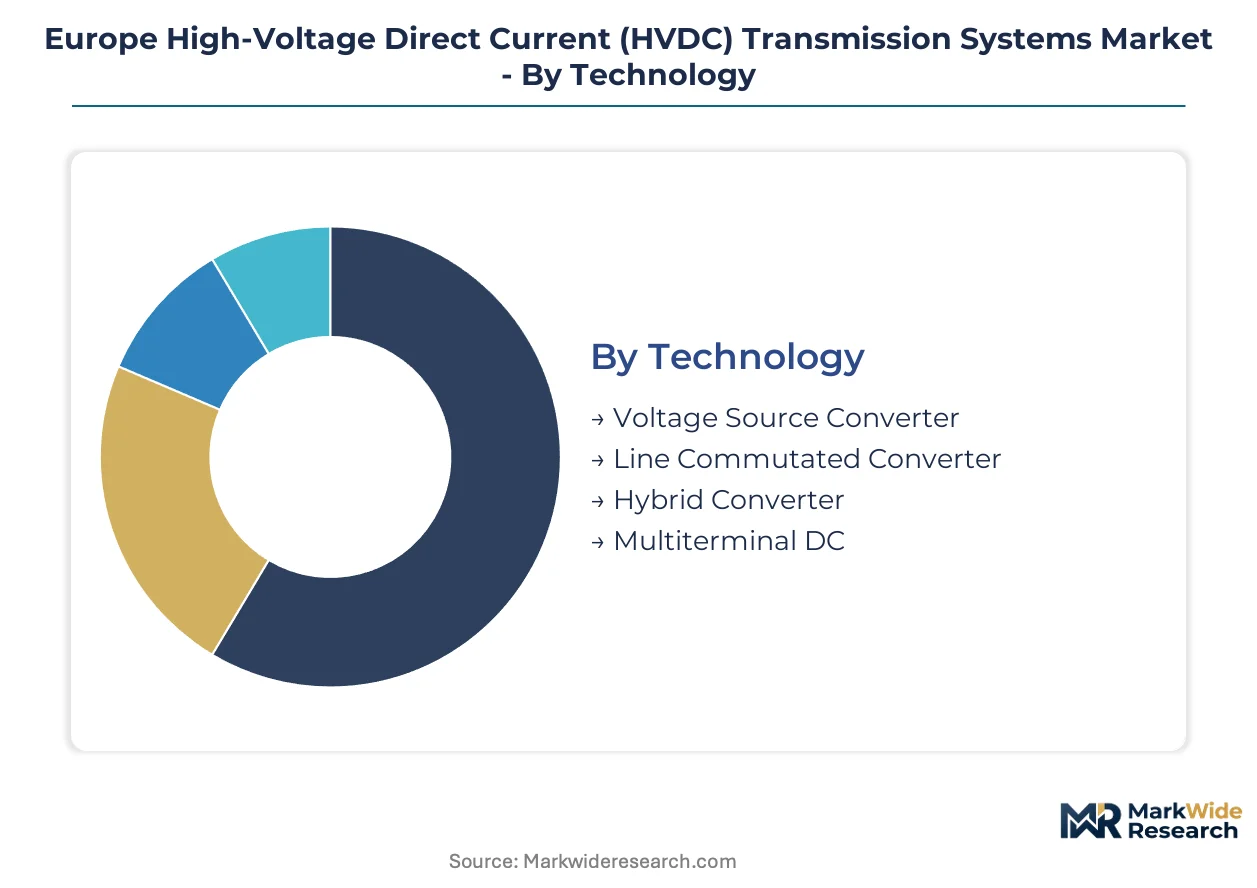
HVDC system architecture varies sharply across deployment contexts. Converter technology choices, installation environments, and end-user requirements create distinct procurement patterns that suppliers must address separately.
Technology:
Converter topology determines grid services capability, project economics, and vendor qualification requirements.
- Voltage Source Converter:Employs insulated-gate bipolar transistors to enable independent active and reactive power control. German and Danish offshore wind developers specify this technology exclusively for new North Sea arrays due to black-start capability and weak-grid support.
- Line Commutated Converter:Relies on thyristor-based rectification with higher power throughput per semiconductor but requires strong synchronous voltage sources. Legacy interconnectors in the Baltic corridor continue operating this established hardware base.
- Hybrid Converter:Combines voltage source and line commutated elements to optimize cost-performance across specific transmission distances.
- Multiterminal DC:Enables three or more converter stations to share a single DC bus, supporting meshed offshore grid architectures.
Line Commutated Converter commands the established base. The steepest expansion runs through Voltage Source Converter.
End User:
Procurement scale and technical sophistication diverge markedly across customer categories.
- Utilities:Transmission system operators in Germany, Denmark, and the United Kingdom drive capital deployment through decade-long infrastructure programs. Their procurement specifications set industry standards for converter efficiency and cable reliability.
- Renewable Energy:Offshore wind developers bundle HVDC connections with generation assets under single project finance structures. North Sea lease round winners in the United Kingdom and Germany now require converter stations as standard array components.
- Industrial:Aluminum smelters and data centers in Norway and Iceland source dedicated HVDC links for remote clean power access.
- Aerospace:Research facilities and ground-based test systems represent a niche specification segment.
Utilities absorb the majority of current capital. Renewable Energy is gaining share fastest as offshore wind targets harden.
Installation Type:
Physical deployment environment dictates vessel requirements, environmental compliance, and construction risk allocation.
- Offshore:Submarine cable systems connecting North Sea wind farms command premium pricing due to specialized cable-laying vessel scarcity and marine survey complexity. German and United Kingdom projects dominate current procurement.
- Underground:Land-based corridors through densely populated regions avoid overhead line opposition. German transmission system operators favor this approach for onshore converter station connections.
- Onshore:Converter stations and terrestrial cable terminations require civil works and grid synchronization infrastructure.
- Overhead:Traditional pylons persist for long-distance terrestrial bulk transfer where social license permits.
Overhead retains cost advantage where permitted. Offshore claims the steepest growth trajectory as marine renewable capacity expands.
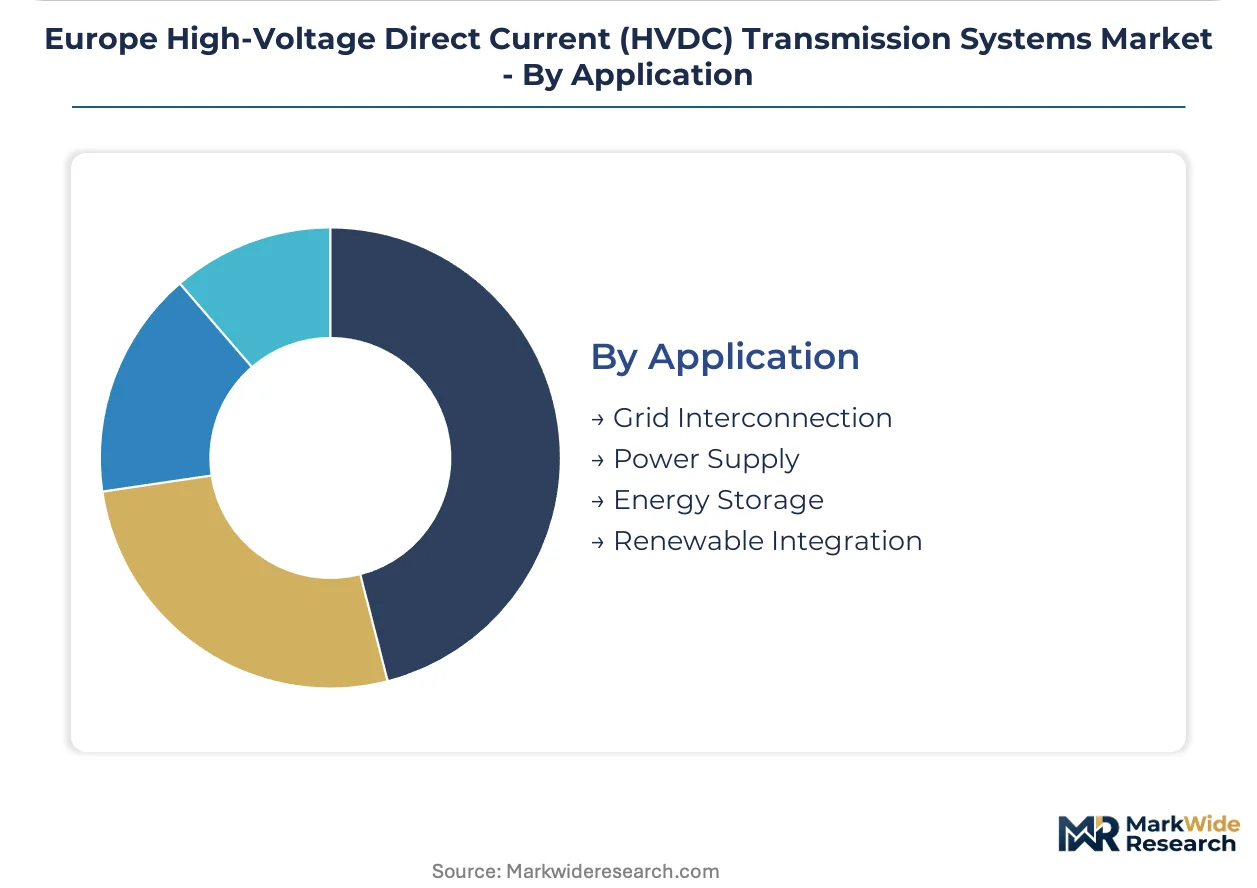
Application:
Functional purpose shapes converter rating, cable specification, and control system architecture.
- Grid Interconnection:Cross-border links between EU member states enable renewable energy trading and system balancing. REPowerEU accelerated permitting targets these projects specifically.
- Renewable Integration:Dedicated collector systems aggregate offshore wind generation for injection into national grids. United Kingdom Round 4 and 5 lease areas drive current demand concentration.
- Power Supply:Remote industrial loads and island networks receive dedicated transmission feeds.
- Energy Storage:Battery and pumped hydro facilities use HVDC for rapid power injection and withdrawal.
Grid Interconnection holds the mature project pipeline. Renewable Integration is climbing the fastest as offshore wind targets escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter station fabrication clusters in Germany and Italy anchor European supply capacity. Cable manufacturing concentrates around Nordic extrusion facilities. Each national market exhibits distinct procurement rhythms tied to offshore wind lease rounds and interconnector permitting.
Germany
North Sea offshore wind auctions and Baltic Sea grid expansion drive converter station demand. The Bundesnetzagentur implements REPowerEU accelerated permitting for cross-border links. Siemens Energy AG anchors manufacturing in Erlangen while Prysmian Group supplies subsea cables from Nordenham.
United Kingdom
Round 4 and 5 offshore wind lease areas require multi-gigawatt HVDC collector systems. Ofgem's cap and floor regime stabilizes interconnector revenue streams. NKT A/S maintains cable extrusion capacity in Kent to serve North Sea arrays.
Denmark
Energy island projects and Kriegers Flak interconnections consume voltage source converter stations. The Danish Energy Agency coordinates permitting with German and Dutch regulators. Vestas and Ørsted procurement specifications influence converter technology standards across the Kattegat.
France
Grid interconnection with Spain and Italy drives land-based converter deployment. CRE oversees tariff structures for cross-border capacity allocation. Nexans S.A. operates high-voltage cable manufacturing in Lyon for Alpine and subsea routes.
Netherlands
Hollandse Kust offshore zones and IJmuiden Ver demand specialized installation vessels. The Netherlands Enterprise Agency bundles transmission concessions with generation leases. Hitachi Energy Ltd supplies converter platforms for Dutch-German corridor projects.
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cable and semiconductor supply. The European market structures around three to five integrated system providers with captive converter technology and a fragmented tier of cable extruders and installation contractors. Two strategic archetypes dominate: full-system integrators bundling converter stations with project execution, and component pure-plays focusing on extruded insulation or subsea installation. Competitive moves concentrate on long-term supply agreements with transmission system operators and joint development of synthetic insulation gases.
Among Germany-based industrial conglomerates, Siemens Energy AG exemplifies the integrated system archetype spanning converter design through offshore installation. Prysmian Group and NKT A/S represent the cable specialization tier, with Italian and Danish origins respectively. These three anchors illustrate how European supply chains segment between platform ownership and component manufacturing depth.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Hitachi Energy Ltd |
| General Electric Company |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Eaton Corporation PLC |
| Prysmian Group |
| NKT A/S |
| Nexans S.A. |
| Others |
Supply & Pricing Matrix
Erlangen anchors European converter station fabrication, where Siemens Energy AG's captive capacity insulates pricing power from raw semiconductor volatility. Cable extrusion clusters around Nordenham and Cologne transfer inventory risk to manufacturers through decade-long availability contracts, compressing spot-market leverage for project developers.
Pricing Analysis
CE marking combined with the F-Gas Regulation dictates the pricing tier structure across converter station procurement. Three-tier pricing structure across premium, standard, and economy levels separates black-start capable voltage source converter platforms from legacy line commutated hardware and refurbished substation equipment. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in standard-tier hardware is intensifying because synthetic insulation gas reformulation extends qualification timelines. Offshore wind developers show least price sensitivity given bundled project finance structures, while industrial offtakers in Norway and Iceland exhibit highest elasticity to capital cost fluctuations.
Supply Chain Analysis
Copper cathode and polypropylene feedstock draw from Chilean mining operations and Belgian petrochemical complexes respectively. Converter semiconductor fabrication concentrates in Germany, Japan, and the United States. Submarine cable armoring depends on Swedish steel rolling capacity. Single-source vulnerability sits with specialized cable-laying vessel operators concentrated among Nordic and Dutch fleets. Distribution runs through transmission system operator procurement departments with multi-year framework agreements dominating capital deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
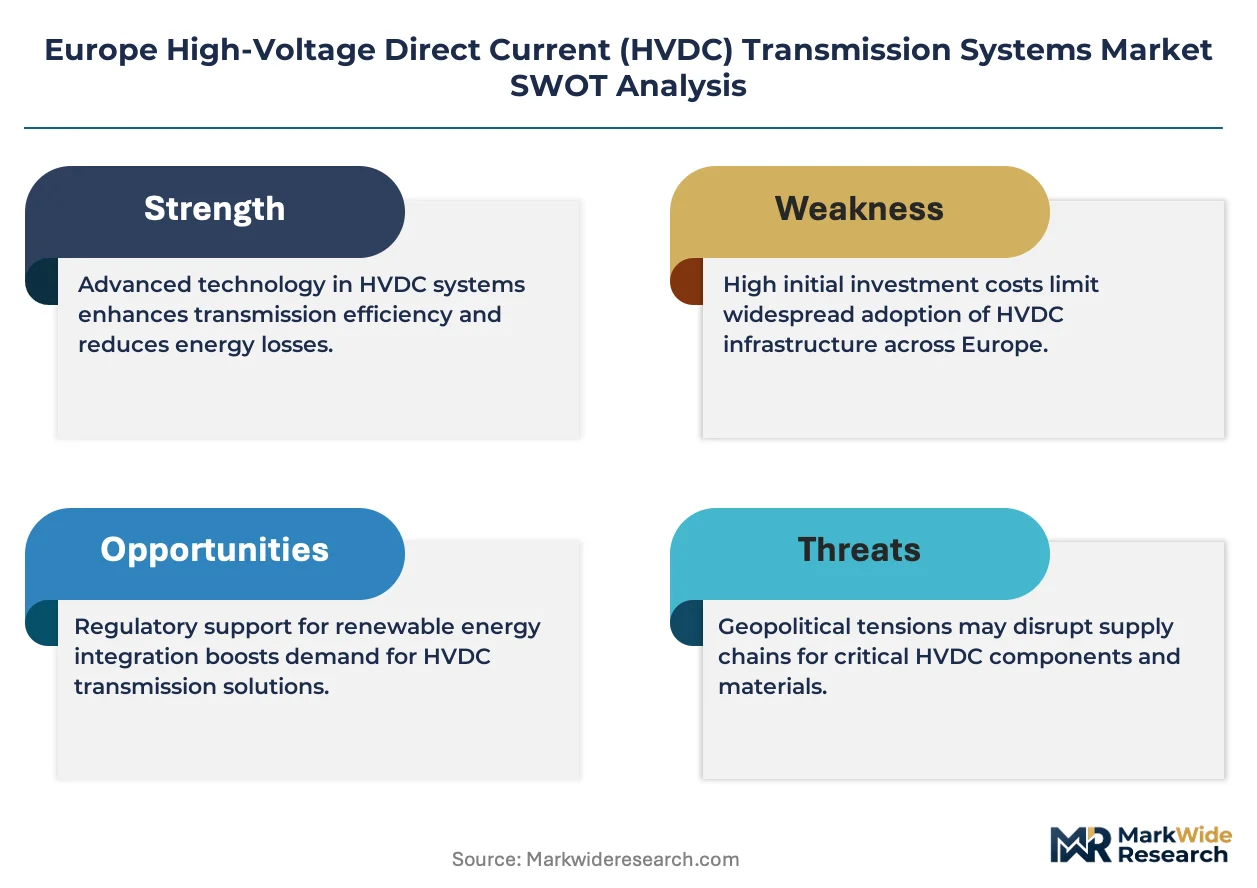
This market demands substitution defense against high-voltage alternating current corridor upgrades and battery storage peaker alternatives. Incumbents must fortify position before grid-scale lithium-ion and green hydrogen storage erodes baseload transmission economics.
For Market Incumbents: Pre-empt synthetic insulation gas supply constraints through joint development agreements with chemical suppliers ahead of F-Gas Regulation deadlines. Capture converter platform standardization benefits by anchoring modular containerized designs across German and United Kingdom offshore arrays. Vertical integration into cable installation vessel partnerships mitigates day-rate volatility that threatens project margins. For New Entrants and Emerging Players: Pursue Baltic Sea offshore wind zones in Poland and Estonia where minimal existing HVDC infrastructure creates first-mover positioning. Target hybrid interconnector-windfarm bundled procurement models that reduce offtake risk through combined generation and transmission asset financing. Lead with voltage source converter black-start capability as the technical wedge against legacy line commutated incumbents in weak-grid applications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cable extrusion specialists with decade-long availability contracts locking in capacity through 2035. Long-term viability favors component pure-plays with captive polymer compounding and marine installation partnerships over asset-light system integrators. Watch for EU AI Act compliance-driven upgrade cycles in existing converter stations as the inflection signal for next-generation control system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Insulation Gas Joint Development | F-Gas Regulation compliance deadlines in Germany and Denmark accelerate chemical supplier partnerships. |
| Modular Converter Platform Standardization | Containerized designs collapse German offshore wind construction schedules from eighteen months to ninety days. |
| Long-term Cable Availability Contracts | Ten-year supply agreements transfer inventory risk from United Kingdom TSOs to Nordic extrusion specialists. |
| Specialized Vessel Capacity Partnerships | Cable-laying ship scarcity exceeding EUR 200,000 day rates demands captive installation access. |
| EU AI Act Control System Compliance | Automated grid coordination mandates create upgrade cycles for multiterminal DC network operators. |
Research Methodology
The analysis maps voltage source converter platforms, line commutated legacy systems, submarine cable extrusion, and installation vessel operations, each validated through transmission system operator planning officers, offshore wind project developers, EPC contractors, and converter station engineering directors. Primary interview intelligence triangulates against Bundesnetzagentur permitting databases, ENTSO-E interconnector project registries, EU Green Deal implementation tracking, and REPowerEU framework documentation. Bottom-up project pipeline aggregation cross-checks with top-down European transmission investment forecasts.
Assumptions held fixed include REPowerEU accelerated permitting timelines and North Sea offshore wind capacity targets; variables tested include synthetic insulation gas cost trajectories and cable-laying vessel day-rate volatility. The analytical framework segments by converter technology, installation environment, end-user category, and application purpose across the projection horizon. CAGRs derive from project-level capital deployment schedules and equipment procurement lead times. Forecast inputs incorporate voltage source converter market share assumptions and subsea cable kilometer deployment intensity per gigawatt of offshore wind capacity.
Macroeconomic conditions sit as an overlay; deviation in eurozone infrastructure investment cycles or North Sea marine consenting delays would shift the trajectory. Forecasts reflect these assumptions without claiming predictive certainty. Cross-checking against ENTSO-E Ten-Year Network Development Plan updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Mobile Substation Market