

Cordless Blind Rivet Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Blind Rivet Gun Market Insights
Buyer concentration across European automotive Tier-1 suppliers is rebalancing as smaller workshop technicians and independent aftermarket providers expand procurement volumes. GESIPA Blindniettechnik leverages its heritage in blind rivet systems to sustain engineering credibility among aircraft fabricators. Robert Bosch competes through battery platform interoperability across its cordless ecosystem. Würth Group anchors distribution density with captive channel control through its direct sales infrastructure.
A cordless blind rivet gun is a portable fastening tool that uses rechargeable battery energy to draw and deform blind rivets without rear access, typically operating at pull forces between 8,000 and 16,000 Newtons depending on material gauge. The tool serves manufacturing environments where pneumatic hose routing limits operator mobility or poses trip hazards. Battery-Powered product types dominate unit shipments due to lithium-ion gravimetric energy density gains that extend cycle counts between charges. Brushless Motor technology leads in premium tier positioning where thermal efficiency and maintenance intervals determine total cost of ownership calculations. Manufacturing Assembly applications absorb the largest volume share as OEMs and Tier-1 Suppliers standardize cordless platforms across mixed-material joining operations.
FAA airworthiness directives and OSHA workplace ergonomics standards shape product certification requirements and operator safety protocols in the United States. EMA machinery safety frameworks and REACH substance restrictions influence design specifications for European-market tools. Stakeholders must monitor evolving battery transport regulations and carbon-border adjustment mechanisms that will determine which cordless platforms qualify for public infrastructure procurement across major manufacturing economies.
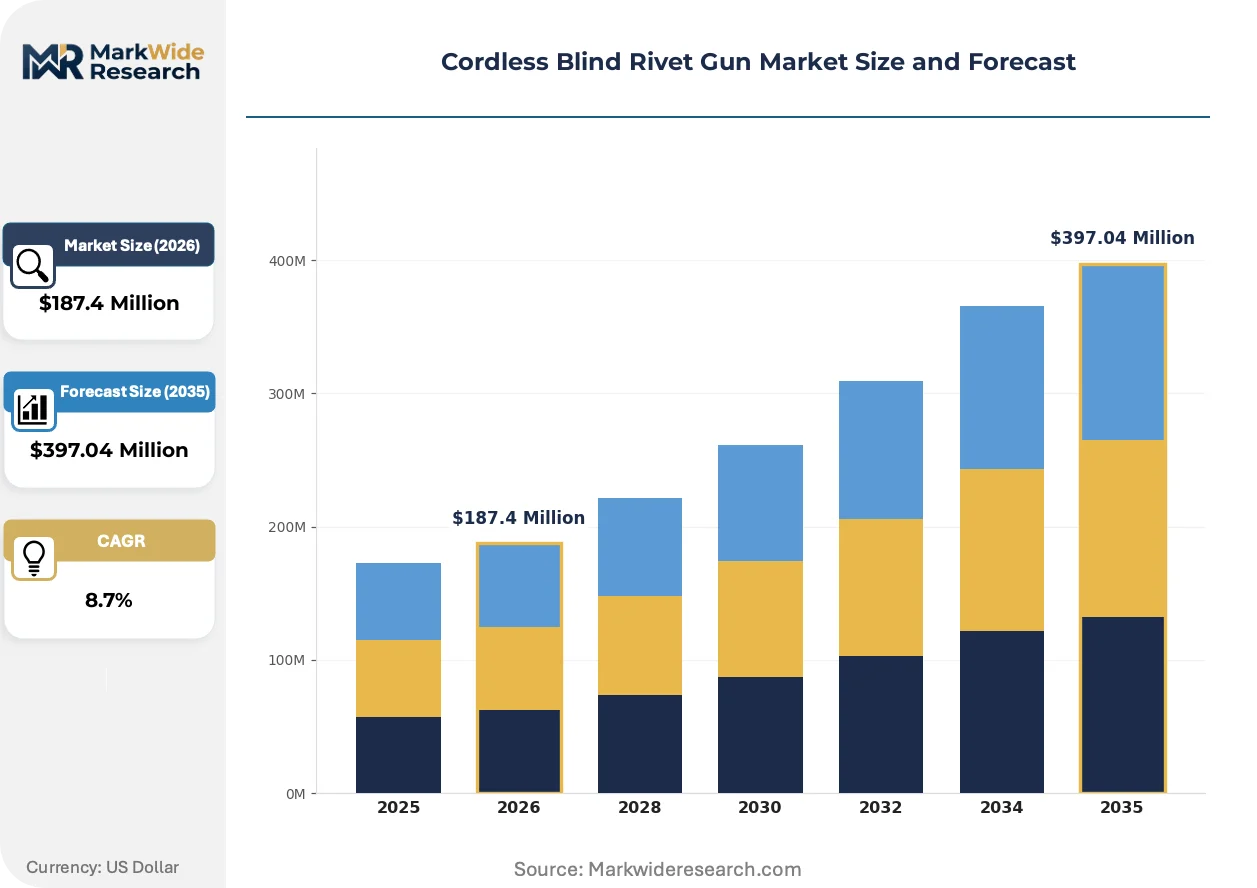
Market Dynamics
Lithium-ion gravimetric energy density gains above 250 Wh/kg are compressing cycle times between charges, allowing single-battery platforms to displace pneumatic tethers across mixed-material assembly floors in Germany, China, and the United States.
Growth Catalysts
- OSHA Ergonomics Directives:US workplace safety mandates on repetitive strain injuries are accelerating cordless platform standardization among Tier-1 automotive suppliers seeking to eliminate hose-related trip hazards and operator fatigue.
- Aerospace Assembly Mobility:Boeing and Airbus tier suppliers are absorbing battery-powered riveting units to enable point-of-use fastening without compressed air infrastructure across fuselage panel lines.
- Brushless Motor Thermal Efficiency:Permanent magnet synchronous designs are extending maintenance intervals beyond 10,000 cycles, lowering total cost of ownership calculations for high-volume manufacturers.
Market Restraints
- Lithium Carbonate Price Volatility:Battery cell input costs fluctuate with Chilean and Australian mining output, compressing margin structures for mid-tier tool assemblers without captive cell supply.
- REACH Substance Restrictions:ECHA limitations on cobalt and nickel compounds in battery cathodes are forcing redesign cycles that delay European market entry for non-compliant platforms.
- Pneumatic Tool Installed Base:Decades of compressed air infrastructure investment in legacy manufacturing plants creates switching friction that slows cordless adoption in cost-sensitive maintenance operations.
Strategic Opportunities
- India Automotive Cluster Expansion:Maruti Suzuki and Hyundai supplier parks near Chennai and Pune present underpenetrated demand for portable fastening tools as domestic vehicle production scales.
- EU Battery Passport Mandates:CSRD-aligned traceability requirements are creating first-mover advantage for manufacturers with blockchain-verified supply chain documentation.
- Carbon Border Adjustment Mechanisms:CBAM phase-in is incentivizing Chinese exporters to localize final assembly in Poland and Hungary to maintain European public procurement eligibility.
Industry Challenges
- FAA Airworthiness Certification Timelines:Tool qualification for aircraft structural applications requires 18-24 month validation cycles that strain R&D capitalization for mid-size manufacturers.
- Battery Transport Regulation Fragmentation:Divergent UN 38.3, IATA, and ADR testing protocols complicate cross-border logistics and inventory positioning for multinational distributors.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Blind Rivet Gun Market Trends and Innovations
Tool intelligence is migrating from the factory floor to the cloud, with connectivity modules now standard on premium platforms. Three developments are compressing competitive differentiation windows.
Brushless motor control algorithms paired with torque-angle sensors are rewriting performance benchmarks for aluminum and titanium rivet deformation. Aerospace fabricators in Toulouse and Hamburg are specifying these platforms for wing stringer assembly. The technology is compressing the premium tier from five-year to three-year replacement cycles as thermal management thresholds advance.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing seal and gasket redesigns for battery compartment ingress protection. German tool manufacturers face 12-month requalification timelines for IP-rated enclosures. The regulatory pressure is concentrating supply relationships with fluoropolymer-free compound specialists in the Rhineland.
Smaller workshop technicians and independent aftermarket providers are consolidating purchase volumes through digital procurement platforms. Würth Group's direct sales infrastructure is losing share to specialized industrial distributors offering configuration tools and same-day fulfillment. The behavioral shift is most visible in Bavaria and Baden-Württemberg where Mittelstand metal fabricators prioritize technical support over brand heritage.
Cordless Blind Rivet Gun Market Segmentation
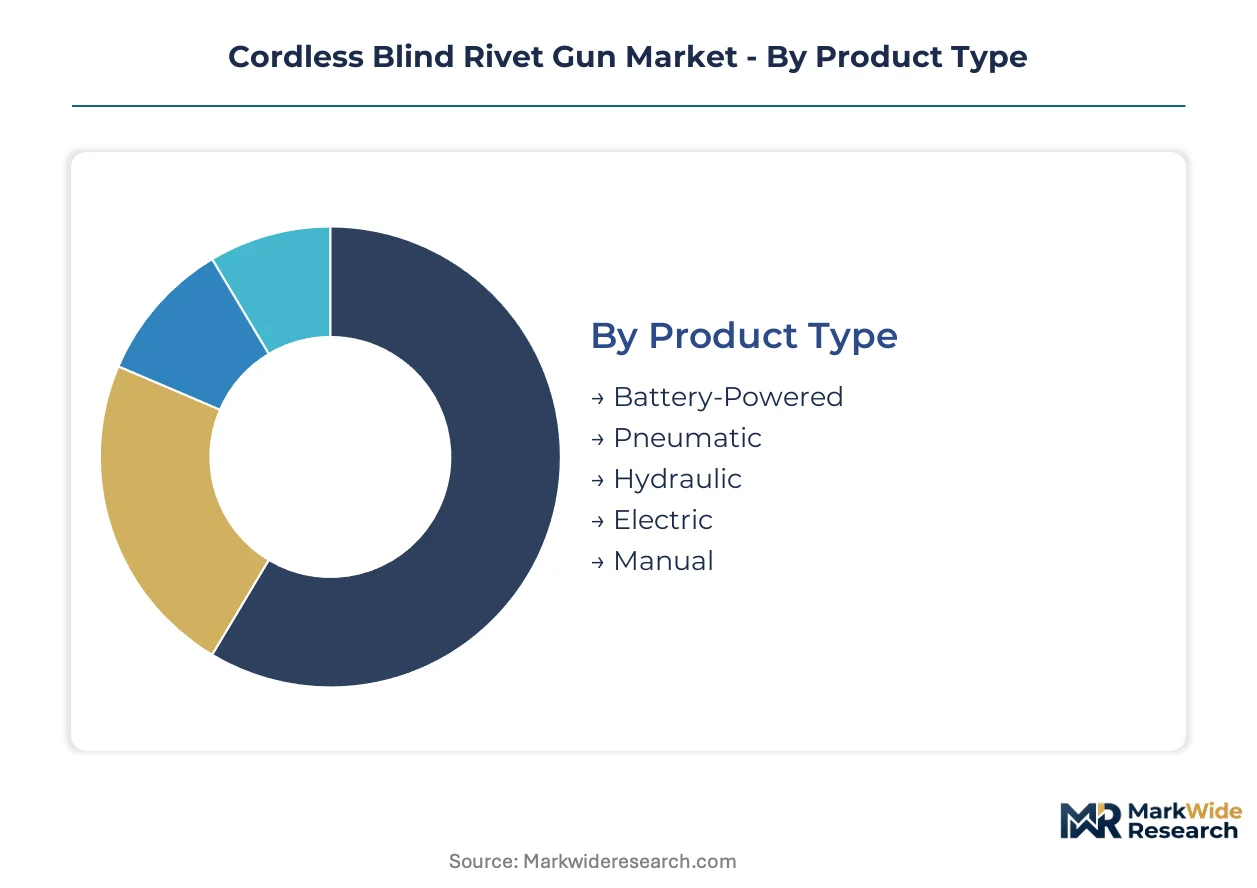
Segmentation in the cordless blind rivet gun market reveals how battery chemistry, motor architecture, and end-user procurement authority reshape competitive positioning. Procurement patterns diverge sharply between high-volume automotive Tier-1 suppliers and fragmented workshop technicians, forcing manufacturers to maintain parallel platform strategies.
Product Type:
Battery-Powered platforms command premium positioning through lithium-ion energy density above 250 Wh/kg, while pneumatic alternatives retain residual share in legacy compressed air infrastructure.
- Battery-Powered:Lithium-ion cells deliver 8,000-16,000 Newton pull forces across 200+ cycles per charge. Demand concentrates among Boeing and Airbus tier suppliers in Hamburg and Toulouse eliminating pneumatic tethering from fuselage panel lines.
- Pneumatic:Compressed air systems require fixed infrastructure but offer lower capital outlay for high-volume operations. Mature deployment sits with German automotive stamping plants in Wolfsburg and Stuttgart maintaining decades-old air compressor networks.
- Hydraulic:Fluid-powered mechanisms generate superior force for structural steel applications in shipyards.
- Electric:Corded electric variants serve workshop environments with reliable grid access and lower duty cycles.
- Manual:Hand-operated tools dominate aftermarket repair scenarios and low-volume furniture fabrication in emerging manufacturing clusters.
Mature deployment sits with Pneumatic systems in legacy automotive plants. Newer deployment is concentrated in Battery-Powered platforms across aerospace mobility initiatives.
Technology:
Motor efficiency and battery chemistry determine thermal management thresholds and maintenance intervals, directly influencing total cost of ownership calculations for procurement committees.
- Brushless Motor:Permanent magnet synchronous designs extend service intervals beyond 10,000 cycles through reduced friction and heat generation. Aerospace fabricators in Seattle and Toulouse specify these platforms for aluminum and titanium wing stringer deformation.
- Lithium-Ion Battery:Gravimetric energy density gains compress charging downtime and enable single-battery shift coverage. Tier-1 automotive suppliers in Detroit and Munich are standardizing these platforms across mixed-material joining floors.
- NiMH Battery:Nickel-metal hydride cells offer thermal stability in extreme temperature environments but carry weight penalties limiting operator mobility.
- Cordless Mechanism:Integrated battery-motor architectures eliminate power cable routing hazards in congested assembly environments.
- Torque Control:Sensor-feedback systems prevent over-torque damage in electronics enclosure applications requiring precision fastening.
Procurement authority for Brushless Motor platforms rests with aerospace OEMs specifying thermal efficiency. Workshop technicians drive volume in Cordless Mechanism mid-tier alternatives.
Application:
Force requirements and material specifications vary dramatically between aluminum aircraft skin joining and furniture-grade steel riveting, fragmenting platform standardization.
- Manufacturing Assembly:Mixed-material automotive body-in-white operations require rapid tool reconfiguration between aluminum, steel, and composite substrates. OEMs in Munich and Detroit absorb the largest volume share as cordless platforms displace pneumatic tethers.
- Aircraft Fabrication:FAA airworthiness certification mandates 18-24 month validation cycles for structural fastening tools. Boeing and Airbus tier suppliers in Everett and Hamburg specify brushless platforms for fuselage panel and wing assembly mobility.
- Shipbuilding:Heavy-gauge steel riveting in Korean and Chinese yards demands hydraulic force supplementation beyond battery-only platforms.
- Electronics Enclosure:Precision torque control prevents damage to sensitive semiconductor housing materials in Shenzhen and Penang contract manufacturing.
- Furniture Production:Lower-duty cycles and standardized material gauges suit economy-tier battery platforms in Polish and Vietnamese export manufacturing.
Volume concentration tracks Manufacturing Assembly standardization. Steepest expansion trajectory appears in Aircraft Fabrication as mobility requirements override pneumatic infrastructure investment.
End User:
Procurement scale and technical specification authority determine whether manufacturers compete on total cost of ownership or upfront capital efficiency.
- OEMs:Original equipment manufacturers in automotive and aerospace verticals standardize cordless platforms across global supplier networks, demanding battery platform interoperability and cloud connectivity modules.
- Tier-1 Suppliers:Contract manufacturers serving multiple OEMs require flexible tooling configurations accommodating mixed production schedules without dedicated pneumatic infrastructure per line.
- Aftermarket Providers:Independent repair and maintenance operations prioritize capital efficiency over performance specifications, absorbing economy-tier manual and entry battery platforms.
- Workshop Technicians:Small metal fabricators in Bavaria and Baden-Württemberg consolidate purchase volumes through digital procurement platforms emphasizing technical support over brand heritage.
Specification authority concentrates with OEMs and Tier-1 Suppliers. Workshop Technicians represent the fastest-growing procurement channel as digital platforms erode traditional distributor control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium carbonate extraction in Chile's Atacama salt flats and Australia's Greenbushes pegmatite deposits anchors battery cell supply chains that feed cordless tool assembly across three manufacturing continents.
United States
OSHA ergonomics directives on repetitive strain injuries accelerate cordless platform standardization at Detroit automotive stamping plants. FAA airworthiness certification requirements govern tool qualification timelines for Boeing tier suppliers in Everett. Brushless motor platforms specified for aluminum wing stringer assembly concentrate in Pacific Northwest aerospace clusters.
Germany
EMA machinery safety frameworks and REACH substance restrictions reshape battery cathode designs for European market entry. ECHA limitations on cobalt compounds force 12-month requalification cycles for IP-rated enclosures. Manufacturing assembly standardization across Munich and Wolfsburg automotive body-in-white operations absorbs premium-tier battery platforms.
China
MIIT battery industry standards and dual carbon goals accelerate lithium-ion energy density improvements above 250 Wh/kg. SAMR product safety certifications govern domestic market access for cordless fastening tools. Shenzhen electronics enclosure fabricators specify precision torque control platforms for semiconductor housing assembly.
Japan
METI industrial efficiency programs promote brushless motor adoption in high-cycle manufacturing environments. JIS standards for portable power tools establish performance benchmarks for domestic and export markets. Nagoya automotive supplier parks standardize cordless platforms across mixed-material joining operations.
India
BIS certification requirements for battery-powered industrial tools create compliance barriers for non-domestic manufacturers. PLI scheme incentives for advanced cell chemistry attract localized assembly investment near Chennai. Maruti Suzuki supplier parks in Pune and Gurugram present underpenetrated demand for portable fastening platforms.
Cordless Blind Rivet Gun Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent cordless fastening categories and regional aftermarket channels. The vendor base stratifies across premium brushless motor specialists, battery platform integrators, and direct-sales distributors with captive channel control. Three archetypes dominate: heritage aircraft fabricators leveraging blind rivet engineering credibility, diversified power tool conglomerates exploiting battery ecosystem interoperability, and industrial supply houses anchoring distribution density. Competitive moves concentrate on geographic expansion into Indian automotive clusters and portfolio diversification toward smart connectivity modules.
Within the heritage engineering tier, GESIPA Blindniettechnik occupies a position exemplifying aircraft fabrication credibility. Among diversified power tool conglomerates, Robert Bosch and Makita represent battery platform interoperability strategies. Würth Group anchors the direct-sales archetype with distribution infrastructure control. These three companies collectively illustrate how competitive positioning fragments across engineering heritage, ecosystem breadth, and channel captivity rather than concentrating on manufacturing scale alone.
| Leading Market Players |
|---|
| GESIPA Blindniettechnik |
| Robert Bosch |
| Würth Group |
| Makita |
| Stanley Black & Decker |
| Milwaukee Electric Tool |
| Hilti |
| Metabowerke |
| JRP Tooling |
| Others |
Pricing and Supply Chain Analysis
Brushless motor thermal efficiency certification separates premium-tier platforms from commodity alternatives, embedding that performance gap into both three-tier pricing structure across premium, standard, and economy levels and into supply chain configurations that source permanent magnet materials from distinct geographic tiers. FAA-validated tools for Boeing and Airbus tier suppliers command bundled service contracts and extended warranty coverage, while workshop-grade platforms compete on unbundled capital outlay with aftermarket support sold separately.
Pricing Analysis
Warranty bundling and field service coverage differentiate premium-tier brushless platforms from economy alternatives where unbundled capital outlay dominates procurement calculations. Pricing stratifies across premium, standard, and economy tiers based on thermal efficiency certification and battery platform interoperability with existing cordless ecosystems. Pricing pressure stems from lithium carbonate volatility compressing margin structures for mid-tier assemblers without captive cell supply. Tier-1 automotive suppliers in Detroit and Munich exhibit lowest price sensitivity given total cost of ownership calculations, while independent aftermarket providers prioritize upfront capital efficiency.
Supply Chain Analysis
Freight cost escalation on lithium-ion cells from South Korea and Japan to European assembly plants is accelerating localization investments near end-user clusters. Battery cell production concentrates in China, South Korea, and Japan, while permanent magnet materials for brushless motors draw from Chinese rare earth processing and Australian mining operations. Single-source vulnerability in cobalt cathode compounds from the DRC and Chilean lithium brine extraction creates input cost volatility. Distribution runs through Würth Group's direct sales infrastructure in Germany and specialized industrial distributors eroding that channel control in Bavaria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lithium carbonate refining capacity constraints in Chile and Australia prop pricing power for manufacturers with captive battery supply agreements, making supply security the decisive competitive variable.
For Market Incumbents: Hedge against cobalt and nickel compound restrictions by accelerating fluoropolymer-free seal requalification with Rhineland compound specialists. Prioritize backward integration into lithium-ion cell assembly near Chennai and Pune to capture PLI scheme incentives and defend margin position from mid-tier competitors exposed to spot market volatility. For New Entrants and Emerging Players: Capture aftermarket channel share from legacy direct-sales infrastructure by deploying digital procurement platforms with same-day fulfillment capabilities. Target workshop technicians in Baden-Württemberg and Bavaria through technical support differentiation rather than brand heritage competition, leveraging configuration tools for mixed-material joining operations. For Investors and Strategic Acquirers: Re-rating potential sits with brushless motor specialists given FAA airworthiness certification timelines that create 18-24 month competitive moats. Long-term viability over the next decade hinges on battery platform interoperability and cloud connectivity module integration. Monitor EU Battery Passport mandate compliance as the inflection signal for European public procurement eligibility.| Strategic Initiative | Industry Significance |
|---|---|
| Brushless Motor Platform Standardization | Extends maintenance intervals beyond 10,000 cycles for Boeing and Airbus tier suppliers. |
| Battery Supply Agreement Localization | Captures PLI scheme incentives near Maruti Suzuki supplier parks in Pune and Chennai. |
| EU Battery Passport Compliance Investment | Secures first-mover advantage for CSRD-aligned traceability in German automotive procurement. |
| Digital Procurement Platform Launch | Erodes Würth Group channel control among Bavarian Mittelstand metal fabricators. |
| FAA Airworthiness Certification Acceleration | Compresses 18-24 month validation cycles for structural fastening tool qualification. |
Research Methodology
SEC filings from power tool manufacturers, FAA airworthiness directive databases, and ECHA REACH substance restriction updates formed the secondary backbone, cross-referenced with primary interviews involving maintenance directors at automotive stamping plants, procurement leads at aerospace Tier-1 suppliers, aftermarket service heads at industrial distributors, and plant engineers at electronics enclosure fabricators. Bottom-up and top-down triangulation validated unit shipment estimates against lithium-ion cell production data and brushless motor import records.
Bottom-up modeling aggregated segment-level demand across product type, motor architecture, and end-user procurement authority, while top-down constraints checked aggregate outputs against known battery platform deployment in Munich, Detroit, and Hamburg manufacturing clusters. CAGRs derived from regression analysis of historical cordless tool adoption rates and projected lithium-ion energy density improvements. Forecast inputs incorporated OSHA ergonomics directive implementation timelines and EMA machinery safety framework phase-in schedules.
The model holds under stable lithium carbonate supply from Chilean and Australian sources; deviation in mining output restrictions or battery transport regulation fragmentation would shift platform economics toward pneumatic alternatives. Forecasts reflect documented assumptions on brushless motor thermal efficiency gains and REACH substance restriction compliance timelines. Stakeholders should weight assumptions against their own operating context and captive supply arrangements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.