
 Fuse Link Market | 2026-2036
Fuse Link Market Size, Share, and Industry Trends Forecast 2026-2036
Fuse Link Market Analysis
Distributor networks serving industrial electrical supply is tilting toward direct OEM partnerships as procurement digitization accelerates. Mersen leverages its ceramic technology leadership to anchor premium fuse link portfolios across European manufacturing zones. Eaton competes through vertical integration into polymer fuse production, sustaining cost advantages in North American utility contracts. Littelfuse specializes in compact surface-mount variants, dominating telecommunications and data center infrastructure segments.
A fuse link is a calibrated overcurrent protection device comprising a metal element—typically silver, copper, or tin alloy—encased in ceramic, glass, or polymer housing, designed to melt and interrupt circuit flow when current exceeds rated thresholds for specified durations. Its primary industrial purpose is safeguarding transformers, switchgear, and distribution panels from thermal damage during fault conditions. Ceramic technology leads in high-voltage power distribution applications where arc-quenching performance and thermal endurance command premium positioning. Polymer fuse links represent the fastest-expanding technology segment, driven by weight reduction demands in renewable energy installations and railway rolling stock. Application demand pools deepest in power distribution utilities, though renewable energy deployment is accelerating fastest as solar and wind farm interconnection standards tighten.
IEC 60269 standards govern fuse link performance ratings across European markets, while UL 248 certification shapes product access in North American electrical infrastructure. India's BIS mandates country-specific testing protocols for fuse links deployed in state power distribution networks, creating localized compliance barriers for imported components. China's GB standards and MIIT energy efficiency directives influence fuse material specifications for equipment manufactured within its industrial zones. Stakeholders must monitor evolving short-circuit capacity requirements as grid modernization programs integrate higher shares of inverter-based renewable generation.
Market Dynamics
IEC 60269 fuse standards and rising renewable energy penetration are forcing utilities to recalibrate procurement specifications across voltage classes and fault-current ratings. Grid modernization programs in Southeast Asia and India's rural electrification push are accelerating replacement cycles for legacy fuse infrastructure.
Growth Catalysts
- India's rural electrification:State utilities are upgrading distribution transformers and switchgear across underserved districts, creating sustained demand for medium-voltage fuse links compliant with BIS testing protocols.
- Renewable interconnection standards:Solar and wind farm developers must install fault-current limiting devices that handle inverter-based generation profiles, expanding the addressable market for high-breaking-capacity fuse technologies.
- Ceramic arc-quenching advances:Improved thermal endurance in ceramic housings enables fuse links to withstand higher short-circuit currents in European manufacturing zones without dimensional expansion.
Market Restraints
- Silver price volatility:Primary fuse element materials face commodity market fluctuations that compress margin structures for manufacturers lacking precious metal hedging capabilities.
- Polymer supply concentration:Specialized engineering resin production for lightweight fuse housings clusters in East Asian chemical processing hubs, exposing buyers to geographic concentration risk.
- Circuit breaker substitution:Resettable overcurrent protection devices are capturing share in low-voltage industrial applications where maintenance access permits non-fuse alternatives.
Strategic Opportunities
- Railway electrification in Southeast Asia:Rolling stock weight reduction mandates are accelerating polymer fuse link adoption for traction power systems in Thailand and Vietnam.
- Data center infrastructure buildouts:Hyperscale facilities require compact surface-mount fuse arrays for power distribution units, opening premium positioning for miniaturized designs.
- EU Green Deal procurement incentives:Public tender scoring systems now favor fuse links with verified recycled content in housing materials, rewarding circular-economy-ready suppliers.
Industry Challenges
- Multi-standard certification timelines:Simultaneous UL 248, IEC 60269, and BIS compliance testing extends product launch cycles by 8-14 months for cross-regional portfolios.
- Legacy switchgear integration:Modern fuse link dimensions and terminal configurations often conflict with installed base specifications in aging European utility infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuse Link Market |
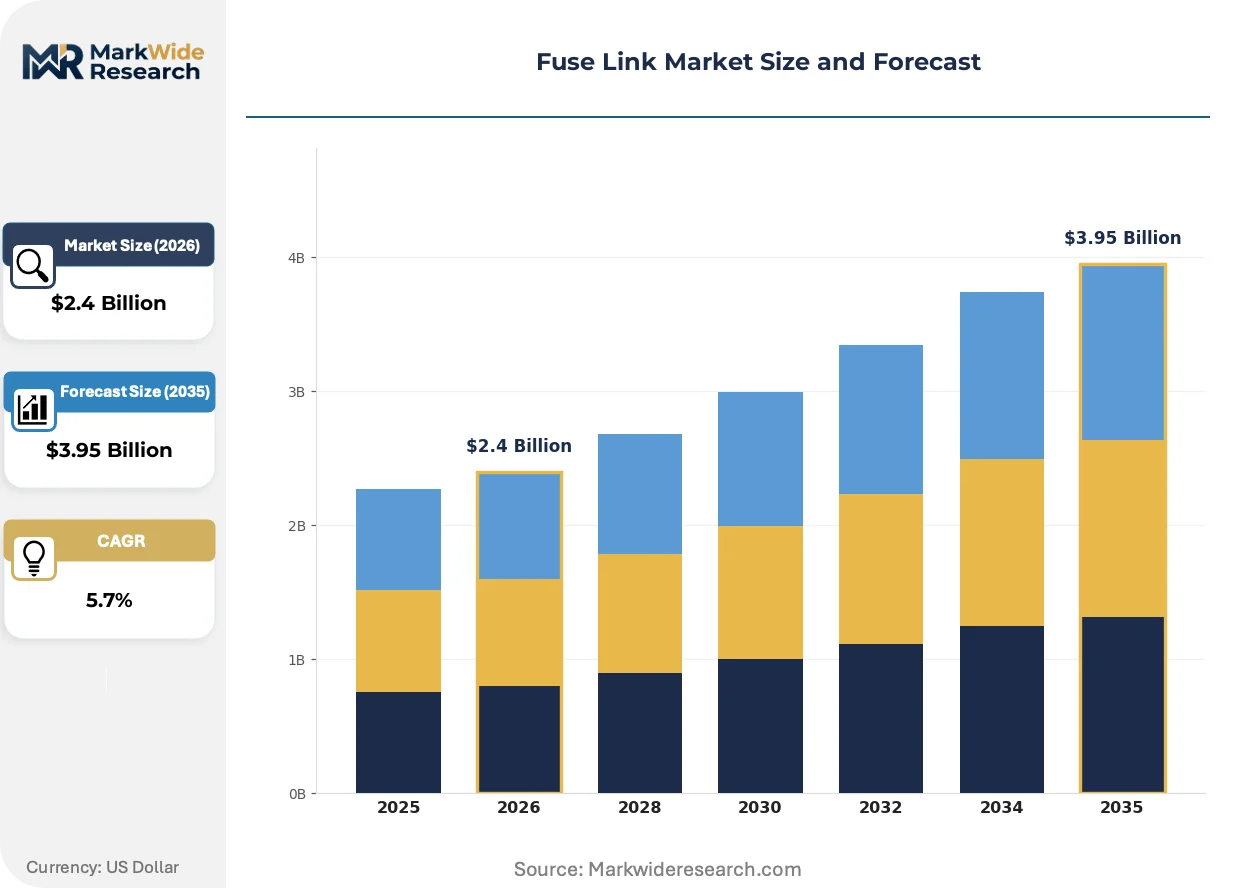
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.95 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuse Links, Fuse Holders, Fuse Cutouts, Fuse Switches Technology: Glass, Ceramic, Polymer, Metal Application: Power Distribution, Renewable Energy, Railways, Telecommunications End User: Manufacturers, Utilities, OEMs, Contractors |
| Companies Covered | Siemens, Mersen, Eaton, Apator, SIBA, ABB, Littelfuse, Hubbell Power Systems, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuse Link Market Emerging Trajectories
Material science breakthroughs and procurement digitization are compressing traditional fuse link development cycles while expanding performance boundaries across voltage classes.
Ceramic-polymer composite housings are hybridizing fuse link construction, combining arc-quenching thermal properties of alumina ceramics with weight advantages of glass-reinforced polymers. Railway OEMs and offshore wind developers are adopting these hybrid designs fastest, driving specification changes in procurement documents. This hybridization is compressing the traditional technology bifurcation between premium ceramic and economy polymer segments.
REACH substance restrictions on cadmium and lead in electrical components are forcing reformulation of traditional fuse element alloys and solder joints. Manufacturers must certify alternative metallurgical compositions without compromising melting-point precision or conductivity ratings. European industrial fuse suppliers face the tightest compliance deadlines, with several already completing full portfolio transitions ahead of regulatory phase-out dates.
Direct OEM partnerships are displacing traditional distributor networks as procurement digitization enables transparent price discovery and technical specification matching. Industrial electrical supply houses in North America are losing share to manufacturer portals for standardized fuse link categories. This channel compression is most visible in utility procurement, where integrated ERP systems now route purchase orders straight to certified production facilities.
Fuse Link Market Segmentation
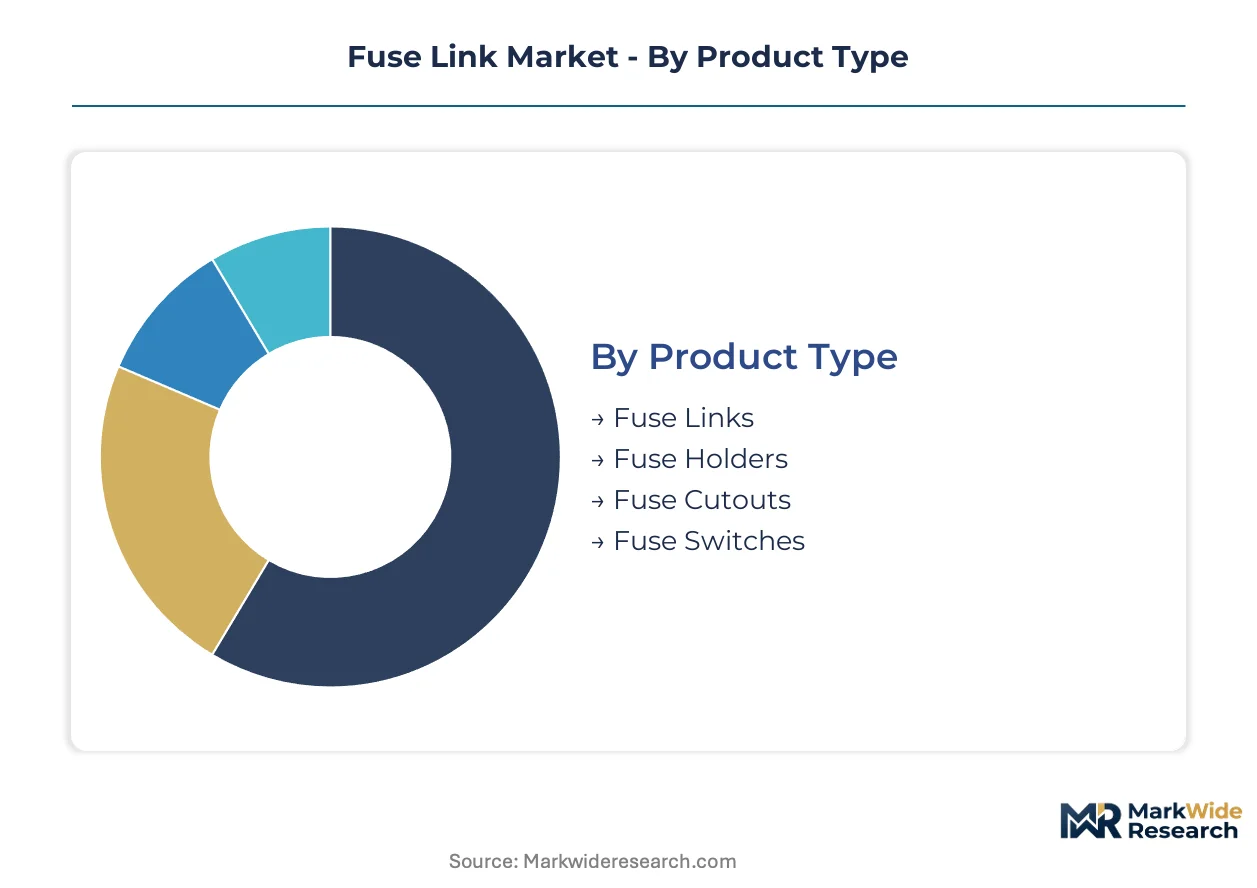
Fuse link procurement varies sharply across voltage classes, material technologies, and end-user sophistication. Each segmentation dimension carries distinct certification requirements and margin structures that shape supplier positioning.
Product Type:
Cost tier determines procurement channel and technical specification depth across the four product categories.
- Fuse Links:Calibrated overcurrent elements—silver, copper, or tin alloy—housed in ceramic, glass, or polymer casings. India's state utilities drive sustained demand for medium-voltage variants compliant with BIS testing protocols as rural electrification accelerates transformer upgrades.
- Fuse Holders:Mounting assemblies securing replaceable fuse elements within switchgear and distribution panels. European manufacturing zones favor DIN-rail compatible designs with IEC 60269 certification for industrial motor protection applications.
- Fuse Cutouts:Pole-mounted expulsion devices protecting overhead distribution lines. Utilities in Southeast Asia specify polymer-housed cutouts for tropical humidity resistance in grid modernization programs.
- Fuse Switches:Combined isolation and protection devices for low-voltage switchgear. Contractors favor these for commercial building installations where space constraints favor integrated functionality.
Fuse links command the established base. The steepest expansion runs through fuse switches.
Technology:
Material selection traces directly to arc-quenching requirements and weight constraints in target applications.
- Ceramic:Alumina-based housings deliver superior thermal endurance and arc extinction in high-voltage power distribution. European utilities specify ceramic fuse links for substation applications where short-circuit currents exceed polymer ratings.
- Polymer:Glass-reinforced engineering resins cut weight by 40-60% versus ceramic equivalents. Railway OEMs in Thailand and Vietnam adopt polymer traction power fuses under rolling stock weight reduction mandates.
- Glass:Transparent tubular housings enable visual fault indication in low-voltage electronics. Telecommunications equipment manufacturers specify glass fuse links for compact power supply protection.
- Metal:Solid-body designs for extreme current-carrying capacity in heavy industrial settings. Mining and steel mill operators specify metal-housed variants for furnace and crusher protection.
Ceramic technology anchors the revenue base. Polymer formulations are climbing the fastest as renewable energy and transportation electrification expand.
Application:
End-use environment dictates breaking capacity, environmental sealing, and replacement accessibility specifications.
- Power Distribution:Medium-voltage fuse links protecting transformers, capacitors, and distribution feeders. India's state utilities represent the deepest demand pool as rural electrification infrastructure scales.
- Renewable Energy:Fault-current limiting devices for solar inverter outputs and wind turbine collector circuits. Interconnection standards tightening across multiple jurisdictions accelerate high-breaking-capacity fuse procurement.
- Railways:Traction power protection for electrified rolling stock and substation equipment. Southeast Asian railway electrification programs specify lightweight polymer designs for overhead catenary systems.
- Telecommunications:Compact surface-mount fuses for data center power distribution units and base station equipment. Hyperscale facility buildouts drive miniaturized array demand.
Power distribution retains the volume base. Renewable energy installations are gaining share fastest as inverter-based generation reshapes grid protection requirements.
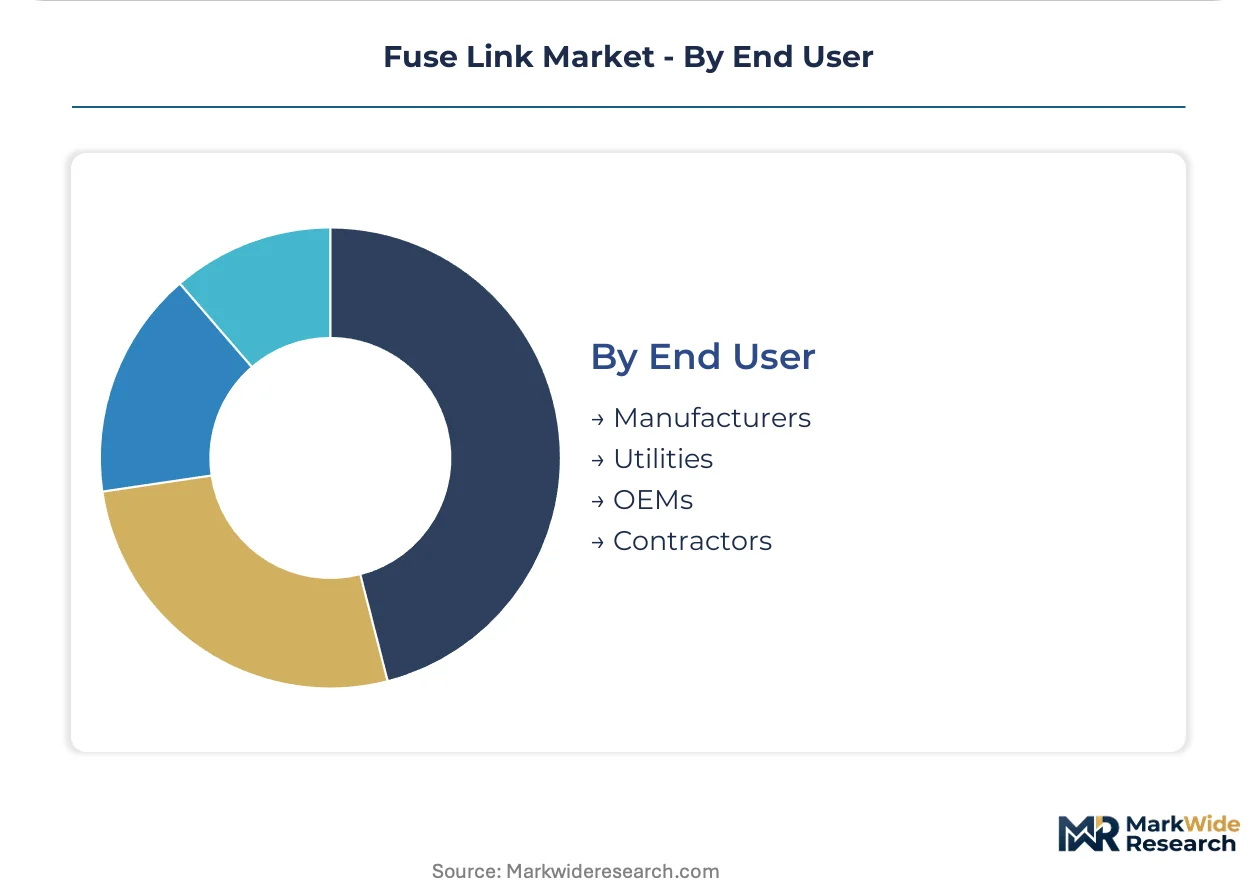
End User:
Customer type shapes procurement sophistication, contract duration, and technical support expectations.
- Utilities:State and regional power distribution companies with formal tender processes and multi-year framework agreements. India's state utilities enforce BIS compliance as mandatory for rural electrification procurement.
- OEMs:Original equipment manufacturers integrating fuse links into switchgear, inverters, and rolling stock. Direct partnerships are displacing distributor networks as procurement digitization enables specification matching.
- Manufacturers:Industrial electrical equipment producers sourcing fuse links for panel assembly. These buyers prioritize UL 248 or IEC 60269 pre-certified components to compress product launch cycles.
- Contractors:Installation and maintenance firms serving commercial and industrial building projects. This segment favors fuse switches and cutouts with tool-free replacement features.
Utilities dominate the established procurement base. OEM direct sourcing is expanding most quickly as channel digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government electrification programs and grid modernization mandates are steering procurement volumes toward specific national markets. Regulatory frameworks in India, Germany, the United States, China, and Japan are establishing distinct compliance thresholds that reshape supplier access and technology preferences.
India
State utilities are executing rural electrification infrastructure upgrades across underserved districts. BIS mandates country-specific testing protocols for medium-voltage fuse links deployed in distribution networks. Manufacturing clusters in Maharashtra and Gujarat are scaling ceramic fuse production to meet utility tender requirements.
Germany
Industrial manufacturing zones require high-breaking-capacity protection for substation equipment and motor control centers. REACH substance restrictions are forcing reformulation of fuse element alloys ahead of regulatory phase-out dates. Production facilities in Bavaria and Baden-Württemberg are transitioning portfolios to cadmium-free compositions.
United States
Utility-scale renewable interconnection projects are driving demand for fault-current limiting devices compatible with inverter-based generation. UL 248 certification shapes product access across North American electrical infrastructure. Procurement digitization in Texas and California utilities is compressing distributor channels in favor of direct OEM relationships.
China
MIIT energy efficiency directives influence fuse material specifications for equipment manufactured within domestic industrial zones. GB standards govern performance ratings for components integrated into switchgear and distribution panels. Yangtze River Delta manufacturing clusters are expanding polymer fuse housing capacity for railway and wind power applications.
Japan
METI guidelines on grid resilience are accelerating replacement cycles for aging distribution protection equipment. JIS standards establish precise dimensional and performance requirements for low-voltage industrial applications. Kanto region utilities are specifying compact fuse designs for dense urban substation retrofits.
Fuse Link Market Vendor Landscape
On the supply side, the industry is consolidating around technology-specialized portfolios with distinct material competencies. Tiered competitive positioning separates ceramic technology leaders from polymer-focused cost optimizers and compact electronics specialists. Dominant competitive moves include backward integration into raw material production and direct OEM partnership structures that displace traditional distribution networks.
Among European industrial electrical suppliers, Mersen and SIBA exemplify ceramic technology leadership anchored in premium high-voltage applications. Eaton represents North American vertical integration into polymer fuse production, sustaining cost advantages in utility procurement. Littelfuse occupies a position within the compact electronics tier, specializing in surface-mount variants for telecommunications and data center infrastructure segments.
| Leading Market Players |
|---|
| Siemens |
| Mersen |
| Eaton |
| Apator |
| SIBA |
| ABB |
| Littelfuse |
| Hubbell Power Systems |
| Schneider Electric |
| Others |
Supply Flow & Price Mechanics
Silver price volatility in commodity markets determines both the spread between premium ceramic and economy polymer fuse tiers and the geographic clustering of manufacturing capacity. Manufacturers lacking precious metal hedging capabilities face margin compression that accelerates backward integration into captive silver refining or alloy production.
Pricing Analysis
Certification level creates the primary spread across fuse link procurement, with BIS-compliant variants for Indian utilities commanding premiums over standard IEC 60269 equivalents. Pricing stratifies across premium ceramic, standard hybrid composite, and economy polymer tiers based on breaking capacity ratings and arc-quenching performance. Cost compression in the polymer segment is intensifying because railway OEMs in Thailand and Vietnam are consolidating purchase volumes under weight-reduction mandates. Contractors serving commercial building installations exhibit the highest price sensitivity, while European utilities purchasing substation-grade ceramic fuses demonstrate the lowest.
Supply Chain Analysis
Contract manufacturing for polymer fuse housings concentrates in Yangtze River Delta chemical processing clusters and selected Bavarian engineering resin facilities. Raw material supply draws from Chilean silver mining operations, Chinese alumina refineries, and South Korean glass-reinforced polymer feedstock producers. Single-source vulnerability runs through East Asian specialized engineering resin production, exposing buyers to geographic concentration risk. Distribution runs through direct OEM partnerships that are displacing traditional industrial electrical supply houses as procurement digitization enables transparent specification matching.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fuse link markets reward suppliers who attach technical advisory and replacement scheduling services to hardware contracts, as Indian state utilities and European railway OEMs expand predictive maintenance programs faster than baseline equipment procurement.
For Market Incumbents: Insulate ceramic technology leadership by securing long-term silver supply agreements with Chilean mining consortiums and accelerating cadmium-free alloy transitions ahead of REACH enforcement deadlines. Add captive polymer compounding capacity in Maharashtra to defend margin position against East Asian resin price volatility. For New Entrants and Emerging Players: Build out BIS certification capabilities to penetrate India's rural electrification tender pipeline, where state utilities prioritize local testing compliance over established brand recognition. Target polymer fuse supply for Southeast Asian railway electrification programs through partnerships with Thai and Vietnamese rolling stock assemblers seeking weight-reduction credentials. For Investors and Strategic Acquirers: EU Green Deal procurement incentives reshaping public tender scoring systems favor acquisition targets with verified recycled-content housing portfolios and circular-economy-ready production footprints. Monitor BIS testing protocol amendments as the critical inflection signal for import substitution opportunities in Indian distribution infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Alloy Production | Captive refining hedges commodity volatility for manufacturers serving IEC 60269 premium segments. |
| BIS Certification Investment | Country-specific testing protocols unlock state utility procurement in India's rural electrification push. |
| Polymer Compounding Capacity Expansion | In-house resin production reduces geographic concentration risk from East Asian chemical hubs. |
| Direct OEM Partnership Structure | Bypassing distributor networks captures margin compression from procurement digitization in utility segments. |
| Cadmium-Free Alloy Transition | REACH compliance ahead of phase-out dates secures European manufacturing zone access. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of utility tender documents, BIS testing protocol amendments, and IEC standard revision drafts. Primary interviews engaged procurement directors at Indian state utilities, fuse application engineers at European railway OEMs, and commercial managers at industrial electrical distributors. Secondary validation drew from customs trade data, CDSCO medical device filings where applicable, and SEC disclosures from listed electrical component manufacturers. Bottom-up demand modeling triangulated against top-down grid investment forecasts across the analysis window.
Forecast inputs considered voltage class segmentation, material technology substitution rates, and end-user procurement digitization maturity. Modeled dimensions spanned product type, housing material, application environment, and customer archetype sophistication. CAGRs were derived from regression analysis of historical tender volumes and projected infrastructure investment trajectories. Industry-specific inputs included solar and wind interconnection standard tightening timelines and railway electrification program announcements.
Stress conditions across silver price bands, polymer resin supply disruptions, and multi-standard certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding grid modernization program execution rates and renewable energy penetration curves. Quarterly review of BIS protocol amendments, REACH substance restriction updates, and Southeast Asian railway procurement announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
Alternators Market
Electrical Power Equipment
Overhead Aluminium Conductors Market
Electrical Power Equipment
Electrical Steel for Electric Vehicle Market
Electrical Power Equipment
North America Oil Filled Electric Heaters Market
Electrical Power Equipment
Solid Vacuum Reclosers Market
Electrical Power Equipment
Global Lightning Arrester Market
Electrical Power Equipment
Gas Insulated Switchgear Sales Market
Electrical Power Equipment
Global Duct Heaters Market
Electrical Power Equipment
Electric Vehicle Charging Cables Market
Electrical Power Equipment
Domestic Hot Water (DHW) Tanks Market
Electrical Power Equipment
Train Contactor Market
Electrical Power Equipment
HVDC Converter Station Market
Electrical Power Equipment
Europe Brushless DC Motors Market
Electrical Power Equipment
Hollow Core Insulator Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
High Voltage Oil Insulated Switchgear Market