
 Fault Circuit Indicator Market | 2026-2036
Fault Circuit Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Fault Circuit Indicator Market Foresight
Utility procurement is decoupling from traditional centralized purchasing toward fragmented regional distribution operators and industrial microgrid developers. ABB leverages its integrated power automation portfolio to serve both transmission-scale utilities and emerging commercial microgrid operators. Schweitzer Engineering Laboratories (SEL) anchors its position through deep specialization in protective relay integration with fault sensing hardware. Schneider Electric competes by extending its EcoStruxure platform to embed circuit health analytics directly into building and grid management software.
A fault circuit indicator is a sensing device installed on electrical distribution lines to detect and signal fault conditions such as short circuits or earth faults, typically operating through electromagnetic field detection with sensitivity thresholds calibrated to distribution voltage classes. Its primary purpose is to reduce outage duration by enabling line crews to locate fault segments without manual sectionalizing. Smart indicators incorporating sensor technology and wireless communication are capturing disproportionate investment as utilities prioritize real-time fault location data over passive visual indication. Permanent installation categories dominate current revenue, though retrofits and upgrades are accelerating where aging overhead infrastructure requires non-disruptive sensor augmentation.
FERC Order 2222 in the United States and the EU Green Deal's distribution grid resilience targets are mandating faster fault isolation and restoration capabilities, directly elevating technical specifications for indicator response time and communication interoperability. IEEE 495 and IEC 60871 standards govern product certification, creating compliance barriers for manufacturers lacking accredited testing infrastructure. Stakeholders must monitor how distributed energy resource interconnection rules reshape fault current profiles and demand for hybrid technology indicators capable of discriminating bidirectional fault signatures.
Market Dynamics
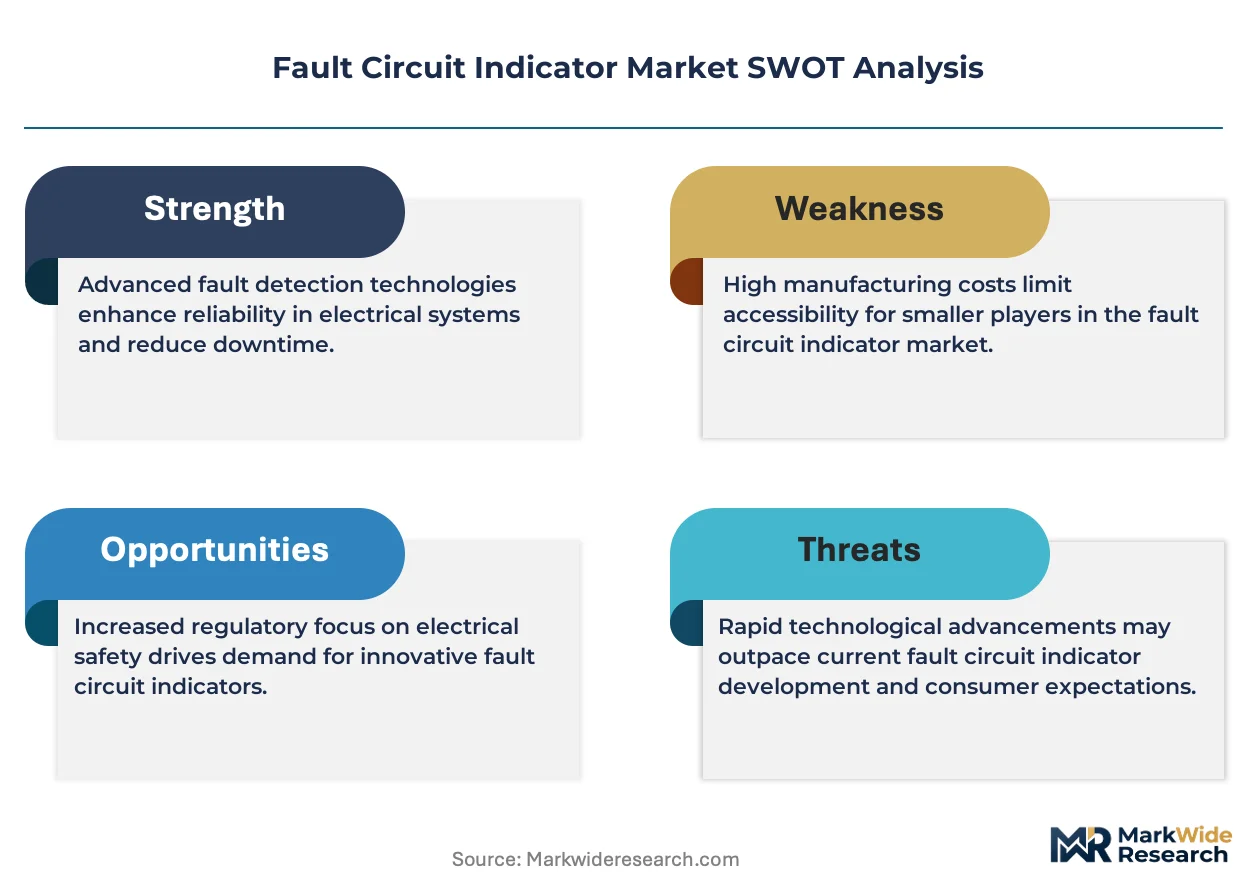
Grid modernization mandates are forcing utilities to replace passive electromechanical fault indicators with networked sensor platforms capable of real-time fault location and two-way communication, fundamentally restructuring procurement priorities toward interoperability and data integration.
Growth Catalysts
- FERC Order 2222:This US regulation mandates distribution utilities to enable faster fault isolation and restoration, directly elevating technical specifications for indicator response time and communication protocols across American grid operators.
- Overhead line sensor retrofit programs:Aging infrastructure in Germany and the United States requires non-disruptive augmentation with wireless fault detection, creating sustained replacement demand without full line reconstruction.
- Industrial microgrid proliferation:Commercial and campus-scale microgrid developers in China are deploying hybrid fault indicators capable of discriminating bidirectional current flows from distributed solar and storage assets.
Market Restraints
- Copper and rare earth magnet cost volatility:Electromagnetic sensing cores depend on neodymium and copper windings, exposing manufacturers to Chinese supply concentration and commodity price swings that compress hardware margins.
- IEC 60871 certification timelines:European accreditation requires 18-24 month testing cycles for wireless communication modules, creating compliance barriers for smaller manufacturers lacking accredited laboratory partnerships.
- Passive visual indicator substitution:Low-cost mechanical flag indicators retain 40% share in budget-constrained rural cooperatives, limiting premium smart sensor penetration in price-sensitive distribution segments.
Strategic Opportunities
- EU Green Deal resilience targets:Distribution grid hardening mandates across Poland, Romania, and Greece create first-mover advantage for indicators with sub-100ms fault detection and automatic sectionalizing integration.
- Drone-mounted thermal verification:Utilities are pairing permanent line sensors with UAV-based fault confirmation, opening aftermarket service contracts for indicator vendors with aerial analytics partnerships.
- 5G-RedCap module integration:Low-power wide-area cellular standards are converging with edge computing, enabling battery-free indicators that harvest line current for power and transmit via public networks.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time operating systems for sub-cycle fault detection require specialized signal processing engineers, with competition intensifying from automotive and aerospace sectors.
- Legacy SCADA integration complexity:Utilities operating 1990s-era DMS platforms face protocol translation burdens when deploying IEC 61850-compliant indicators, extending deployment timelines and requiring custom middleware.
- IP fragmentation in wireless mesh protocols:Proprietary communication stacks from incumbent vendors create interoperability disputes, forcing buyers into single-source commitments that conflict with open-architecture procurement policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fault Circuit Indicator Market |
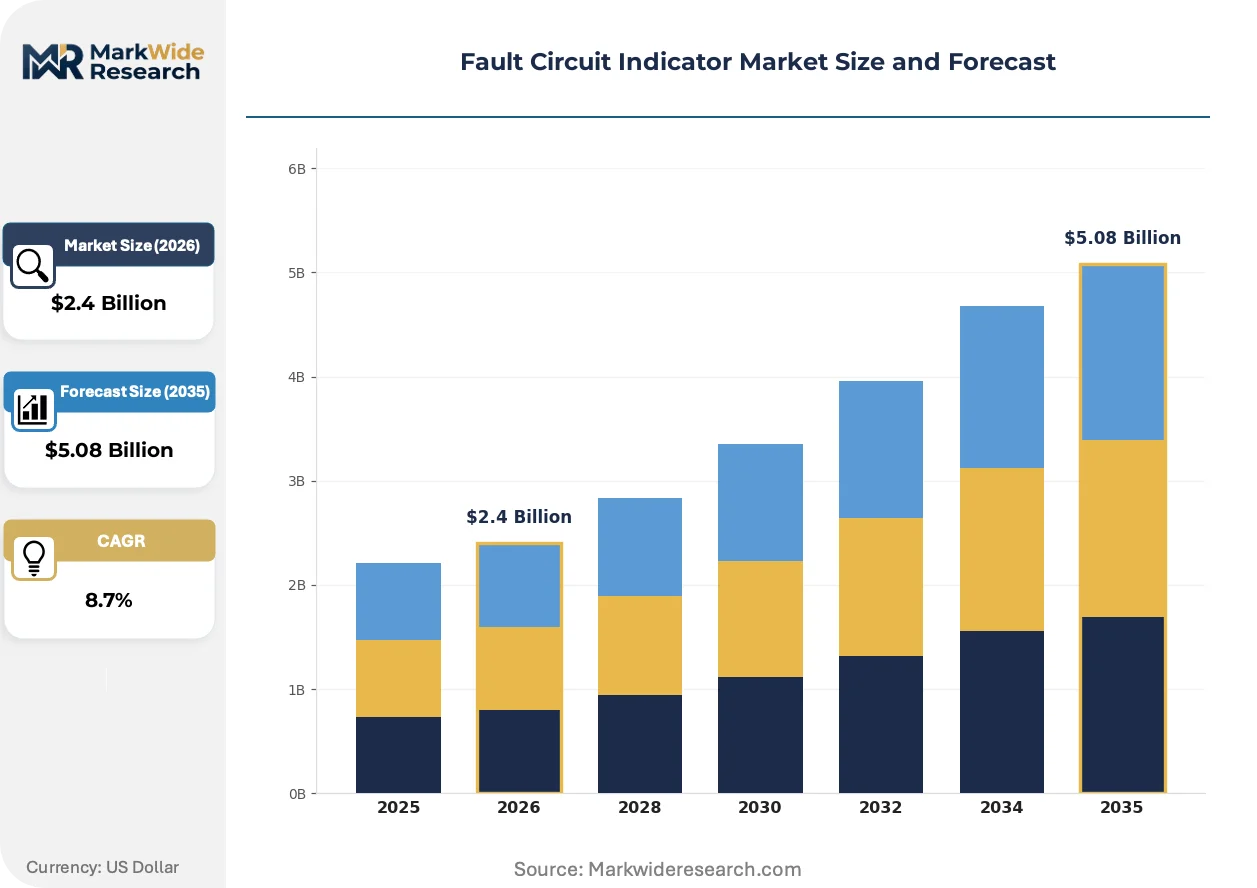
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Indicators, Analog Indicators, Wireless Indicators, Smart Indicators Installation: Permanent Installation, Temporary Installation, Retrofits, Upgrades End User: Utility Companies, Industrial Facilities, Commercial Buildings, Residential Users Technology: Optical Technology, Electromagnetic Technology, Sensor Technology, Hybrid Technology |
| Companies Covered | ABB, Schneider Electric, Schweitzer Engineering Laboratories (SEL), NORTROLL, Elektro-Mechanik GmbH, Dipl.-Ing. H. Horstmann GmbH, Siemens, CELSA, Eaton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fault Circuit Indicator Market Shifts & Advancements
Fault circuit indicators are evolving from standalone electromechanical devices into networked grid edge computers, with sensing, communication, and analytics functions collapsing into single hardware platforms that redefine vendor value propositions.
Self-powered wireless fault indicators with energy harvesting from line current is overtaking battery-dependent designs across North American and European utilities. ABB and SEL are deploying photovoltaic-thermal hybrid units that eliminate maintenance cycles. This technology is overtaking traditional battery-replacement service contracts as the primary revenue anchor, compressing vendor business models toward upfront hardware margins.
EU Green Deal distribution resilience directives are accelerating mandatory fault location performance standards in Germany, France, and the Netherlands. National regulators now require sub-500-meter sectionalizing precision for urban networks. Medium-voltage underground cable indicators with distributed acoustic sensing are capturing disproportionate investment as utilities respond to urban densification constraints.
Regional distribution operators are consolidating procurement authority previously held by centralized transmission utilities. Mid-sized municipal utilities in Texas, Bavaria, and Shandong now issue direct tenders for indicator fleets under 1,000 units. This fragmentation is visible most acutely in the United States, where FERC Order 2222 implementation has spawned over 200 independent distribution-level procurement entities with diverging technical specifications.
Fault Circuit Indicator Market Segmentation
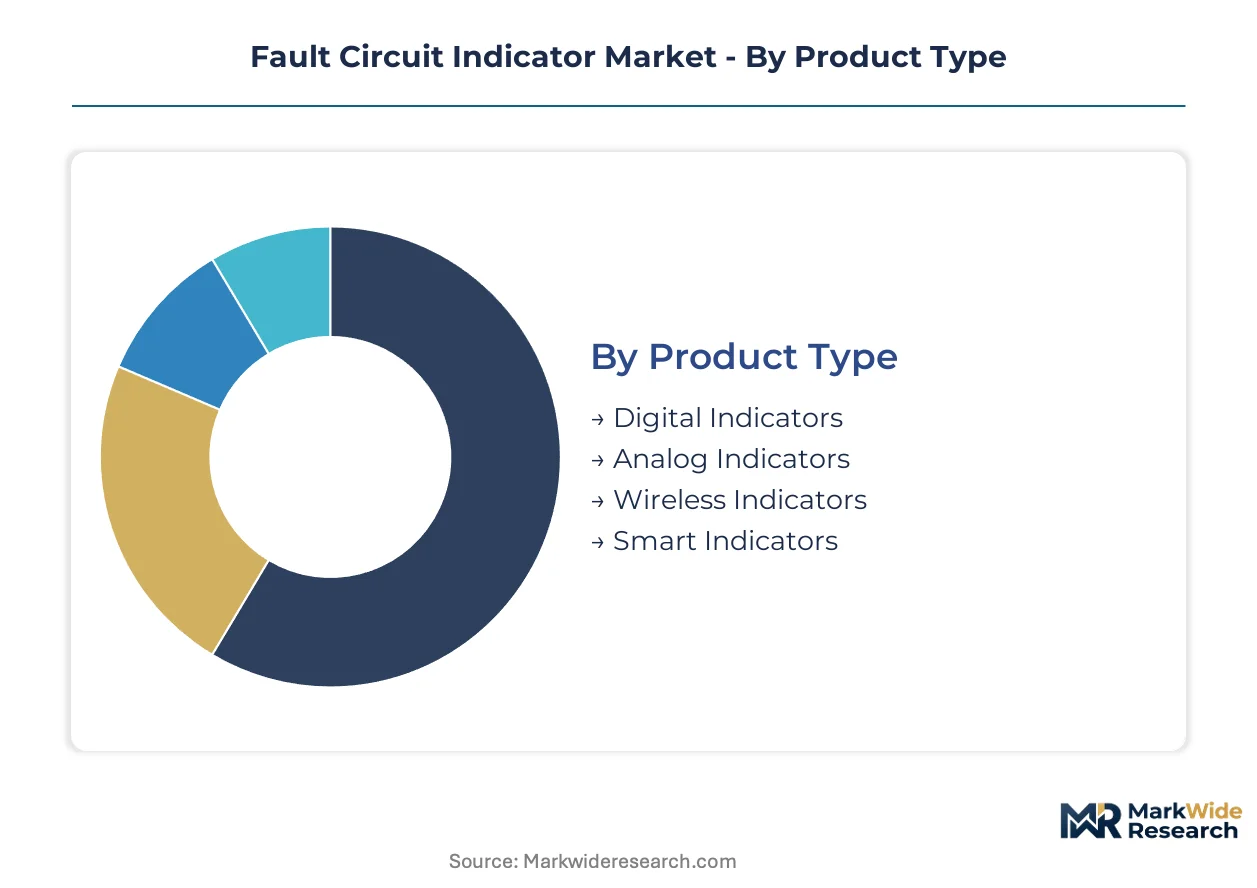
Fault circuit indicator procurement varies sharply by buyer technical sophistication and grid infrastructure maturity. Segment boundaries determine pricing power, certification requirements, and vendor selection criteria across utility, industrial, and commercial channels.
Product Type:
Buyer investment capacity separates passive hardware purchasers from data-integrated platform adopters.
- Smart Indicators:These units combine electromagnetic sensing with edge computing and IEC 61850-compliant communication protocols. German distribution operators and Texas municipal utilities are concentrating procurement here as FERC Order 2222 and EU Green Deal mandates elevate real-time fault location requirements above visual flagging.
- Wireless Indicators:Self-powered designs harvest line current for telemetry transmission via cellular or mesh networks. North American rural cooperatives facing battery maintenance cost pressures are shifting procurement toward these maintenance-free alternatives despite 15-20% hardware premiums.
- Digital Indicators:Microprocessor-based units with LCD fault displays and basic data logging capabilities.
- Analog Indicators:Electromechanical flag and LED systems without communication functionality retain dominance in budget-constrained emerging market utilities.
Volume sits with Analog Indicators; growth tilts toward Smart Indicators.
Installation:
Deployment economics hinge on whether line crews can access energized conductors without service interruption.
- Permanent Installation:Hot-stick mountable clamp designs with 25-30 year service life dominate new-build distribution corridors. Chinese state grid corporations and U.S. investor-owned utilities are standardizing on these for greenfield urban underground cable networks where access windows are prohibitively expensive.
- Retrofits:Non-disruptive augmentation of 1960s-1980s overhead infrastructure with wireless sensor pods accelerates where full line reconstruction faces regulatory or budget barriers. Polish and Romanian operators under EU resilience funding are prioritizing this category for aging rural feeders.
- Upgrades:Communication module add-ons to existing electromagnetic indicators extend asset life without full replacement.
- Temporary Installation:Portable clamp-on units for storm response and maintenance outage sectionalizing serve emergency restoration crews.
Revenue concentrates in Permanent Installation; expansion is steepest in Retrofits.
End User:
Procurement scale and technical specification authority fragment across centralized utilities and distributed facility operators.
- Utility Companies:Transmission-scale operators and distribution cooperatives issue fleet tenders exceeding 10,000 units with mandatory IEEE 495 certification. U.S. municipal utilities in California and Florida are consolidating previously fragmented purchasing through joint procurement alliances to negotiate interoperability standards.
- Industrial Facilities:Campus-scale microgrid operators in China and petrochemical complexes on the U.S. Gulf Coast demand hybrid indicators discriminating bidirectional fault currents from on-site solar and battery assets.
- Commercial Buildings:Hospital and data center operators with internal medium-voltage distribution specify indicators integrating with building management systems via BACnet protocols.
- Residential Users:Individual property-level deployment remains negligible outside off-grid solar installations in remote geographies.
Spending dominance rests with Utility Companies; Industrial Facilities are climbing the fastest.
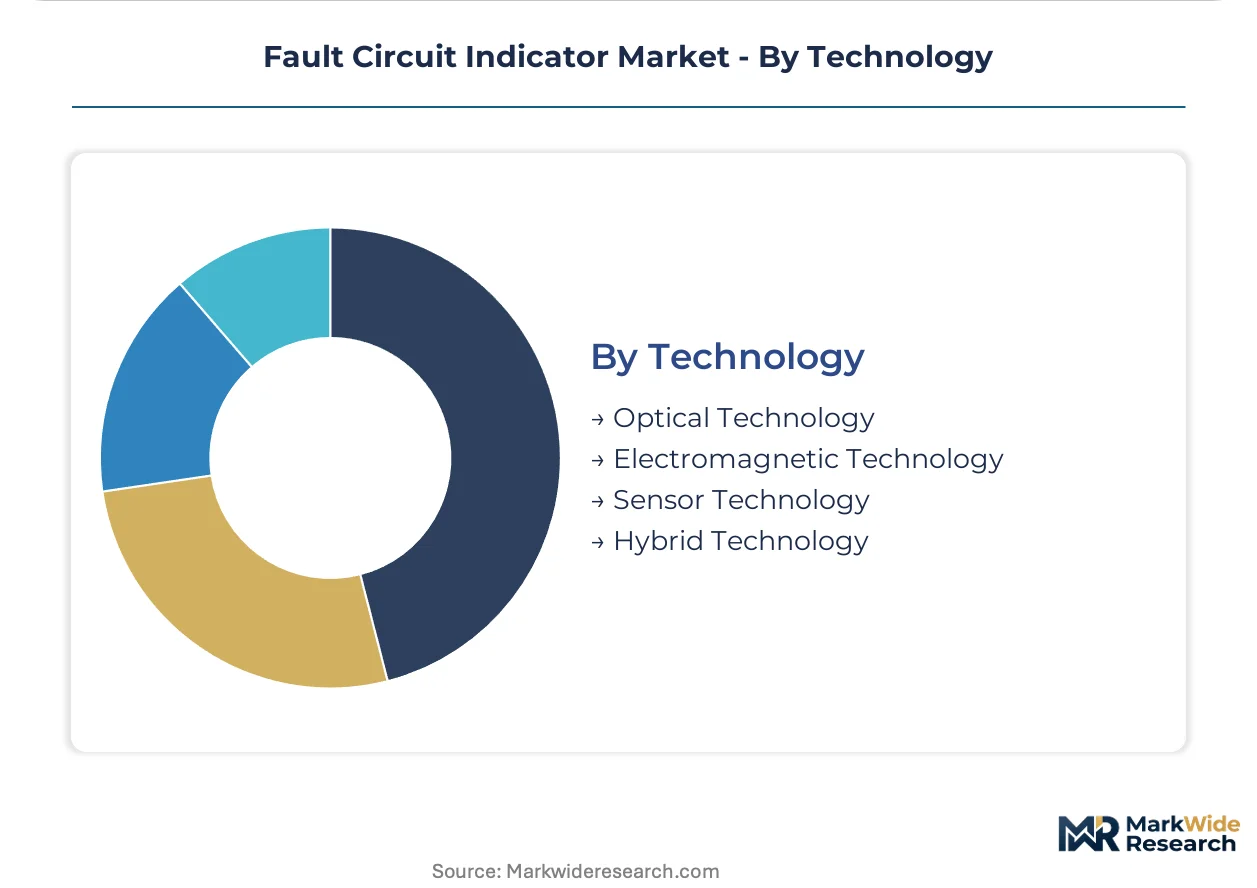
Technology:
Sensing modality selection determines fault signature discrimination capability and environmental immunity.
- Electromagnetic Technology:Current transformer-based detection with calibrated threshold sensitivity to distribution voltage classes remains the cost-optimized baseline. Legacy deployments across the U.S. Midwest and Central European rural networks maintain this installed base.
- Hybrid Technology:Multi-physics sensing combining electromagnetic, acoustic, and thermal channels enables discrimination of high-impedance faults and bidirectional current flows. Underground cable networks in Dutch urban centers and Shanghai's distribution densification projects are concentrating demand here as fault location precision requirements tighten.
- Sensor Technology:MEMS accelerometer and temperature arrays for distributed parameter monitoring.
- Optical Technology:Fiber-optic current sensing for EMI-critical environments near high-voltage substations.
Installed base clusters with Electromagnetic Technology; specification momentum favors Hybrid Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility procurement for fault circuit indicators concentrates in the United States, Germany, and China as distribution network resilience investments accelerate. Grid modernization mandates from FERC and the EU Green Deal are restructuring procurement toward real-time fault location capabilities. Each geography presents distinct regulatory drivers and infrastructure maturity profiles.
United States
FERC Order 2222 mandates faster fault isolation and restoration capabilities across distribution utilities. Texas municipal utilities and California investor-owned operators are consolidating fragmented purchasing through joint procurement alliances. The Southeast storm corridor drives emergency restoration fleet deployment for temporary installation indicators.
Germany
EU Green Deal distribution grid resilience targets elevate technical specifications for sub-100ms fault detection. Bavarian and North Rhine-Westphalia operators lead overhead line sensor retrofit programs for aging 1960s-1980s infrastructure. Dutch urban centers and Frankfurt underground cable networks concentrate hybrid technology demand for distributed acoustic sensing.
China
State Grid corporations standardize on permanent installation designs for greenfield urban underground networks. Shandong and Shanghai distribution densification projects drive specification tightening for fault location precision. Industrial microgrid developers in campus-scale solar and storage deployments demand bidirectional current discrimination capabilities.
Poland
EU resilience funding channels investment toward non-disruptive augmentation of rural feeders with wireless sensor pods. National regulators under Green Deal implementation require automatic sectionalizing integration for distribution hardening. Romanian and Greek operators mirror this retrofit acceleration pattern under similar funding mechanisms.
Fault Circuit Indicator Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart grid edge computing integration and microgrid-specific sensing portfolios. The vendor base clusters around three archetypes: integrated power automation conglomerates, protective relay specialists, and regional electromechanical fabricators. Dominant competitive moves include strategic partnerships for communication protocol certification and portfolio diversification into energy harvesting designs.
Within the integrated automation tier, ABB leverages its power automation portfolio breadth, while Schneider Electric extends platform-based building and grid management software. Schweitzer Engineering Laboratories anchors the protective relay specialist position through deep hardware-software integration. Among European fabricators, NORTROLL and Elektro-Mechanik GmbH exemplify regional precision engineering capabilities serving distribution operators with specialized certification compliance.
| Leading Market Players |
|---|
| ABB |
| Schneider Electric |
| Schweitzer Engineering Laboratories (SEL) |
| NORTROLL |
| Elektro-Mechanik GmbH |
| Dipl.-Ing. H. Horstmann GmbH |
| Siemens |
| CELSA |
| Eaton |
| Others |
Supply & Pricing Matrix
Captive in-house production of electromagnetic sensing cores anchors supply position for tier-one manufacturers while insulating them from neodymium and copper price swings that compress margins for outsourced competitors. This vertical integration choice concentrates pricing power with ABB, SEL, and Schneider Electric, enabling three-tier pricing structures across premium smart indicators, standard wireless units, and economy analog devices.
Pricing Analysis
Volume concentrates in analog indicators while margins concentrate in smart sensor platforms. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified smart indicators from basic wireless units and electromechanical flag systems. Cost compression in the analog tier intensifies because Chinese fabricators flood emerging markets with unbranded mechanical indicators. Rural electric cooperatives in the United States Midwest exhibit highest price sensitivity, while German distribution operators under EU Green Deal mandates show lowest sensitivity to hardware premiums.
Supply Chain Analysis
IEC 60871 and IEEE 495 certification gating creates 18-24 month qualification timelines that filter out unaccredited suppliers before volume procurement decisions. Manufacturing concentrates in Germany, China, and the United States, with electromagnetic cores drawing from Chinese rare earth processing and copper windings sourced from Chilean and Indonesian smelters. Single-source vulnerability in neodymium magnet supply exposes European and North American assemblers to export restriction risk. Distribution runs through utility procurement alliances and industrial EPC contractors rather than open distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FERC Order 2222 and EU Green Deal technical specifications erect barrier-to-entry moats for players with accredited testing infrastructure and certified protocol stacks.
For Market Incumbents: Deploy firmware development capacity as the priority lever to counter embedded systems talent scarcity from automotive and aerospace competition. Acquire specialized signal processing engineering teams in Poland and Romania where technical education pipelines remain under-tapped. Consolidate position by extending energy harvesting intellectual property into 5G-RedCap module integration before cellular standards fully converge. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer the lowest-friction entry vector for indicator vendors lacking established field service networks. Target Polish and Romanian distribution operators under EU resilience funding as the most penetrable geography, where retrofit demand for wireless sensor pods outstrips incumbent capacity. Lead with drone-mounted thermal verification service bundling to differentiate beyond hardware commoditization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated power automation conglomerates seeking sensor technology tuck-ins. Long-term viability favors vendors with hybrid technology portfolios capable of discriminating bidirectional fault signatures from distributed solar and storage assets. Watch for inflection in distributed energy resource interconnection rule changes that reshape fault current profiles and obsolete single-physics sensing architectures.| Strategic Initiative | Industry Significance |
|---|---|
| 5G-RedCap Module Integration | Enables battery-free indicators harvesting line current for public network transmission. |
| Hybrid Technology Development | Combines electromagnetic, acoustic, and thermal sensing for bidirectional fault discrimination. |
| Drone Partnership Formation | Creates aftermarket service contracts pairing permanent sensors with UAV-based fault confirmation. |
| Certification Laboratory Investment | Accelerates IEC 60871 and IEEE 495 approval timelines for wireless communication modules. |
| Microgrid-Specific Portfolio Launch | Captures industrial campus demand for indicators discriminating solar and battery fault currents. |
Research Methodology
Document review covered FERC orders, EU Green Deal implementation directives, IEEE 495 and IEC 60871 standards documentation, and utility procurement databases, complemented by interviews with distribution planning engineers, protective relay specialists, microgrid developers, and SCADA integration consultants. Secondary validation drew from EIA grid modernization reports, State Grid Corporation technical specifications, and SEC filings from listed power automation suppliers. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Segment-level outputs reflect product type, installation category, end-user archetype, and technology modality interactions modeled throughout the forecast period. CAGRs were derived from regression against grid modernization spending trajectories, regulatory mandate implementation schedules, and distributed energy resource penetration curves. Key inputs included overhead line sensor retrofit program announcements, industrial microgrid project development pipelines, and rare earth magnet price volatility indices.
Inputs from utility procurement databases and standards body documentation were available through the study window; gaps in real-time deployment tracking for Chinese state grid projects introduce uncertainty bands around Asia-Pacific volume assumptions. Forecasts reflect documented assumptions regarding FERC Order 2222 implementation pace and EU resilience funding allocation efficiency. A model refresh is warranted upon material change in distributed energy resource interconnection rules or IEEE 61850 protocol revision timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Power Equipment
North America Alternating Current (AC) Drive Market
Electrical Power Equipment
South America Air Insulated Switchgear Market
Electrical Power Equipment
Bucket Water Heater Market
Electrical Power Equipment
North America Power Inverter Market
Electrical Power Equipment
Nuclear Cables Sales Market
Electrical Power Equipment
Residential Air Insulated Power Distribution Component Market
Electrical Power Equipment
SF6 Gas Circuit Breaker Market
Electrical Power Equipment
Offshore Cables Market
Electrical Power Equipment
Electric Submersible Pump Cable Market
Electrical Power Equipment
Alternator Regulator Market
Electrical Power Equipment
Power Strip Market
Electrical Power Equipment
High Voltage Direct Current (HVDC) Cables Market
Electrical Power Equipment
Substation Market
Electrical Power Equipment
Overhead Power Cables Market
Electrical Power Equipment
Packaged Substation Market
Electrical Power Equipment
Global Magnetic Circuit Breaker Market