
 Global Controlled Release Drug Delivery Market | 2026-2036
Global Controlled Release Drug Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Controlled Release Drug Delivery Market Foresight
Consolidation among hospital group purchasing organizations is realigning how long-acting formulations reach end users. Pfizer leverages its manufacturing scale to supply integrated delivery networks with extended-release platforms. Alkermes specializes in depot formulations for CNS therapy areas, sustaining its position through proprietary polymer technologies. Novartis competes across multiple controlled-release modalities, extending its reach from oncology to cardiovascular applications.
Controlled release drug delivery encompasses formulations engineered to release active pharmaceutical ingredients at predetermined rates over hours to months, utilizing polymeric matrices, osmotic pumps, or lipid-based carriers to maintain therapeutic plasma concentrations. These systems reduce dosing frequency, improve patient compliance, and minimize peak-trough fluctuations that compromise safety or efficacy. Polymeric technology dominates current revenue owing to decades of clinical validation and scalable manufacturing infrastructure, while nanoparticle platforms represent the fastest-expanding segment as precision targeting gains traction in oncology. Oral controlled-release products occupy the largest volume position due to patient preference and cost-effective production, though implantable systems command premium pricing in chronic therapy areas where adherence determines outcomes.
The FDA maintains stringent bioequivalence standards for extended-release generics, while the EMA's quality guidelines for modified-release products shape development priorities across European development pipelines. Japan's PMDA evaluates controlled-release submissions through its Sakigake designation pathway, accelerating access for novel delivery mechanisms. Stakeholders must monitor evolving pharmacopeial standards for in-vitro dissolution testing, as harmonization between FDA, EMA, and ICH guidelines will determine which platform technologies achieve multi-regional commercialization without redundant clinical programs.
Market Dynamics
Hospital group purchasing organizations are consolidating procurement for long-acting formulations, forcing manufacturers to restructure commercial strategies around integrated delivery networks rather than individual institutions.
Growth Catalysts
- FDA Accelerated Approval Pathways:The FDA's streamlined review for complex generics and sustained-release platforms compresses time-to-market for bioequivalent extended-release products.
- Japan's Sakigake Designation:PMDA's priority review pathway for novel delivery mechanisms accelerates commercialization timelines for first-in-class depot formulations.
- Aging Demographics in Germany:Chronic disease prevalence among elderly populations expands addressable patient pools for monthly and quarterly dosing regimens.
Market Restraints
- Polymer Raw Material Concentration:Specialty biodegradable polymers for depot systems source predominantly from European and Chinese chemical suppliers, creating input vulnerability.
- Bioequivalence Study Costs:FDA requirements for extended-release generic approval demand expensive pharmacokinetic bridging studies that deter mid-scale entrants.
- Biologic Substitution Threat:Long-acting monoclonal antibodies and gene therapies displace small-molecule controlled-release products in oncology and immunology.
Strategic Opportunities
- India's CDSCO Fast-Track:India's streamlined approval for novel drug delivery systems offers early-mover positioning in a price-sensitive, volume-driven market.
- Oncology Nanoparticle Convergence:Combining lipid-based carriers with immune-modulating payloads opens precision-targeting applications in solid tumors.
- Direct-to-Specialist Distribution:Bypassing wholesale channels to supply CNS-focused clinics directly improves margin capture for depot antipsychotics.
Industry Challenges
- Formulation Scientist Scarcity:The specialized expertise required for polymeric matrix design and dissolution modeling outpaces academic pipeline output.
- Multi-Regional Dissolution Harmonization:Divergent FDA, EMA, and ICH pharmacopeial standards for in-vitro testing force redundant validation programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Controlled Release Drug Delivery Market |
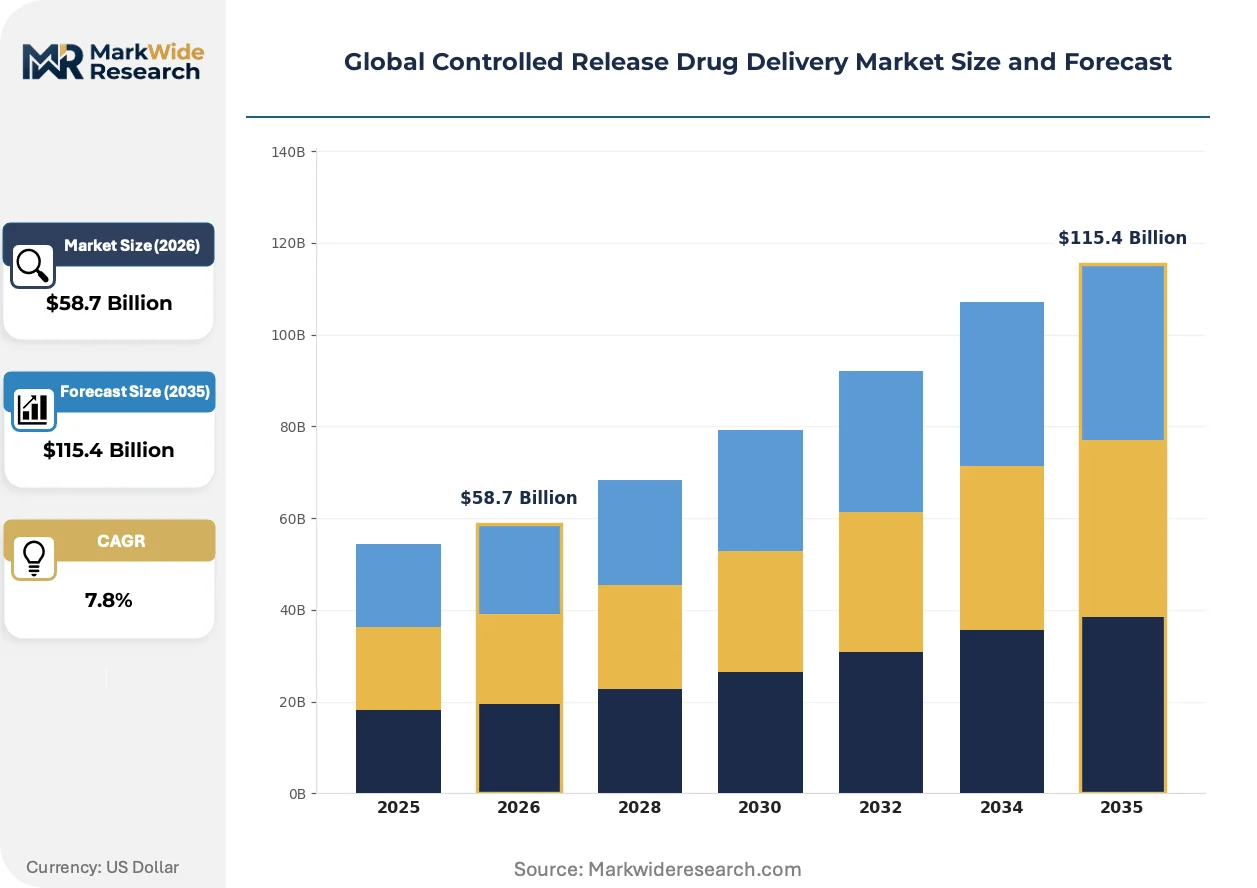
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $115.4 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral, Transdermal, Injectable, Implantable, Pulmonary Technology: Polymeric, Liposomal, Nanoparticle, Biodegradable, Hydrogel Therapy Area: Oncology, Cardiovascular, Neurology, Endocrinology, Infectious Diseases End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Manufacturing, Clinical Trials |
| Companies Covered | Johnson & Johnson, Merck & Co., Pfizer, Novartis, AbbVie, Alkermes, Teva Pharmaceutical Industries, GlaxoSmithKline, AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Controlled Release Drug Delivery Market Shifts & Advancements
Delivery platform convergence is compressing the gap between chronic therapy management and acute intervention, with formulation science now determining competitive differentiation as much as molecular innovation.
Implantable osmotic pump technology is unifying sustained drug release with real-time biosensing capabilities. Cardiology and endocrinology practices in the United States are piloting these integrated systems for glucose-responsive insulin delivery and heart failure monitoring. The technology is unifying therapeutic delivery with diagnostic feedback, collapsing the traditional separation between drug and device revenue streams.
REACH regulation amendments in Europe are mandating biodegradable polymer certification for implantable medical devices. Manufacturers must now document complete degradation pathways and metabolic byproduct safety profiles before CE marking approval. Depot formulations for contraception and hormone replacement face the steepest compliance curves, with reformulation timelines extending eighteen to twenty-four months.
Integrated delivery networks now specify outcome-based contracts that tie formulary placement to adherence metrics and hospitalization reduction. Specialty pharmacy channels are displacing traditional wholesale distribution for high-value implantable systems. This restructuring is most visible in United States oncology and CNS therapy areas, where pharmacy benefit managers negotiate total-cost-of-care arrangements directly with manufacturers.
Global Controlled Release Drug Delivery Market Segmentation
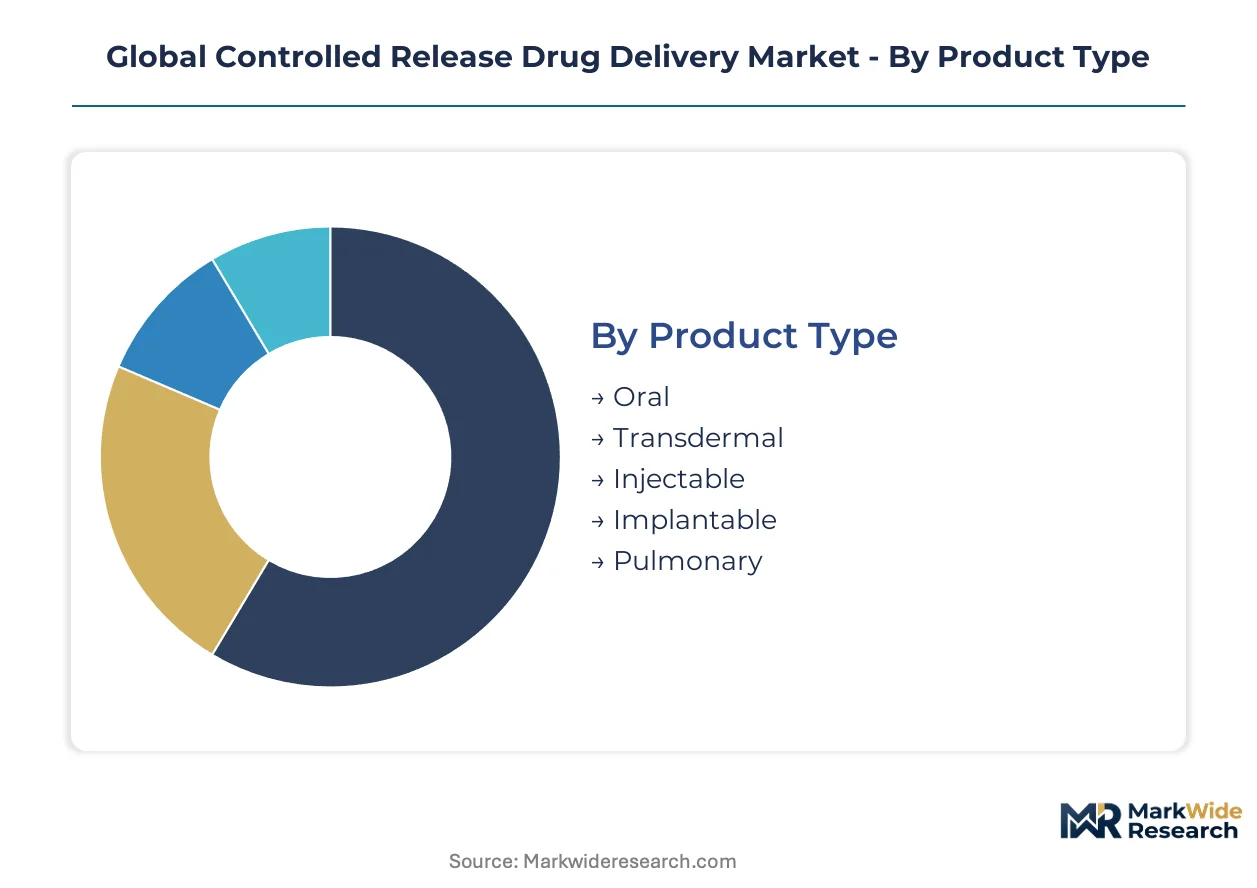
Controlled release drug delivery segments diverge sharply between high-volume oral platforms and premium implantable systems. Technology choices determine manufacturing complexity, regulatory pathway length, and reimbursement positioning across therapy areas.
Product Type:
Oral formulations dominate unit volumes while implantable systems capture margin concentration in chronic therapy management.
- Oral:Matrix tablets and osmotic pump capsules utilize hydroxypropyl methylcellulose and polyethylene oxide to achieve zero-order release kinetics. Demand clusters in Germany and Japan for hypertension and diabetes maintenance where elderly populations prioritize dosing convenience.
- Injectable:Depot suspensions and microsphere formulations enable monthly to quarterly dosing for antipsychotics and hormonal therapies. Biotechnology firms in the United States drive procurement for long-acting contraceptives and CNS applications where adherence gaps inflate healthcare costs.
- Transdermal:Adhesive patches deliver nicotine, opioids, and hormones through stratum corneum penetration enhancers.
- Implantable:Subcutaneous rods and intrauterine systems provide multi-year release for contraception and testosterone replacement.
- Pulmonary:Dry powder inhalers and nebulized formulations target local respiratory action with limited systemic exposure.
Mature deployment sits with Oral. Newer deployment is concentrated in Implantable.
Technology:
Platform selection determines scalability barriers and intellectual property defensibility across development pipelines.
- Polymeric:PLGA, PLA, and polycaprolactone matrices degrade through hydrolysis to enable tunable release profiles spanning weeks to months. The FDA's bioequivalence standards for extended-release generics validate this technology's manufacturing reproducibility.
- Nanoparticle:Lipid-polymer hybrid carriers and solid lipid nanoparticles achieve tumor-targeted accumulation through enhanced permeability and retention effects. EMA's quality guidelines for nanomedicines are accelerating clinical translation in European oncology pipelines.
- Liposomal:Phospholipid bilayers encapsulate hydrophilic and hydrophobic payloads for intravenous administration.
- Biodegradable:Natural polymers including chitosan and alginate address sustainability mandates under REACH amendments.
- Hydrogel:Three-dimensional polymer networks respond to pH, temperature, or glucose concentration for stimulus-responsive release.
Established manufacturing infrastructure supports Polymeric. Steepest expansion trajectory belongs to Nanoparticle.
Therapy Area:
Clinical unmet need and reimbursement generosity determine which disease categories absorb premium delivery technologies.
- Oncology:Sustained-release formulations reduce chemotherapy toxicity through tumor-localized concentration and systemic exposure minimization. Japan's PMDA Sakigake designation accelerates approval for novel depot chemotherapeutics addressing pancreatic and liver malignancies.
- Neurology:Long-acting injectable antipsychotics and depot formulations for Parkinson's disease address adherence failures that drive hospitalization. United States specialty clinics specify outcome-based contracts tying formulary placement to reduced emergency department visits.
- Cardiovascular:Osmotic pump tablets maintain consistent antihypertensive plasma levels to prevent stroke and myocardial infarction.
- Endocrinology:Glucose-responsive insulin delivery systems integrate biosensing with therapeutic release.
- Infectious Diseases:Long-acting antiretroviral injectables transform HIV prevention and treatment paradigms.
Volume concentration rests with Cardiovascular. Margin capture concentrates in Oncology.
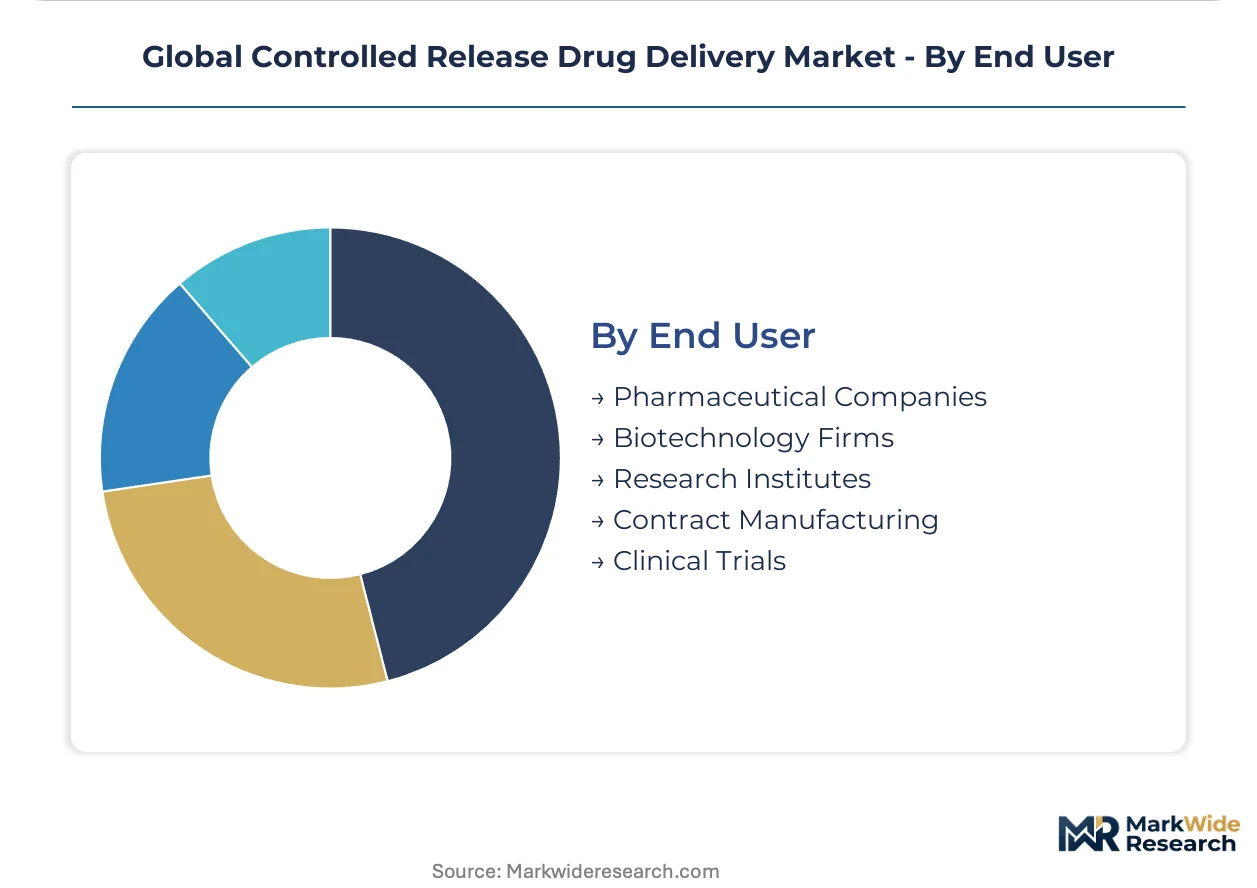
End User:
Customer sophistication and internal manufacturing capabilities determine outsourcing intensity for formulation development.
- Pharmaceutical Companies:Large-cap developers leverage controlled-release platforms to extend patent protection and differentiate against generic competition. Consolidating hospital group purchasing organizations in the United States force these firms to restructure commercial strategies around integrated delivery networks.
- Contract Manufacturing:CDMOs specializing in polymeric extrusion and microsphere production absorb capacity constraints from clients lacking GMP-compliant depot manufacturing. India's CDSCO fast-track approvals attract these organizations to establish regional technical centers.
- Biotechnology Firms:Venture-backed developers outsource formulation science to accelerate proof-of-concept timelines.
- Research Institutes:Academic centers advance mechanistic understanding of release kinetics and degradation pathways.
- Clinical Trials:CROs manage comparator sourcing and bioequivalence study execution for generic submissions.
Direct procurement dominates at Pharmaceutical Companies. Outsourcing growth centers on Contract Manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and chronic disease prevalence concentrate demand in the United States, Germany, and Japan. Specialty clinics and integrated delivery networks in these markets absorb the majority of premium implantable systems.
United States
Integrated delivery networks now specify outcome-based contracts tying formulary placement to adherence metrics and reduced hospitalization. The FDA maintains stringent bioequivalence standards for extended-release generics that compress approval timelines for complex platforms. Greater Boston and Research Triangle Park host concentrated formulation science capabilities serving CNS and oncology applications.
Germany
Aging demographics expand addressable patient pools for monthly and quarterly dosing regimens in hypertension and diabetes maintenance. REACH regulation amendments mandate biodegradable polymer certification for implantable medical devices, extending reformulation timelines. The Rhine-Main cluster anchors polymeric extrusion manufacturing serving depot contraception and hormone replacement therapies.
Japan
PMDA's Sakigake designation accelerates commercialization timelines for first-in-class depot formulations addressing pancreatic and liver malignancies. The national pharmaceutical regulator evaluates controlled-release submissions through priority review pathways for novel delivery mechanisms. The Kansai corridor concentrates microsphere production infrastructure for long-acting antipsychotics.
India
CDSCO fast-track approvals for novel drug delivery systems attract contract manufacturing organizations establishing regional technical centers. The country's national pharmaceutical regulator streamlines pathways for complex generics and sustained-release platforms. Hyderabad and Ahmedabad host expanding GMP-compliant depot manufacturing serving domestic and export markets.
China
NMPA reform of drug review procedures accelerates controlled-release generic approvals amid expanding chronic disease burden. The national medical products administration harmonizes quality guidelines with ICH standards for modified-release submissions. The Yangtze River Delta concentrates lipid-based nanoparticle development for oncology-targeted delivery systems.
Global Controlled Release Drug Delivery Market Competitive Landscape
United States producers anchor one tier; European specialists hold differentiated positions in depot polymer technologies. The vendor base segments across large-cap pharmaceutical developers, biotechnology-focused formulation specialists, and contract manufacturing organizations absorbing capacity constraints. Three archetypes dominate: scale-driven integrated networks, technology-anchored depot specialists, and regional CDMOs serving price-sensitive markets. M&A activity concentrates on polymer platform acquisitions and geographic expansion into Indian regulatory fast-tracks.
Among United States-based developers, Pfizer exemplifies scale-driven network supply while Alkermes occupies a specialist position in CNS depot formulations. Novartis sits within the diversified platform tier competing across multiple controlled-release modalities from oncology to cardiovascular applications. These three anchors represent distinct competitive vectors: manufacturing scale, proprietary polymer technology, and therapeutic breadth.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Merck & Co. |
| Pfizer |
| Novartis |
| AbbVie |
| Alkermes |
| Teva Pharmaceutical Industries |
| GlaxoSmithKline |
| AstraZeneca |
| Others |
Supply & Pricing Matrix
Formulation scientist scarcity in the Rhine-Main cluster and Greater Boston corridor amplifies labor-cost differentials that separate premium implantable systems from commodity oral generics. Polymer synthesis expertise commands compensation premiums that feed directly into three-tier pricing stratification across controlled-release platforms.
Pricing Analysis
Volume concentration in oral matrix tablets compresses margins through scale competition, while implantable depot systems sustain premium positioning via outcome-based contracting with integrated delivery networks. Price differentiation hinges on FDA bioequivalence certification tier and polymer biodegradability grade under REACH amendments. Cost compression in oral generics intensifies as Indian CDSCO fast-track approvals expand supply capacity. Hospital group purchasing organizations exhibit highest price sensitivity, whereas specialty CNS clinics absorb premium pricing for adherence-guaranteed depot formulations.
Supply Chain Analysis
Single-source vulnerability sits with European and Chinese specialty chemical suppliers of PLGA and polycaprolactone polymers essential for depot matrix production. Raw material procurement draws from Germany, China, and India for biodegradable polymer feedstocks, with hydroxypropyl methylcellulose and polyethylene oxide anchoring oral formulation supply. Tariff exposure on Chinese chemical inputs threatens margin stability for microsphere manufacturers. Distribution runs through consolidating hospital group purchasing organizations in the United States and specialty pharmacy channels displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The controlled release drug delivery market sits in a technology-transition phase where nanoparticle platforms displace legacy polymeric matrices in oncology applications. Lipid-polymer hybrid carriers now command development priority over conventional depot formulations.
For Market Incumbents: To counter biologic substitution threats from long-acting monoclonal antibodies, Pfizer-scale manufacturers should deepen backward integration into polymer synthesis capacity in Germany's REACH-compliant chemical corridor. Alkermes-type specialists must defend CNS depot positioning through proprietary polymer patent extensions and direct-to-specialist distribution channel control bypassing wholesale intermediaries.
For New Entrants and Emerging Players: Capture India's CDSCO fast-track pathway for novel drug delivery systems before incumbent contract manufacturing organizations consolidate regional technical centers. Target oncology nanoparticle convergence applications where EMA quality guidelines accelerate clinical translation and formulation expertise scarcity deters large-cap pharmaceutical developers from rapid response.
For Investors and Strategic Acquirers: The window for entry favors polymer platform specialists with biodegradable certification documentation ahead of REACH amendment deadlines. Long-term viability centers on acquisition targets possessing Sakigake-designated depot formulations in Japan and established GMP-compliant microsphere infrastructure. Watch FDA bioequivalence study backlog clearance rates as the inflection signal for generic extended-release market entry velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Polymer Certification | REACH amendment compliance secures CE marking for implantable depot systems in European markets. |
| Sakigake Designation Pursuit | PMDA priority review accelerates commercialization timelines for novel oncology depot formulations. |
| Direct-to-Specialist Distribution | Bypassing wholesale channels improves margin capture for CNS-focused long-acting injectables. |
| CDSCO Fast-Track Establishment | Regional technical centers in Hyderabad and Ahmedabad capture price-sensitive volume markets. |
| Outcome-Based Contracting | Integrated delivery network formulary placement ties to adherence metrics and hospitalization reduction. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this controlled release drug delivery market assessment. Primary interviews with formulation science directors, regulatory affairs leads at depot specialists, hospital group purchasing organization procurement managers, and specialty pharmacy channel heads combined with FDA bioequivalence submission databases, EMA quality guideline documents, and PMDA Sakigake designation records. Bottom-up polymer platform demand modeling and top-down chronic disease prevalence projections enabled triangulation across data sources.
Granularity-level modeling operated at technology-platform-by-therapy-area intersection, with polymeric, nanoparticle, and liposomal carriers crossed against oncology, neurology, and cardiovascular applications across the analysis window. Administration route segmentation separated oral, injectable, and implantable delivery systems. CAGR derivation incorporated patient population aging trajectories, regulatory approval velocity by jurisdiction, and hospital procurement consolidation patterns. Forecast inputs included bioequivalence study completion rates and biodegradable polymer supply expansion timelines.
The model holds under stable regulatory harmonization between FDA, EMA, and ICH pharmacopeial standards; deviation in dissolution testing guideline divergence would shift multi-regional commercialization feasibility materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Cough Suppressant Drugs Market
Pharmaceuticals
Mexico Diabetes Drugs Market
Pharmaceuticals
Hydroxychloroquine Market
Pharmaceuticals
Flavors Into Over-The-Counter (OTC) Pharmaceuticals Market
Pharmaceuticals
Lignocaine/ Lidocaine Market
Pharmaceuticals
Global Orally Disintegrating Tablet Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Europe Heparin Market
Pharmaceuticals
Global Bacterial Vaccines Market
Pharmaceuticals
Japan Pharmaceutical Market
Pharmaceuticals
Global Dengue Vaccine Market
Pharmaceuticals
Global Chemotherapy-Induced Nausea and Vomiting (CINV) Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Europe Diabetes Drugs Market