
 Global Dementia Drugs Market | 2026-2036
Global Dementia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dementia Drugs Market Foresight
ICH E6 Good Clinical Practice certification is reorganizing which developers can advance late-stage dementia candidates into pivotal trials. Eli Lilly and Company anchors its position through deep vertical integration into amyloid antibody manufacturing. Biogen specializes in neurology portfolio concentration that sustains its relevance despite past regulatory setbacks. Eisai Co., Ltd. leverages its co-development alliance structure to extend commercial reach across multiple geographies simultaneously.
Dementia drugs comprise pharmaceutical agents designed to modulate neurotransmitter activity, slow neurodegenerative progression, or modify underlying disease pathology through monoclonal antibodies, small molecules, and natural extracts administered via oral or parenteral routes. These therapeutics target cognitive decline, behavioral symptoms, and functional impairment in patients with progressive neurodegenerative disorders. Cholinesterase Inhibitors occupy the largest installed base due to decades of clinical familiarity and generic availability, while NMDA Antagonists retain steady utilization in moderate-to-severe cases. Combination Drugs represent the fastest-expanding margin pool as physicians seek synergistic efficacy profiles and payers negotiate outcomes-based contracts.
FDA accelerated approval standards, EMA conditional marketing authorization pathways, and Japan PMDA Sakigake designation criteria collectively determine which developers can commercialize novel mechanisms before confirmatory trial completion. These frameworks create divergent market access timelines that shape portfolio prioritization and partnership strategies across the Atlantic and Pacific basins. Stakeholders must monitor biomarker qualification progress and post-approval confirmatory trial designs to anticipate which therapeutic categories will retain reimbursement or face regulatory withdrawal.
Market Dynamics
FDA accelerated approval pathways for amyloid-targeting therapies are compressing development timelines while fragmenting reimbursement negotiations across payers. This regulatory velocity is forcing developers to build confirmatory trial infrastructure before commercial launch.
Growth Catalysts
- PMDA Sakigake designation:Japan's priority review system grants early market access to dementia candidates with breakthrough potential, shortening approval cycles by twelve to eighteen months.
- Specialty neurology clinic expansion:Dedicated Alzheimer's treatment centers in the United States and Germany are expanding patient screening capacity and accelerating enrollment into therapeutic protocols.
- Biomarker qualification progress:CSF amyloid and tau assay standardization is enabling patient stratification that improves trial efficiency and label differentiation.
Market Restraints
- Plasma collection infrastructure scarcity:Amyloid antibody manufacturing requires specialized apheresis networks concentrated in the United States and Switzerland, creating supply bottlenecks.
- ICH E6 GCP certification barriers:Late-stage trial sites in Eastern Europe and Latin America lack the documentation systems required for FDA-submissible data packages.
- Generic cholinesterase inhibitor saturation:Donepezil and rivastigmine commoditization caps pricing power in the largest installed patient base.
Strategic Opportunities
- Combination therapy protocols:Physicians in Germany and Japan are experimenting with cholinesterase-NMDA antagonist sequencing that creates margin expansion beyond monotherapy benchmarks.
- EMA conditional marketing authorization:The pathway allows European commercialization before confirmatory readouts, capturing revenue during trial completion.
- Home infusion services:Parenteral amyloid antibodies are migrating from hospital outpatient departments to specialized home nursing networks in the United States.
Industry Challenges
- Neuroimaging specialist shortage:PET amyloid scan interpretation requires fellowship-trained radiologists concentrated at academic medical centers in Boston, Munich, and Tokyo.
- Post-approval confirmatory trial design:FDA mandates for accelerated approval conversions demand larger patient populations and longer follow-up than original pivotal studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dementia Drugs Market |
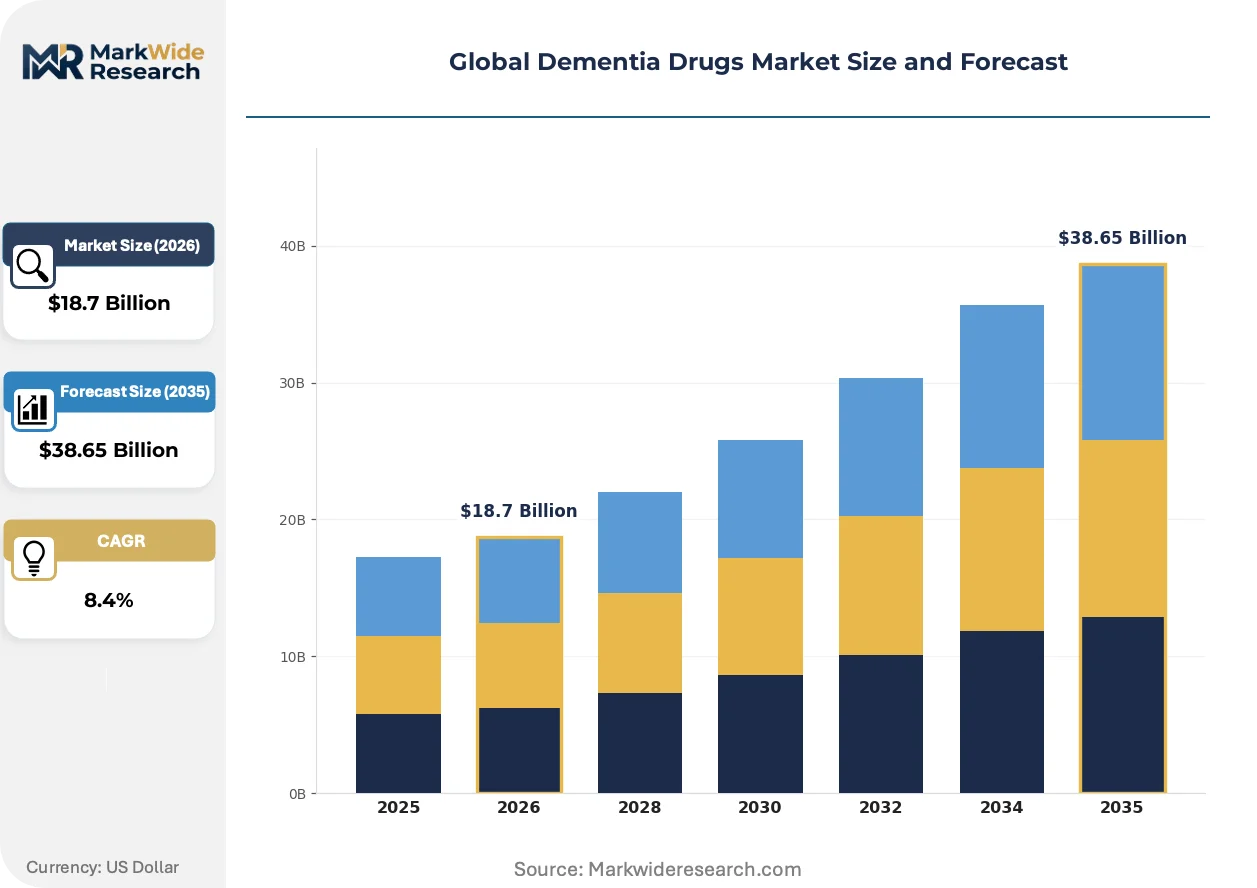
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Cholinesterase Inhibitors, NMDA Antagonists, Combination Drugs, Natural Extracts Therapy Area: Alzheimer’s Disease, Lewy Body Dementia, Frontotemporal Dementia, Vascular Cognitive Impairment Patient Type: Early-stage Diagnosis, Moderate-stage Diagnosis, Late-stage Diagnosis, Mild Cognitive Impairment Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Institutional Dispensaries |
| Companies Covered | Eli Lilly and Company, Eisai Co., Ltd., Novartis AG, Johnson & Johnson, F. Hoffmann-La Roche AG, Biogen, AbbVie Inc., Teva Pharmaceutical Industries, H. Lundbeck A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dementia Drugs Market Shifts & Advancements
Biomarker-driven patient selection is replacing clinical syndrome diagnosis as the entry criterion for premium therapeutic categories. This shift is compressing addressable populations while improving response rates.
Blood-based amyloid assays are fragmenting the diagnostic hierarchy that previously required PET imaging or lumbar puncture. Neurology clinics in the United States and Japan are adopting plasma p-tau217 testing as a screening triage tool. This technology is fragmenting referral patterns between primary care physicians and memory specialists, compressing time-to-treatment initiation.
EMA conditional marketing authorization pathways are creating divergent commercial timelines between European and United States market entry. Developers are prioritizing EMA submissions to capture revenue during FDA confirmatory trial completion. Germany and France are seeing earlier patient access to novel mechanisms than the United States for the first time in two decades.
Integrated care networks are consolidating dementia drug procurement decisions at the system level rather than individual physician discretion. Kaiser Permanente and similar closed systems in California are negotiating outcomes-based contracts that tie reimbursement to cognitive decline velocity metrics. This consolidation is most visible in the United States, where Medicare Advantage penetration exceeds fifty percent in several metropolitan markets.
Global Dementia Drugs Market Segmentation
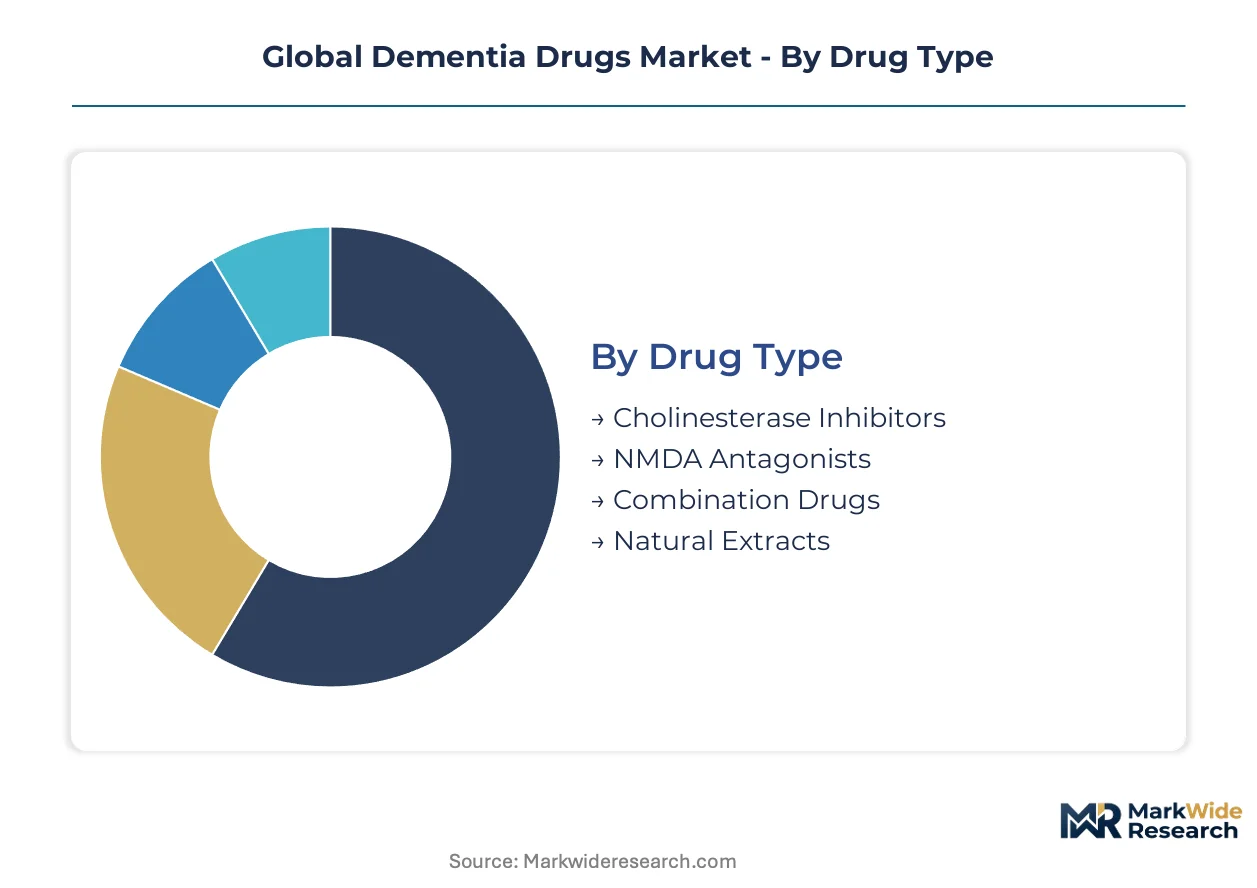
Segmentation in dementia therapeutics determines reimbursement pathways, prescriber access, and manufacturing scale requirements. Each category reflects distinct clinical decision points that shape portfolio allocation across development pipelines.
Drug Type:
Hospital outpatient departments and specialty neurology clinics channel amyloid antibodies, while retail pharmacies handle oral small molecules for chronic maintenance.
- Cholinesterase Inhibitors:Donepezil, rivastigmine, and galantamine modulate acetylcholinesterase activity to temporarily improve synaptic signaling. Demand concentrates in Germany and Japan where generic substitution rates remain moderate and physician familiarity sustains first-line prescribing.
- NMDA Antagonists:Memantine blocks glutamatergic excitotoxicity in moderate-to-severe Alzheimer's cases. Utilization clusters in United States Medicare Advantage networks that have standardized combination protocols with cholinesterase inhibitors.
- Combination Drugs:Fixed-dose memantine-donepezil formulations address adherence gaps in polypharmacy patients. These products flow through institutional dispensaries attached to memory care facilities.
- Natural Extracts:Ginkgo biloba and huperzine A derivatives serve complementary medicine channels in Japan and select European markets with traditional medicine reimbursement carve-outs.
Cholinesterase Inhibitors dominate installed base. Combination Drugs are where expansion concentrates.
Therapy Area:
Clinical trial infrastructure and biomarker qualification progress determine which indications attract development investment versus generic maintenance.
- Alzheimer's Disease:Amyloid-targeting monoclonal antibodies and small molecule BACE inhibitors define the addressable market. FDA accelerated approval pathways have compressed launch timelines for anti-amyloid therapies in the United States.
- Lewy Body Dementia:Cholinesterase inhibitors retain stronger efficacy signals here than in Alzheimer's, creating a distinct prescriber base among movement disorder specialists.
- Frontotemporal Dementia:Tau-directed therapies and symptomatic behavioral agents serve a smaller, genetically stratified population with limited approved options.
- Vascular Cognitive Impairment:Management focuses on cardiovascular risk modification with adjunctive cognitive agents, primarily through hospital pharmacy discharge protocols.
Alzheimer's Disease commands development resources. Lewy Body Dementia offers the steepest expansion trajectory as biomarker differentiation improves.
Patient Type:
Diagnostic technology penetration shapes which patient strata gain access to premium therapeutics versus standard-of-care generics.
- Early-stage Diagnosis:Blood-based amyloid screening and CSF biomarker protocols identify candidates for disease-modifying antibodies. United States specialty clinics in Boston and San Francisco lead enrollment concentration.
- Moderate-stage Diagnosis:Functional decline metrics trigger cholinesterase inhibitor initiation or combination therapy escalation in Germany's integrated care networks.
- Late-stage Diagnosis:Institutional care settings in Japan prioritize behavioral symptom management over cognitive preservation, shifting demand toward NMDA antagonists and psychotropic adjuncts.
- Mild Cognitive Impairment:Pre-dementia stratification trials in the United States and Switzerland are expanding the treatable population ahead of formal Alzheimer's conversion.
Early-stage Diagnosis captures premium pricing. Mild Cognitive Impairment is gaining share fastest as screening technology diffuses.
Distribution Channel:
Cold chain requirements for parenteral biologics and reimbursement prior authorization complexity determine channel economics.
- Hospital Pharmacies:Infusion centers and outpatient departments administer amyloid antibodies requiring refrigeration and specialized nursing oversight. United States academic medical centers anchor this channel.
- Retail Pharmacies:Oral solid formulations for chronic maintenance flow through CVS, Walgreens, and independent networks with 90-day refill programs.
- Online Pharmacies:Mail-order penetration concentrates in United States Medicare Part D plans and Japanese long-term care insurance beneficiaries seeking home delivery.
- Institutional Dispensaries:Skilled nursing facilities and memory care units in Germany manage directly observed therapy for adherence-critical regimens.
Hospital Pharmacies command biologic revenue. Online Pharmacies are climbing the fastest as integrated payers consolidate fulfillment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and Japan's PMDA Sakigake designation are reshaping commercial entry timelines for amyloid-targeting therapies. Germany's EMA conditional marketing authorization framework and Medicare Advantage network consolidation in the United States are creating divergent patient access patterns across major markets.
United States
Medicare Advantage penetration exceeding fifty percent in metropolitan markets is consolidating procurement decisions at the system level. FDA mandates for post-approval confirmatory trials demand larger patient populations than original pivotal studies. Boston and San Francisco anchor specialty clinic concentration for early-stage diagnostic enrollment.
Germany
Integrated care networks are standardizing combination therapy protocols that sequence cholinesterase inhibitors with NMDA antagonists. EMA conditional marketing authorization allows European commercialization before confirmatory readouts. Munich hosts fellowship-trained radiologist clusters essential for PET amyloid scan interpretation.
Japan
PMDA Sakigake designation shortens approval cycles by twelve to eighteen months for breakthrough dementia candidates. Long-term care insurance beneficiaries are driving mail-order pharmacy penetration for chronic maintenance therapies. Tokyo academic medical centers lead biomarker qualification progress for CSF amyloid and tau assay standardization.
Switzerland
Specialized apheresis networks for amyloid antibody manufacturing concentrate plasma collection infrastructure. Swissmedic maintains alignment with EMA pathways while preserving national discretion on novel mechanism evaluation. Basel anchors pharmaceutical manufacturing clusters with cold chain logistics for parenteral biologics.
United Kingdom
NICE technology appraisals are tightening cost-effectiveness thresholds for disease-modifying therapies entering the NHS. London's memory specialist networks are adopting blood-based amyloid assays as screening triage tools. The Southeast corridor concentrates trial site infrastructure for ICH E6 GCP certification.
Global Dementia Drugs Market Competitive Landscape
Listed leaders compete with private specialists across regulatory submission capacity and manufacturing scale. The vendor base concentrates around three tiers: integrated pharmaceutical conglomerates with captive biologics infrastructure, neurology-focused mid-caps with portfolio depth, and regional generics manufacturers serving commoditized symptomatic agents. Strategic archetypes include amyloid antibody specialists, cholinesterase inhibitor incumbents, and combination therapy formulators. Competitive moves center on confirmatory trial infrastructure pre-positioning and outcomes-based contract negotiation with integrated payers.
Within the integrated pharmaceutical tier, Eli Lilly and Company and Novartis AG exemplify archetypes of vertical manufacturing control. Biogen occupies a position representing neurology portfolio concentration despite regulatory headwinds. Eisai Co., Ltd. anchors the co-development alliance structure that extends commercial reach across multiple geographies simultaneously.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Eisai Co., Ltd. |
| Novartis AG |
| Johnson & Johnson |
| F. Hoffmann-La Roche AG |
| Biogen |
| AbbVie Inc. |
| Teva Pharmaceutical Industries |
| H. Lundbeck A/S |
| Others |
Supply & Pricing Matrix
ICH E6 Good Clinical Practice certification gates both manufacturing qualification and price differentiation simultaneously, as sites lacking documentation systems cannot supply FDA-submissible data packages regardless of cost efficiency. This regulatory filter concentrates premium pricing power with certified biologics manufacturers while relegating uncertified producers to commoditized symptomatic agents.
Pricing Analysis
Certification level creates the primary spread between premium amyloid antibodies and economy cholinesterase inhibitors, with FDA-grade manufacturing commanding three-tier pricing structure across premium, standard, and economy levels. Brand premiums attach to disease-modifying mechanisms versus generic donepezil saturation. Pricing pressure stems from Medicare Advantage outcomes-based contracts that tie reimbursement to cognitive decline velocity metrics. Hospital systems exhibit lowest price sensitivity for parenteral biologics, while retail pharmacy channels face intense commoditization.
Supply Chain Analysis
Specialized apheresis networks in the United States and Switzerland anchor plasma collection infrastructure for amyloid antibody production. Manufacturing draws from Chinese active pharmaceutical ingredient suppliers for small molecules and German specialty chemical producers for antibody reagents. Single-source vulnerability concentrates in cold chain logistics for parenteral biologics. Distribution runs through hospital outpatient departments for infusion therapies and retail networks for oral maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
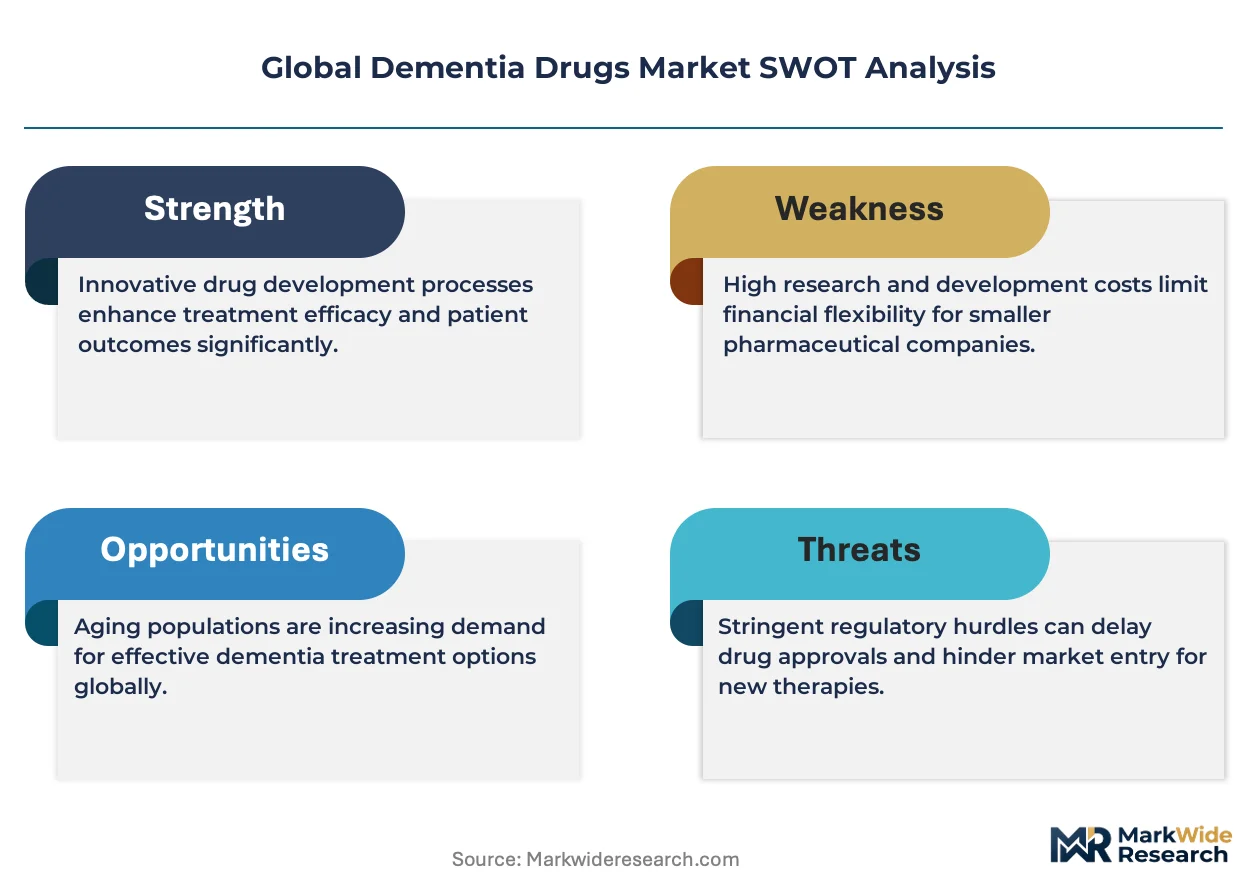
Generic cholinesterase inhibitor substitution threatens incumbent margins as payers mandate therapeutic interchange, forcing developers to defend premium positioning through mechanism differentiation and outcomes-based contracting.
For Market Incumbents: Consolidate manufacturing scale in certified biologics infrastructure to outpace amyloid antibody demand surges. Deepen backward integration into plasma collection networks to secure input supply against apheresis bottlenecks. Lock hospital system partnerships through risk-sharing agreements that demonstrate cognitive preservation value. For New Entrants and Emerging Players: Home infusion services represent the most penetrable service-layer gap where incumbents under-serve parenteral therapy patients. Target United States Medicare Advantage networks seeking to shift administration from academic medical centers to specialized nursing networks. Pursue co-development alliance structures that extend commercial reach without captive manufacturing investment. For Investors and Strategic Acquirers: Carve-out targets emerge from large pharmaceutical conglomerates divesting neurology portfolios to refocus on oncology and immunology. Position for five-to-ten year viability through disease-modifying mechanism exposure versus symptomatic agent commoditization. Watch FDA confirmatory trial readouts as inflection indicators for reimbursement durability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Confirmatory trial infrastructure pre-positioning secures accelerated approval conversion timelines before commercial launch. |
| Regulatory Approval Pathway | EMA conditional marketing authorization captures European revenue during FDA confirmatory completion. |
| Manufacturing Scale-Up | Captive biologics capacity insulates against plasma collection infrastructure scarcity in United States and Switzerland. |
| Pipeline Diversification | Tau-directed therapies for frontotemporal dementia expand addressable population beyond amyloid-focused Alzheimer's. |
| Strategic Partnership | Integrated care network contracts with Kaiser Permanente-type systems lock outcomes-based reimbursement. |
Research Methodology
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation across FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient flow modeling and top-down pharmaceutical revenue triangulation anchored market sizing.
Variance decomposition across treatment line, dosage form, administration route, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from biomarker adoption curves, diagnostic technology penetration rates, and payer policy evolution. Forecast inputs incorporated Medicare Advantage network consolidation velocity and blood-based amyloid assay diffusion patterns.
Material uncertainties — FDA confirmatory trial failures, biomarker qualification reversals, and plasma collection infrastructure disruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory pathway persistence and reimbursement stability. Practitioners should keep alternative scenarios live as payer consolidation and diagnostic technology diffusion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Non-Sterile Compounding Pharmacy Market
Pharmaceuticals
Valganciclovir Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Gemcitabine Hydrochloride Market
Pharmaceuticals
Human Growth Hormone Treatment and Drugs Market
Pharmaceuticals
Intranasal Corticosteroids Market
Pharmaceuticals
Recombinant Plasma Protein Therapeutics Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Vasopressin Antagonists Market
Pharmaceuticals
Marine Derived Pharmaceuticals Market
Pharmaceuticals
Carbetocin Acetate Market
Pharmaceuticals
GCC Generic Injectables Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Intravenous Pegloticase Market