
 Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market | 2026-2036
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market Insights
Cell chemistry standardization is narrowing the technology stack for electric vehicle batteries deployed across the Middle East and Africa. Contemporary Amperex Technology Co. Limited leverages its LFP cell expertise to anchor supply agreements with regional OEMs seeking thermal stability in hot climates. Samsung SDI Co., Ltd. differentiates through high-nickel cathode R&D intensity aimed at premium passenger vehicle segments. BYD Company Limited extends its vertical battery manufacturing model into African markets through modular pack designs suited to variable grid conditions.
A lithium-ion battery for electric vehicle applications stores electrochemical energy through lithium-ion intercalation between a graphite anode and a metal-oxide cathode, typically achieving energy densities of 150–300 Wh/kg depending on chemistry, with primary purpose to power traction motors for zero-emission propulsion. NMC chemistry dominates premium passenger vehicle applications where energy density governs range performance, while LFP cells capture commercial vehicle and two-wheeler segments where cycle life and cost structure outweigh gravimetric targets. Fleet operators represent the fastest-growing end-user channel as municipal bus contracts and last-mile delivery electrification concentrate procurement volume.
Saudi Arabia's SFDA and the UAE's MOHAP coordinate product safety frameworks for imported battery systems, while South Africa's central energy regulator enforces grid-interconnection standards for charging infrastructure. These bodies shape market access through certification requirements that favor suppliers with pre-tested thermal management systems. Stakeholders must monitor evolving local-content thresholds and chemistry-specific recycling mandates as governments link battery procurement to industrial policy objectives.
Market Dynamics
Fleet electrification mandates across the Middle East and Africa are compressing procurement timelines and forcing battery suppliers to pre-certify thermal management systems for desert operating conditions.
Growth Catalysts
- UAE Net-Zero Transport Targets:Federal procurement quotas for electric municipal buses are concentrating demand from Dubai's RTA and Abu Dhabi's ITC into multi-year supply agreements.
- South Africa Renewable Storage Mandates:Grid-interconnection standards for charging infrastructure are creating bundled procurement of batteries with solar generation assets.
- Cell Chemistry Standardization:LFP dominance in commercial vehicle segments is reducing supplier qualification overhead and accelerating fleet operator adoption cycles.
Market Restraints
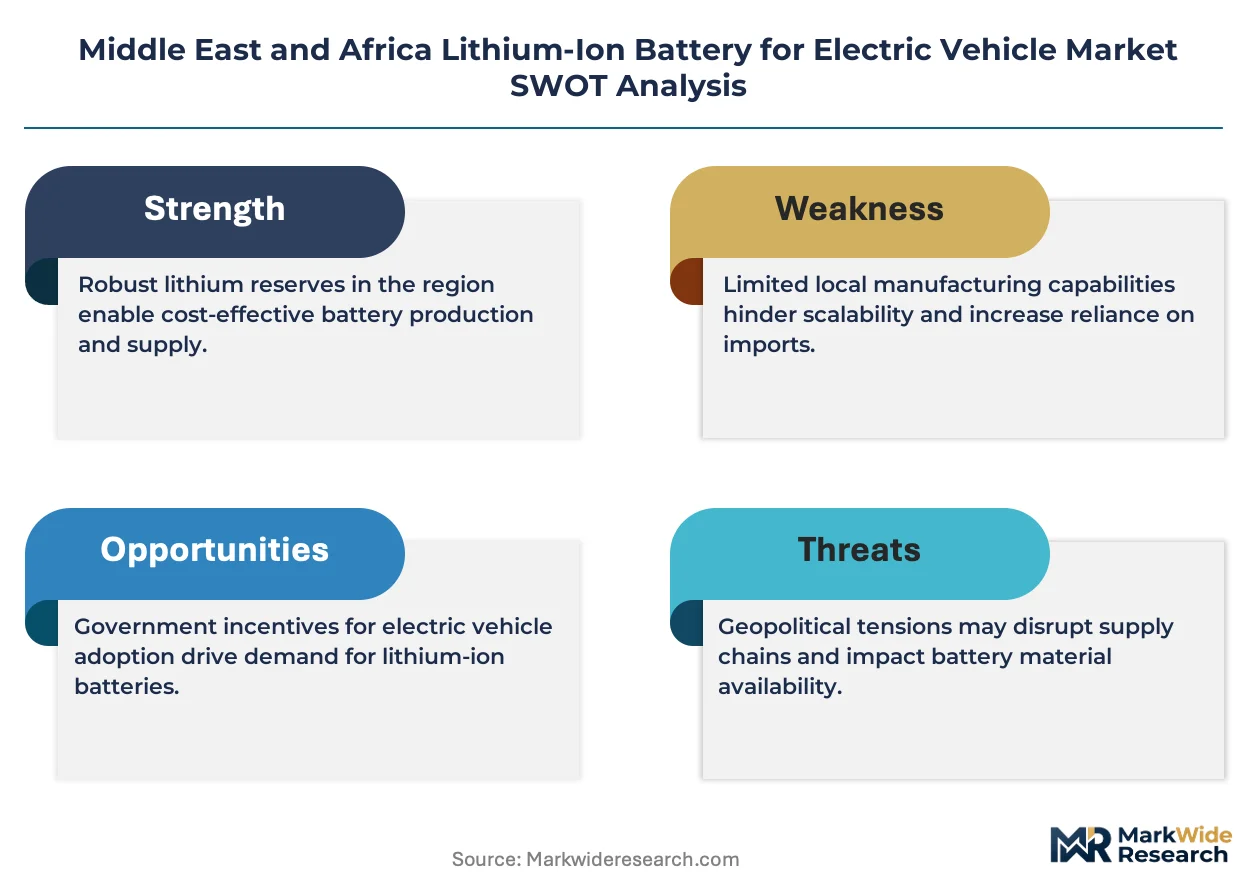
- Lithium Carbonate Price Volatility:Input cost swings from Chilean and Australian concentrate suppliers are compressing cell manufacturer margins and delaying African market entry.
- Single-Source Cathode Supply:NMC precursor dependence on Chinese refining capacity creates concentration risk for premium passenger vehicle programs in Saudi Arabia.
- Thermal Degradation Limits:High-nickel chemistries face accelerated calendar aging in Gulf climates above 45°C ambient, restricting their deployable geography.
Strategic Opportunities
- Second-Life Stationary Storage:Retired EV packs from UAE ride-hail fleets are repurposing into Dubai Industrial City's peak-shaving installations.
- Saudi Local Content Thresholds:SFDA battery certification pathways now reward in-country assembly, incentivizing joint venture structures for cell finishing operations.
- Modular Swappable Architecture:Two-wheeler and three-wheeler segments in Kenya and Nigeria are adopting battery-as-a-service models decoupling vehicle from energy asset ownership.
Industry Challenges
- Thermal Management Engineering Talent:Gulf-based OEMs face acute shortages of battery pack simulation specialists familiar with IEC 62660 abuse testing protocols.
- Multi-Regulator Certification Timelines:Parallel SFDA, MOHAP, and South African Bureau of Standards approval processes extend product launch windows by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market |
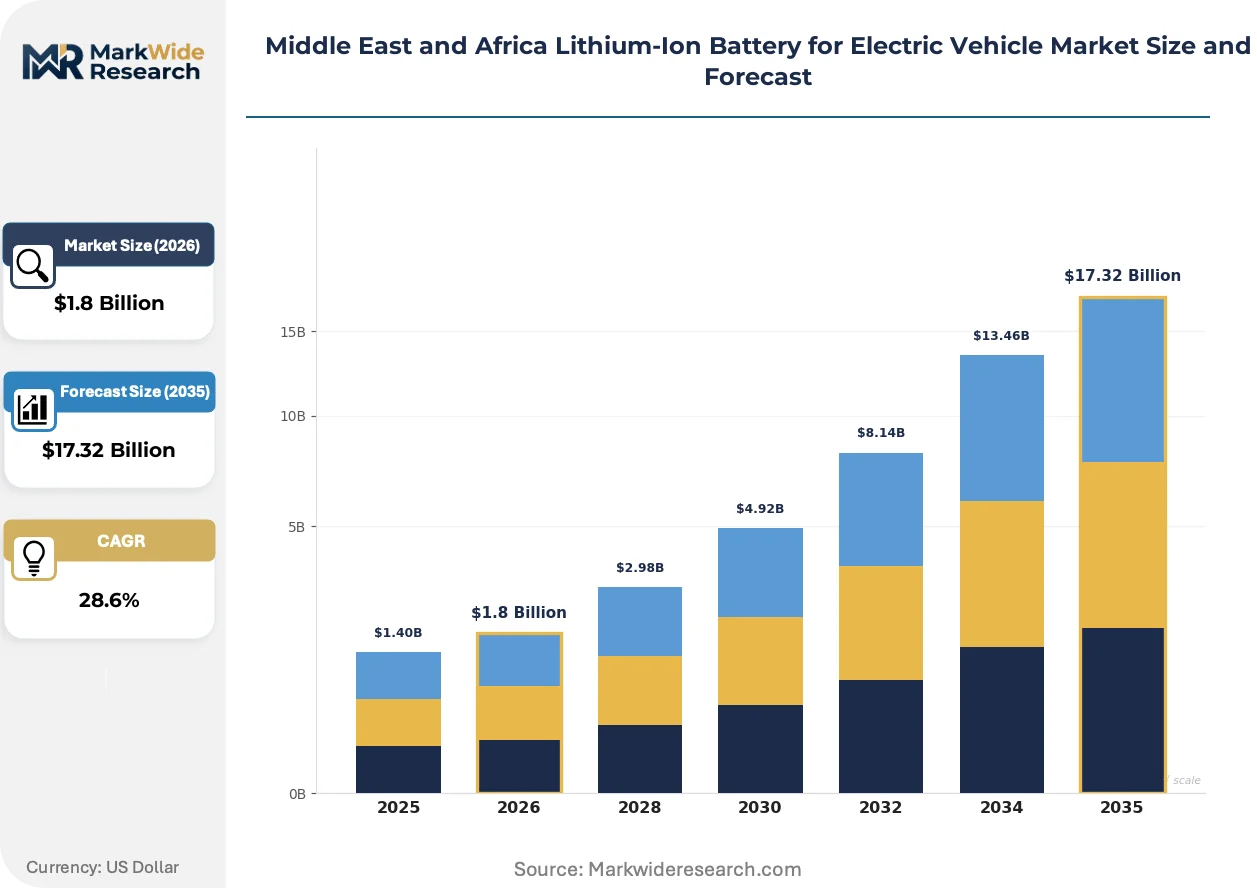
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: LFP, NMC, NCA, LTO End User: OEMs, Fleet Operators, Aftermarket Providers, Charging Infrastructure Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Public Transport Distribution Channel: Direct Sales, Distributors, Online Retail, Dealerships |
| Companies Covered | Panasonic Corporation, Contemporary Amperex Technology Co. Limited, Samsung SDI Co., Ltd., BYD Company Limited, LG Energy Solution Ltd., SK On, Toshiba Corporation, Hitachi Ltd., Saft, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market Trends and Innovations
Desert climate adaptation is driving divergence in battery system architecture between Gulf markets and temperate African economies, with thermal management becoming the primary design variable rather than energy density optimization.
Solid-state electrolyte research is hybridizing with conventional liquid-cell manufacturing lines as Samsung SDI and regional partners pilot sulfide-based prototypes for premium Saudi passenger programs. These systems promise 40% faster charging without thermal runaway risk in 50°C ambient conditions. The hybridizing approach allows incumbent producers to leverage existing electrode coating infrastructure while introducing ceramic separators.
Saudi Arabia's SFDA and UAE's MOHAP have synchronized battery safety frameworks through a mutual recognition agreement on UN 38.3 test reports, eliminating redundant certification for suppliers serving both markets. This regulatory convergence reduces qualification costs by approximately one-third for qualified manufacturers. Premium passenger and commercial bus segments are consolidating procurement around pre-approved supplier lists to exploit this streamlined pathway.
Fleet operators across Dubai, Riyadh, and Johannesburg are consolidating procurement through centralized tender platforms that unbundle battery supply from vehicle OEM agreements. Municipal transit authorities now issue separate RFPs for cell supply, pack assembly, and charging infrastructure, forcing tier-one suppliers to bid as component vendors rather than system integrators. This disintermediation is most advanced in UAE federal contracts, where DEWA's procurement arm coordinates multi-agency battery purchasing.
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market Segmentation
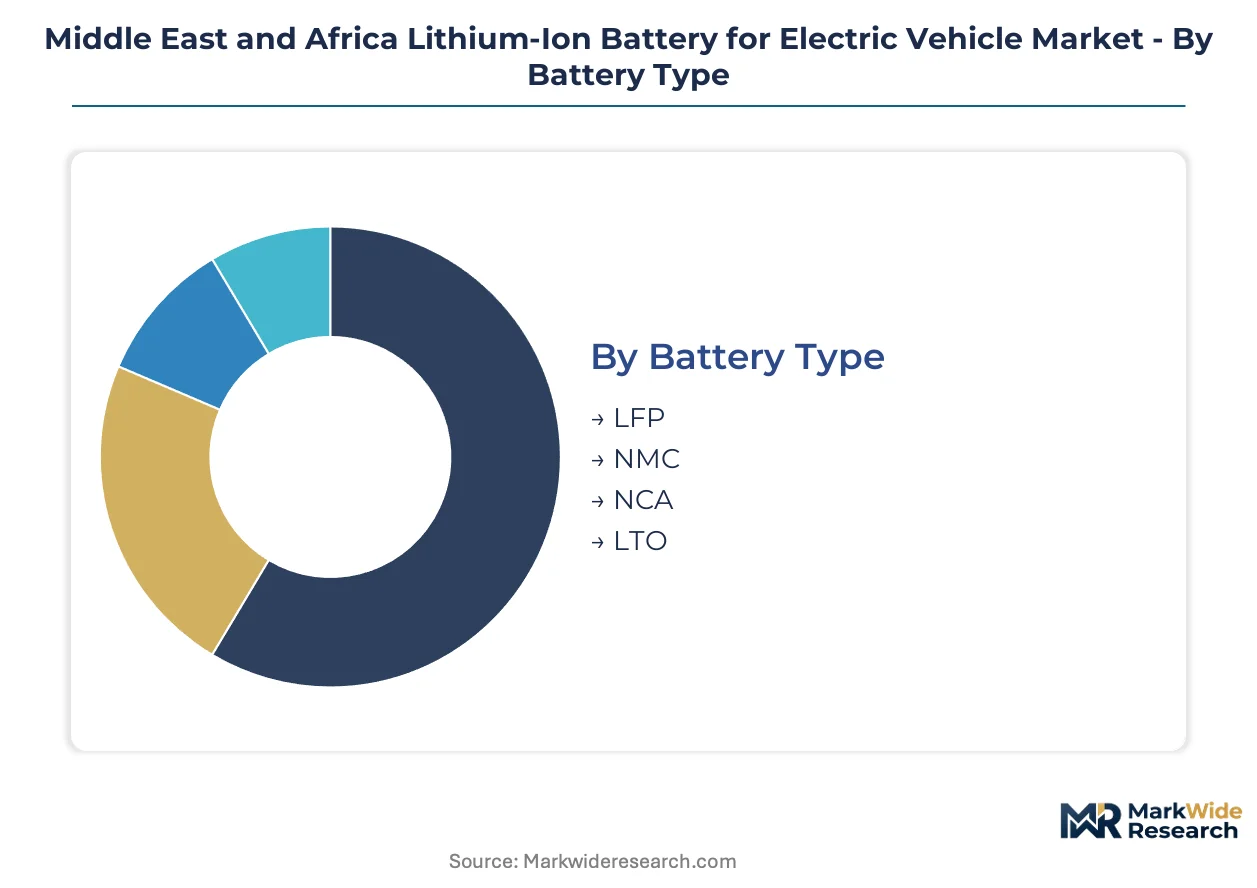
Segmentation in the Middle East and Africa lithium-ion battery for electric vehicle market reveals how thermal constraints, procurement consolidation, and fleet electrification timelines reshape supplier priorities. Understanding these dimensions allows stakeholders to align cell chemistry, channel strategy, and application focus with the region's divergent climate and regulatory conditions.
Battery Type:
Cost tier differentiation across cathode chemistries determines deployable geography and end-use eligibility in desert climates.
- LFP:Lithium iron phosphate cells deliver superior thermal stability and extended cycle life at moderate energy density. Fleet operators in Dubai and Riyadh favor LFP for municipal bus contracts where ambient temperatures exceed 45°C and replacement cycles must stretch across eight to ten years.
- NMC:Nickel-manganese-cobalt formulations achieve higher gravimetric energy density through elevated nickel content. Premium passenger vehicle programs in Saudi Arabia specify NMC for range-competitive sedans despite accelerated calendar aging risks in Gulf summer conditions.
- NCA:Nickel-cobalt-aluminum cathodes occupy niche positioning for high-performance electric SUVs targeting wealthy consumers in UAE urban centers.
- LTO:Lithium-titanate oxide anode systems enable extreme fast-charging for airport shuttle and port logistics fleets in South African commercial hubs.
LFP holds installed capacity. NMC is rotating up the share rankings.
End User:
Customer type concentration is compressing supplier qualification pathways and reshaping contract structures across the value chain.
- Fleet Operators:Municipal transit authorities and logistics consolidators in Johannesburg, Dubai, and Riyadh now issue standalone battery procurement tenders unbundled from vehicle supply agreements. These entities concentrate volume and demand pre-certified thermal management systems for desert operation.
- OEMs:Regional vehicle assemblers in Saudi Arabia and Morocco source cells for domestic pack integration, navigating SFDA certification timelines and local-content thresholds that reward in-country assembly.
- Aftermarket Providers:Independent service networks in Kenya and Nigeria specialize in battery refurbishment and second-life redeployment for commercial vehicle segments.
- Charging Infrastructure:Grid-interconnection developers in South Africa bundle stationary storage with solar generation assets under renewable energy procurement mandates.
Fleet operators command procurement volume. Aftermarket providers are climbing the fastest.
Application:
Application maturity varies sharply between climate-adapted commercial segments and range-sensitive passenger categories.
- Commercial Vehicles:Last-mile delivery vans and urban freight trucks across UAE free zones adopt standardized LFP pack formats with active liquid cooling. Operators prioritize total cost of ownership over energy density, accepting weight penalties for thermal reliability.
- Public Transport:Electric bus deployments in Dubai RTA and Abu Dhabi ITC contracts specify battery-as-a-service arrangements that separate asset ownership from vehicle procurement, reducing municipal capital burden.
- Passenger Vehicles:Private electric car adoption concentrates in Saudi urban centers and UAE expatriate communities, with NMC-dominant chemistries favored for highway range requirements.
- Two-Wheelers:Swappable battery architectures for electric motorcycles and three-wheelers are expanding most quickly in Lagos and Nairobi, where grid reliability concerns favor modular energy asset models.
Commercial vehicles anchor current deployment. Two-wheelers are gaining share fastest.
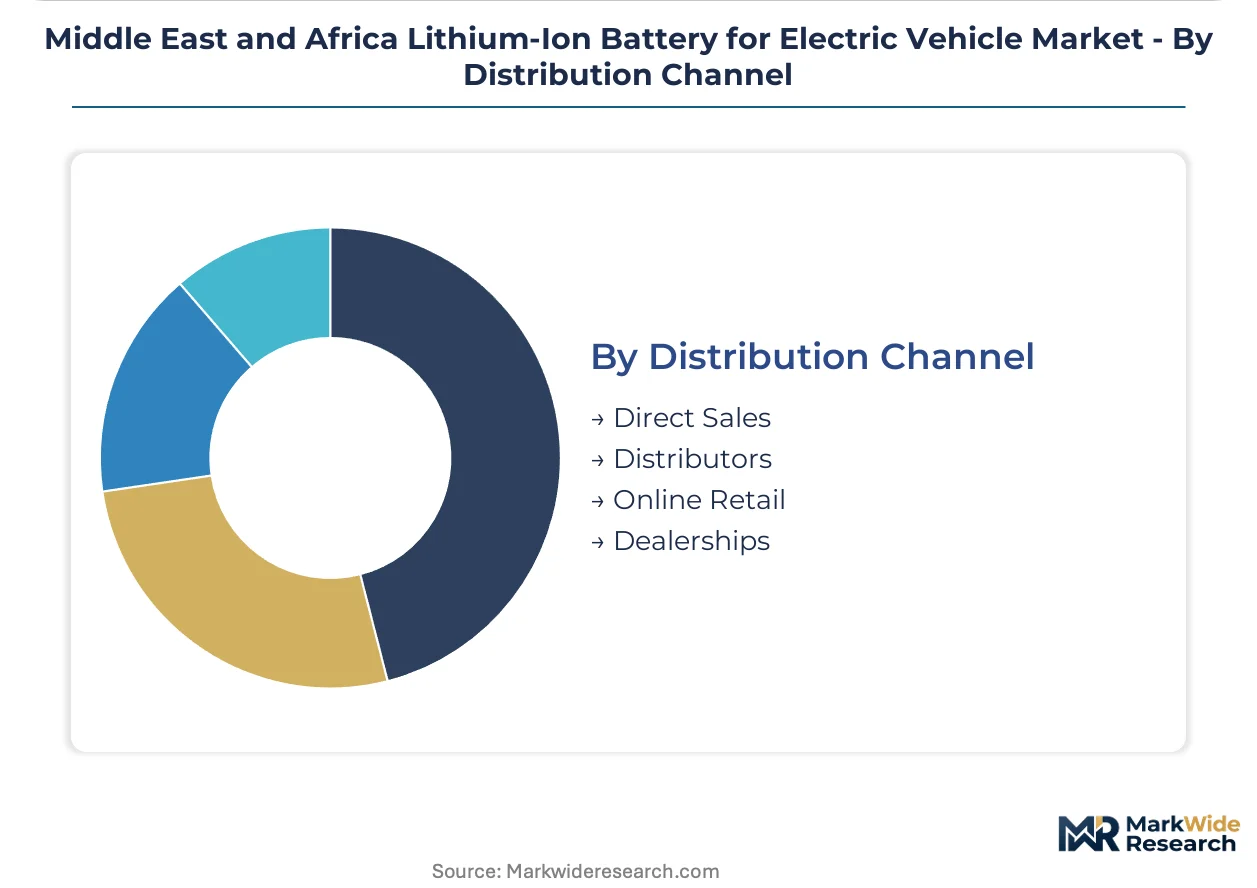
Distribution Channel:
Channel configuration reflects the technical complexity of battery systems and the consolidation of regional procurement platforms.
- Direct Sales:Cell manufacturers negotiate multi-year supply agreements directly with Dubai's DEWA procurement arm and Saudi fleet consolidators, bypassing intermediaries for high-volume municipal contracts.
- Distributors:Authorized technical distributors in South Africa and Morocco manage inventory, certification documentation, and local service networks for mid-scale commercial vehicle operators.
- Dealerships:Vehicle retail networks in UAE and Saudi Arabia bundle battery warranties with passenger vehicle sales, handling warranty claims through OEM-authorized service centers.
- Online Retail:E-commerce platforms serve aftermarket replacement demand for two-wheeler battery packs in Nigerian and Kenyan urban markets, though logistics complexity limits penetration for full EV systems.
Direct sales capture municipal procurement volume. Distributors are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports lithium-ion cells to UAE and Saudi Arabia assembly plants, while South Africa imports packs for domestic commercial vehicle integration. This trade corridor shapes battery procurement patterns across the region.
United Arab Emirates
Dubai's RTA and Abu Dhabi's ITC concentrate municipal bus electrification procurement through centralized tender platforms. MOHAP battery safety frameworks synchronize with Saudi SFDA standards, eliminating redundant certification cycles. Dubai Industrial City hosts pack assembly operations serving Gulf Cooperation Council markets.
Saudi Arabia
Domestic vehicle assemblers source cells for in-country pack integration under local-content thresholds. SFDA certification pathways reward in-country finishing operations, incentivizing joint venture structures. Riyadh anchors premium passenger vehicle programs demanding high-nickel cathode chemistries.
South Africa
Grid-interconnection standards from the central energy regulator bundle stationary storage with solar generation assets. Johannesburg municipal transit authorities issue standalone battery tenders unbundled from vehicle supply agreements. Cape Town logistics hubs adopt LFP packs for last-mile delivery electrification.
Morocco
Regional vehicle assemblers navigate European Union-adjacent export requirements while serving domestic African markets. Casablanca industrial zones concentrate pack integration capacity for commercial vehicle segments. Moroccan automotive clusters leverage proximity to European battery regulations for technology transfer.
Kenya
Two-wheeler and three-wheeler segments adopt battery-as-a-service models decoupling vehicle from energy asset ownership. Nairobi ride-hail fleets pilot swappable architectures addressing grid reliability concerns. Mombasa port logistics corridors test modular pack designs for variable grid conditions.
Middle East and Africa Lithium-Ion Battery for Electric Vehicle Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement consolidation and chemistry differentiation vectors. The market structure tiers around scale-driven cell manufacturers, regional pack integrators, and chemistry-focused R&D houses. Dominant competitive moves include capacity expansion into Gulf assembly zones and strategic partnerships with municipal fleet operators.
Within the scale-driven tier, Contemporary Amperex Technology Co. Limited and BYD Company Limited occupy positions anchored to LFP cell expertise and vertical manufacturing models. Samsung SDI Co., Ltd. exemplifies the high-nickel cathode specialization archetype targeting premium passenger segments. These three entities represent the dominant competitive anchors shaping supply agreement structures across UAE, Saudi Arabia, and South African markets.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Contemporary Amperex Technology Co. Limited |
| Samsung SDI Co., Ltd. |
| BYD Company Limited |
| LG Energy Solution Ltd. |
| SK On |
| Toshiba Corporation |
| Hitachi Ltd. |
| Saft |
| Others |
Pricing and Supply Chain Analysis
Single-source cathode precursor dependence on Chinese refining capacity compresses pricing power for Gulf-based OEMs while simultaneously forcing supply chain restructuring toward in-country finishing operations. This concentration risk widens the spread between NMC premium tiers and LFP standard offerings as qualification timelines and thermal certification costs embed into landed pricing.
Pricing Analysis
Current-generation LFP cells command standard-tier positioning against prior-generation NMC formulations now relegated to economy segments, while next-generation solid-state prototypes anchor premium pricing for Saudi passenger programs. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in certification grade and volume scale, with MOHAP pre-certification adding cost premiums for desert thermal management. Cost compression in standard-tier LFP packs is intensifying because fleet operators consolidate municipal procurement through centralized tender platforms. Fleet operators in Dubai and Riyadh exhibit highest price sensitivity due to total-cost-of-ownership mandates, while premium passenger segments in UAE urban centers show lowest sensitivity to chemistry-driven pricing spreads.
Supply Chain Analysis
Export-control regimes on cathode precursor technologies limit technology transfer for high-nickel formulations into Saudi assembly zones. Cell manufacturing concentrates in China, South Korea, and Japan, with pack integration shifting toward UAE and Saudi Arabia under local-content thresholds. Raw material flows draw from Chilean and Australian lithium concentrate, Indonesian nickel, and Chinese cobalt refining capacity. Single-source vulnerability in cathode precursor supply creates concentration risk for NMC-dependent premium programs. Distribution runs through direct sales channels for municipal procurement and authorized technical distributors for mid-scale commercial operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across procurement consolidation models and chemistry specialization creates entry niches for differentiated players. Fleet operator unbundling of battery supply from vehicle agreements fragments incumbent control.
For Market Incumbents: Harden thermal management certification portfolios against emerging Korean cell manufacturers seeking Gulf market entry through aggressive pricing. Deepen in-country assembly partnerships with Saudi industrial zone operators to satisfy SFDA local-content thresholds. Prioritize LFP capacity expansion in Dubai Industrial City to defend municipal bus procurement share against Chinese vertical manufacturers. For New Entrants and Emerging Players: Modular swappable architectures for two-wheeler segments in Lagos and Nairobi represent the most penetrable entry point given battery-as-a-service model traction and limited incumbent presence. Aftermarket refurbishment networks in Kenya and Nigeria offer second-mover consolidation opportunities. Target technical distributor partnerships in South Africa to bypass direct sales channel barriers for commercial vehicle segments. For Investors and Strategic Acquirers: SFDA-MOHAP mutual recognition agreement on UN 38.3 test reports reshapes the acquisition landscape by reducing qualification costs for dual-market suppliers. Long-term viability centers on pack integrators with established thermal engineering capabilities and pre-certified product portfolios. Watch for municipal tender platform consolidation signals as inflection indicators for scale-driven acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Desert Thermal Certification Investment | MOHAP and SFDA pre-certification unlocks multi-year municipal supply agreements in Gulf markets. |
| Local Content Joint Venture Formation | In-country pack finishing satisfies Saudi industrial policy while reducing tariff exposure on imported cells. |
| Second-Life Storage Partnership | Retired UAE ride-hail packs redeploy into Dubai Industrial City peak-shaving installations. |
| Swappable Architecture Platform Launch | Battery-as-a-service models in Lagos and Nairobi decouple vehicle from energy asset ownership. |
| High-Nickel Cathode R&D Intensification | Samsung SDI and regional partners pilot sulfide-based prototypes for premium Saudi passenger programs. |
Research Methodology
A standing panel of OEM platform engineers, fleet procurement directors, cell manufacturer sales leads, and regulatory affairs specialists at SFDA and MOHAP provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders against secondary validation from UN 38.3 test report databases, customs trade flows for lithium concentrate, and municipal tender platform disclosures. Bottom-up cell shipment estimates triangulated against top-down vehicle production forecasts.
Scenario-bracketing around lithium carbonate price volatility and thermal degradation limits in Gulf climates bounded the projection range. Segmentation modeling spanned cathode chemistry tiers, end-user procurement channels, application thermal requirements, vehicle class architectures, and regional regulatory clusters. CAGRs derived from volume trajectory analysis across fleet electrification timelines and charging infrastructure buildout schedules. Cell chemistry standardization curves and local-content threshold implementation paced the forecast inputs.
Stress conditions across lithium concentrate supply disruptions, NMC precursor export restrictions, and municipal procurement delay scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts embed assumptions on SFDA certification pathway stability and MOHAP-SFDA regulatory convergence maintenance. Material shifts in Chinese cathode precursor trade policy or Gulf climate adaptation technology breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium Hydroxide Market
Lithium-ion Battery
Asia-Pacific Lithium-Ion Battery Market
Lithium-ion Battery
Global Lithium Mining Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Ultra Low Temperature Lithium Battery Market
Lithium-ion Battery
France SLI Battery Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Taiwan Lithium-Ion Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
United States Battery Cell Market
Lithium-ion Battery
Lithium-Ion Battery Pack for Consumer Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Lithium Battery Pack Market