
 21700 Lithium Battery Sales Market | 2026-2036
21700 Lithium Battery Sales Market Size, Share, and Industry Trends Forecast 2026-2036
21700 Lithium Battery Sales Market Insights
Project finance tied to giga-scale cell manufacturing is tilting competitive access toward capital-intensive producers. Panasonic Group leverages its captive supply agreements with automotive OEMs to sustain volume commitments across multiple continents. Samsung SDI anchors its position through in-house cathode production and stringent Korean KTC certification standards. EVE Energy Co., Ltd competes aggressively on cylindrical cell cost structures while expanding European logistics hubs.
21700 lithium batteries designate cylindrical cells measuring 21 millimeters in diameter and 70 millimeters in length, typically employing nickel-cobalt-aluminum or nickel-manganese-cobalt cathode chemistries with silicon-graphite composite anodes to achieve energy densities exceeding 300 watt-hours per kilogram. These cells primarily serve electric vehicle powertrains and high-drain industrial equipment requiring sustained discharge rates above 10 amperes. The cylindrical format dominates automotive procurement volumes due to superior thermal management and automated assembly compatibility. Energy Storage applications represent the fastest-expanding demand pool as grid-scale integrators specify 21700 cells for modular battery rack architectures.
The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape cell sourcing decisions for suppliers serving European automotive OEMs. China's GB standards and NMPA safety protocols enforce rigorous thermal runaway testing that filters lower-tier manufacturers from qualified supplier lists. The US IRA domestic content bonuses redirect contract flows toward North American cell assembly investments. Stakeholders must monitor how regional compliance fragmentation affects qualification timelines and capital allocation across manufacturing footprints.
Market Dynamics
Electric vehicle OEM procurement is consolidating around 21700 cylindrical formats as thermal management requirements and automated assembly compatibility override legacy pouch cell preferences in powertrain design cycles.
Growth Catalysts
- EU Battery Regulation carbon mandates:Recycled content thresholds and carbon footprint declarations are forcing automotive OEMs to qualify European-sourced 21700 cells, redirecting contract flows toward compliant producers.
- Silicon-graphite anode adoption:Silicon-doped composite anodes are pushing energy densities past 300 watt-hours per kilogram, enabling extended-range electric vehicle platforms without pack volume expansion.
- Jiangsu cathode precursor clustering:China's concentration of nickel-cobalt-manganese precursor production is compressing logistics costs for cylindrical cell manufacturers serving domestic and export markets.
Market Restraints
- Nickel price volatility:Cathode raw material cost swings are compressing margin structures for producers locked into long-term automotive supply agreements with fixed pricing clauses.
- Single-region supply concentration:China's dominance of refined lithium hydroxide and cathode active material production creates geographic vulnerability for cell manufacturers dependent on just-in-time precursor delivery.
- Thermal runaway propagation limits:Cell-to-cell thermal isolation requirements under China's GB standards are adding engineering complexity and material cost to pack integration designs.
Strategic Opportunities
- US IRA domestic content bonuses:North American cell assembly investments are attracting project finance as Treasury Department guidance clarifies qualification thresholds for electric vehicle tax credit stacking.
- Grid-scale energy storage integration:Modular battery rack architectures for utility-scale stationary storage are specifying 21700 cells for standardized containerized deployments.
- Solid-state electrolyte convergence:Hybrid solid-liquid electrolyte formulations paired with cylindrical formats are opening pathways for next-generation safety performance without manufacturing line retooling.
Industry Challenges
- Cell-level traceability system deployment:EU Battery Regulation digital passport requirements and China's NMPA batch tracking mandates are forcing simultaneous multi-standard compliance investments.
- Dry electrode coating scale-up:Solvent-free electrode manufacturing processes promise cost reduction but require capital-intensive pilot-to-production equipment transitions with unproven throughput rates.
- Recycling infrastructure alignment:Closed-loop black mass recovery networks for nickel-cobalt recovery are not yet synchronized with projected end-of-life cell volumes from 2026-2028 production batches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 21700 Lithium Battery Sales Market |
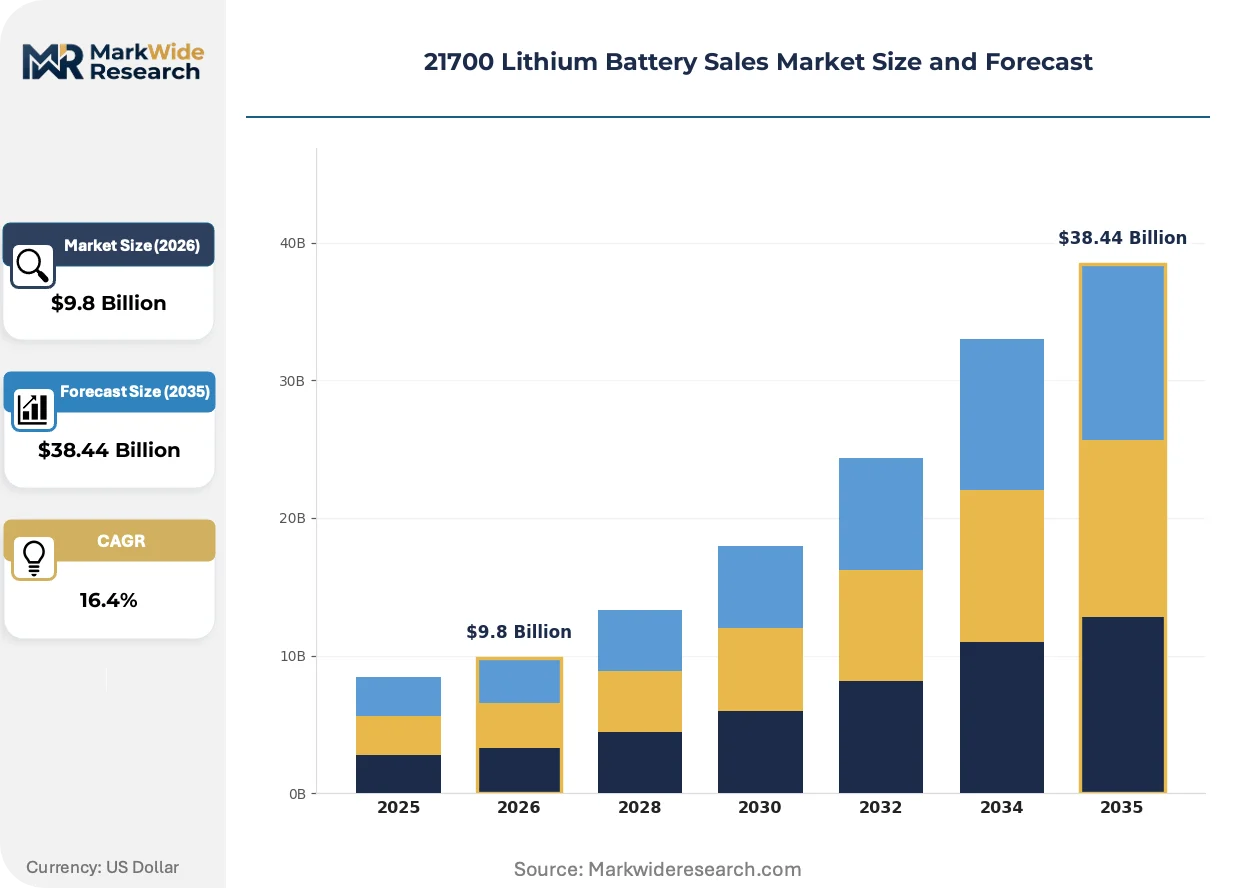
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prismatic, Pouch, Button End User: Consumer Electronics, Automotive, Industrial, Energy Storage Technology: Lithium-Ion, Lithium Polymer, Solid-State, Nickel-Manganese Application: Electric Vehicles, Power Tools, Medical Devices, Renewable Energy |
| Companies Covered | Panasonic Group, LG Chem, Samsung SDI, EVE Energy Co., Ltd, BAK Battery, Tianjin Lishen, Sony Corporation, Hitachi Ltd, Sunpower, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
21700 Lithium Battery Sales Market Trends and Innovations
Advanced manufacturing techniques and regulatory disclosure requirements are compressing development cycles while expanding the addressable application set beyond automotive powertrains into stationary storage and industrial equipment.
Silicon-dominant anode formulations are virtualizing the energy density frontier for cylindrical cells. Automotive OEMs are accelerating qualification timelines for silicon concentrations exceeding 10% by weight. This chemistry transition is virtualizing the competitive boundary between premium and standard cell tiers, forcing incumbent producers to retool coating lines or cede high-margin contract segments.
China's NMPA battery safety certification protocols are tightening thermal runaway testing standards for cell-level submissions. Domestic manufacturers must now demonstrate 30-minute no-fire propagation under nail penetration and overcharge scenarios. European automotive OEMs are responding by demanding equivalent test data from Asian suppliers, effectively exporting Chinese regulatory stringency into global procurement specifications.
Automotive OEMs are consolidating supplier relationships around dual-source strategies with volume guarantees rather than spot-market purchasing. Tier-one cell producers are capturing multi-year offtake agreements with penalty clauses for delivery shortfalls. This behavioral shift is most visible in Germany's automotive corridor, where KBA type-approval timelines incentivize early supplier lock-in to secure homologation slots for new electric vehicle platforms.
21700 Lithium Battery Sales Market Segmentation
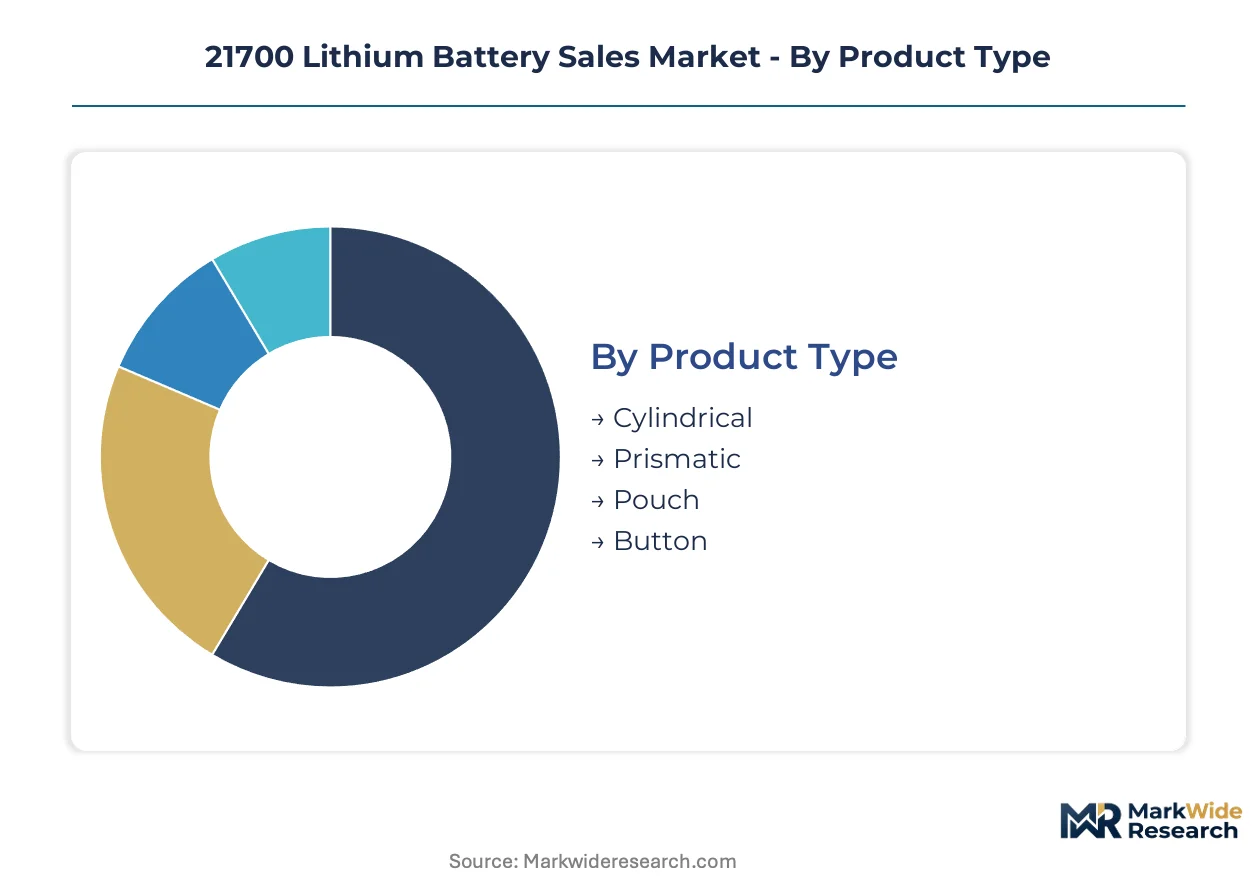
21700 cell procurement patterns diverge sharply across end-use specifications, with automotive powertrains demanding uniform cylindrical formats while stationary storage and industrial applications tolerate greater format flexibility. Segmentation clarity enables suppliers to align capacity investments with qualification timelines and margin structures.
Product Type:
Cell geometry determines thermal management architecture and assembly automation compatibility across the use-case spectrum.
- Cylindrical:The 21mm diameter format enables superior heat dissipation through radial conduction paths and seamless integration with laser welding equipment. Automotive OEMs in Germany's KBA homologation corridor specify cylindrical cells exclusively for powertrain platforms requiring sustained discharge above 10 amperes.
- Prismatic:Flat rectangular formats maximize volumetric packing efficiency in space-constrained battery enclosures. Chinese manufacturers serving domestic electric bus producers favor prismatic cells for their structural rigidity and simplified module assembly.
- Pouch:Flexible laminated aluminum casings offer weight advantages for aerospace and premium consumer electronics applications where gram-level optimization overrides cycle life requirements.
- Button:Compact disc-shaped cells address wearable medical devices and IoT sensors requiring sub-watt-hour energy storage with minimal footprint.
The dominant share belongs to Cylindrical, while Prismatic is closing the gap fastest in heavy-duty commercial vehicle applications.
End User:
Customer archetypes impose distinct certification burdens and contract structures that reshape producer margin profiles.
- Automotive:OEM procurement teams enforce IATF 16949 quality system compliance and demand cell-level traceability from precursor mine to pack assembly. Tier-one suppliers capture multi-year offtake agreements with penalty clauses for delivery shortfalls under Germany's KBA type-approval timelines.
- Energy Storage:Grid-scale integrators specify 21700 cells for modular containerized deployments where standardized rack architectures reduce balance-of-system costs. China's State Grid Corporation drives procurement volumes for utility-scale frequency regulation installations.
- Industrial:Forklift and warehouse automation OEMs prioritize cycle life and opportunity-charging compatibility over energy density metrics.
- Consumer Electronics:Laptop and power tool manufacturers specify cells with accelerated qualification cycles and compressed lead times for seasonal product launches.
Automotive commands the largest revenue pool, though Energy Storage is expanding most quickly as renewable penetration targets escalate across multiple jurisdictions.
Technology:
Cathode and electrolyte chemistry selections determine energy density ceilings and safety certification pathways.
- Lithium-Ion:Nickel-cobalt-aluminum and nickel-manganese-cobalt oxide cathodes paired with silicon-graphite composite anodes deliver energy densities exceeding 300 watt-hours per kilogram. China's NMPA safety protocols enforce 30-minute no-fire propagation standards that filter lower-tier producers from qualified supplier lists.
- Solid-State:Hybrid solid-liquid electrolyte formulations promise enhanced thermal stability without manufacturing line retooling. Korean MFDS certification requirements for medical device batteries are accelerating solid-state pilot production timelines.
- Lithium Polymer:Gel electrolyte systems enable ultra-thin form factors for consumer electronics with moderate discharge rate requirements.
- Nickel-Manganese:Reduced cobalt content addresses raw material cost volatility while maintaining acceptable energy density for mid-range electric vehicle platforms.
Lithium-Ion retains overwhelming volume share, yet Solid-State is gaining share fastest among safety-critical medical and aerospace applications.
Application:
Functional deployment contexts dictate pack integration complexity and service life expectations.
- Electric Vehicles:Battery electric and plug-in hybrid platforms require cells capable of 1,000+ deep discharge cycles with minimal capacity fade. The EU Battery Regulation's carbon footprint declarations are forcing OEMs to requalify cell suppliers against recycled content thresholds.
- Renewable Energy:Solar-plus-storage and wind farm installations demand 6,000+ cycle life with daily charge-discharge cycling. China's Jiangsu manufacturing corridor concentrates production capacity serving domestic photovoltaic integration projects.
- Power Tools:Cordless equipment manufacturers prioritize high discharge rates and mechanical durability over volumetric energy density.
- Medical Devices:Implantable and portable diagnostic equipment requires FDA and EMA biocompatibility certifications with extended shelf stability.
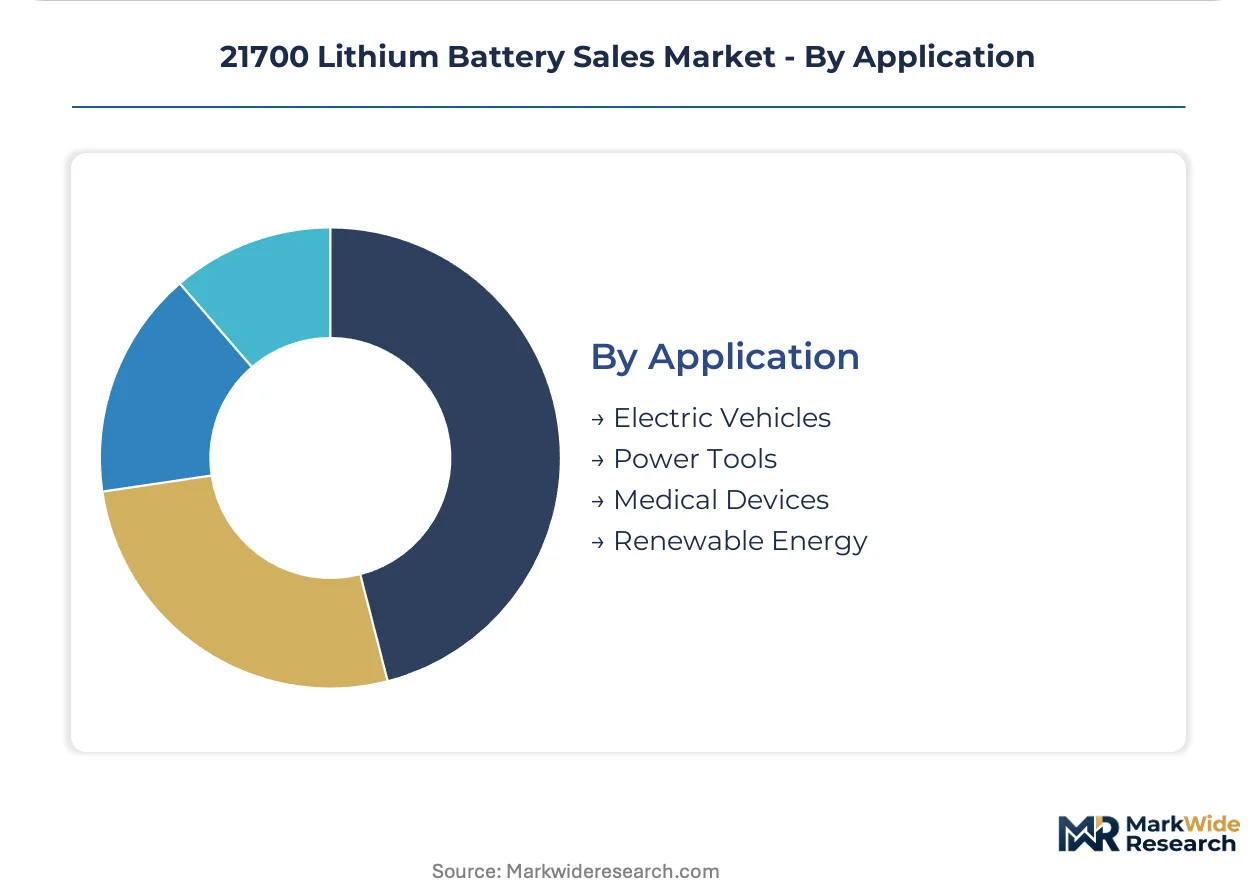
Electric Vehicles holds the dominant position, though Renewable Energy is climbing the fastest as grid-scale procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US IRA domestic content bonuses redirect contract flows toward North American cell assembly investments, while China's NMPA protocols and the EU Battery Regulation create divergent compliance corridors that reshape capital allocation across manufacturing footprints.
China
Jiangsu and Guangdong manufacturing corridors concentrate cathode precursor supply clusters that compress logistics costs for cylindrical cell producers. The NMPA enforces 30-minute no-fire propagation standards under GB safety protocols that filter lower-tier manufacturers from qualified supplier lists. Shenzhen and Dongguan logistics hubs are expanding European export capacity to serve automotive OEM qualification timelines.
United States
Treasury Department guidance on IRA tax credit stacking attracts project finance for giga-scale cell assembly investments. The NHTSA coordinates with EPA on battery safety and end-of-life recycling standards that affect pack integration designs. Michigan and Ohio automotive corridors are securing multi-year offtake agreements with penalty clauses for delivery shortfalls under compressed homologation schedules.
Germany
KBA type-approval timelines incentivize early supplier lock-in to secure homologation slots for new electric vehicle platforms. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape cell sourcing decisions. Bavaria and Baden-Württemberg automotive clusters are consolidating procurement relationships around dual-source strategies with volume guarantees.
South Korea
KTC certification standards anchor supplier qualification for automotive OEMs seeking premium-tier cell supply. The MFDS accelerates solid-state pilot production timelines for medical device battery applications. Seoul and Busan manufacturing bases are leveraging in-house cathode production to sustain margin structures against Chinese cost competition.
Japan
METI industrial policy supports next-generation battery chemistry development through coordinated R&D consortia. JIS standards govern cell quality systems for domestic automotive and industrial equipment OEMs. Nagoya and Osaka industrial corridors are specializing in silicon-dominant anode formulations for premium electric vehicle platforms.
21700 Lithium Battery Sales Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply tiers. The market structure consolidates around capital-intensive producers with captive automotive relationships and fragmented specialist manufacturers serving industrial and consumer segments. Three archetypes dominate: integrated chemical-to-cell producers, cylindrical format specialists, and diversified electronics conglomerates with battery divisions. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with producers securing multi-year offtake agreements to defend position.
Within the integrated producer tier, Panasonic Group and LG Chem exemplify archetypes combining captive supply agreements with multi-continental volume commitments. Samsung SDI occupies a position emphasizing in-house material production and stringent certification compliance. Among cylindrical specialists, EVE Energy Co., Ltd represents aggressive cost-structure competition paired with European logistics expansion. These three anchors illustrate how qualification timelines and regional regulatory fragmentation reward distinct strategic postures.
| Leading Market Players |
|---|
| Panasonic Group |
| LG Chem |
| Samsung SDI |
| EVE Energy Co., Ltd |
| BAK Battery |
| Tianjin Lishen |
| Sony Corporation |
| Hitachi Ltd |
| Sunpower |
| Others |
Pricing and Supply Chain Analysis
China's Jiangsu cathode precursor clustering funnels pricing power toward integrated chemical-to-cell producers while compressing margin pools for assembly-only manufacturers dependent on spot-market nickel sulfate and lithium hydroxide procurement. Automotive OEM multi-year offtake agreements with fixed pricing clauses lock in volume commitments but expose tier-two suppliers to raw material cost swings that tier-one incumbents absorb through backward integration into cathode active material production.
Pricing Analysis
Certification level creates the primary spread across automotive procurement tiers, with NMPA-compliant cells commanding substantial premia over uncertified alternatives in Chinese domestic supply. Three-tier pricing structure across premium, standard, and economy levels reflects IATF 16949 quality system compliance, KBA homologation status, and silicon-graphite anode concentration. Cost compression in standard-tier cylindrical cells is intensifying because Korean and Japanese producers are expanding European logistics hubs to capture EU Battery Regulation compliance bonuses. Grid-scale energy storage integrators exhibit highest price sensitivity due to standardized rack architecture commoditization, while German automotive OEMs prioritize qualification timelines over unit economics.
Supply Chain Analysis
Extended payment terms from automotive OEMs and supply-chain finance facilities are reshaping working capital requirements for cathode precursor suppliers serving cylindrical cell manufacturers. Raw material sourcing draws from Indonesian nickel laterite, Chilean lithium brine, and Australian spodumene concentrate, with refined processing concentrated in China's Fujian and Sichuan provinces. Single-source vulnerability pervades high-purity nickel sulfate supply, where Indonesian HPAL output expansion lags cell demand growth. Distribution runs through Shenzhen and Dongguan logistics hubs for European export, with North American volumes increasingly served by Michigan and Ohio assembly investments qualifying for IRA domestic content bonuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified cell supply is tightening faster than giga-scale capacity expansion, creating acute scarcity around NMPA certification expertise and silicon-anode coating capabilities that determines supplier list access. Incumbents holding captive automotive relationships must now defend against integrated chemical producers backward integrating into cell assembly.
For Market Incumbents: Insulate automotive offtake agreements through multi-year volume guarantees with penalty clauses for delivery shortfalls, while accelerating in-house cathode active material production to offset nickel price volatility. Samsung SDI's Korean KTC certification anchor and Panasonic's captive supply agreements illustrate how qualification depth and geographic diversification defend against Chinese cost competitors expanding European logistics footprints. Priority investment in dry electrode coating pilot lines preserves margin structures against solvent-based manufacturing cost escalation. For New Entrants and Emerging Players: Build out modular battery rack architectures for utility-scale energy storage applications, where standardized containerized deployments tolerate new supplier qualification timelines absent KBA homologation urgency. Grid-scale integrators in China's State Grid Corporation procurement corridor and European renewable penetration markets present the most penetrable demand pool. Go-to-market positioning around silicon-dominant anode concentrations exceeding 10% by weight enables premium-tier pricing without direct competition against established automotive supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward integrated chemical-to-cell producers with NMPA certification capabilities and existing cathode precursor supply relationships, as these assets compound scarcity value across the analysis window. Acquisition target archetypes include cylindrical specialists with European logistics infrastructure and silicon-anode coating expertise. The signal to watch is Treasury Department IRA guidance clarification on domestic content bonus thresholds, which would redirect contract flows and revalue North American assembly investments.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Graphite Anode Scale-Up | Energy density exceeding 300 watt-hours per kilogram enables extended-range electric vehicle platforms without pack redesign. |
| European Logistics Hub Expansion | Shenzhen and Dongguan export capacity growth accelerates qualification timelines for EU Battery Regulation compliance. |
| Dry Electrode Coating Transition | Solvent-free manufacturing reduces operational expenditure but requires capital-intensive pilot-to-production equipment transitions. |
| Cathode Precursor Backward Integration | In-house nickel-cobalt-manganese production insulates margin structures against spot-market raw material cost volatility. |
| Multi-Year Offtake Agreement Lock-In | Automotive OEM dual-source strategies with volume guarantees secure homologation slots under Germany's KBA timelines. |
Research Methodology
Operator-level perspectives from cell manufacturing executives, automotive OEM procurement leads, cathode precursor plant managers, and grid-scale storage integrators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against NMPA certification databases, EU Battery Regulation implementation guidance, SEC filings from listed battery producers, and customs trade data tracking lithium hydroxide and nickel sulfate flows. Bottom-up capacity modeling across Jiangsu, Guangdong, Michigan, and Bavarian manufacturing corridors triangulated against top-down automotive production forecasts.
Scenario-bracketing around nickel price volatility bands and IRA domestic content bonus qualification thresholds bounded high and low growth paths across the projection horizon. Segmentation dimensions modeled include cell geometry, end-user archetype, cathode chemistry, and regional regulatory compliance cluster. CAGRs derived from fitted S-curve adoption patterns for silicon-anode concentrations and grid-scale storage procurement trajectories. Industry-specific forecast inputs incorporated KBA homologation queue depths and NMPA batch tracking mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese producers or integrated chemical conglomerates would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Polymer Batteries Market
Lithium-ion Battery
Lithium-Ion Battery Cathode Material Market
Lithium-ion Battery
Power Lithium Battery Market
Lithium-ion Battery
Lithium Ion Battery Wet Coated Diaphragm Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market
Lithium-ion Battery
Lithium Iodide Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market