
 Global Potassium Metabisulfite Market | 2026-2036
Global Potassium Metabisulfite Market Size, Share, and Industry Trends Forecast 2026-2036
Global Potassium Metabisulfite Market Foresight
Sodium metabisulfite is shifting toward partial displacement in niche wine and food applications where sulfur dioxide residual limits are tightening. BASF SE leverages its integrated sulfur chemistry chain to sustain cost-advantaged supply of high-purity grades across European winemaking regions. Aditya Birla Chemicals anchors its position through captive raw material access and broad Asian distribution density.
Potassium metabisulfite (K2S2O5) is a white crystalline salt containing approximately 57.6% sulfur dioxide equivalent by weight, produced via neutralization of potassium carbonate with sulfurous acid followed by crystallization and drying. The compound functions primarily as an oxygen scavenger, antimicrobial agent, and bisulfite source across food, pharmaceutical, and industrial process streams. Food grade material commands the widest volume footprint, though pharmaceutical grade specifications are tightening as USP and EP monograph requirements elevate assay and impurity thresholds. Winemaking application retains structural dominance in value terms, while water treatment demand is accelerating fastest as municipal and industrial plants deploy bisulfite for dechlorination and membrane protection.
FDA food additive regulations under 21 CFR 182.3637 and REACH registration requirements through ECHA govern purity, labeling, and occupational exposure limits for potassium metabisulfite in food and industrial channels. China's GB standards through SAMR and NMPA oversight for pharmaceutical-grade material add compliance layers for exporters serving Asian manufacturing networks. Stakeholders must monitor evolving sulfur dioxide threshold regulations in key consuming jurisdictions and assess backward integration into sulfur or potassium feedstocks as margin protection against raw material volatility.
Market Dynamics
REACH registration requirements through ECHA are compressing supplier margins and accelerating consolidation among European potassium metabisulfite producers unable to absorb purity-testing costs.
Growth Catalysts
- Water treatment infrastructure:Municipal dechlorination systems in China deploy potassium metabisulfite for membrane protection, creating sustained volume pull from state-funded environmental programs.
- FDA 21 CFR 182.3637:The regulation's clarity on sulfur dioxide residual limits enables food-grade material penetration into processed fruit and vegetable preservation.
- Winemaking stabilization:French and Italian bottling facilities expand antioxidant dosing to meet extended shelf-life specifications for export markets.
Market Restraints
- Sulfur feedstock volatility:Refinery-derived sulfur supply fluctuations in the US Gulf Coast transmit directly to potassium metabisulfite production economics.
- Sodium metabisulfite substitution:Lower-cost sodium grades capture share in industrial dechlorination where sulfur dioxide residual limits remain permissive.
- REACH registration burden:ECHA's data requirements and substance evaluation timelines exclude smaller European compounders from food-grade participation.
Strategic Opportunities
- Pharmaceutical-grade expansion:USP and EP monograph upgrades for assay precision create premium positioning for producers with analytical chemistry capabilities.
- India's food processing sector:FSSAI enforcement of preservative standards in packaged foods opens import substitution potential for compliant regional manufacturers.
- EU Green Deal chemistry:The framework's bio-based process incentives reward producers developing renewable sulfur recovery pathways.
Industry Challenges
- Analytical chemistry talent scarcity:USP and EP compliance requires specialized chromatography and titration expertise that competes with broader pharmaceutical quality assurance markets.
- Legacy equipment retrofit costs:Crystallization and drying systems designed for lower-purity outputs demand capital reinvestment to meet tightening impurity thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Potassium Metabisulfite Market |
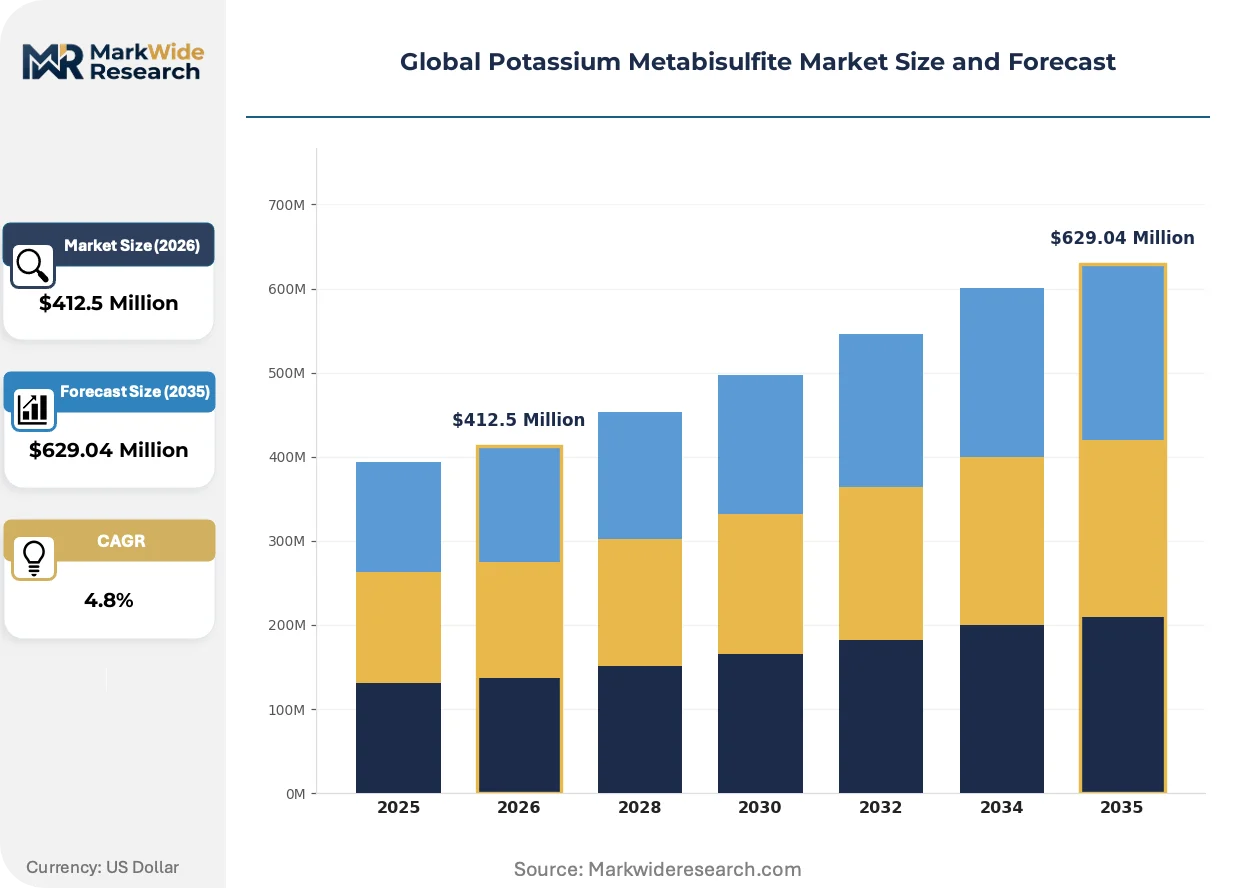
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Agricultural Grade Form: Powder, Granules, Crystals, Liquid Application: Food Preservation, Water Treatment, Winemaking, Chemical Manufacturing, Textile Processing End User: Food & Beverage Producers, Water Treatment Plants, Wineries, Chemical Manufacturers |
| Companies Covered | BASF SE, Aditya Birla Chemicals, LAFFORT, Alkaloid AD Skopje, Murphy and Son, Avantor Performance Chemicals, FMC Corporation, Anmol Chemicals Group, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Potassium Metabisulfite Market Shifts & Advancements
Continuous crystallization technology is compressing batch-to-batch variability and enabling real-time quality adjustment that static tank systems cannot match.
Membrane-based sulfur dioxide recovery systems are overtaking traditional scrubber configurations in new plant designs. Chinese water treatment operators adopt these units for dechlorination duty cycles exceeding 8,000 hours annually. The technology is overtaking conventional absorption towers by eliminating liquid effluent handling and reducing potassium salt consumption per treated volume.
REACH registration requirements through ECHA now mandate updated chemical safety reports for potassium metabisulfite used above one tonne annually. The regulation forces downstream users to document occupational exposure scenarios for winemaking and water treatment applications. Italian and German formulators are responding by consolidating supplier relationships to reduce registration duplication costs.
Direct procurement from compounders is replacing distributor intermediation among large-scale water treatment operators. Municipal utilities in China's Yangtze River basin now negotiate annual supply contracts with potassium metabisulfite manufacturers rather than regional chemical traders. This pattern is most visible in provinces where SAMR-mandated quality traceability requirements make distributor documentation liabilities untenable.
Global Potassium Metabisulfite Market Segmentation
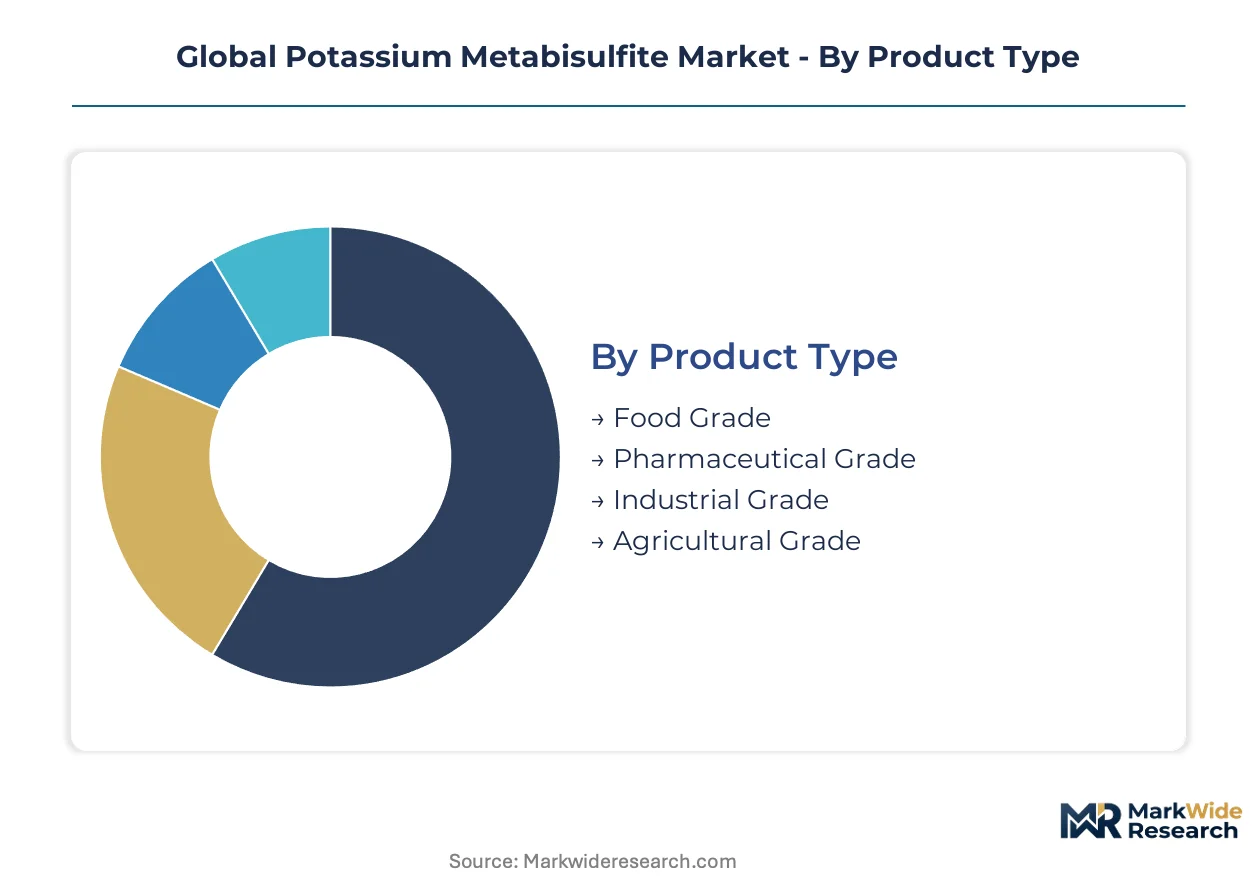
Potassium metabisulfite specifications diverge sharply across end-use channels, with purity thresholds, physical form requirements, and regulatory compliance burdens creating distinct investment profiles for producers. Understanding these segment boundaries enables targeted capacity allocation and margin optimization strategies.
Product Type:
Capital intensity escalates steeply from industrial grades through pharmaceutical specifications, with analytical infrastructure and quality systems driving fixed cost differentials.
- Food Grade:Material meeting 21 CFR 182.3637 and EFSA purity specifications dominates volume flows into wine stabilization and processed food preservation. French and Italian bottling facilities absorb the majority of high-purity food-grade output for antioxidant dosing in export-bound wines.
- Pharmaceutical Grade:USP and EP monograph compliance demands chromatographic assay capabilities and dedicated manufacturing suites that multiply capital requirements. Demand concentrates among contract manufacturers serving sterile injectable formulations where bisulfite antioxidant function is critical.
- Industrial Grade:Municipal dechlorination systems in China deploy this specification for membrane protection duty cycles.
- Agricultural Grade:Fungicidal and post-harvest treatment applications in specialty crop regions drive seasonal demand patterns.
Food Grade absorbs the bulk of installed capacity; Pharmaceutical Grade is expanding most quickly.
Form:
Dissolution kinetics and handling economics shape form selection, with powder dominating high-volume applications and crystals commanding premium positioning in precision-dosing scenarios.
- Powder:Rapid dissolution characteristics make this form essential for continuous-feed water treatment systems and high-throughput food processing lines. Chinese municipal utilities specify powder for automated dechlorination skids operating above 8,000 annual hours.
- Granules:Reduced dusting and improved flow properties enable manual dosing in smaller-scale winemaking operations. Italian cooperative wineries favor granules for barrel-room applications where precise sulfur dioxide addition prevents oxidation.
- Crystals:Pharmaceutical compounders specify crystalline material for controlled-release formulations.
- Liquid:Pre-dissolved solutions eliminate handling hazards in confined-space installations.
Powder commands the widest manufacturing footprint; Liquid solutions are climbing the fastest as water treatment automation spreads.
Application:
Regulatory complexity and technical performance requirements fragment the application landscape, with winemaking retaining value concentration despite water treatment's volume acceleration.
- Winemaking:Antioxidant and antimicrobial stabilization during bottling requires precise sulfur dioxide residual management. French producers expanding export shelf-life specifications drive premium-grade demand.
- Water Treatment:Municipal dechlorination and reverse osmosis membrane protection create sustained pull from China's state-funded environmental infrastructure programs. Membrane-based sulfur dioxide recovery systems are displacing conventional absorption towers in new plant designs.
- Food Preservation:Processed fruit and vegetable processors leverage bisulfite for enzymatic browning inhibition.
- Chemical Manufacturing:Reductive bleaching and polymerization control applications consume technical grades.
- Textile Processing:Dye reduction and fabric finishing operations in South Asian manufacturing clusters drive regional demand.
Winemaking anchors value generation; Water Treatment is gaining share fastest on infrastructure investment cycles.
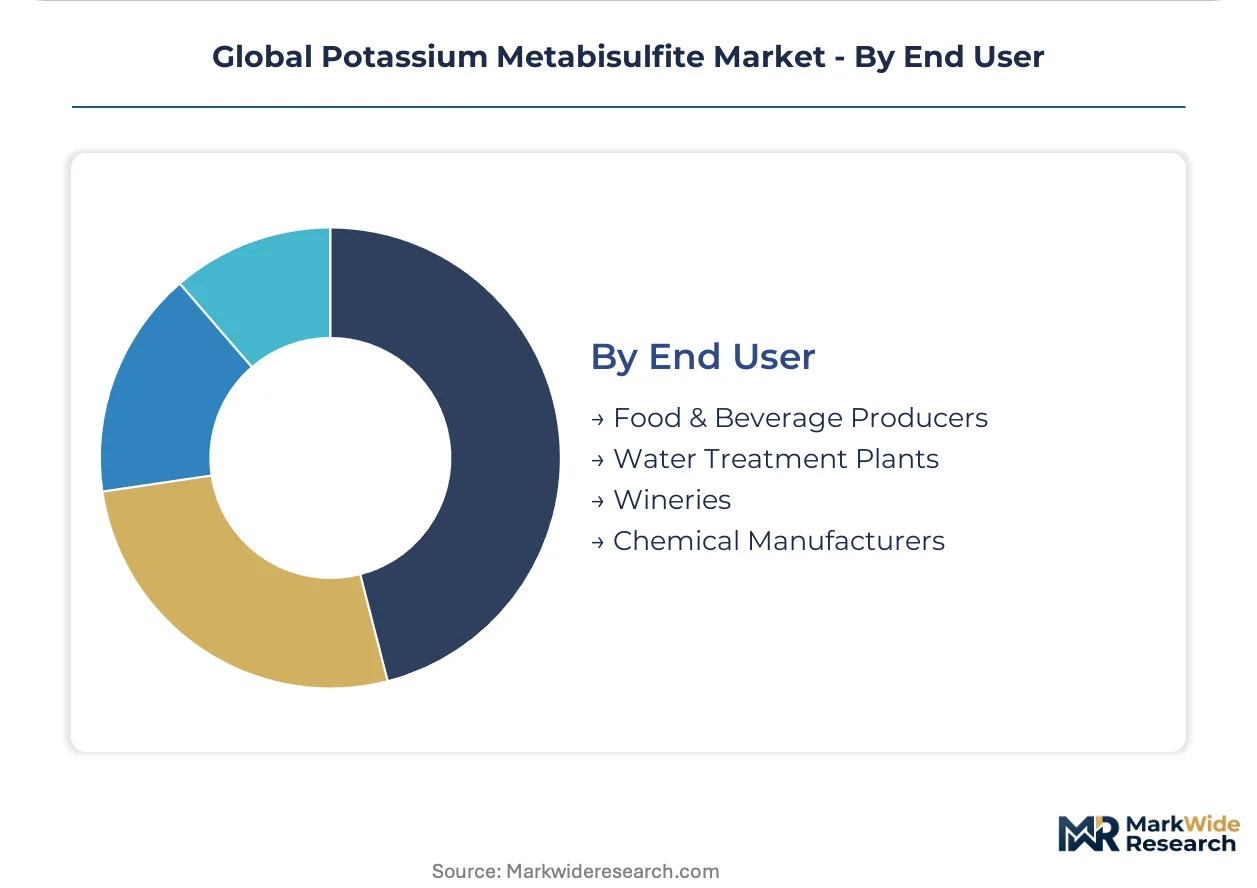
End User:
Procurement scale and technical sophistication stratify the customer base, with direct manufacturer relationships replacing distributor intermediation among large-volume accounts.
- Food & Beverage Producers:Multi-site processors with internal quality laboratories negotiate specification-tightened supply contracts. FSSAI enforcement in India's packaged food sector is opening import substitution opportunities for compliant regional manufacturers.
- Water Treatment Plants:Municipal utilities in China's Yangtze River basin now procure directly from compounders to satisfy SAMR-mandated traceability requirements that render distributor documentation untenable.
- Wineries:Consolidated bottling groups in France and Italy drive food-grade specification evolution.
- Chemical Manufacturers:Captive bisulfite production or tolling arrangements dominate this segment.
Water Treatment Plants are consolidating procurement fastest; Food & Beverage Producers retain the most fragmented supplier base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for potassium metabisulfite clusters in winemaking regions and water treatment infrastructure hubs across five countries. France, Italy, China, the United States, and Germany absorb the majority of food-grade and industrial-grade volumes through distinct regulatory and application pathways.
France
Bordeaux and Burgundy bottling facilities drive food-grade consumption for export wine stabilization. ANSM enforces strict sulfur dioxide residual limits under EU food additive frameworks. Champagne houses in Reims deploy precision-dosing systems for extended shelf-life specifications in Asian export markets.
Italy
Tuscan and Piedmont cooperative wineries favor granular potassium metabisulfite for barrel-room antioxidant applications. REACH registration through ECHA mandates updated chemical safety reports for compounders exceeding one tonne annual usage. Veneto packaging clusters near Verona consolidate supplier relationships to reduce registration duplication costs.
China
Municipal utilities in the Yangtze River basin procure powder-form material directly from manufacturers for automated dechlorination skids. SAMR-mandated quality traceability requirements render distributor documentation untenable in Jiangsu and Zhejiang provinces. Membrane-based sulfur dioxide recovery systems displace conventional absorption towers in new Shanghai municipal plant designs.
United States
California Central Valley fruit processors leverage FDA 21 CFR 182.3637 clarity to expand bisulfite usage in enzymatic browning inhibition. EPA and OSHA jointly govern occupational exposure limits in food handling facilities. Gulf Coast refinery sulfur supply fluctuations transmit directly to domestic potassium metabisulfite production economics.
Germany
Rhineland-Palatinate chemical manufacturers consume technical grades for reductive bleaching and polymerization control applications. ECHA substance evaluation timelines exclude smaller compounders from food-grade participation, accelerating consolidation. Bavarian pharmaceutical contract manufacturers demand USP-grade material for sterile injectable formulations.
Global Potassium Metabisulfite Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with food-grade winemaking applications favoring established chemical houses while water treatment procurement shifts toward direct manufacturer relationships. The supplier base exhibits moderate concentration at the top tier, with European and Asian producers commanding distinct geographic strongholds. Three archetypes dominate: integrated sulfur chemistry operators, regional compounders with captive raw material access, and pharmaceutical-grade specialists with analytical chemistry capabilities. Capacity expansion in China's Yangtze basin and backward integration into sulfur feedstocks represent the two dominant competitive moves.
Among integrated chemical conglomerates, BASF SE anchors the European food-grade tier through its sulfur chemistry chain integration. Aditya Birla Chemicals occupies a position exemplifying Asian regional compounders with broad distribution density. LAFFORT represents specialized winemaking chemical suppliers with deep penetration in French and Italian bottling facilities.
| Leading Market Players |
|---|
| BASF SE |
| Aditya Birla Chemicals |
| LAFFORT |
| Alkaloid AD Skopje |
| Murphy and Son |
| Avantor Performance Chemicals |
| FMC Corporation |
| Anmol Chemicals Group |
| American Elements |
| Others |
Supply & Pricing Matrix
Gulf Coast refinery sulfur price indices cascade through potassium metabisulfite production economics, compressing margins for non-integrated compounders while rewarding producers with captive sulfur chemistry chains. Food-grade material commands premium positioning over industrial grades as REACH compliance costs and analytical infrastructure investments stratify the supplier base.
Pricing Analysis
Volume concentration in industrial-grade dechlorination applications runs on thinner margins than pharmaceutical-grade specialty positioning. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified material for sterile injectables from food-grade winemaking specifications and bulk industrial powder. Pricing pressure stems from sodium metabisulfite substitution in water treatment segments where sulfur dioxide residual limits remain permissive. Municipal utilities in China's Yangtze basin exhibit highest price sensitivity through direct procurement negotiations, while pharmaceutical contract manufacturers show least sensitivity due to monograph compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with refinery-derived sulfur supply concentrated along the US Gulf Coast, German Rhineland-Palatinate chemical corridors, and Chinese Shandong province manufacturing clusters. Production draws from elemental sulfur, potassium carbonate, and sulfurous acid feedstocks with crystallization and drying equipment representing critical fixed-asset bottlenecks. Tariff exposure on sulfur imports from key producing regions threatens margin stability for European compounders lacking backward integration. Distribution runs through direct manufacturer relationships replacing distributor intermediation among large-scale water treatment operators in Jiangsu and Zhejiang provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
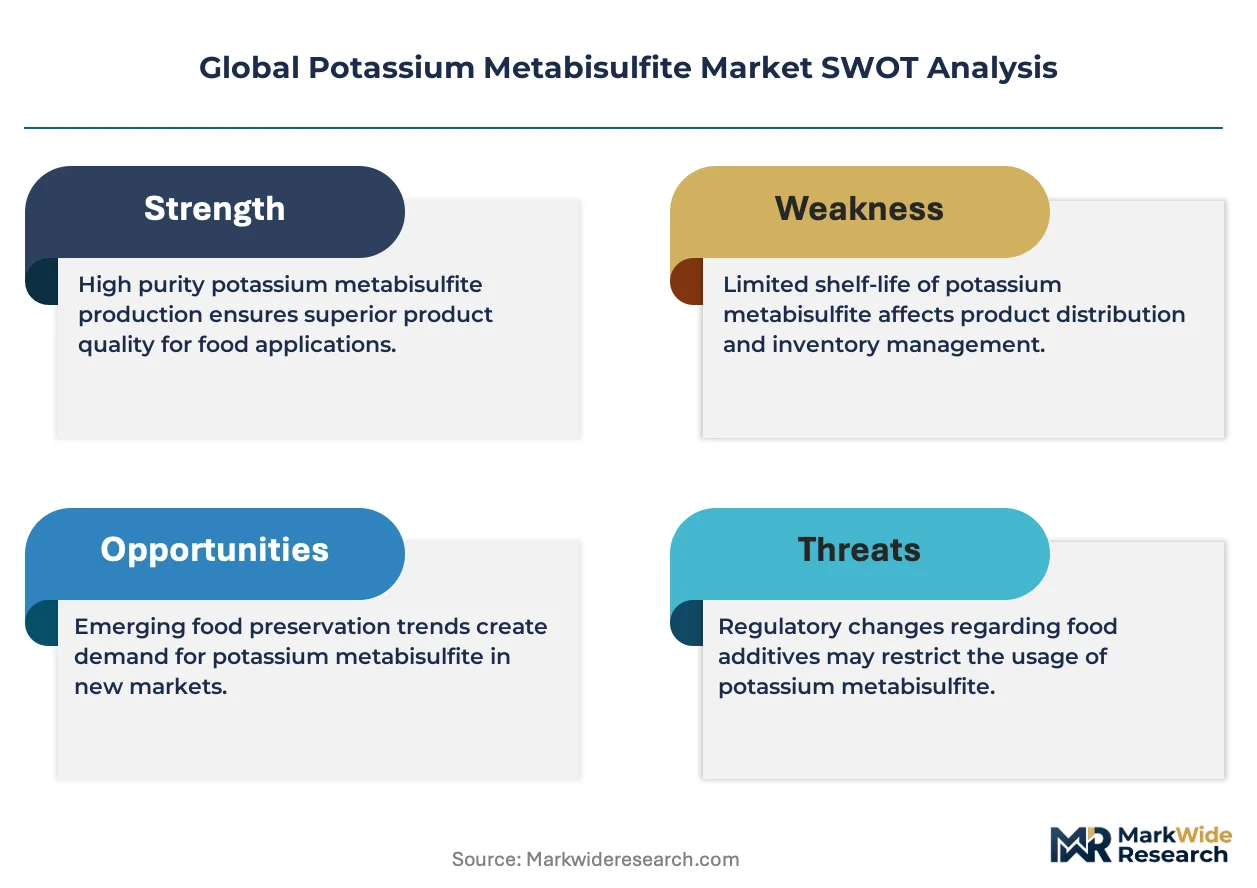
This market reads as supply-constrained with crystallization and drying system capacity serving as the binding bottleneck supporting pricing power across food and pharmaceutical grades.
For Market Incumbents: Hedge against sodium metabisulfite displacement by deepening analytical chemistry capabilities for USP and EP monograph compliance. BASF SE anchors European positioning through integrated sulfur chemistry; competitors must match this upstream control or concede cost-advantaged supply to regional compounders with captive raw material access in Asia. Capacity reinvestment in continuous crystallization technology defends margin position against batch-system rivals.
For New Entrants and Emerging Players: Capture white-space in India's food processing sector where FSSAI enforcement of preservative standards opens import substitution potential for compliant regional manufacturers. Water treatment automation in China's provincial municipalities offers penetrable volume as SAMR-mandated traceability requirements render distributor documentation untenable. Lead with membrane-based sulfur dioxide recovery system integration as differentiated technical positioning.
For Investors and Strategic Acquirers: The window for entry favors pharmaceutical-grade specialists with chromatographic assay capabilities and dedicated manufacturing suites. Long-term viability hinges on analytical chemistry talent retention and USP monograph upgrade responsiveness. Watch for ECHA substance evaluation timeline accelerations as inflection indicator for European supplier consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfur Feedstocks | Captive supply from refinery partnerships insulates margin against Gulf Coast price volatility. |
| Continuous Crystallization Technology Deployment | Real-time quality adjustment compresses batch variability for pharmaceutical-grade compliance. |
| Pharmaceutical-Grade Capacity Expansion | USP and EP monograph positioning captures premium pricing from sterile injectable demand. |
| Direct Procurement Relationship Development | Municipal utility contracts in China's Yangtze basin eliminate distributor documentation liabilities. |
| Green Manufacturing Transition | EU Green Deal bio-based process incentives reward renewable sulfur recovery pathway investment. |
Research Methodology
Document review covered customs and trade flow databases, ECHA REACH registration filings, FDA 21 CFR additive regulations, and SEC chemical company disclosures, complemented by interviews with plant managers at potassium metabisulfite production facilities, procurement leads at French and Italian bottling cooperatives, technical R&D directors in water treatment equipment manufacturing, and distribution channel partners across Asian chemical trading networks. Secondary validation drew from ACC and Cefic industry reports, SAMR quality standard publications, and USP monograph documentation. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic drivers.
Output modeling generated volume and value trajectories across the projection horizon through segmented analysis by grade tier, end-use application, physical form, and regional production hub. CAGRs were derived from regression analysis against historical demand elasticity patterns and forward-looking infrastructure investment cycles. Forecast inputs incorporated municipal dechlorination system deployment schedules in China, winemaking export shelf-life specification evolution in France and Italy, and pharmaceutical contract manufacturing capacity expansion plans.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to sulfur feedstock price volatility, REACH registration burden evolution, and sodium metabisulfite substitution acceleration in industrial segments. Forecasts reflect documented assumptions on regulatory timeline stability and infrastructure investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Lignin Waste Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Global Molten Sulfur Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Global Nitrite Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Isovaleryl Chloride Market