
 Giardiasis Treatment Market | 2026-2036
Giardiasis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Giardiasis Treatment Market Analysis
Subscription-based antimicrobial stewardship programs is broadening what hospitals purchase beyond the pill itself. Pfizer Inc. anchors its position through manufacturing scale across multiple continents. Teva Pharmaceuticals leverages its generic portfolio depth to compete on cost in emerging markets. Baxter International Inc. differentiates through intravenous delivery expertise in acute care settings.
Giardiasis treatment encompasses pharmaceutical interventions targeting the protozoan parasite Giardia lamblia, with metronidazole and tinidazole functioning as nitroimidazole compounds that disrupt parasite DNA synthesis. These agents serve the primary commercial purpose of eliminating intestinal colonization and preventing transmission in community water systems. The metronidazole segment maintains mature volume leadership due to decades of clinical familiarity and low production cost. Nitazoxanide represents the fastest-expanding category among antiparasitic treatments, driven by pediatric tolerability and broad-spectrum coverage. Intravenous delivery mode captures concentrated margin pools in hospital settings where oral administration fails.
FDA bioequivalence standards and WHO prequalification schemes govern product registration and procurement eligibility across donor-funded programs. The EPA Safe Drinking Water Act indirectly shapes demand by highlighting the waterborne transmission pathway that drives prophylactic and curative need. India's CDSCO and CDSCO-aligned state regulators enforce local manufacturing quality that determines market access for domestic and imported supplies. Stakeholders must monitor shifting resistance patterns and essential medicines list revisions to align pipeline investments with reimbursable demand.
Market Dynamics
Waterborne parasite prevalence in tropical climates sustains baseline demand, while WHO prequalification programs are compressing supplier eligibility and consolidating procurement channels around certified manufacturers.
Growth Catalysts
- Pediatric formulation demand:Hospital buyers in high-burden regions prioritize nitazoxanide suspensions for tolerability in children under five. India's CDSCO fast-track approvals for pediatric indications accelerate commercialization timelines.
- Essential medicines list expansion:National formularies in Brazil and Nigeria now mandate first-line antiparasitic coverage. Government tenders follow these revisions, locking in multi-year volume commitments.
- Antimicrobial stewardship programs:Subscription-based hospital purchasing bundles giardiasis treatment into broader infectious disease protocols. These programs expand addressable spend per account beyond single-product transactions.
Market Restraints
- Active pharmaceutical ingredient concentration:Nitroimidazole precursor manufacturing clusters in China and India. Geopolitical friction or export restrictions disrupt downstream formulation supply.
- Metronidazole resistance emergence:Treatment failure rates in Bangladesh and Kenya exceed clinical thresholds. Physicians retreat to second-line options, fragmenting volume across smaller product categories.
- EPA Safe Drinking Water Act compliance costs:Municipal water system upgrades in the US reduce symptomatic case incidence. Prophylactic demand compression follows infrastructure investment cycles.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Diagnostic capacity gaps mask true disease burden in Ethiopia and Uganda. Point-of-care test deployment would unlock latent treatment demand.
- Intravenous-to-oral switch protocols:Hospital discharge programs in acute care settings favor oral tinidazole completion. Formulation developers capture margin from shortened length-of-stay incentives.
- WHO prequalification pipeline:Generic manufacturers securing PQ status gain automatic eligibility in Global Fund and UNICEF tenders. This regulatory asset commands premium pricing in donor-funded channels.
Industry Challenges
- Bioequivalence study execution:FDA reference-scaled average bioequivalence requirements for nitazoxanide demand specialized CRO capabilities. Study design complexity extends development timelines.
- Cold chain integrity for pediatric suspensions:Last-mile distribution in Nigeria's northern states faces temperature excursion risks. Packaging innovation and logistics partnerships absorb working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Giardiasis Treatment Market |
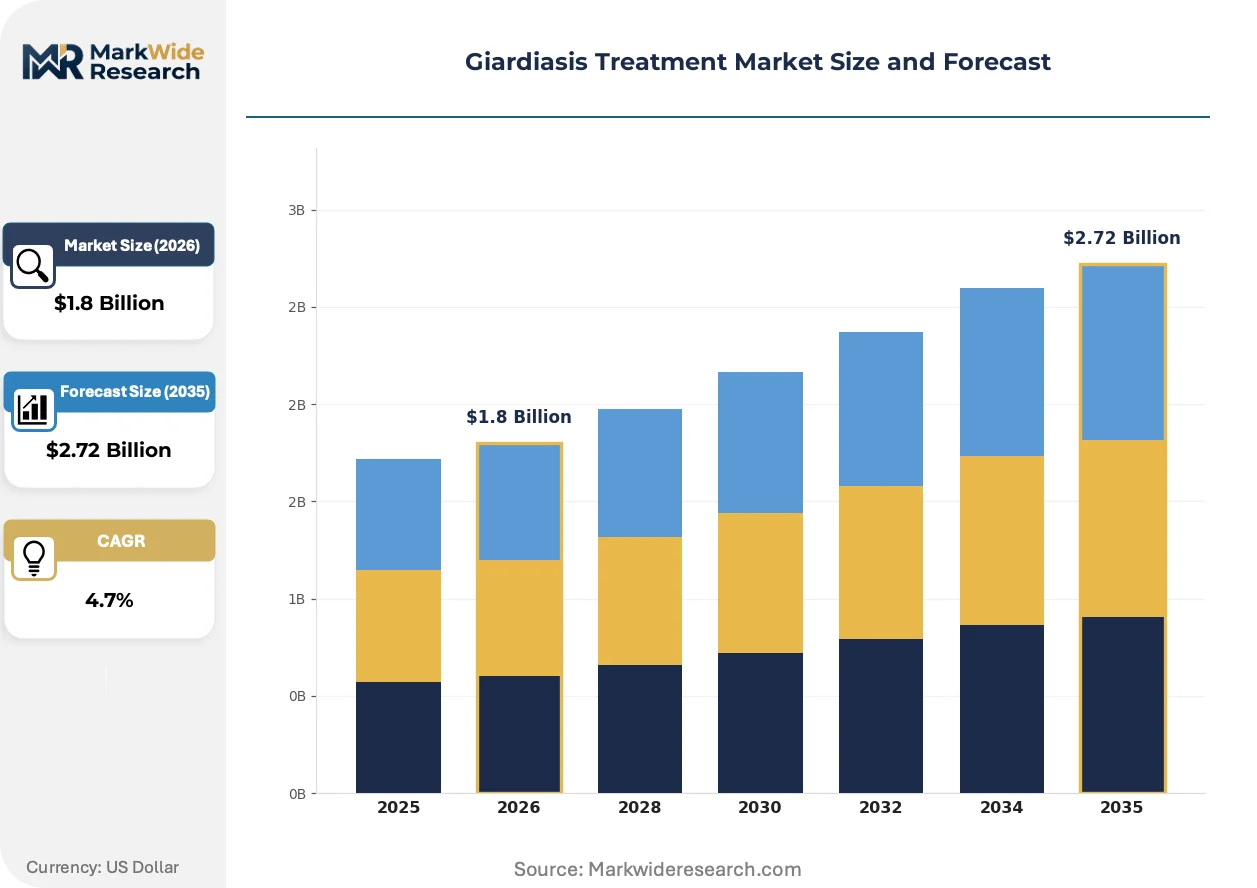
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metronidazole, Tinidazole, Nitazoxanide, Albendazole Therapy Area: Gastrointestinal Infections, Parasitic Infections, Antibiotic Resistance, Antiparasitic Treatment Delivery Mode: Oral, Intravenous, Pediatric Formulations, Combination Therapy End User: Pharmacies, Hospitals, Clinics, Online Pharmacies |
| Companies Covered | Pfizer Inc., Teva Pharmaceuticals, Baxter International Inc., Zydus Pharmaceuticals Inc., Lupin Pharmaceuticals, Inc., Aurobindo Pharma Limited, Heritage Pharmaceuticals Inc., Roxane Laboratories, Inc., Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Giardiasis Treatment Market Emerging Trajectories
Formulation science and procurement digitization are restructuring how antiparasitic therapies reach end-users, with regulatory data requirements simultaneously elevating barriers and rewarding compliance investment.
Pharmacogenomic screening is converging with nitroimidazole prescribing protocols. Large hospital systems in São Paulo and Mumbai pilot CYP2A6 variant testing to predict metronidazole metabolism rates. This convergence is compressing trial-and-error dosing cycles and reducing adverse event liability exposure.
REACH authorization requirements for pharmaceutical impurities are tightening analytical method specifications. European manufacturers must demonstrate sub-ppm control of nitroimidazole degradation products. The generic API segment faces disproportionate compliance cost pressure, accelerating consolidation toward integrated producers.
Hospital formulary committees now unbundle infection control bundles to scrutinize antiparasitic line-item economics. Group purchasing organizations in Brazil's SUS system negotiate tinidazole and nitazoxanide as separate SKUs rather than infectious disease portfolio blocks. This disaggregation is most visible in southeastern state procurement auctions where price transparency platforms publish winning bid spreads.
Giardiasis Treatment Market Segmentation
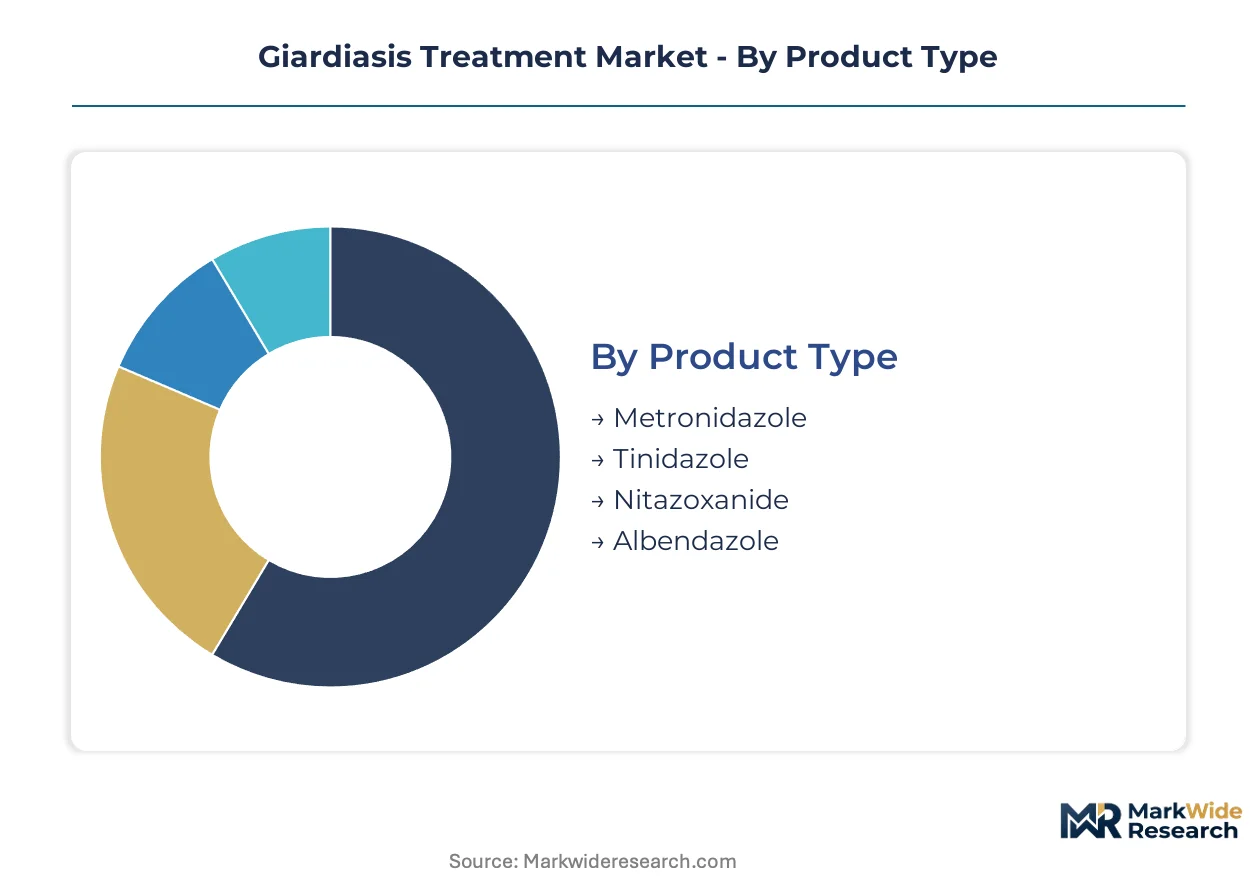
Giardiasis treatment procurement splits across therapeutic mechanism, clinical setting, and patient population, with each axis commanding distinct margin structures and regulatory requirements. Understanding these divides clarifies where formulation investment yields access to reimbursable demand versus commodity competition.
Product Type:
Cost tier separates originator chemistry from generic substitution patterns in national tenders.
- Metronidazole:Nitroimidazole compound disrupts parasite DNA synthesis through electron transport interference. Volume concentrates in India's government hospital networks where CDSCO-mandated bioequivalence standards determine tender eligibility for domestic manufacturers.
- Tinidazole:Second-generation nitroimidazole with extended half-life enabling single-dose regimens. Brazil's SUS procurement auctions favor this agent for outpatient compliance in southeastern state municipalities.
- Nitazoxanide:Thiazolide antiparasitic with broad-spectrum coverage against protozoa and helminths. Pediatric tolerability drives hospital formulary placement in Nigeria's northern states.
- Albendazole:Benzimidazole compound primarily targeting helminth infections with secondary giardiasis application. Demand clusters in mass drug administration programs for soil-transmitted helminths.
Metronidazole leads volumes today; nitazoxanide is gaining share fastest.
Therapy Area:
Application context dictates reimbursement pathway and prescriber specialty access.
- Gastrointestinal Infections:Symptomatic diarrhea management in acute care settings. Hospital discharge protocols in São Paulo favor tinidazole for reduced length-of-stay metrics.
- Parasitic Infections:Broad protozoan and helminth coverage requirements. WHO prequalification programs consolidate procurement around certified manufacturers for donor-funded channels.
- Antibiotic Resistance:Nitroimidazole failure retreatment protocols. Resistance emergence in Bangladesh and Kenya fragments volume across second-line options.
- Antiparasitic Treatment:General category encompassing prophylactic and curative indications. EPA Safe Drinking Water Act compliance in the US compresses prophylactic demand through infrastructure investment cycles.
Gastrointestinal infections anchor current prescribing; parasitic infections applications are climbing fastest.
Delivery Mode:
Margin concentration follows acute care dependency and formulation complexity.
- Oral:Standard tablet and capsule presentations for ambulatory patients. India's CDSCO fast-track approvals accelerate commercialization timelines for generic entrants.
- Intravenous:Hospital-administered formulations for severe dehydration or malabsorption cases. Baxter International's delivery expertise captures concentrated margin pools where oral administration fails.
- Pediatric Formulations:Suspensions and dispersible tablets for children under five. Cold chain integrity challenges in Nigeria's northern states absorb working capital through packaging innovation.
- Combination Therapy:Co-formulated or sequential regimens for refractory infections. Pharmacogenomic screening pilots in Mumbai predict metronidazole metabolism rates to optimize dosing.
Oral administration dominates volume; pediatric formulations show steepest expansion trajectory.
End User:
Customer type determines price transparency and procurement leverage.
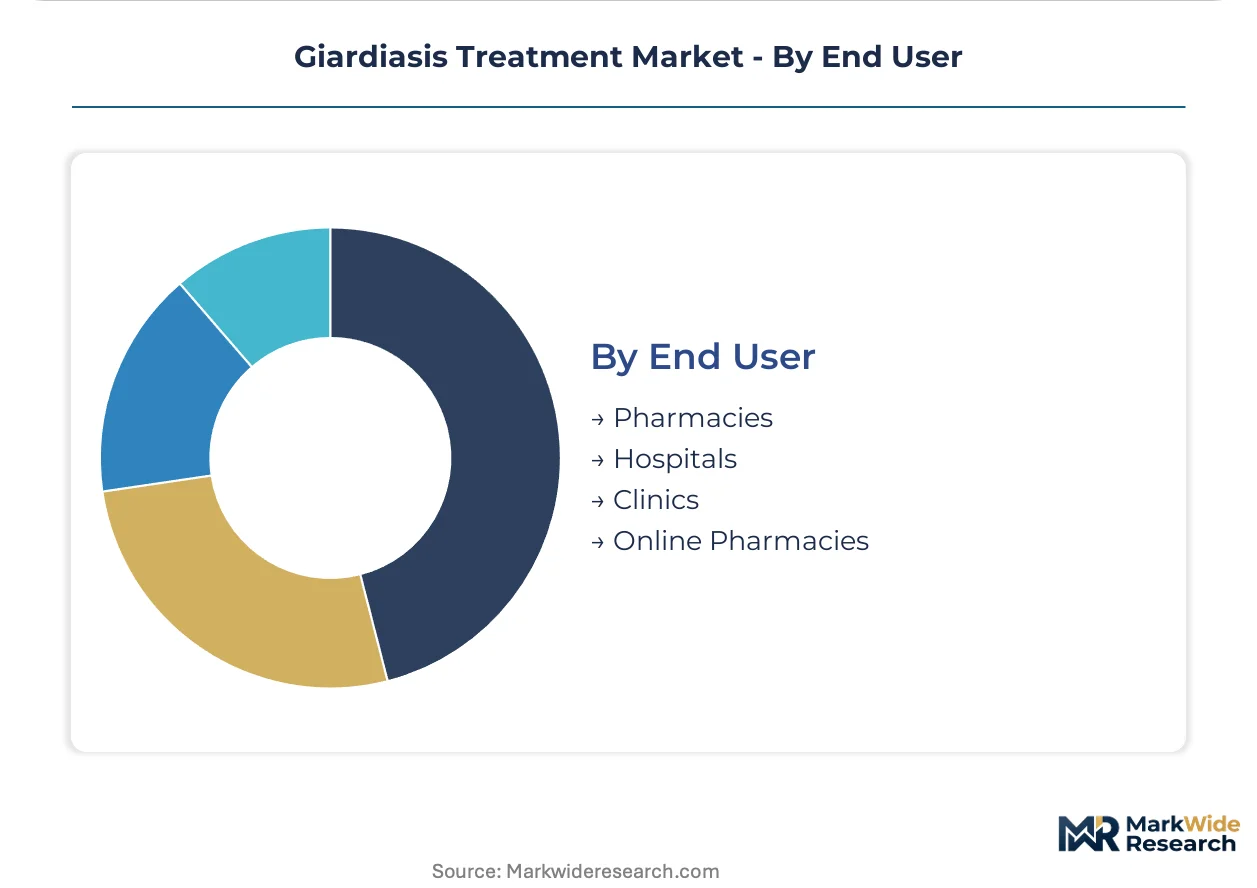
- Pharmacies:Retail dispensing for ambulatory prescriptions with cash-pay and insurance mix. Brazil's price transparency platforms publish winning bid spreads for consumer comparison.
- Hospitals:Inpatient and emergency department administration with formulary committee oversight. Subscription-based antimicrobial stewardship programs bundle giardiasis treatment into broader infectious disease protocols.
- Clinics:Outpatient diagnostic and treatment services in high-burden regions. Point-of-care test deployment in Ethiopia and Uganda would unlock latent treatment demand.
- Online Pharmacies:Direct-to-consumer dispensing with prescription verification requirements. India's state-aligned regulators enforce quality standards determining platform eligibility.
Hospitals command the largest transaction values; online pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as API producers relocate to jurisdictions with streamlined bioequivalence pathways and lower compliance overhead. Cost-of-compliance gaps between mature and emerging regulatory regimes are accelerating facility migration toward CDSCO-aligned markets.
United States
EPA Safe Drinking Water Act infrastructure investments are compressing symptomatic case incidence in municipal systems. FDA bioequivalence standards for nitazoxanide generics demand specialized CRO capabilities that extend development timelines. Formulation science clusters in Greater Boston and the Research Triangle Park are advancing pharmacogenomic screening protocols for CYP2A6 variant testing.
India
CDSCO fast-track approvals for pediatric indications are accelerating commercialization timelines for domestic manufacturers. Government hospital networks concentrate metronidazole volume under bioequivalence-mandated tender eligibility. API and formulation production clusters in Maharashtra and Gujarat are capturing contract manufacturing demand from Western sponsors seeking cost-advantaged supply.
Brazil
SUS procurement auctions in southeastern state municipalities favor single-dose tinidazole regimens for outpatient compliance. ANVISA alignment with WHO prequalification standards is consolidating supplier eligibility around certified manufacturers. São Paulo's hospital discharge protocols are piloting intravenous-to-oral switch programs to reduce length-of-stay metrics.
Nigeria
WHO prequalification status determines automatic eligibility in Global Fund and UNICEF tender channels for northern state procurement. Cold chain integrity challenges for pediatric suspensions are absorbing working capital through packaging innovation in Kano and Kaduna distribution corridors. Diagnostic capacity gaps in Ethiopia-bordering regions mask latent treatment demand awaiting point-of-care test deployment.
Germany
REACH authorization requirements for nitroimidazole degradation products are tightening analytical method specifications to sub-ppm thresholds. EMA-aligned manufacturers face disproportionate compliance cost pressure relative to Asian competitors. Bavarian chemical clusters are consolidating toward integrated producers capable of captive API supply and finished formulation output.
Giardiasis Treatment Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originator chemistry commanding premium positioning in hospital procurement while generic substitution patterns dominate retail pharmacy channels. The vendor base organizes around three strategic archetypes: multinational pharmaceutical conglomerates with manufacturing scale across multiple continents, mid-cap generic houses leveraging portfolio depth for cost competition, and acute-care delivery specialists capturing concentrated margin pools in intravenous formulations. Consolidation pressure is accelerating through M&A activity targeting WHO prequalification assets and capacity expansion in CDSCO-aligned jurisdictions.
Among North American-based conglomerates, Pfizer Inc. exemplifies the scale-driven archetype through multi-continent manufacturing footprints. Teva Pharmaceuticals occupies a position within the generic portfolio depth tier, competing on cost in emerging market tenders. Baxter International Inc. anchors the acute-care specialization vector, differentiating through delivery expertise where oral administration fails. These three entities collectively represent the competitive positioning spectrum spanning originator, generic, and delivery-mode specialization.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceuticals |
| Baxter International Inc. |
| Zydus Pharmaceuticals Inc. |
| Lupin Pharmaceuticals, Inc. |
| Aurobindo Pharma Limited |
| Heritage Pharmaceuticals Inc. |
| Roxane Laboratories, Inc. |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap API producers in western India anchor supply-side discipline through captive manufacturing networks that compress cost structures while preserving margin buffers against tender volatility. Their ownership concentration permits rapid capacity reallocation when CDSCO bioequivalence deadlines shift procurement eligibility, creating pricing power asymmetries against foreign competitors facing longer compliance timelines.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for metronidazole generics as domestic manufacturers absorb CDSCO-mandated bioequivalence costs into scale economies. Three-tier pricing structure across WHO-prequalified, CDSCO-certified, and unregistered tiers separates hospital tenders from retail pharmacy substitution patterns. Pricing pressure stems from nitazoxanide pediatric suspensions capturing formulary preference premiums that erode metronidazole standard-tier margins. Government hospital networks in India exhibit highest price sensitivity; acute-care intravenous formulations in Brazilian SUS hospitals show lowest.
Supply Chain Analysis
Nitroimidazole precursor manufacturing rests on specialty chemical clusters in China and India, with intermediate synthesis capabilities concentrated in Shandong province and Gujarat state. Key inputs span 2-methylimidazole feedstock, nitration reagents, and crystallization solvents. Single-source vulnerability runs through Shandong export permit volatility that disrupts downstream formulation supply. Distribution runs through government tender depots in high-burden countries, UNICEF prequalified channels, and hospital GPO contracts in Brazil and Nigeria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Giardiasis Treatment Market compounds steadily as waterborne parasite prevalence in tropical climates sustains replacement demand regardless of economic cycles. Essential medicines list expansions in high-burden countries lock in multi-year volume commitments that smooth revenue volatility.
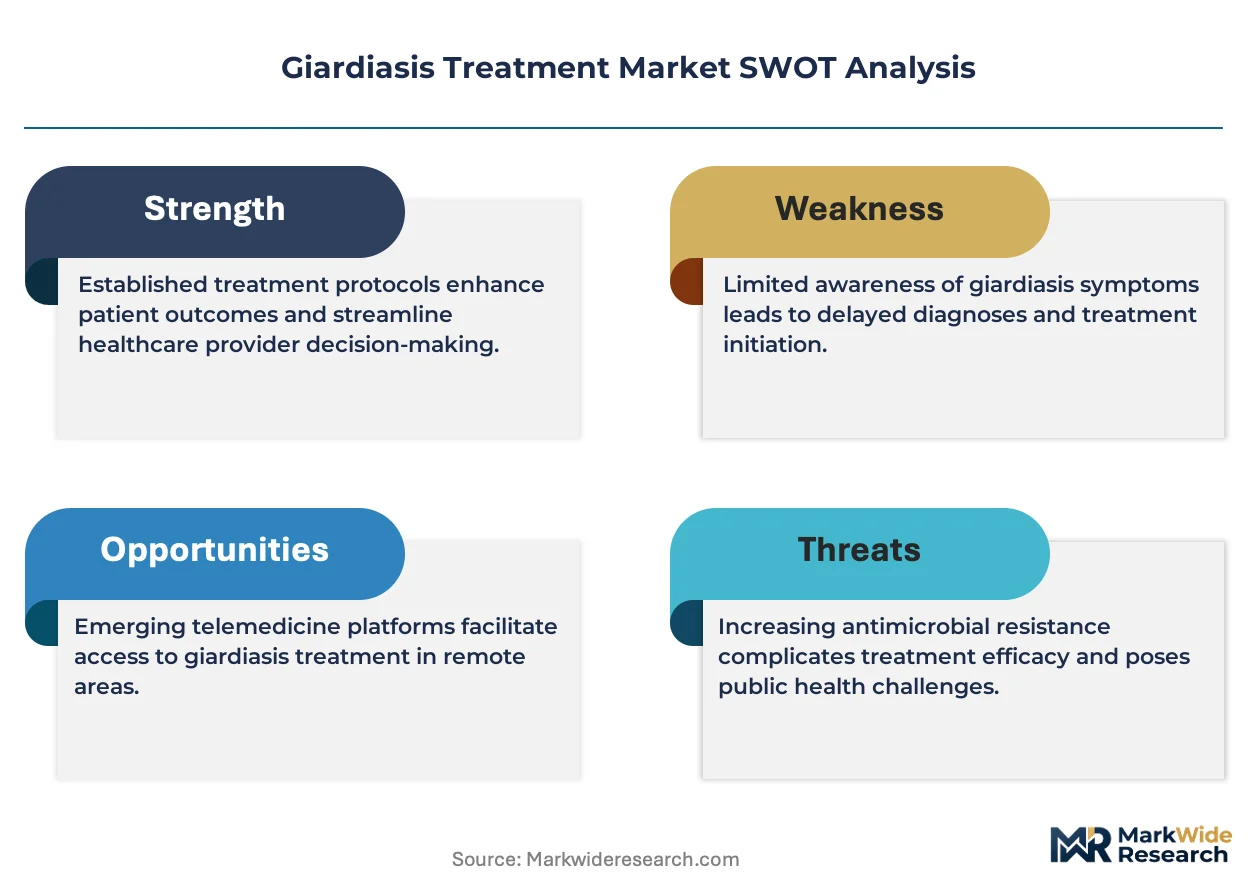
For Market Incumbents: Deepen backward integration into nitroimidazole precursor manufacturing to insulate margin structures from Shandong export friction. Secure WHO prequalification status for pediatric suspension portfolios to capture automatic eligibility in Global Fund and UNICEF tenders, defending against emerging generic houses with faster CDSCO-aligned approval timelines. For New Entrants and Emerging Players: CDSCO fast-track approvals for pediatric indications in India open a window for nitazoxanide suspension specialists to penetrate government hospital networks before multinational incumbents complete bioequivalence dossiers. Target diagnostic capacity gaps in Ethiopia and Uganda with point-of-care test bundling that unlocks latent treatment demand. Pursue contract manufacturing partnerships with Maharashtra-based API producers to compress facility investment requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap generic houses lacking WHO prequalification status but possessing CDSCO-certified manufacturing infrastructure. The five-to-ten year viability window favors acquisition targets with captive API supply and finished formulation flexibility across oral and pediatric delivery modes. Watch for nitazoxanide resistance emergence in Bangladesh and Kenya as the inflection signal that would accelerate second-line option fragmentation and reshape portfolio prioritization.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pursuit | Unlocks automatic eligibility in Global Fund and UNICEF procurement channels. |
| Pediatric Formulation Development | Captures hospital formulary preference in Nigeria's northern states and India's government networks. |
| API Backward Integration | Insulates margin structures from Shandong export permit volatility and geopolitical friction. |
| Point-of-Care Diagnostic Bundling | Addresses latent demand in Ethiopia and Uganda by masking diagnostic capacity gaps. |
| Intravenous-to-Oral Switch Protocols | Aligns with São Paulo hospital discharge programs to reduce length-of-stay metrics. |
Methodological Framework
Coverage spans India, Brazil, Nigeria, the United States, and Germany, with primary inputs from each market's regulatory and procurement stakeholders. Drug development executives, CDSCO regulatory affairs leads, hospital formulary directors, and SUS procurement managers provided qualitative grounding. Secondary validation drew from FDA bioequivalence filings, WHO prequalification databases, CDSCO approval records, and ANVISA tender publications. Bottom-up volume modeling triangulated against top-down expenditure estimates from national essential medicines list budgets.
Rate-of-change decomposition segmented growth across therapeutic mechanism, delivery mode, patient population, and regional regulatory cluster. Treatment line stratification modeled first-line metronidazole substitution against second-line retreatment protocols. Dosage form analysis tracked tablet, suspension, and intravenous share shifts. CAGRs derived from epidemiological burden projections intersected with procurement volume commitments and infrastructure investment cycles. Resistance pattern surveillance data and essential medicines list revision timelines informed trajectory adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under metronidazole resistance acceleration or nitroimidazole precursor export restrictions. Projections reflect assumptions about CDSCO approval velocity, WHO prequalification pipeline progression, and municipal water infrastructure investment cycles in high-burden countries. A small set of named triggers warrants ongoing watch: nitazoxanide resistance emergence thresholds, Shandong export permit volatility, and essential medicines list revision schedules in Brazil and Nigeria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Europe Lysosomal Disease Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Phototherapy Treatment Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Corneal Transplant Market
Medical Treatment
Angelman Syndrome Treatment Market
Medical Treatment
Hemorrhagic Shock Treatment Market
Medical Treatment
Anaphylaxis Treatment Market
Medical Treatment
Global Uterine Fibroids Treatment Market
Medical Treatment
Hypercoagulability Treatment Market
Medical Treatment
US Direct Anterior Approach (Total Hip Replacement) Market
Medical Treatment
Hyponatremia Treatment Market
Medical Treatment
Global Thyroid Disorder Treatment Market
Medical Treatment
Global Fabry Disease Treatment Market
Medical Treatment
Thyroid Gland Disorders Treatment Market