
 Cholera Treatment Market | 2026-2036
Cholera Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Cholera Treatment Market Outlook
Indian pharmaceutical manufacturers is shifting bulk oral rehydration salt production toward WHO-prequalified facilities. Sanofi leverages its established vaccine infrastructure to anchor cholera immunization programs in endemic zones. GlaxoSmithKline plc competes through differentiated heat-stable formulation technology. Emergent BioSolutions Inc specializes in government contract fulfillment for emergency response stockpiles.
Cholera treatment encompasses fluid replacement therapy, antimicrobial intervention, and micronutrient supplementation designed to reverse severe dehydration and electrolyte collapse from Vibrio cholerae infection. Oral rehydration salts remain the foundational intervention, typically formulated with sodium chloride, trisodium citrate, potassium chloride, and glucose in specific osmolar ratios to maximize intestinal sodium-glucose cotransport. Antibiotics command concentrated margin pools due to limited-source manufacturing and cold-chain requirements, while zinc supplementation gains traction in pediatric protocols for its demonstrated reduction in episode duration. Emergency Response applications attract premium pricing through rapid-deployment logistics, whereas Community Health channels sustain volume through recurring endemic-country procurement.
FDA oversight governs export-grade antibiotic specifications from US-based suppliers, while WHO prequalification dictates market access for developing-country tenders. India's CDSCO enforces batch-release protocols for domestically manufactured intravenous fluids and ORS sachets. National regulatory authorities across endemic nations increasingly mandate stability testing at tropical temperatures. Stakeholders must monitor evolving procurement centralization patterns and prequalification renewal timelines to secure long-term contract visibility.
Market Dynamics
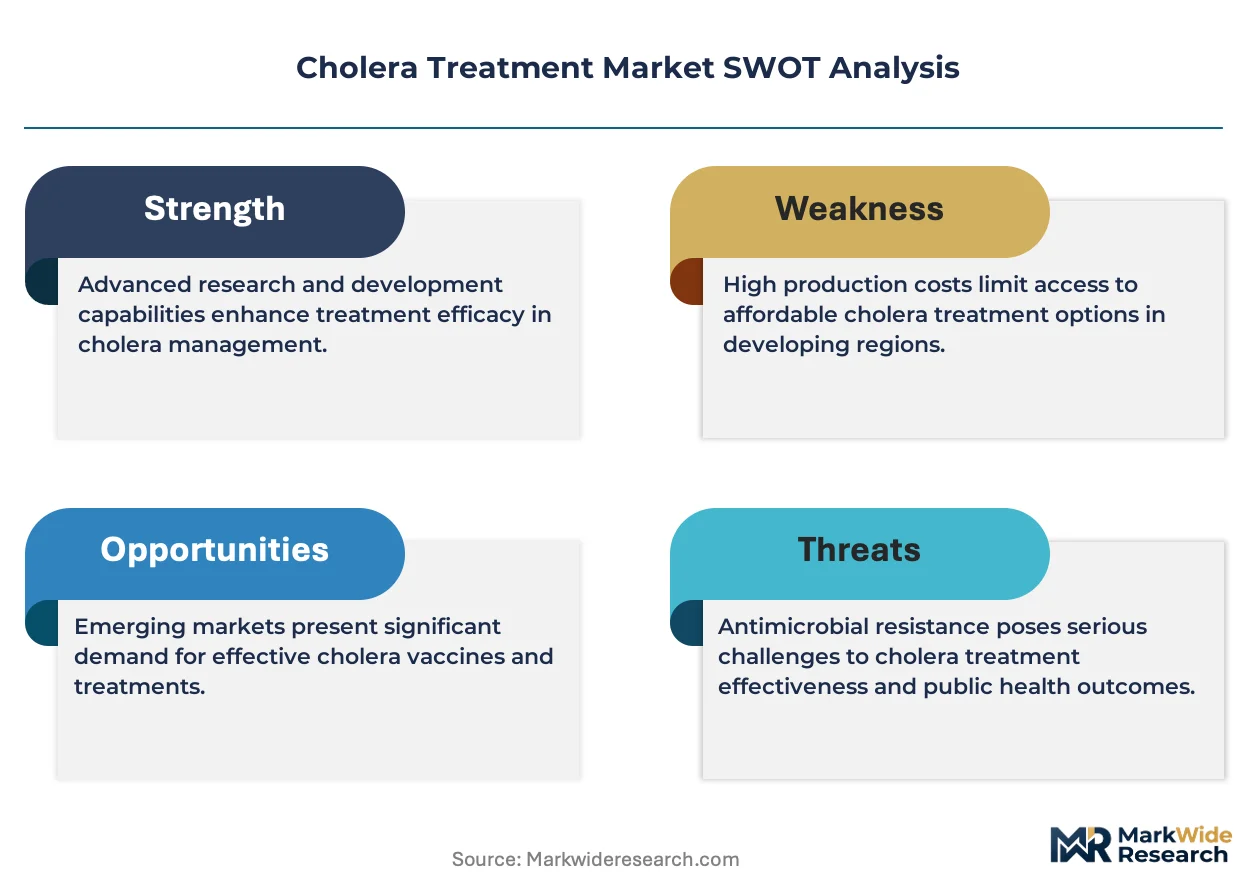
WHO prequalification standards are compressing supplier margins while concentrating procurement authority into fewer national stockpile managers across endemic zones. This regulatory tightening is eliminating subscale manufacturers and reshaping competitive positioning around certification velocity rather than price alone.
Growth Catalysts
- Emergency stockpile mandates:Government procurement agencies in Bangladesh and Yemen now maintain rolling 12-month buffer inventories. This institutionalizes recurring tender cycles and reduces demand volatility for qualified suppliers.
- CDSCO batch-release automation:India's pharmaceutical regulator has streamlined domestic ORS and IV fluid approvals. Reduced clearance timelines accelerate product-to-market velocity for manufacturers with established quality systems.
- Heat-stable formulation advances:Cold-chain-independent oral vaccines and rehydration therapies unlock distribution into rural clinics lacking refrigeration infrastructure. This technology removes the primary barrier to last-mile penetration.
Market Restraints
- Active pharmaceutical ingredient concentration:Three Indian manufacturers control bulk azithromycin and ciprofloxacin supply for cholera antibiotics. Any disruption at these nodes propagates through finished-dose production globally.
- Stability testing mandates:National regulatory authorities in endemic countries now require accelerated degradation studies at 40°C/75% humidity. This adds 8-12 months to registration timelines and excludes suppliers lacking tropical-climate validation capabilities.
- Oral rehydration therapy substitution:Low-osmolarity ORS formulations are displacing standard ORS in pediatric protocols. Manufacturers with legacy standard-ORS production lines face stranded capacity without retooling investment.
Strategic Opportunities
- Haiti reconstruction procurement:Post-conflict health system rebuilding is channeling multilateral development bank funding into centralized cholera treatment procurement. First-mover suppliers can anchor multi-year framework agreements.
- Zinc-ORS co-packaging:WHO guidelines now recommend simultaneous zinc supplementation for children under five. Bundled product formats capture premium positioning while simplifying caregiver compliance.
- Drone delivery corridors:Last-mile distribution partnerships with aerial logistics providers bypass road infrastructure gaps in flood-prone regions. This channel innovation compresses emergency response times from days to hours.
Industry Challenges
- Qualified person scarcity:WHO prequalification dossier preparation requires specialized regulatory affairs expertise. The limited pool of consultants with successful cholera-product submission experience creates bottlenecks for mid-tier manufacturers.
- Legacy equipment retrofit costs:Transitioning from standard-ORS to low-osmolarity production requires granulation line modifications and dissolution testing upgrades. Capital deployment timelines misalign with tender award cycles.
- Multisite audit coordination:Stringent supply chain verification demands simultaneous inspections of API sources, finished-dose facilities, and third-party logistics providers. Synchronization failures risk prequalification suspension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholera Treatment Market |
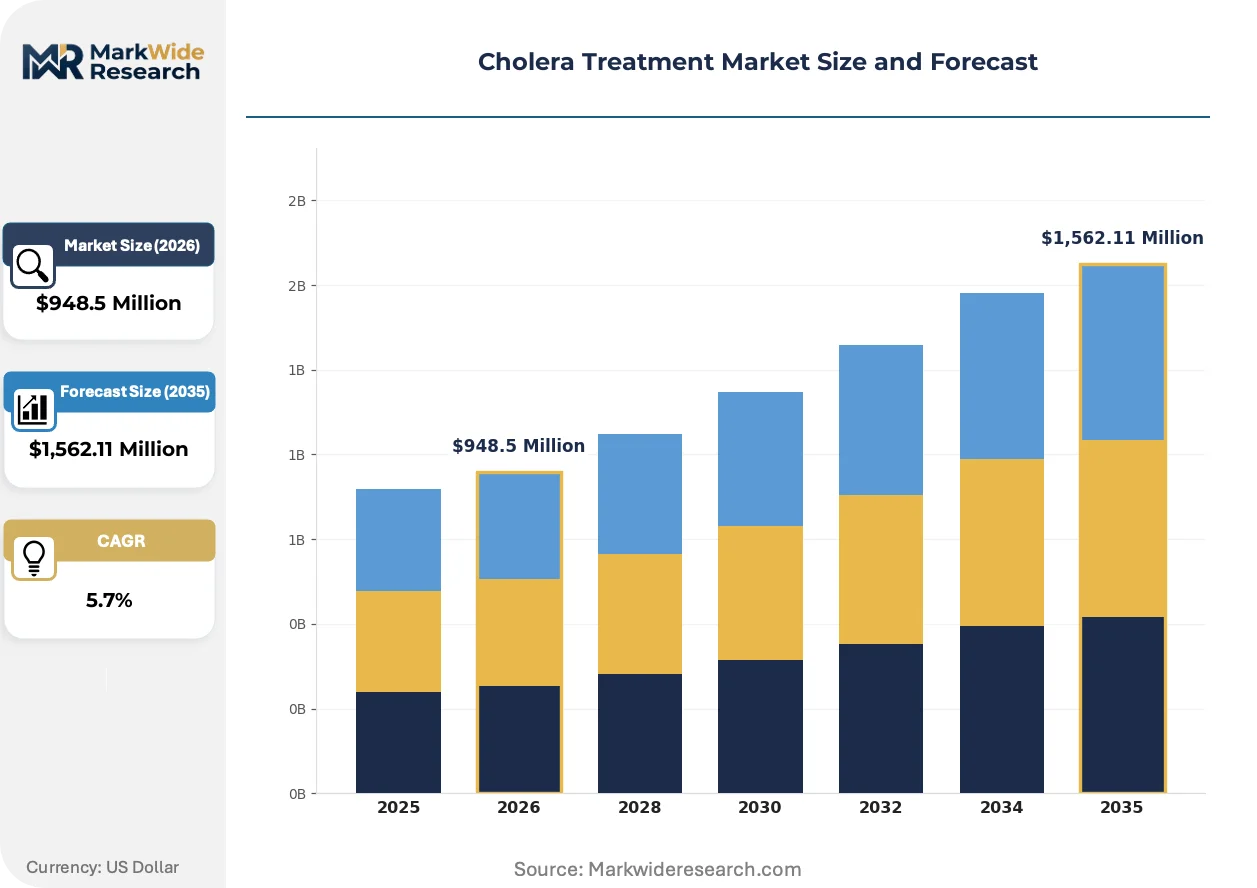
| Market Size in 2026 | $948.5 Million |
| Market Size in 2035 | $1,562.11 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Rehydration Salts, Antibiotics, Intravenous Fluids, Zinc Supplement Application: Hospital, Community Health, Home Care, Emergency Response End User: Patients, Healthcare Providers, NGOs, Government Agencies Treatment Mode: Inpatient Care, Outpatient Care, Self-Administration, Telemedicine |
| Companies Covered | Sanofi, Valneva SE, Emergent BioSolutions Inc, EUBIOLOGICS CO., LTD, Astellas Pharma Inc, GlaxoSmithKline plc, Johnson & Johnson, Merck & Co., Sun Pharmaceutical Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholera Treatment Market Strategic Shifts
Formulation science and distribution logistics are converging to reshape how cholera therapies reach outbreak zones. Three developments are compressing the gap between production and patient access.
Low-osmolarity oral rehydration salts are rewriting clinical protocol standards for severe dehydration management. These formulations reduce stool output volume by 25% compared to standard ORS, prompting ministries of health in Bangladesh and Yemen to mandate their inclusion in national essential medicines lists. Procurement specifications now exclude legacy standard-ORS products from new tenders, forcing manufacturers to reformulate or exit endemic markets.
WHO prequalification renewal timelines are tightening from five years to three years for cholera vaccines and antibiotics. This regulatory compression accelerates capital redeployment cycles for manufacturers and elevates the strategic value of dedicated regulatory affairs functions. Suppliers with in-house WHO liaison capabilities are capturing disproportionate tender share as competitors struggle with documentation lag.
Centralized procurement consortia are consolidating previously fragmented national tender processes. The Gavi-funded global stockpile mechanism now aggregates demand from 15 endemic countries into single-source awards. This buyer concentration rewards scale and certification breadth while marginalizing regional suppliers lacking multi-country registration portfolios.
Cholera Treatment Market Segmentation
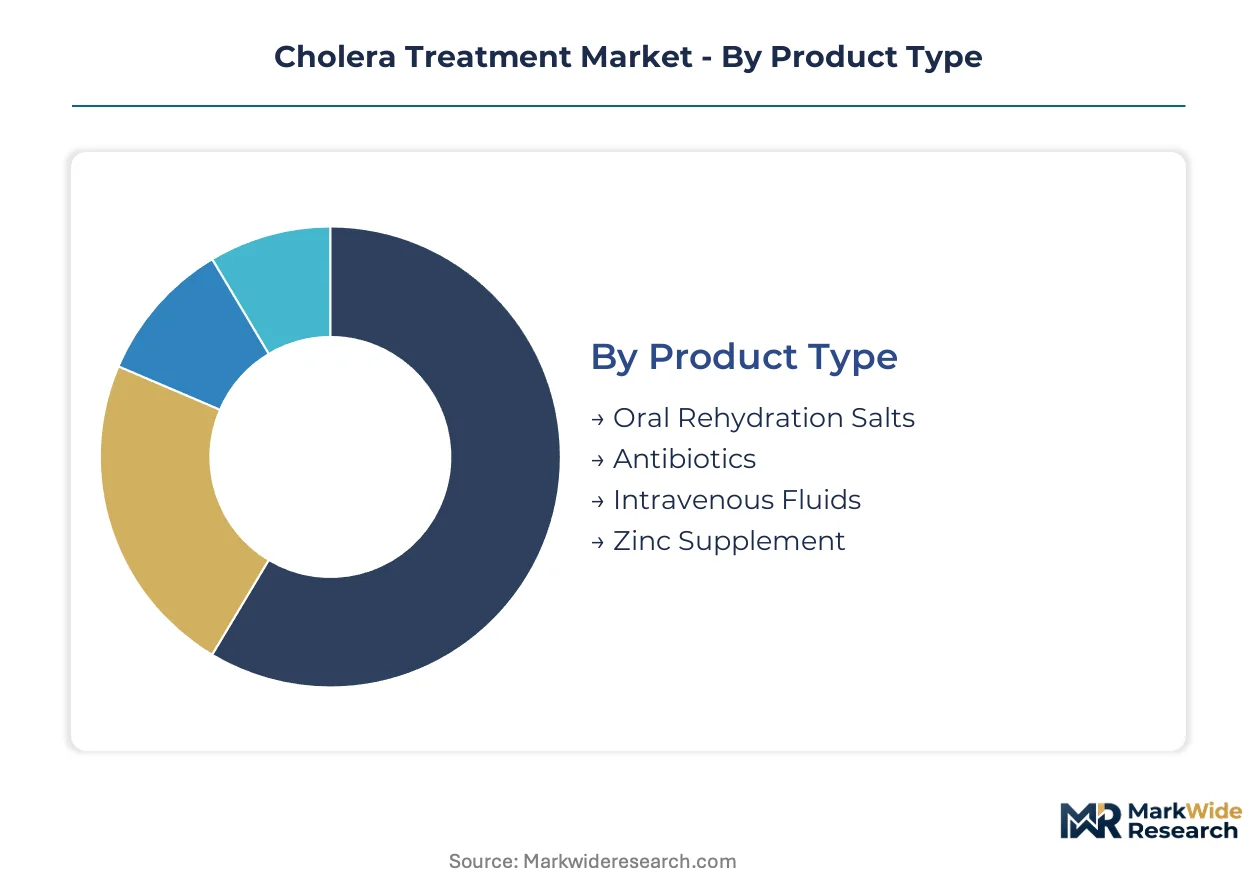
Cholera treatment procurement splits across product categories with divergent margin profiles and distribution requirements. Understanding these fault lines clarifies where manufacturers concentrate R&D investment versus where they chase volume through tender participation.
Product Type:
Cost tier drives supplier selection more than clinical differentiation in endemic-country tenders.
- Oral Rehydration Salts:Formulated with sodium chloride, trisodium citrate, potassium chloride, and glucose in WHO-specified osmolar ratios to maximize intestinal sodium-glucose cotransport. Demand concentrates in Bangladesh and Yemen where national programs distribute sachets through community health workers; low-osmolarity formulations are displacing standard ORS in pediatric protocols.
- Antibiotics:Azithromycin and ciprofloxacin reduce stool volume and treatment duration when co-administered with rehydration therapy. Procurement clusters in emergency response stockpiles managed by government agencies in Haiti and Yemen; cold-chain requirements and limited-source API manufacturing sustain premium positioning.
- Intravenous Fluids:Ringer's lactate and normal saline address severe dehydration with circulatory collapse. CDSCO batch-release protocols govern Indian domestic supply.
- Zinc Supplement:WHO guidelines recommend simultaneous administration for children under five to reduce episode duration. Co-packaging with ORS captures premium positioning in pediatric tenders.
Volume sits with Oral Rehydration Salts; growth tilts toward Zinc Supplement co-formulations.
Application:
Channel selection determines pricing power and contract duration for suppliers.
- Emergency Response:Rapid-deployment logistics with pre-positioned stockpiles in flood-prone regions command premium pricing through guaranteed availability clauses. Government agencies in Yemen and Haiti anchor multi-year framework agreements for surge capacity.
- Community Health:Recurring endemic-country procurement through decentralized distribution networks sustains volume for qualified manufacturers. Bangladesh's national ORS program exemplifies institutionalized demand.
- Hospital:IV fluid administration and inpatient monitoring for severe cases. WHO prequalification standards filter supplier participation.
- Home Care:Self-administered ORS and zinc for mild dehydration episodes. Caregiver compliance challenges favor simplified dosing formats.
Emergency Response commands margin premiums; Community Health delivers recurring volume scale.
End User:
Procurement authority concentration reshapes competitive dynamics across buyer categories.
- Government Agencies:Centralized tendering through ministries of health in endemic zones aggregates demand into multi-year awards. Prequalification velocity determines contract access more than price alone.
- NGOs:Médecins Sans Frontières and International Medical Corps operate parallel procurement for outbreak response. Flexible sourcing tolerates shorter registration timelines than government tenders.
- Healthcare Providers:Hospital pharmacies and clinic networks manage inventory for routine cases. Stockout risk drives preference for suppliers with local warehousing.
- Patients:Out-of-pocket purchase in informal retail channels for mild episodes. Price sensitivity favors generic ORS sachets.
Contract concentration favors Government Agencies; flexibility advantages sit with NGOs.
Treatment Mode:
Care setting determines product format requirements and reimbursement pathways.
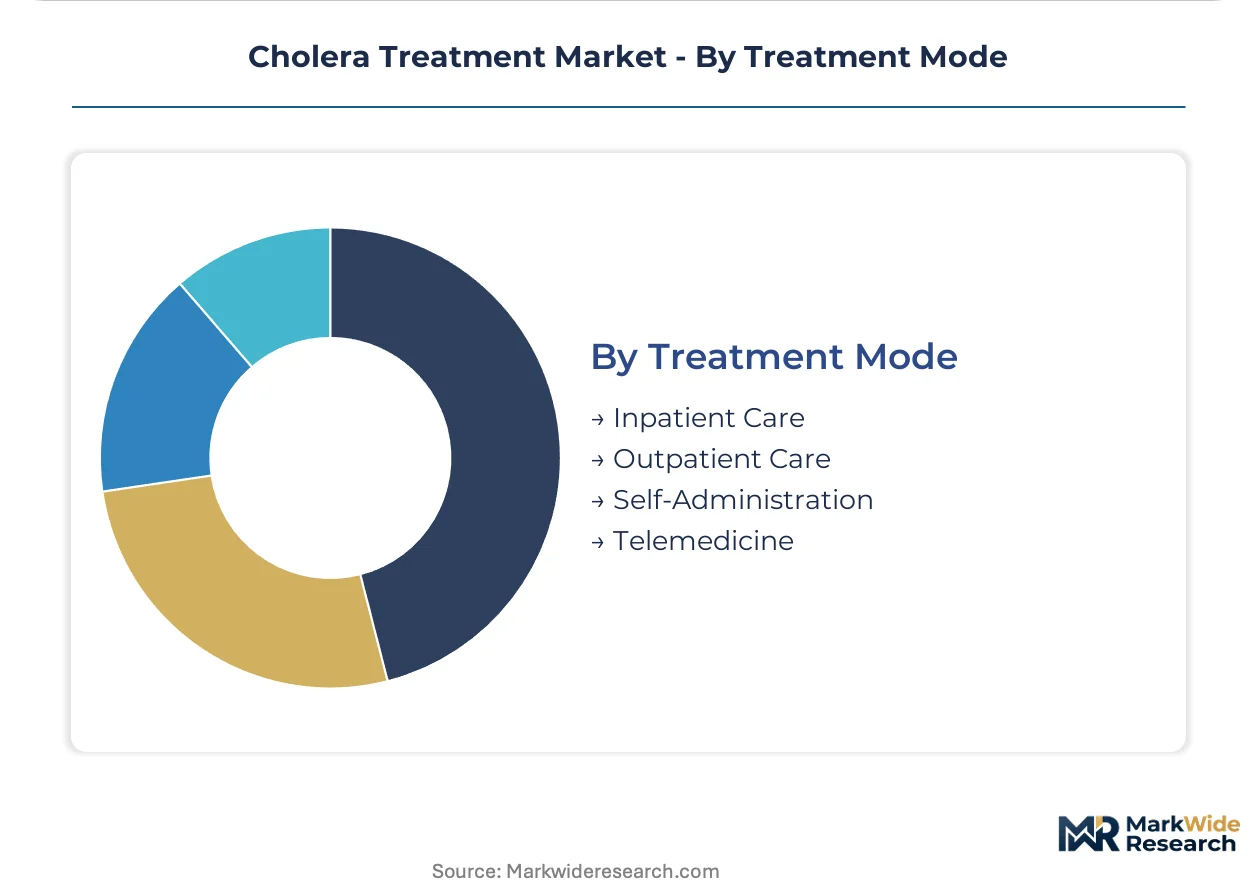
- Inpatient Care:IV fluid resuscitation and continuous monitoring for severe dehydration with shock. Hospital accreditation standards govern supplier qualification.
- Outpatient Care:Supervised ORS administration and antibiotic dispensing in clinic settings. Community health worker training investments shape protocol adherence.
- Self-Administration:Patient or caregiver-directed ORS preparation from sachets. Clear pictorial instructions determine compliance rates in low-literacy populations.
- Telemedicine:Remote symptom triage and treatment guidance via mobile platforms. Connectivity gaps in rural outbreak zones limit penetration despite protocol development.
Inpatient Care anchors acute revenue; Outpatient Care scales through health worker network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient manufacturing concentrates in Indian chemical clusters, while finished-dose formulation and prequalification expertise distributes across European and North American regulatory jurisdictions. Demand gravity follows outbreak patterns in tropical river deltas and conflict-affected urban corridors.
Bangladesh
The Ganges-Brahmaputra delta sustains the world's highest endemic cholera burden, with Dhaka's International Centre for Diarrhoeal Disease Research anchoring clinical trial infrastructure. The Directorate General of Drug Administration mandates WHO prequalification for all ORS tenders, eliminating non-certified suppliers from national procurement. Beximco Pharmaceuticals and Incepta Vaccine Limited operate formulation facilities in Tongi and Savar industrial zones.
Yemen
Protracted conflict has institutionalized emergency stockpile procurement through Sana'a-based central medical stores and Aden port logistics corridors. The national medicines regulatory authority defers to WHO emergency use assessment for outbreak response products. Hudaydah and Mukalla serve as distribution nodes for Red Sea coastal deployment.
Haiti
Post-earthquake reconstruction has centralized cholera treatment procurement through Port-au-Prince ministry of health warehouses. The national regulatory authority requires stability testing at 40°C for all imported rehydration products. Cap-Haïtien and Gonaïves function as northern supply hubs for Artibonite Valley outbreak response.
India
Bulk azithromycin and ciprofloxacin API production clusters in Hyderabad's Patancheru-Bollaram pharmaceutical corridor and Ahmedabad's Changodar belt. CDSCO batch-release automation has compressed domestic ORS clearance timelines from 90 to 45 days. Pune and Baddi house WHO-prequalified finished-dose facilities serving export markets.
United States
Emergency response stockpile procurement flows through the Strategic National Stockpile and CDC-directed deployment protocols. FDA export-grade antibiotic specifications govern finished-dose quality for international tender participation. Maryland and North Carolina host vaccine development clusters with biodefense contracting expertise.
Cholera Treatment Market Competitive Environment
Global majors compete with regional champions across prequalification velocity and stockpile fulfillment capacity. The supplier base stratifies into three tiers: multinational pharmaceutical conglomerates with dedicated vaccine divisions, mid-scale generic manufacturers with WHO-certified facilities, and emergency-response specialists focused on government contracting. Consolidation pressure intensifies as procurement centralization favors suppliers with multi-country registration portfolios. Capacity expansion and strategic partnerships represent the dominant competitive moves, with technology licensing gaining traction for heat-stable formulation access.
Within the multinational tier, Sanofi and GlaxoSmithKline plc exemplify archetypes of vaccine infrastructure leverage and differentiated formulation technology respectively. Emergent BioSolutions Inc occupies a position as the government contract fulfillment specialist, anchoring emergency response procurement channels. These three entities represent distinct strategic postures: Sanofi leverages established immunization program relationships, GlaxoSmithKline plc competes through product-specific technical differentiation, and Emergent BioSolutions Inc concentrates on surge capacity guarantees for stockpile managers.
| Leading Market Players |
|---|
| Sanofi |
| Valneva SE |
| Emergent BioSolutions Inc |
| EUBIOLOGICS CO., LTD |
| Astellas Pharma Inc |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Merck & Co. |
| Sun Pharmaceutical Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Regulatory affairs specialists concentrated in Hyderabad and Pune pharmaceutical clusters command wage premiums that compress supplier margins at the mid-tier, widening spreads between WHO-prequalified premium offerings and standard-grade alternatives. Labor-cost differentials between certified and uncertified manufacturing facilities directly translate into pricing-tier stratification across endemic-country tenders.
Pricing Analysis
Guaranteed availability clauses bundled into emergency response contracts command substantial premiums over unbundled commodity procurement. Three-tier pricing structure across premium, standard, and economy levels separates WHO-prequalified stockpile-grade products from domestically certified alternatives and informal channel generics. Pricing pressure stems from procurement centralization into Gavi-funded consortia that aggregate demand from multiple endemic nations. Government agencies in Bangladesh and Yemen exhibit lowest price sensitivity due to donor-funded procurement, while out-of-pocket retail purchasers in informal channels demonstrate acute cost consciousness.
Supply Chain Analysis
Formulation chemists and quality assurance auditors are scarce in Baddi and Changodar manufacturing belts, constraining expansion timelines for finished-dose facilities. Bulk azithromycin API production centers on Hyderabad's Patancheru corridor, while oral rehydration salt compounding clusters in Ahmedabad and Pune. Supply chain risk hinges on single-source dependency for heat-stable formulation excipients imported from European specialty chemical suppliers. Distribution runs through ministry of health central medical stores in Dhaka, Sana'a, and Port-au-Prince, with last-mile deployment via community health worker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cholera treatment market is executing a technology-transition phase as low-osmolarity oral rehydration salts displace legacy standard-ORS formulations in national essential medicines lists. This substitution mandates capital retooling for incumbent manufacturers while opening white-space for entrants with purpose-built low-osmolarity production lines.
For Market Incumbents: Anticipate accelerated prequalification renewal cycles by embedding dedicated WHO liaison functions within regulatory affairs teams. Sanofi and GlaxoSmithKline plc demonstrate archetypal defensive positioning through vaccine infrastructure leverage and heat-stable formulation differentiation respectively. Capacity addition in WHO-prequalified Indian facilities anchors long-term contract visibility against emerging regional competitors.
For New Entrants and Emerging Players: Begin with zinc-ORS co-packaging tenders targeting pediatric protocols in Bangladesh and Yemen, where bundled product formats face limited qualified competition. Drone delivery corridor partnerships with aerial logistics providers offer the most penetrable go-to-market angle for bypassing road infrastructure gaps in flood-prone regions.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale generic manufacturers possessing WHO-certified facilities and multi-country registration portfolios given procurement centralization into single-source awards. Acquisition targets should demonstrate established quality systems capable of tropical-stability validation. The signal to watch is CDSCO batch-release automation adoption rates as a proxy for Indian regulatory efficiency improvements.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Renewal Investment | Accelerated three-year cycles favor manufacturers with dedicated regulatory affairs infrastructure. |
| Heat-Stable Formulation Licensing | Technology access agreements with GlaxoSmithKline plc unlock cold-chain-independent rural distribution. |
| Zinc-ORS Co-Packaging Development | Bundled pediatric formats capture premium positioning under revised WHO guidelines. |
| Drone Delivery Corridor Partnership | Aerial logistics integration compresses emergency response times in Yemen and Haiti flood zones. |
| Backward Integration into API Supply | Captive azithromycin production mitigates single-source concentration risk from Patancheru manufacturers. |
Study Parameters
Independent corroboration across regulatory affairs directors, government procurement officers, and community health program managers underwrites the qualitative findings. Primary interviews with formulary committee members at Dhaka's International Centre for Diarrhoeal Disease Research, Sana'a central medical store administrators, and Port-au-Prince ministry of health warehouse operators supplied ground-truth validation. Secondary sources include WHO prequalification dossier databases, CDSCO batch-release records, and Gavi stockpile procurement disclosures. Bottom-up demand modeling from endemic-country tender awards reconciles against top-down market sizing from pharmaceutical trade flow analysis.
Comparable historical reference periods anchored the forecast window to post-2010 procurement centralization trends and prequalification standard evolution. Segmentation dimensions span product type, application channel, end-user procurement authority, and treatment mode across the projection horizon. CAGRs derive from regression analysis of tender award values against outbreak frequency indices and donor funding commitments. Forecast inputs incorporate stability testing mandate adoption timelines and heat-stable formulation penetration curves.
Underlying measurement precision varies by segment; emergency response stockpile valuations carry tighter precision than informal retail channel estimates due to documentation transparency. Forecasts reflect documented assumptions regarding WHO prequalification renewal timelines, donor funding continuity, and regulatory harmonization progress. Material deviation in outbreak frequency patterns, API supply disruptions, or procurement centralization pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Hypercalcemia Treatment Market
Medical Treatment
Non-Invasive Surgery Market
Medical Treatment
Infertility Treatment Market
Medical Treatment
Tauopathies Treatment Market
Medical Treatment
China Nose Reconstruction Market
Medical Treatment
Non-Infectious Diarrhea Treatment Market
Medical Treatment
Post-Operative Nausea and Vomiting (PONV) Market
Medical Treatment
Lysosomal Disease Treatment Market
Medical Treatment
US and Japan Platelet Rich Plasma Market
Medical Treatment
Surgical Procedures Volume Market
Medical Treatment
Isovaleric Acidemia Treatment Market
Medical Treatment
Otoplasty Market
Medical Treatment
Rotator Cuff Injury Treatment Market
Medical Treatment
Hyperphosphatemia Treatment Market
Medical Treatment
Global Hyperhidrosis Treatment Market
Medical Treatment
North America Chronic Disease Management Market