
 Middle East Electric Vegetable Chopper Market | 2026-2036
Middle East Electric Vegetable Chopper Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Electric Vegetable Chopper Market Insights
Smart motor control and blade-speed modulation is fragmenting the traditional single-speed electric chopper architecture into tiered performance categories. Philips leverages its appliance R&D network to sustain premium positioning across Gulf retail channels. Geepas anchors volume sales through hypermarket distribution dominance in the UAE and Saudi Arabia. Moulinex competes on European design heritage while Dessini specializes in price-accessible compact units for first-time buyers.
An electric vegetable chopper is a motorized countertop appliance employing stainless-steel cross blades or disc cutters driven by AC or DC motors ranging from 200W to 500W, designed to reduce manual chopping time for residential and commercial food preparation. Compact Choppers occupy the highest unit-volume position due to apartment-sized kitchen constraints prevalent across Gulf urban centers, while Multi-Function Choppers command margin premiums by integrating slicing, grating, and whisking attachments that reduce counter clutter. Heavy-Duty Choppers lead the restaurant and catering segment where continuous-duty cycles exceed fifty daily operations, and Mini Choppers address single-person households expanding across Riyadh and Jeddah.
SASO mandates energy-efficiency ratings and electrical safety certifications for all small appliances entering Saudi Arabia, while the UAE's Emirates Authority for Standardization and Metrology (ESMA) enforces ECAS conformity marks that block non-compliant imports at Dubai ports. These frameworks elevate compliance costs for budget manufacturers but create protected terrain for established brands with in-house certification teams. Stakeholders must monitor evolving Gulf Cooperation Council harmonization talks that could unify testing protocols across member states.
Market Dynamics
SASO energy-efficiency labeling mandates are compressing motor wattage ranges across Saudi Arabia, forcing manufacturers to redesign thermal management systems while UAE hospitality procurement teams demand continuous-duty cycles that strain compact chopper architectures.
Growth Catalysts
- Commercial Kitchen Automation:Restaurant chains across Dubai and Riyadh are replacing manual prep stations with motorized choppers to reduce labor dependency and standardize portion consistency during peak service windows.
- SASO Energy Labeling:Saudi Arabia's mandatory efficiency tiers are accelerating motor redesign investments, creating competitive separation between certified and non-compliant import suppliers.
- Apartment Downsizing:Gulf urban densification is concentrating demand for sub-2-liter bowl capacities that fit constrained counter spaces in Jeddah and Abu Dhabi high-rises.
Market Restraints
- Copper Winding Cost Volatility:AC motor stators depend on copper price stability, and Gulf currency pegs amplify input cost swings for manufacturers sourcing from Asian wire suppliers.
- Import Concentration Risk:Over-reliance on Shenzhen and Ningbo assembly clusters creates vulnerability to Red Sea shipping disruptions affecting Jebel Ali port throughput.
- Thermal Limitation:Compact chopper housings below 300W cannot sustain fifty-plus daily cycles without blade housing warping, restricting their deployment in hotel breakfast prep lines.
Strategic Opportunities
- Kuwait Catering Underpenetration:Institutional foodservice in Kuwait City remains dominated by manual processing, presenting first-mover advantage for continuous-duty chopper suppliers with local service networks.
- Smart Motor Convergence:Integration of Hall-effect sensors with variable-frequency drives enables torque-adaptive chopping that reduces vegetable bruising in fine-dining applications.
- Hypermarket Private Label:Carrefour and Lulu are expanding captive brand kitchen electrics, opening shelf space for OEM suppliers willing to co-develop exclusive motor specifications.
Industry Challenges
- ESMA Certification Timelines:UAE conformity assessment procedures for rotating electrical appliances currently extend sixteen to twenty weeks, delaying seasonal product launches.
- After-Sales Technician Scarcity:Motor rewinding and blade carriage alignment require specialized skills that Gulf vocational programs have not scaled to match appliance sales velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Electric Vegetable Chopper Market |
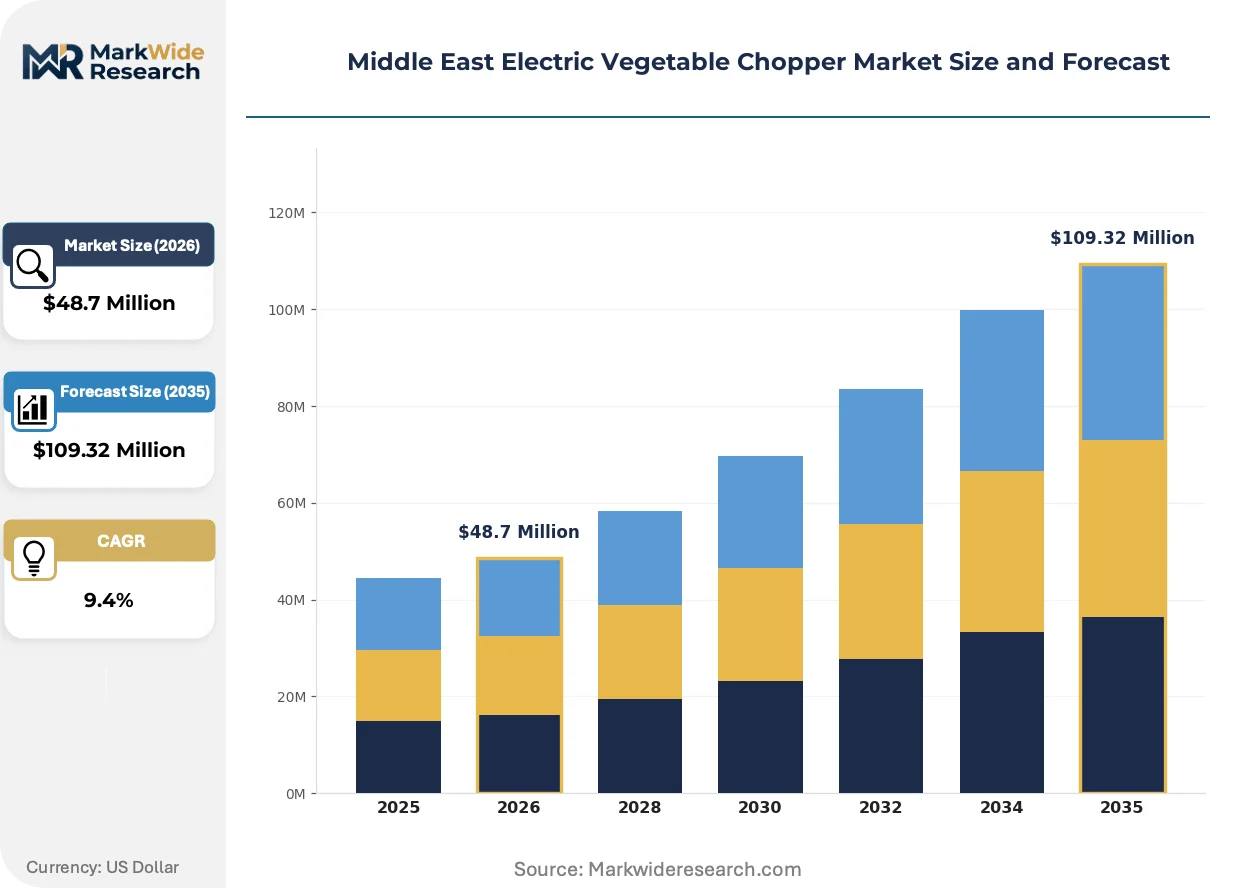
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $109.32 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Choppers, Multi-Function Choppers, Heavy-Duty Choppers, Mini Choppers End User: Households, Restaurants, Caterers, Food Processing Units Feature: Safety Lock, Multiple Speed Settings, Dishwasher Safe, Silent Operation Distribution Channel: Online Retailers, Hypermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Philips, Geepas, Afra Electronics, Black & Decker, Moulinex, Dessini, Group SEB, Kent RO, Kingston, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Electric Vegetable Chopper Market Trends and Innovations
Brushless DC motor architectures and sensor-based load detection are rewriting performance expectations across residential and commercial segments, compressing the traditional divide between home and professional-grade equipment.
Variable-speed inverter drives with torque feedback loops are rendering obsolete the single-speed induction motors that previously dominated sub-400W chopper categories. Saudi restaurant equipment buyers are specifying these units for soft-vegetable processing that demands blade speed modulation. The technology is compressing price premiums between entry-level and mid-tier product lines as controller costs decline.
SASO's 2024 update to small appliance safety standards is mandating double-insulation or grounded construction for all motorized food prep equipment entering Saudi Arabia. The regulation is elevating tooling costs for manufacturers but creating protected shelf space for brands with in-house EMC testing laboratories. UAE distributors are responding by consolidating supplier relationships around pre-certified product portfolios to avoid Dubai port detention.
Direct-to-hotel procurement teams are bypassing traditional kitchen equipment dealers in favor of manufacturer-aligned service contracts that bundle installation, staff training, and blade replacement schedules. This channel compression is most visible across Dubai's hotel corridor, where procurement directors negotiate multi-property supply agreements. The shift is squeezing margin for independent distributors who lack technical service capabilities.
Middle East Electric Vegetable Chopper Market Segmentation
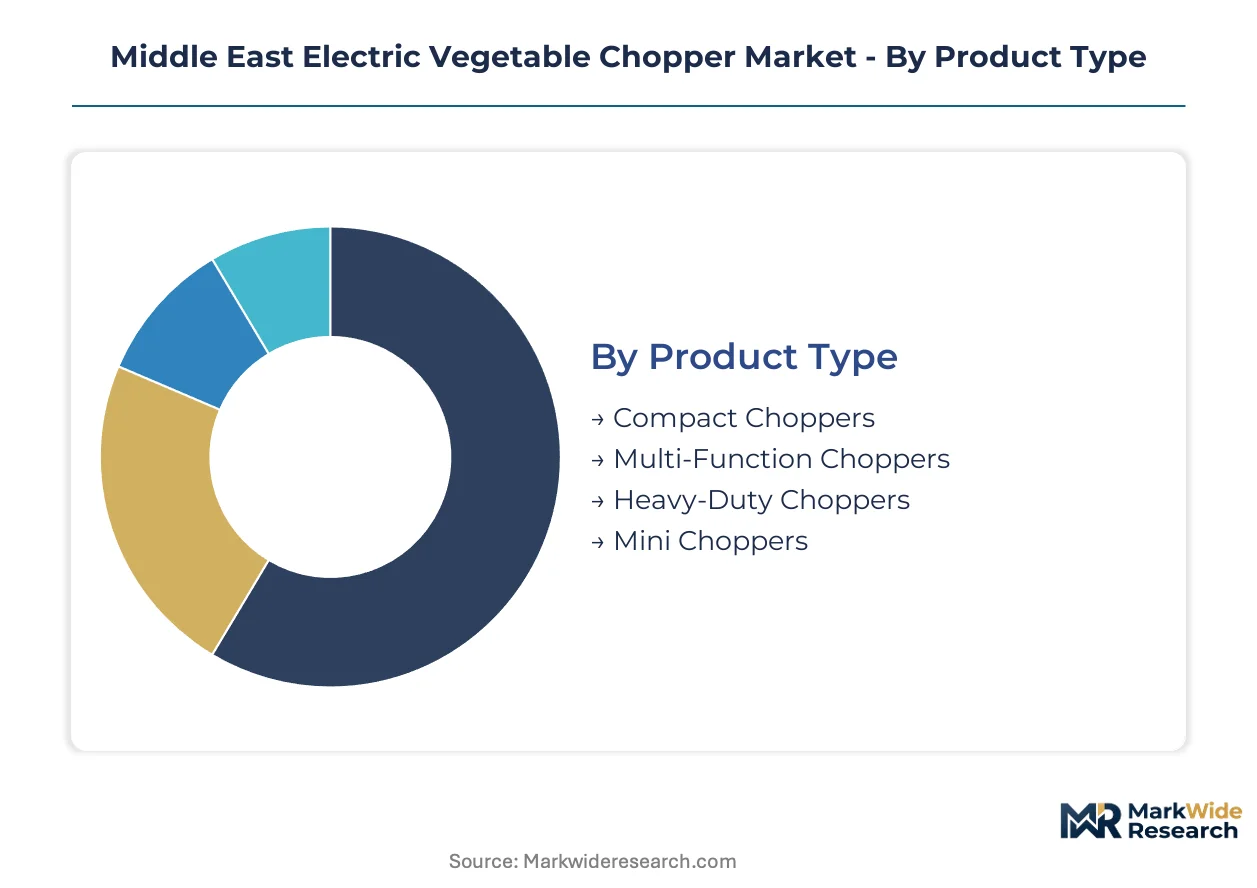
Segmentation in the Middle East electric vegetable chopper market reveals distinct procurement cycles and technical requirements across residential and commercial buyers. Kitchen space constraints and SASO energy regulations fragment demand into specialized product tiers with diverging replacement frequencies.
Product Type:
Compact Choppers turn inventory fastest in Gulf retail channels due to apartment-driven volume, while Heavy-Duty Choppers cycle slowest through restaurant procurement committees with extended evaluation periods.
- Compact Choppers:These units employ 200-300W AC induction motors and sub-2-liter polycarbonate bowls engineered for Gulf urban kitchen dimensions. Demand concentrates across Dubai and Abu Dhabi high-rise residential towers where counter depth rarely exceeds 45 centimeters and SASO efficiency labeling favors lower-wattage designs.
- Multi-Function Choppers:Modular attachment systems integrate slicing discs, grating drums, and whisking spindles that reduce single-purpose appliance clutter. Saudi Arabian household buyers in Riyadh and Jeddah prioritize these units for Ramadan meal preparation volumes that strain single-blade architectures.
- Heavy-Duty Choppers:Continuous-duty 400-500W brushless DC motors with thermal cutout protection serve hotel breakfast prep lines across the UAE hospitality corridor.
- Mini Choppers:Single-serving 150-200W units address expanding solo-occupant households in Riyadh's northern districts and Jeddah's Al-Hamra district.
Compact Choppers anchors the volume base while Multi-Function Choppers gains share at the steepest rate.
End User:
Cost tier differentiation separates specification-intensive commercial buyers from price-sensitive residential purchasers with diverging service contract expectations.
- Households:Individual buyers prioritize bowl capacity-to-wattage ratios and dishwasher-safe componentry for daily vegetable prep in Saudi and Emirati homes. Jeddah and Dubai Marina apartment dwellers drive replacement demand every 3-4 years as motor brush wear accumulates.
- Restaurants:Dubai's hotel corridor procurement teams specify continuous-duty cycles exceeding fifty daily operations with manufacturer-aligned service contracts that bundle blade replacement schedules. These buyers bypass traditional kitchen equipment dealers in favor of direct manufacturer relationships that compress independent distributor margins.
- Caterers:Kuwait City institutional foodservice operators remain manual-processing dependent, presenting expansion opportunity for continuous-duty suppliers with local technician networks.
- Food Processing Units:Central kitchen facilities in Saudi Arabia's Qassim Region date processing industry require industrial-grade feed chutes and stainless-steel construction for hygiene compliance.
Households dominate absolute unit shipments while Restaurants expands most quickly as labor substitution accelerates across Gulf hospitality.
Feature:
Application context determines which functional attributes command premium positioning versus baseline inclusion.
- Safety Lock:Interlocking bowl-motor engagement mechanisms prevent blade activation when lids are unsecured. SASO's 2024 small appliance safety standards mandate double-insulation or grounded construction that elevates tooling costs but protects shelf space for certified suppliers.
- Multiple Speed Settings:Variable-frequency inverter drives with Hall-effect sensor feedback enable torque-adaptive chopping that reduces vegetable bruising in fine-dining applications across Dubai's restaurant sector.
- Dishwasher Safe:Polycarbonate bowl and blade carriage materials withstand Gulf municipal water temperatures and detergent chemistries for residential convenience.
- Silent Operation:Brushless DC motor architectures with noise-dampening housings address open-plan kitchen layouts prevalent in premium Saudi residential developments.
Safety Lock functions as table-stakes inclusion while Multiple Speed Settings climbs the fastest as restaurant buyers specify soft-vegetable processing capability.
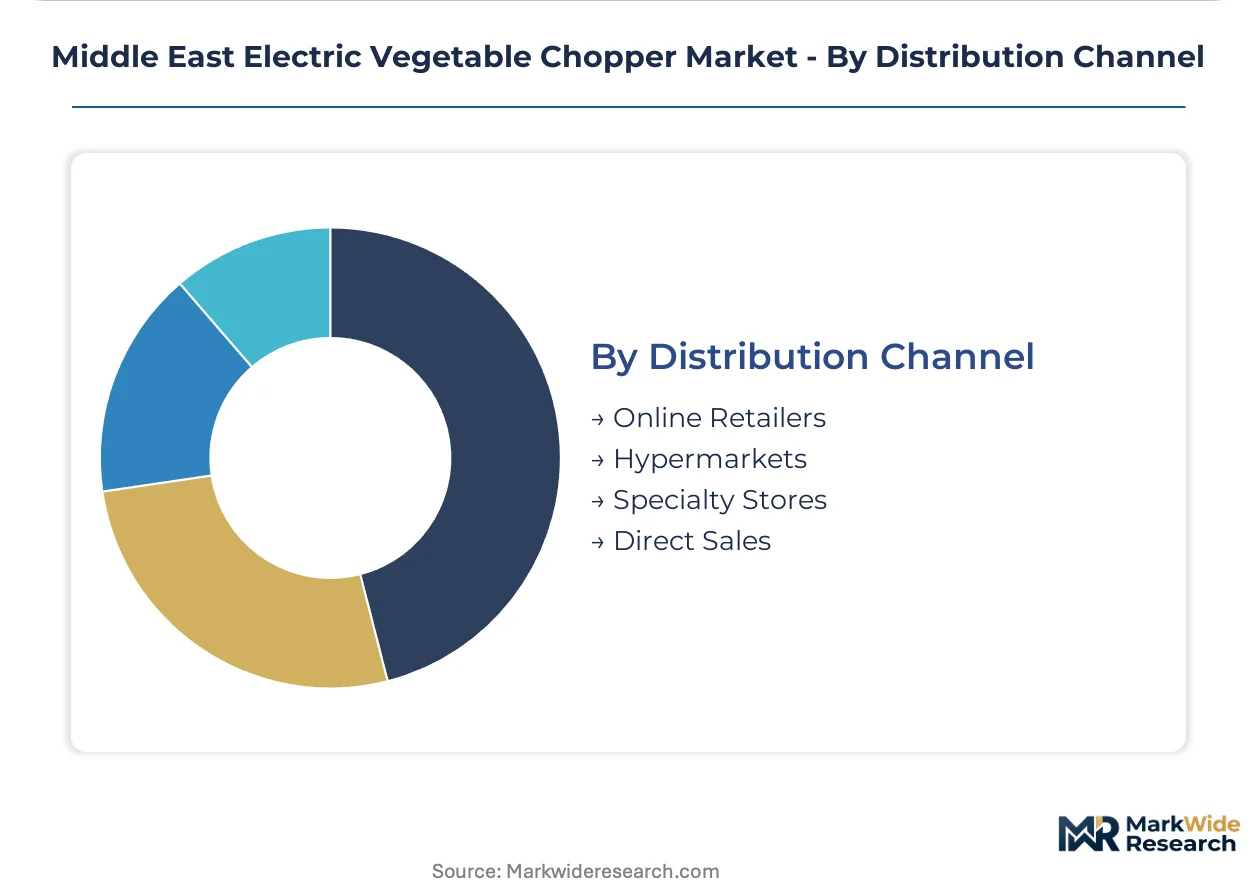
Distribution Channel:
Geography and buyer type fragment channel preference between digital convenience and tactile evaluation requirements.
- Online Retailers:Amazon.ae and Noon.com capture Riyadh and Jeddah residential buyers seeking specification comparison and doorstep delivery for compact chopper categories. Return logistics complexity limits heavy-duty commercial penetration.
- Hypermarkets:Carrefour and Lulu Hypermarket dominate UAE and Saudi Arabia volume through captive private label expansion and in-store demonstration capacity that drives impulse conversion for first-time buyers.
- Specialty Stores:Kitchen equipment dealers in Dubai's Deira district and Riyadh's Olaya district serve restaurant procurement teams with hands-on motor torque evaluation.
- Direct Sales:Manufacturer-aligned technical service contracts bypass traditional distribution for hotel chain multi-property agreements across the Abu Dhabi-Dubai corridor.
Hypermarkets anchors the volume base while Direct Sales gains share at the steepest rate as procurement channel compression accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East electric vegetable chopper market operates on a net import basis, with finished appliances flowing from Shenzhen and Ningbo assembly clusters through Jebel Ali and Dammam ports while local distribution networks capture value through certification handling and service contract bundling.
United Arab Emirates
Dubai's hotel corridor procurement teams specify continuous-duty choppers with manufacturer-aligned service contracts that bundle blade replacement schedules. ESMA enforces ECAS conformity marks that block non-compliant imports at Dubai ports, elevating compliance costs for budget manufacturers. Abu Dhabi's hospitality sector concentrates demand in the premium heavy-duty segment where multi-property supply agreements compress independent distributor margins.
Saudi Arabia
SASO energy-efficiency labeling requirements are pushing manufacturers toward lower-wattage motor designs across Riyadh and Jeddah retail channels. The 2024 update to small appliance safety standards mandates double-insulation or grounded construction for all motorized food prep equipment. Jeddah's Al-Hamra district and Riyadh's northern districts drive mini chopper demand from expanding solo-occupant households.
Kuwait
Institutional foodservice in Kuwait City remains dominated by manual processing, presenting first-mover advantage for continuous-duty chopper suppliers with local service networks. The country's national standards body enforces electrical safety certifications that parallel Gulf Cooperation Council harmonization talks. Catering operators in the capital show limited penetration of automated food prep equipment despite labor cost pressures.
Qatar
Hospitality infrastructure expansion around Doha drives specification-intensive procurement for hotel breakfast prep lines requiring fifty-plus daily operation cycles. The national regulator enforces conformity assessment procedures for rotating electrical appliances that extend import timelines. Premium residential developments in West Bay and The Pearl-Qatar incorporate open-plan kitchen layouts that favor silent-operation brushless DC motor architectures.
Middle East Electric Vegetable Chopper Market Competitive Landscape
On the supply side, the industry is structured around three tiers: premium brands with in-house certification teams, volume players leveraging hypermarket distribution dominance, and price-accessible specialists targeting first-time buyers. Strategic archetypes include the European design heritage positioning, the R&D-networked appliance conglomerate, and the compact-unit specialist. Competitive moves center on direct-to-hotel procurement channel compression and private label co-development with retail chains.
Within the premium-tier vector, Philips leverages its appliance R&D network to sustain positioning across Gulf retail channels. Geepas anchors volume sales through hypermarket distribution dominance in the UAE and Saudi Arabia. Moulinex competes on European design heritage while occupying a position that exemplifies the mid-market archetype balancing performance credentials with accessibility.
| Leading Market Players |
|---|
| Philips |
| Geepas |
| Afra Electronics |
| Black & Decker |
| Moulinex |
| Dessini |
| Group SEB |
| Kent RO |
| Kingston |
| Others |
Pricing and Supply Chain Analysis
Red Sea shipping disruption exposure determines both pricing tier spreads and supply chain shape across the Middle East electric vegetable chopper market, compressing margins for manufacturers reliant on Shenzhen and Ningbo assembly clusters while elevating landed costs for UAE and Saudi buyers.
Pricing Analysis
The technology-generation pricing gap between single-speed induction motor choppers and variable-frequency inverter-driven units spans approximately two performance tiers, with brushless DC architectures commanding premium positioning in Dubai's hospitality procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects SASO certification grade and after-sales service bundling rather than raw motor wattage alone. Cost compression in the economy tier intensifies because Geepas and Dessini compete on hypermarket shelf space with minimal differentiation. Restaurant procurement teams show least price sensitivity due to manufacturer-aligned service contract preferences, while first-time residential buyers in Jeddah and Riyadh exhibit highest elasticity.
Supply Chain Analysis
Export-control regime limitations on advanced motor controller semiconductors constrain flows of Hall-effect sensors and variable-frequency drive components to Gulf assembly operations, forcing manufacturers toward dual-sourcing strategies. Finished appliance production concentrates in China, Vietnam, and Malaysia, with polycarbonate bowl molding and copper stator winding as critical input dependencies. Single-source vulnerability around Shenzhen controller chip suppliers amplifies lead time volatility for ESMA-certified product lines. Distribution runs through Jebel Ali and Dammam port clusters into hypermarket and direct-to-hotel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality procurement teams across the UAE's hotel corridor, fragmenting traditional kitchen equipment dealer influence and compressing independent distributor margins in commercial segments.
For Market Incumbents: Harden certification infrastructure against SASO's evolving energy-efficiency tiers by investing in in-house EMC testing laboratories that accelerate product approval timelines. Deepen backward integration into brushless DC motor controller supply to reduce dependency on constrained semiconductor flows from Asian suppliers. Channel control through direct-to-hotel service contract bundling defends positioning against emerging OEM competitors. For New Entrants and Emerging Players: Kuwait City institutional catering represents the most penetrable entry point, with manual processing dominance creating first-mover advantage for continuous-duty chopper suppliers willing to deploy local technician networks. Saudi Arabia's northern districts and Jeddah's Al-Hamra area offer secondary residential expansion for mini chopper specialists targeting solo-occupant household growth. A co-development partnership with Carrefour or Lulu private label programs provides shelf access without established brand equity. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors component-level specialists with brushless DC motor and sensor-integration capabilities over assembled-product brands. Long-term viability across the analysis window hinges on regulatory compliance infrastructure rather than manufacturing scale alone. The signal to watch is ESMA-SASO harmonization progress, which would consolidate certification costs and favor pre-compliant supplier portfolios. Cross-checking against customs throughput data at Jebel Ali is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Motor Controller Integration | Hall-effect sensor adoption enables torque-adaptive chopping for fine-dining applications in Dubai. |
| Hypermarket Private Label Co-Development | Carrefour and Lulu captive brands open shelf space for OEM suppliers with exclusive motor specifications. |
| Direct-to-Hotel Service Contract Bundling | Manufacturer-aligned technical support compresses independent distributor margins across the Abu Dhabi-Dubai corridor. |
| SASO Certification Infrastructure Investment | In-house EMC testing laboratories protect shelf space against port detention risks at Dammam. |
| Kuwait Technician Network Deployment | Local service capabilities address institutional catering underpenetration in Kuwait City. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs import records, ESMA certification databases, and SASO energy-efficiency labeling registries to validate market sizing assumptions. Interviews with restaurant procurement directors, hypermarket category buyers, appliance manufacturing engineers, and port logistics coordinators informed demand-side and supply-side dynamics. Bottom-up triangulation across product-type shipment estimates and top-down validation against Gulf retail channel revenue flows ensured cross-verified outputs.
Forecast inputs include motor technology adoption curves, SASO regulatory implementation timelines, and hospitality construction pipeline data across the projection horizon. Segmentation modeling spans product type, end user, feature set, and distribution channel dimensions with regional regulatory cluster overlays. CAGRs derive from fitted growth curves against historical appliance import velocity and projected replacement cycles. Brushless DC motor cost decline trajectories and copper price volatility assumptions inform margin compression scenarios.
Practitioners should monitor Red Sea shipping route stability and Gulf Cooperation Council harmonization talks for early signals of supply chain or regulatory revision. Forecasts reflect assumptions around ESMA certification timeline consistency and hospitality sector labor substitution rates. Cross-checking against Jebel Ali port throughput statistics and Saudi customs clearance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Mixers and Attachments Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
India Electric Vegetable Choppers Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Mixer Grinder Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Household Bread Machine Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Europe Electric Vegetable Chopper Market