
 Vapour Particle Barrier Market | 2026-2036
Vapour Particle Barrier Market Size, Share, and Industry Trends Forecast 2026-2036
Vapour Particle Barrier Market Analytics
Polyethylene is broadening its role as the dominant substrate in vapour particle barrier formulations, displacing conventional vinyl in high-performance construction envelopes. BASF SE leverages its polymer research infrastructure to sustain technical leadership in breathable membrane chemistry. Owens Corning anchors North American supply through vertically integrated fiberglass composite operations that feed barrier lamination lines. DuPont differentiates via fluoropolymer expertise inherited from decades of industrial film development.
A vapour particle barrier is a controlled-permeability membrane or coating engineered to block liquid water and airborne particulates while permitting water vapour diffusion, typically achieving permeance ratings between 1 and 10 perms depending on polymer density and reinforcement. These barriers protect building assemblies, electronic housings, and vehicle cabins from moisture-driven degradation, corrosion, and microbial contamination. Membrane products command the largest revenue pool among product types due to established contractor familiarity and code-mandated installation in commercial roofing, though coating formats are gaining traction in automotive underbody and aerospace fuel cell sealing where substrate geometry prevents sheet application. Polyethylene leads material consumption by volume for cost-sensitive construction tiers, while polyester films capture premium electronics and aerospace segments demanding dimensional stability across temperature cycling.
EPA regulations on volatile organic compound emissions from adhesive and sealant formulations are reshaping solvent-based product lines toward waterborne and hot-melt alternatives. REACH restrictions on phthalate plasticizers and halogenated flame retardants are forcing European manufacturers to reformulate vinyl-based barriers or pivot toward polypropylene and polyester substrates. OSHA permissible exposure limits for isocyanates in spray-applied coatings are tightening installation protocols and driving demand for pre-fabricated membrane systems. Stakeholders must monitor evolving building energy codes that increasingly couple air tightness with vapour management, as jurisdictions reward or mandate combined air-and-vapour control layers that compress traditional multi-product specifications into unified barrier systems.
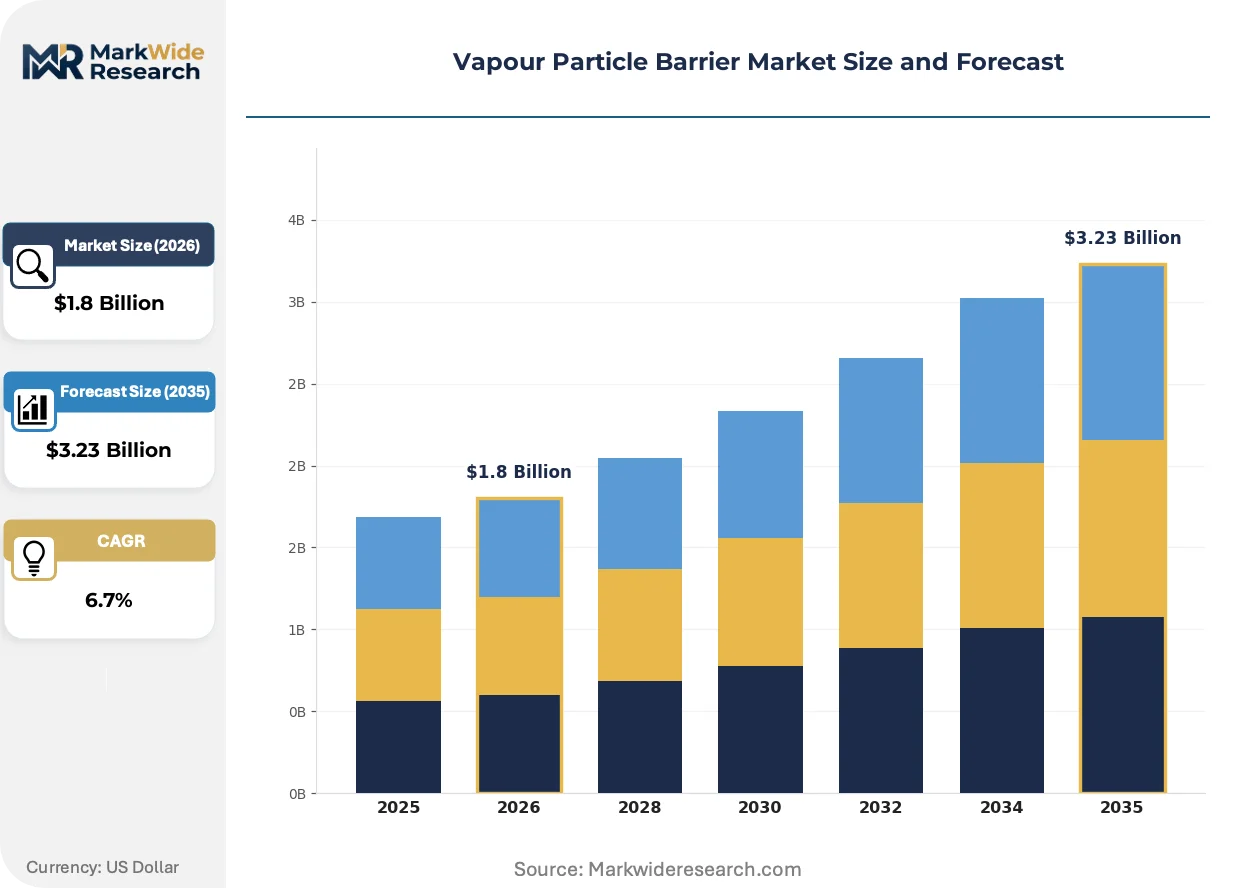
Market Dynamics
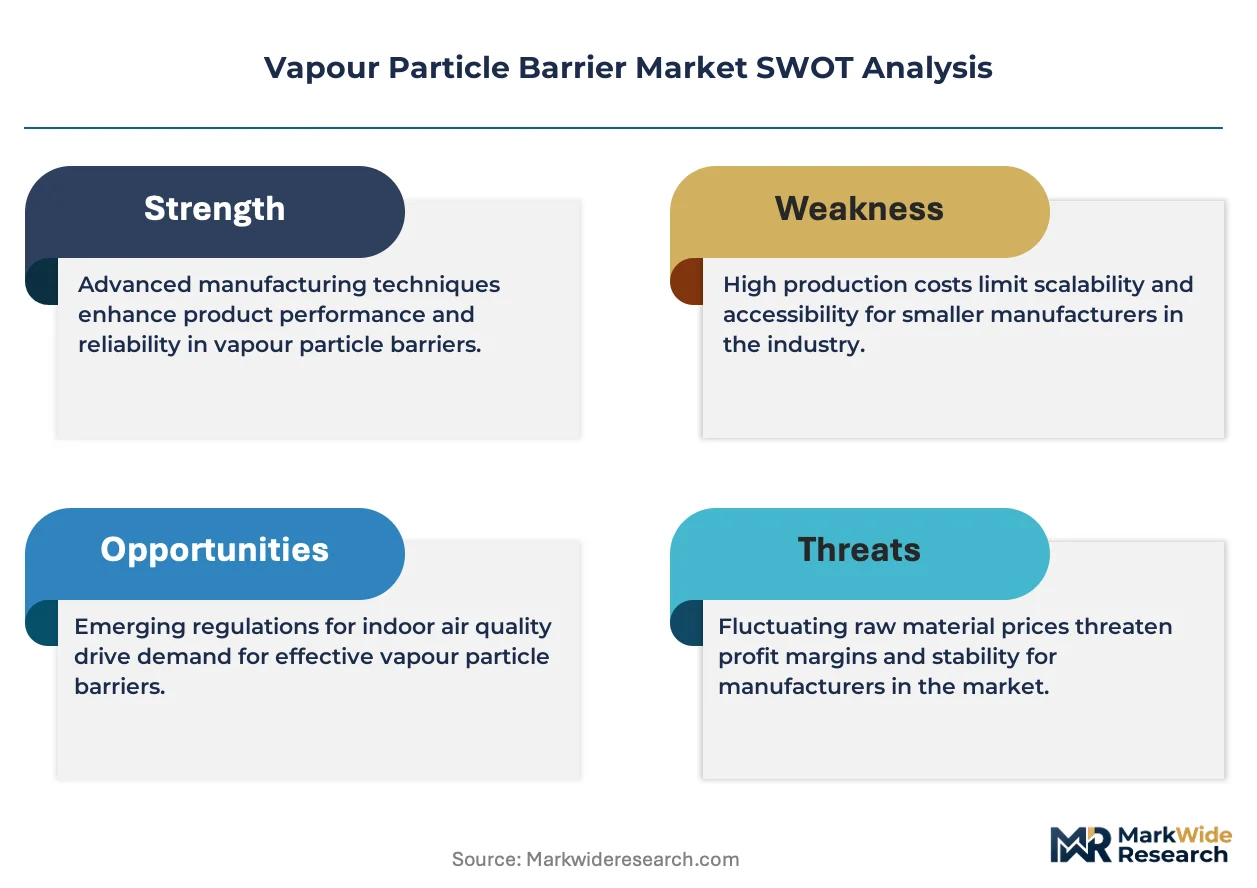
Pharmaceutical cleanroom construction is compressing specification cycles for vapour particle barriers, forcing membrane suppliers to validate performance data faster while maintaining EU F-Gas and REACH compliance across multiple substrate chemistries.
Growth Catalysts
- Cleanroom Construction Surge:Biotech facility builds in Germany's industrial corridor are specifying high-performance polyethylene barriers for contamination control. Contractors now bundle air-and-vapour control layers to meet tightening energy codes.
- REACH-Driven Reformulation:ECHA restrictions on phthalate plasticizers are accelerating polyester and polypropylene adoption in European barrier formulations. Manufacturers pivoting early capture specification lock-in from institutional buyers.
- Automotive Underbody Sealing:Spray-applied coating formats are penetrating electric vehicle battery enclosures where membrane sheets fail on complex geometries. Tier-1 suppliers in Stuttgart and Wolfsburg are qualifying these systems.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene price swings compress margin buffers for polyethylene-dominant barrier producers. European converters face particular exposure due to naphtha-cracker economics.
- Isocyanate Exposure Limits:OSHA permissible exposure thresholds for spray-applied polyurethane coatings are tightening installation protocols in the US. Contractors face equipment upgrade costs or shift toward pre-fabricated membrane systems.
- Fluoropolymer Substitution Pressure:Per- and polyfluoroalkyl substance scrutiny under EU F-Gas Regulation is forcing reformulation of premium breathable membranes. Performance gaps in water repellency persist with silicone alternatives.
Strategic Opportunities
- Aerospace Fuel Cell Sealing:Hydrogen propulsion systems in commercial aviation require vapour barriers with extreme temperature cycling resistance. Toulouse and Hamburg airframe clusters represent concentrated qualification activity.
- Combined Air-Vapour Control Layers:Building codes in Denmark and the Netherlands now mandate unified barrier systems. Suppliers with certified multi-function products bypass traditional multi-specification procurement.
- Electronics Miniaturization:Wearable device housings demand sub-micron particle barriers with moisture breathability. Japanese consumer electronics OEMs are qualifying polyester film laminates for next-generation product lines.
Industry Challenges
- Polymer Science Talent Scarcity:Formulation chemists with expertise in controlled permeability membrane design command premium compensation. German and Swiss technical universities produce insufficient graduates for industrial demand.
- Multi-Jurisdiction Certification Timelines:Simultaneous EPA VOC compliance, REACH substance registration, and CE marking for construction products extends product launch cycles. Smaller manufacturers lack regulatory affairs bandwidth for parallel filings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vapour Particle Barrier Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane, Coating, Sealant, Adhesive Material: Polyethylene, Polypropylene, Vinyl, Polyester Application: Construction, Automotive, Aerospace, Electronics End User: Contractors, Manufacturers, Distributors, OEMs |
| Companies Covered | BASF SE, Carlisle Companies, CertainTeed Corporation, DuPont, Holcim, Kingspan Group, Soprema Group, Owens Corning, W. R. Meadows, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vapour Particle Barrier Market Evolving Landscape
Breathable membrane chemistry is bifurcating between cost-optimized construction grades and precision-engineered electronics applications, with regulatory pressure on legacy materials accelerating substrate diversification.
Co-extruded multilayer polyethylene films with tuned pore structures are expanding into pharmaceutical cleanroom envelopes where vinyl barriers previously dominated. Facility engineers in Basel and Munich are specifying these systems for simultaneous particle filtration and moisture management. The technology is compressing traditional multi-membrane stackups into single-product installations, reducing labor cost and failure modes.
EU F-Gas Regulation phase-down schedules are forcing reformulation of hydrofluorocarbon-based breathable coatings. Membrane producers in Belgium and the Netherlands are accelerating silicone and bio-based polyurethane development. Construction segments face near-term supply constraints as qualification cycles lag regulatory deadlines by eighteen to thirty-six months.
Biotech procurement teams now require outcome-based performance guarantees rather than material specifications alone. Facility operators in Copenhagen and Stockholm are contracting for guaranteed cleanroom classification maintenance over ten-year horizons. German barrier suppliers are responding with integrated monitoring systems that validate in-situ permeability and particle retention.
Vapour Particle Barrier Market Segmentation
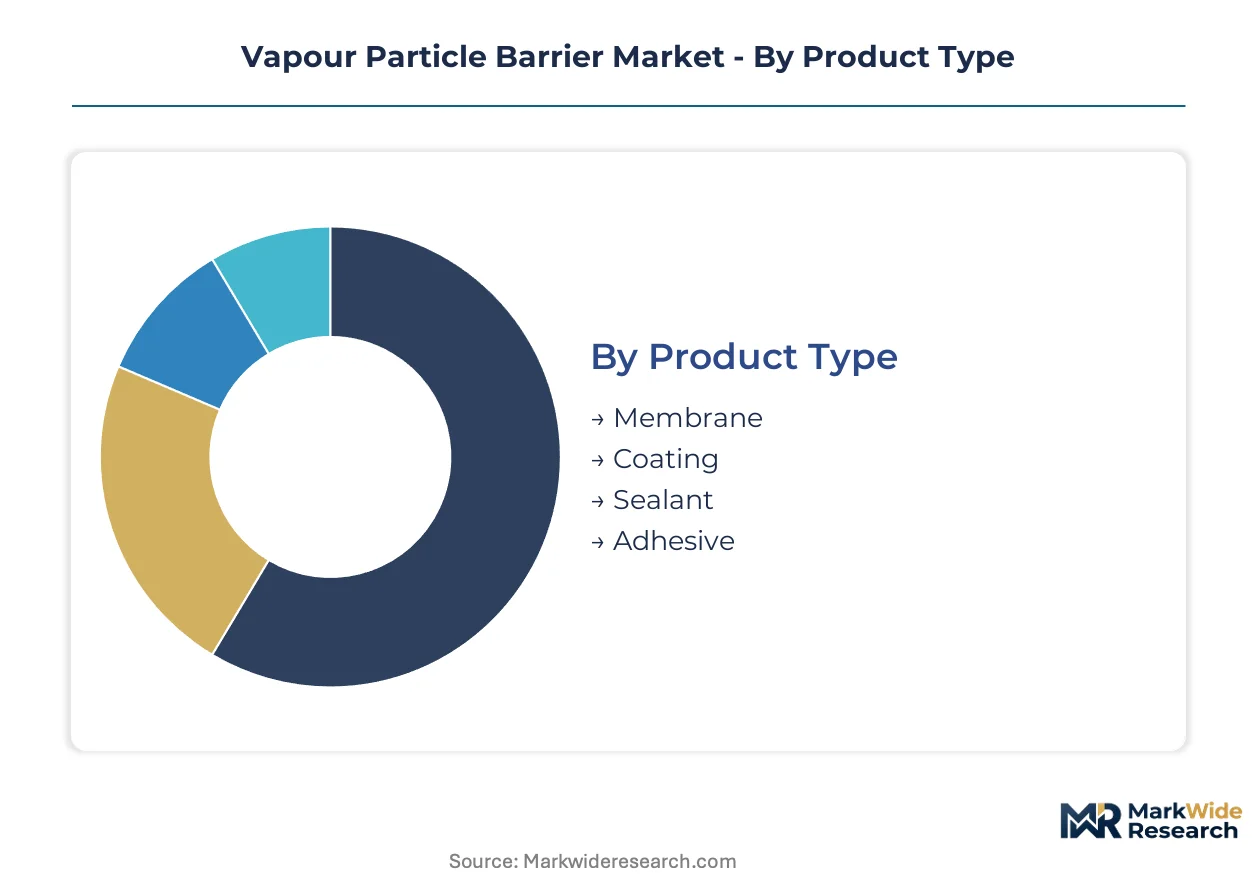
Vapour particle barrier procurement splits across four dimensions that determine specification cycles, margin structures, and regulatory exposure. Product format dictates installation labor intensity. Material chemistry governs REACH and F-Gas compliance pathways. Application verticals concentrate demand in geographically clustered facility builds.
Product Type:
Membrane suppliers in Germany's industrial corridor dominate installed capacity through vertically integrated extrusion and lamination operations.
- Membrane:Co-extruded multilayer films with tuned pore structures achieve 1-10 perm ratings for simultaneous liquid water blocking and vapour diffusion. Pharmaceutical cleanroom construction in Basel and Munich specifies these systems for single-product envelope solutions.
- Coating:Spray-applied polyurethane and silicone formulations penetrate electric vehicle battery enclosures in Stuttgart where complex substrate geometries prevent sheet membrane application. OSHA isocyanate exposure limits are tightening contractor equipment requirements.
- Sealant:Paste-consistency barriers with high solids content bridge membrane terminations and penetrations in commercial roofing assemblies. German facility engineers bundle these with primary air-vapour control layers.
- Adhesive:Pressure-sensitive and hot-melt formulations laminate barrier films to substrates in electronics housings and automotive interior panels. EPA VOC regulations are compressing solvent-based product lines.
Membrane absorbs the bulk of installed capacity; coating is expanding most quickly.
Material:
Feedstock cost tiers stratify supplier margins, with naphtha-cracker economics in Europe amplifying ethylene price volatility exposure.
- Polyethylene:Dominates construction-grade barrier volume through cost-optimized blown and cast film extrusion. REACH-compliant formulations without phthalate plasticizers are capturing specification lock-in from institutional buyers in Denmark and the Netherlands.
- Polyester:Biaxially oriented films with dimensional stability across temperature cycling serve premium electronics and aerospace segments. Japanese wearable device OEMs are qualifying sub-micron laminates for next-generation housings.
- Polypropylene:Random and block copolymer grades displace vinyl in European barrier formulations facing ECHA phthalate restrictions. Belgian and Dutch producers are accelerating qualification cycles.
- Vinyl:Flexible PVC barriers with legacy contractor familiarity are retreating to cost-sensitive construction tiers. Reformulation costs for REACH compliance are compressing margins for remaining producers.
Polyethylene commands the greatest production volume; polyester climbs the fastest on electronics qualification activity.
Application:
End-use concentration in facility construction creates demand lumpiness that favors suppliers with flexible extrusion assets.
- Construction:Commercial roofing and building envelope applications mandate code-compliant air-vapour control layers. Denmark and Netherlands building codes now require unified barrier systems that compress multi-product specifications.
- Automotive:Underbody sealing and battery enclosure protection in electric vehicles drive spray-applied coating adoption. Tier-1 suppliers in Wolfsburg and Stuttgart are qualifying these systems.
- Aerospace:Hydrogen fuel cell sealing in commercial aviation demands extreme temperature cycling resistance. Toulouse and Hamburg airframe clusters represent concentrated qualification pipelines.
- Electronics:Miniaturized housings for wearable devices require sub-micron particle barriers with moisture breathability. Japanese consumer electronics OEMs are driving polyester film specification.
Construction absorbs the bulk of installed capacity; aerospace gains share fastest on hydrogen propulsion timelines.
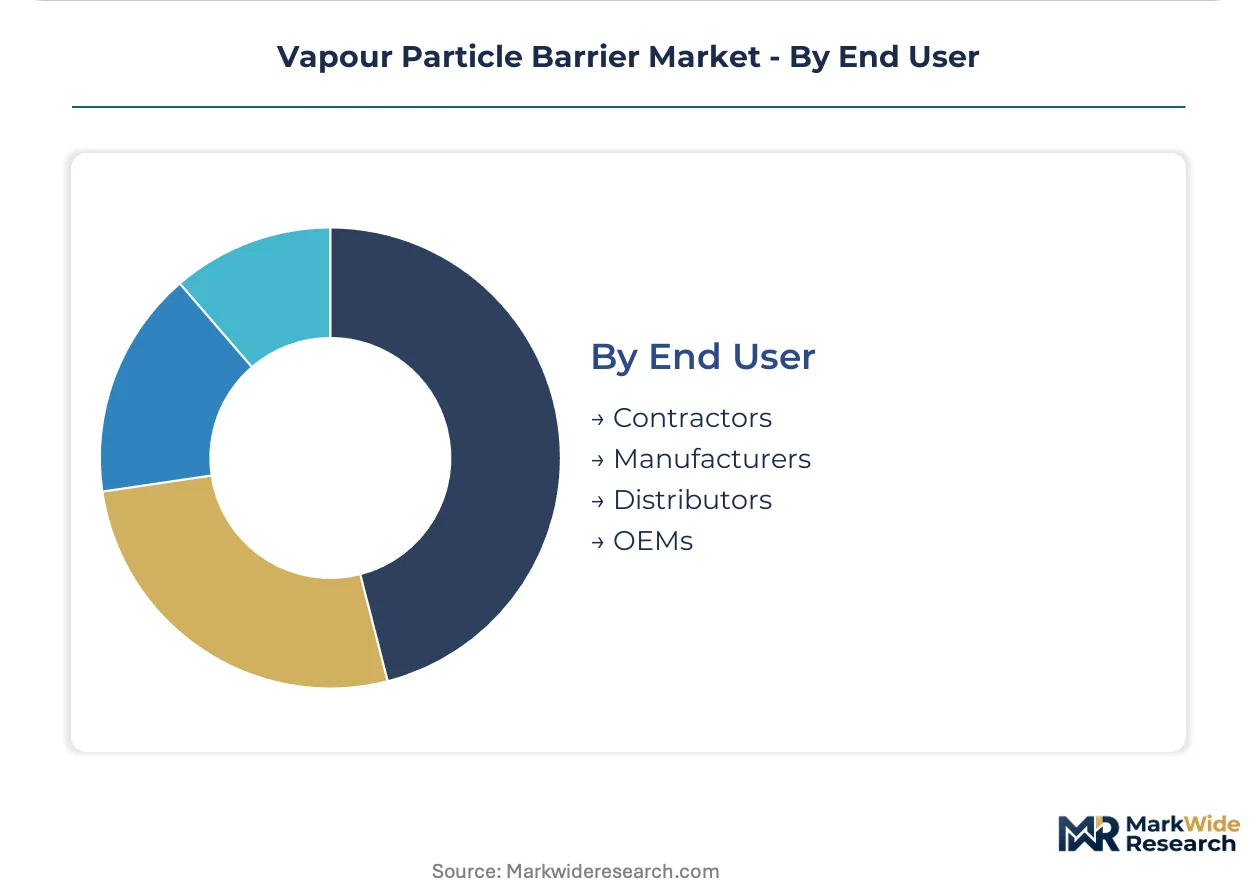
End User:
Procurement authority concentration among large facility operators and automotive OEMs compresses specification cycles and demands outcome-based performance guarantees.
- Contractors:Commercial roofing and building envelope installers purchase membrane rolls and accessory sealants through distribution. German contractors now bundle air-vapour control layers to meet tightening energy codes.
- Manufacturers:Tier-1 automotive and electronics producers specify barrier materials for in-house lamination and component assembly. Biotech facility operators in Copenhagen and Stockholm contract for ten-year cleanroom classification guarantees.
- Distributors:Construction supply and industrial distribution intermediaries stock standard membrane grades for contractor spot purchasing. Inventory exposure to ethylene price swings compresses working capital efficiency.
- OEMs:Original equipment manufacturers in automotive and electronics verticals qualify barrier materials for direct supply relationships. Aerospace OEMs in Toulouse and Hamburg drive qualification timelines for fuel cell sealing systems.
Contractors absorb the bulk of volume through distribution; OEMs are expanding most quickly on direct specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for vapour particle barriers concentrates in facility construction clusters where pharmaceutical cleanroom and precision manufacturing investments are accelerating. Germany's industrial corridor absorbs disproportionate specification activity, while regulatory divergence between EPA and REACH frameworks fragments supplier compliance strategies across Atlantic markets.
Germany
Biotech facility construction in Stuttgart and Munich drives specification of co-extruded polyethylene membranes for contamination control. EU F-Gas Regulation phase-down schedules force reformulation of hydrofluorocarbon-based breathable coatings. The Rhine-Main industrial cluster hosts concentrated qualification activity for combined air-vapour control layers.
United States
Commercial roofing contractors in the Southeast and Midwest bundle membrane systems to meet tightening energy code requirements. EPA volatile organic compound regulations on adhesive formulations compress solvent-based product lines toward waterborne alternatives. The Pacific Northwest electronics manufacturing corridor qualifies polyester film laminates for wearable device housings.
France
Aerospace hydrogen fuel cell sealing programs in Toulouse demand vapour barriers with extreme temperature cycling resistance. ECHA restrictions on phthalate plasticizers accelerate polyester and polypropylene adoption in barrier formulations. The Île-de-France region concentrates cleanroom construction for pharmaceutical contract manufacturing.
Japan
Consumer electronics OEMs in the Kanto region qualify sub-micron particle barriers with moisture breathability for next-generation wearable devices. METI industrial standards guide membrane performance specifications for precision manufacturing applications. Osaka-based automotive suppliers test spray-applied coating formats for electric vehicle battery enclosures.
Netherlands
Building codes in Randstad municipalities mandate unified air-vapour control layers that compress traditional multi-product specifications. REACH compliance requirements tighten material specifications for construction-grade barrier imports. Eindhoven's high-tech systems sector drives qualification of precision-engineered membrane laminates for electronics packaging.
Vapour Particle Barrier Market Competitive Landscape
Capacity expansion dominates the current landscape as suppliers position extrusion assets near pharmaceutical and automotive manufacturing clusters. The market structure tiers between integrated chemical conglomerates with captive polymer supply and specialized membrane fabricators focused on niche performance segments. Strategic archetypes include diversified materials giants leveraging polymer research infrastructure, vertically integrated building products suppliers controlling distribution channels, and regional specialists capturing specification lock-in through rapid qualification cycles. Portfolio diversification and geographic expansion constitute the dominant competitive moves, with manufacturers adding coating capabilities to complement membrane offerings and establishing technical service presence in biotech construction corridors.
Among European chemical conglomerates, BASF SE anchors the polymer science tier through its research infrastructure in breathable membrane chemistry. DuPont occupies a position in fluoropolymer-derived barrier technology inherited from decades of industrial film development. Owens Corning exemplifies the vertically integrated North American archetype, with fiberglass composite operations feeding barrier lamination capacity. These three represent distinct strategic positions: polymer innovation leadership, specialty materials heritage, and backward integration into reinforcement substrates.
| Leading Market Players |
|---|
| BASF SE |
| Carlisle Companies |
| CertainTeed Corporation |
| DuPont |
| Holcim |
| Kingspan Group |
| Soprema Group |
| Owens Corning |
| W. R. Meadows |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock volatility cascades through polyethylene-dominant barrier formulations, compressing margin buffers for European converters while amplifying price tier separation between REACH-compliant specialty grades and commodity construction membranes. Naphtha-cracker economics in the Rhine-Ruhr corridor tether converter pricing power to upstream petrochemical swings, forcing buyers into longer-term offtake contracts or spot-market exposure.
Pricing Analysis
Volume-mix splits across construction-grade polyethylene membranes and precision-engineered polyester films for electronics. Three-tier pricing structure across premium, standard, and economy levels separates certified cleanroom systems from commodity roofing barriers, with REACH-compliant formulations commanding tier premiums. Cost compression in standard-grade polyethylene is intensifying because of ethylene price swings, while aerospace and pharmaceutical buyers show lowest price sensitivity due to qualification lock-in.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale biotech facility demand in Germany and the Netherlands, while distribution networks serve contractor spot purchasing across construction segments. Supply concentrates in Germany, Belgium, and the Netherlands through vertically integrated extrusion and lamination assets. Raw material dependencies center on ethylene, propylene, and specialty polyester resins. Single-source vulnerability persists for fluoropolymer-derived breathable coatings facing EU F-Gas phase-down deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH compliance and F-Gas reformulation capabilities, with regulatory bandwidth scarcity forcing smaller manufacturers toward exit or acquisition.
For Market Incumbents: Anchor specification lock-in through integrated air-vapour control layer certification in Denmark and Netherlands building code jurisdictions. Deepen backward integration into captive polymer supply to buffer ethylene price volatility, while accelerating silicone-based coating qualification to offset fluoropolymer substitution pressure from EU F-Gas Regulation timelines. For New Entrants and Emerging Players: Launch via outcome-based performance contracting for biotech cleanroom operators in Copenhagen and Stockholm seeking ten-year classification guarantees. Target spray-applied coating formats for electric vehicle battery enclosures in Stuttgart, where complex geometries exclude incumbent membrane suppliers and OSHA isocyanate limits create equipment-upgrade barriers for established contractors. For Investors and Strategic Acquirers: ECHA phthalate restriction enforcement acceleration is the leading indicator that vinyl-barrier manufacturers with stranded reformulation costs will become distressed acquisition targets. Five-to-ten-year viability favors specialists with parallel EPA VOC and REACH compliance capabilities. Monitor Belgian and Dutch membrane producers for qualification cycle completion on polypropylene alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Extrusion asset additions near Stuttgart and Munich biotech corridors capture specification proximity. |
| Backward Integration | In-house ethylene sourcing buffers naphtha-cracker margin compression for European converters. |
| Green Manufacturing Transition | Bio-based polyurethane development aligns with EU F-Gas Regulation phase-down deadlines. |
| Long-term Supply Agreement | Offtake contracts with German automotive OEMs secure coating volume for battery enclosure programs. |
| Joint Venture | Partnerships with Swiss technical universities address polymer science talent scarcity in membrane design. |
Research Methodology
Independent corroboration across plant managers at extrusion facilities, procurement leads at biotech facility operators, and distribution channel partners underwrites the qualitative findings. Technical R&D directors at barrier manufacturers provided formulation roadmaps, while secondary validation drew from ECHA substance restriction filings, EU F-Gas Regulation implementation schedules, and customs data on polyethylene film trade flows. Bottom-up segment sizing and top-down market triangulation reconciled volume estimates across the analysis window.
Rate-of-change decomposition separated volume growth from price-mix effects across product type, material chemistry, application vertical, and end-user procurement channel dimensions. CAGRs were derived from segment-level growth trajectories weighted by revenue contribution, with pharmaceutical cleanroom construction timelines and electric vehicle battery enclosure adoption curves serving as primary demand-side inputs. Automotive qualification pipelines and aerospace fuel cell sealing programs provided cross-validation on coating format expansion.
Feedstock price spikes, regulatory deadline acceleration, and polymer science talent scarcity are the dominant revision risks to installed capacity and margin assumptions. Forecasts reflect documented assumptions on ethylene cost trajectories and REACH compliance transition timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Europe Portable Gas Detector Market
Detection and Regulation Devices
Radiometric Detectors Market
Detection and Regulation Devices
Neutron Detector Market
Detection and Regulation Devices
ESD Suppressors Market
Detection and Regulation Devices
Duct Smoke Detectors Market
Detection and Regulation Devices
Limiter Diodes Market
Detection and Regulation Devices
Microwave Leakage Detector Market
Detection and Regulation Devices
Chemical Detection Armband Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Hydrogen Leak Detector Market
Detection and Regulation Devices
Explosive Detectors Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Photoionization Detectors Market
Detection and Regulation Devices
Positive Temperature Coefficient (PTC) Thermistor Market
Detection and Regulation Devices
Wireless Gas Detection System Market