
 US Nurse Call Systems Market | 2026-2036
US Nurse Call Systems Market Size, Share, and Industry Trends Forecast 2026-2036
US Nurse Call Systems Market Insights
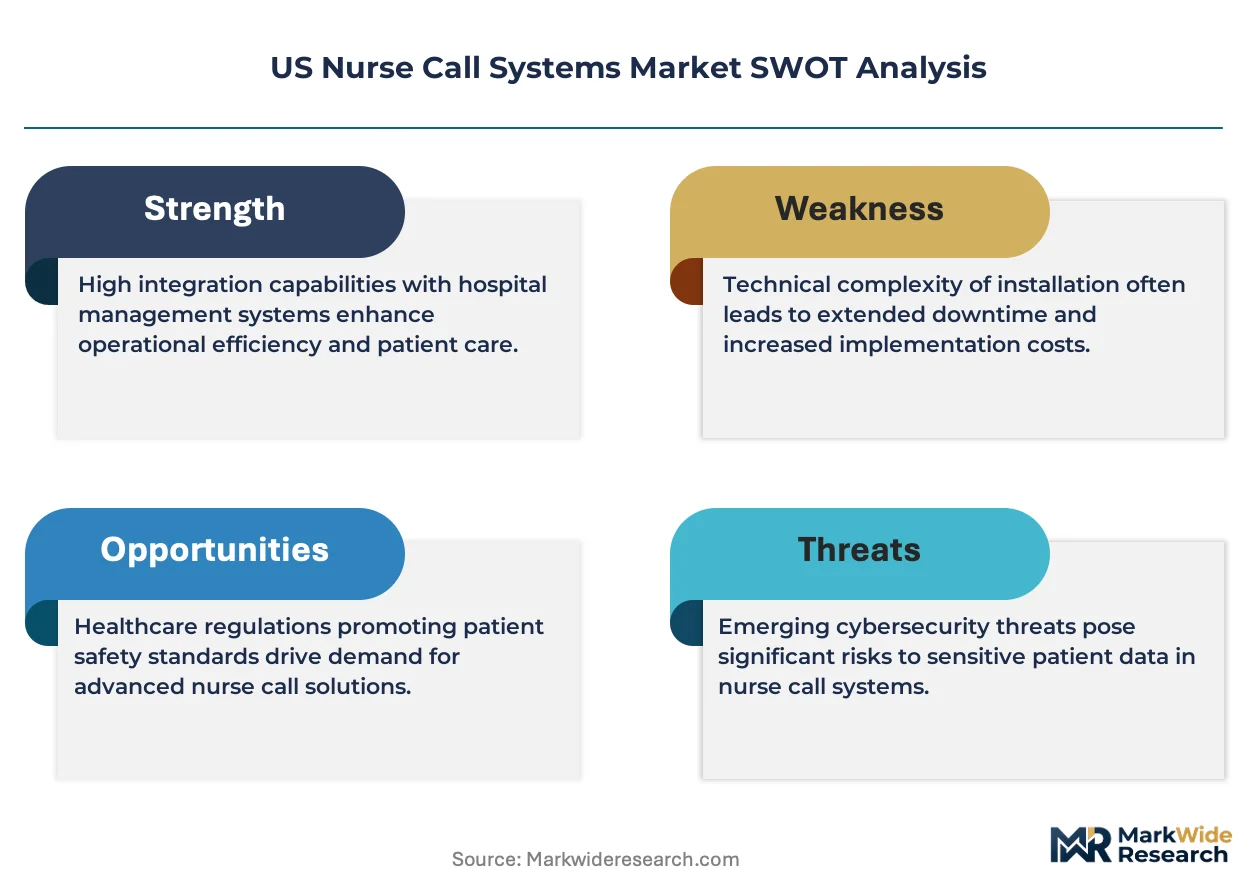
Joint Commission accreditation is reorganizing competitive access for US nurse call systems vendors, elevating patient safety and response-time metrics into procurement scorecards. Hill-Rom Services Inc. leverages its installed base across integrated delivery networks to sustain service revenue streams. Rauland-Borg Corporation anchors its position through specialized education and acute-care workflow expertise. Honeywell International Inc. competes on building-automation convergence, extending nurse call into broader facility management platforms.
Nurse call systems encompass bedside alert terminals, corridor dome lights, and central nurse console stations that route patient-initiated requests to assigned caregivers through hardwired, wireless, or IP-based architectures. These systems employ dual-tone multi-frequency signaling and priority-queuing algorithms to achieve sub-30-second response-time benchmarks in emergency code scenarios. IP-based system types capture expanding margin pools as Ethernet backbones displace legacy copper-loop infrastructure and enable EHR-adjacent workflow integration. Wireless technology segments built on Wi-Fi and Bluetooth protocols are displacing infrared and ultrasound alternatives in retrofit installations across long-term care and assisted living applications.
FDA 510(k) clearance requirements govern medical device classification for advanced nurse call peripherals, while CMS Conditions of Participation enforce minimum staffing-response documentation that shapes system specification. State-level Departments of Health in California, New York, and Texas impose additional fire-safety and electrical-code overlays that filter vendor eligibility. Stakeholders must monitor interoperability mandates from the Office of the National Coordinator for Health IT as these will determine which platform architectures retain reimbursement-adjacent relevance.
Market Dynamics
IP-based nurse call architectures are displacing legacy copper-loop infrastructure across acute care hospitals, compressing installation timelines and forcing incumbent vendors to rewrite service revenue models around software subscriptions rather than hardware replacement cycles.
Growth Catalysts
- CMS Conditions of Participation:Federal staffing-response documentation mandates compel hospitals to upgrade legacy systems with timestamped alert logging capabilities.
- Bluetooth Low Energy protocols:Wireless retrofit installations in assisted living facilities eliminate costly hardwiring while enabling wander-management integration.
- Sun Belt senior housing construction:Florida, Arizona, and Texas lead national bed additions, concentrating demand for scalable nurse call platforms.
Market Restraints
- Copper-loop infrastructure stranded assets:Acute care hospitals face write-down pressures when abandoning decades-old wired installations.
- FDA 510(k) clearance timelines:Advanced peripherals with biometric monitoring trigger medical device classification, extending commercialization by 12-18 months.
- Electrical contractor capacity constraints:Specialized low-voltage installation labor pools in California and New York limit deployment velocity.
Strategic Opportunities
- EHR-adjacent workflow convergence:Epic and Cerner interoperability modules position nurse call data as reimbursable clinical documentation.
- Micro-hospital formats:Compact emergency departments in Texas exurbs require modular, cloud-managed systems without on-premise server rooms.
- Joint Commission patient safety metrics:Response-time scorecards create procurement preference for vendors with predictive analytics.
Industry Challenges
- Biomedical engineering talent scarcity:Health systems compete with technology firms for IP-networking specialists capable of VLAN segmentation.
- Legacy system integration complexity:Pneumatic tube and patient television networks resist standard API protocols, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Nurse Call Systems Market |
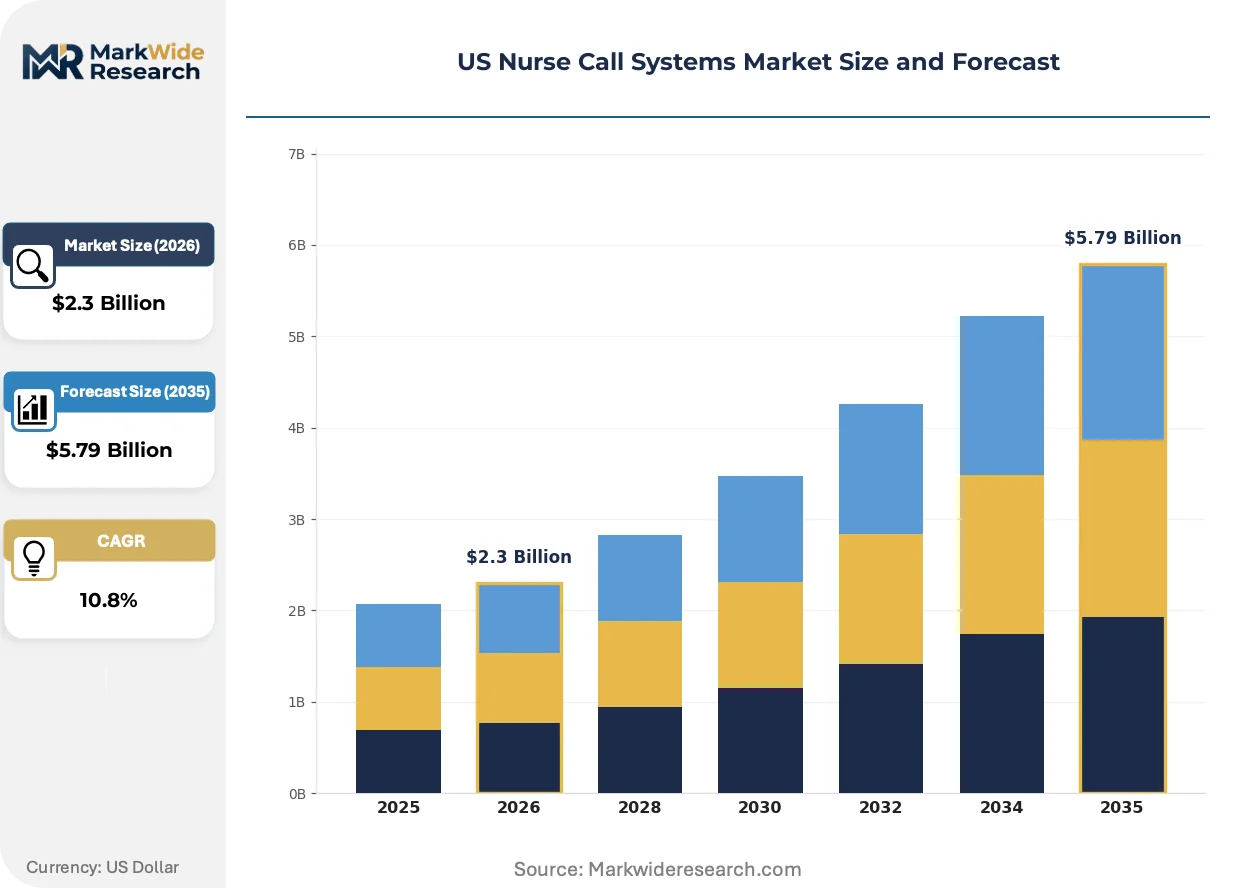
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Wired, Wireless, IP-Based, Hybrid Technology: Radio Frequency, Infrared, Ultrasound, Bluetooth, Wi-Fi Application: Hospitals, Long-Term Care, Assisted Living, Rehabilitation Centers End User: Nursing Facilities, Home Healthcare, Ambulatory Clinics, Senior Care Communities |
| Companies Covered | Hill-Rom Services Inc., Rauland-Borg Corporation, Honeywell International Inc., Ascom Holding AG, Stanley Healthcare, Cornell Communications, TekTone Sound and Signal Mfg., Inc., Jeron Electronic Systems, Inc., Critical Alert Systems LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Nurse Call Systems Market Trends and Innovations
Software-defined functionality is compressing hardware refresh cycles while elevating cybersecurity and interoperability to primary procurement criteria. Vendors now compete on platform extensibility rather than terminal durability.
Voice-activated bedside terminals are fragmenting traditional button-based alert hierarchies. Acute care nurses in teaching hospitals adopt hands-free calling during sterile procedures. This technology is fragmenting established response protocols by enabling parallel caregiver notification streams that bypass central console queuing.
FDA cybersecurity guidance for networked medical devices tightens premarket submission requirements for wireless nurse call peripherals. Manufacturers must document threat modeling and software bill of materials. Hospital procurement committees in California and Massachusetts now require SBOM disclosure as a contractual precondition.
Subscription-based service models displace capital expenditure purchasing in multi-site health systems. Chief financial officers favor operational expenditure treatment for infrastructure that refreshes every 36-48 months. This shift concentrates vendor selection authority within health system IT governance committees rather than facilities management departments.
US Nurse Call Systems Market Segmentation
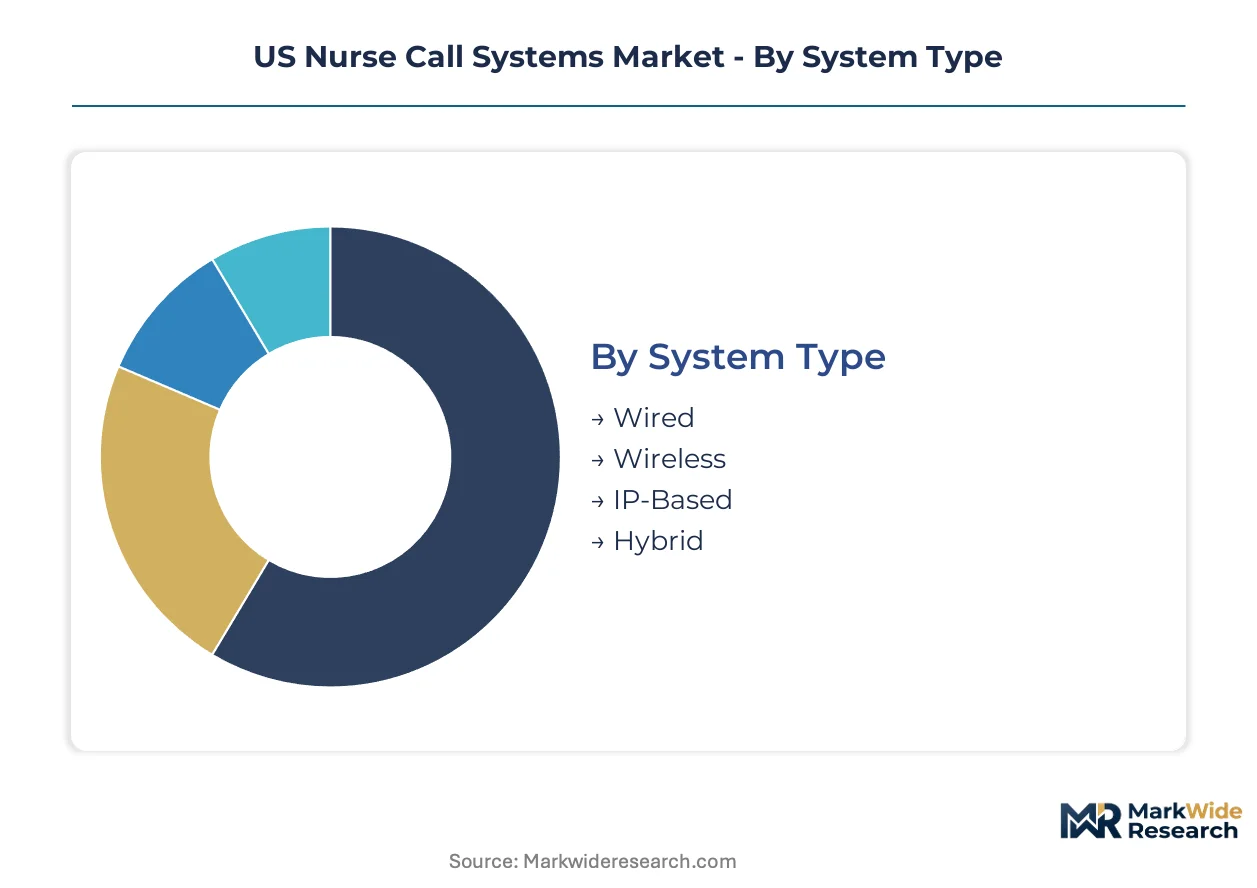
Segmentation in nurse call systems determines procurement pathways, installation complexity, and long-term service revenue structures. Technology choices lock facilities into specific upgrade trajectories, while application context shapes regulatory compliance requirements and response-time benchmarks.
System Type:
Margin pools concentrate in platforms that minimize infrastructure abandonment while enabling software-defined feature expansion.
- IP-Based:Ethernet backbone architecture eliminates dedicated copper-loop infrastructure and enables direct EHR integration through HL7 messaging protocols. Acute care hospitals in Texas and Florida are standardizing on IP-native platforms to satisfy Joint Commission documentation requirements while avoiding stranded asset write-downs.
- Wireless:Eliminates hardwiring costs in retrofit scenarios and supports rapid bed reconfiguration for surge capacity. Senior care communities across Arizona's Sun Belt corridor favor wireless deployments to accelerate occupancy ramp timelines without construction disruption.
- Wired:Legacy copper-loop installations persist in mid-century hospital infrastructure where conduit access permits incremental endpoint replacement.
- Hybrid:Bridges IP backbones with wireless peripherals to protect existing infrastructure investments during phased migration.
The dominant share belongs to IP-Based systems, while Wireless is closing the gap fastest in greenfield senior housing construction.
Technology:
Protocol selection determines location accuracy, battery life, and interoperability with adjacent building systems.
- Bluetooth:Low Energy protocols enable sub-meter location precision for wander management and asset tracking through mesh network topologies. Assisted living operators in Florida integrate Bluetooth beacons with nurse call infrastructure to unify resident safety and facility security budgets.
- Wi-Fi:Leverages existing enterprise wireless infrastructure to reduce dedicated hardware costs and simplify IT governance. Hospital systems with Cisco or Aruba deployments standardize on Wi-Fi-native nurse call to consolidate VLAN management under biomedical engineering.
- Radio Frequency:Proprietary 400-900 MHz bands persist in legacy installations where FCC spectrum allocation permits continued operation.
- Infrared:Line-of-sight dependency limits adoption to controlled corridor environments with minimal daylight interference.
- Ultrasound:High power consumption and acoustic interference from medical equipment constrain deployment to specialized psychiatric units with RF restrictions.
Bluetooth holds the technology leadership position for new installations, with Wi-Fi gaining share fastest among integrated delivery networks consolidating IT infrastructure.
Application:
Facility type dictates response-time thresholds, staffing ratios, and reimbursement documentation intensity.
- Hospitals:Acute care environments demand sub-30-second emergency response with full audit trails for CMS Conditions of Participation compliance. Level I trauma centers in California and Texas specify redundant communication paths and automatic escalation algorithms.
- Long-Term Care:Skilled nursing facilities balance wander management integration with Medicaid reimbursement documentation requirements. Texas nursing homes lead national adoption of integrated fall detection and call system platforms.
- Assisted Living:Residential settings prioritize discreet form factors and family notification features over clinical documentation depth.
- Rehabilitation Centers:Therapy-focused workflows require portable pendant coverage across gym and aquatic therapy zones with waterproofing specifications.
Hospitals command the largest installed base, though Long-Term Care is expanding most quickly as Medicaid managed care penetration tightens oversight requirements.
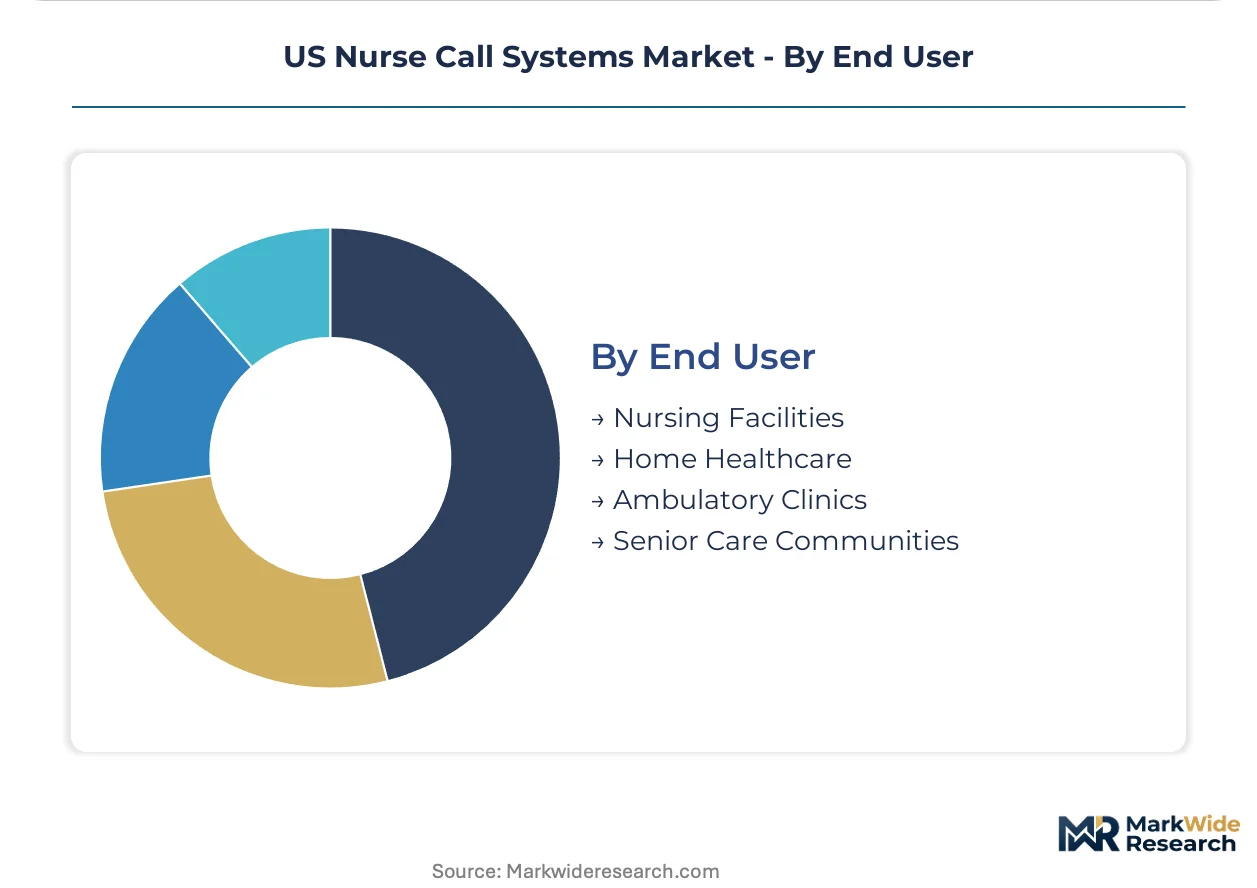
End User:
Purchasing authority and budget treatment vary sharply across care delivery models.
- Senior Care Communities:Independent living and continuing care retirement communities consolidate amenity and safety technology under single capital budgets. Florida's active adult developments specify nurse call as competitive differentiation in lease-up marketing.
- Nursing Facilities:Medicare and Medicaid reimbursement dependence drives procurement through group purchasing organizations with standardized specification templates.
- Home Healthcare:Mobile personal emergency response systems compete with traditional nurse call for remote monitoring budgets.
- Ambulatory Clinics:Procedure-based workflows favor lightweight notification systems without centralized console infrastructure.
Senior Care Communities represent the most dynamic end-user segment, while Nursing Facilities remain the volume anchor through Medicaid-funded bed expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and senior care developers concentrate demand in states with favorable reimbursement environments and rapid bed expansion. Sun Belt markets dominate volume, while legacy infrastructure states face replacement cycles.
Texas
Micro-hospital construction in Houston and Dallas exurbs drives modular, cloud-managed system specifications. CMS Conditions of Participation enforcement tightens documentation requirements for Level I trauma centers in the Texas Medical Center. San Antonio's military health corridor anchors demand for redundant communication paths in VA hospital renovations.
Florida
Active adult developments in The Villages and Naples specify nurse call as lease-up differentiation. Florida's Agency for Health Care Administration imposes additional fire-safety overlays on skilled nursing facility licensing. Tampa Bay's senior care construction pipeline concentrates demand for wireless retrofit platforms.
California
Biomedical engineering talent scarcity in Los Angeles and San Francisco slows IP-network deployment velocity. California's Department of Health mandates electrical-code compliance that filters vendor eligibility for acute care upgrades. Stanford Health and UCSF Medical Center drive EHR-adjacent workflow integration requirements.
Arizona
Senior housing developers in Phoenix and Tucson prioritize rapid occupancy ramp without construction disruption. Arizona's Department of Health Services aligns with federal CMS staffing-response mandates for assisted living facilities. Scottsdale's luxury continuing care retirement communities consolidate amenity and safety technology budgets.
New York
Specialized low-voltage contractor capacity constraints limit deployment velocity in the five boroughs. New York State Department of Health enforces fire-safety and electrical-code overlays beyond federal minimums. Northwell Health and NewYork-Presbyterian drive predictive analytics procurement for Joint Commission response-time scorecards.
US Nurse Call Systems Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with installed base leverage. The vendor base separates into three tiers: legacy infrastructure incumbents with service revenue streams, building-automation conglomerates pursuing platform convergence, and specialized workflow software vendors. Dominant competitive moves include IP-native platform development to displace copper-loop infrastructure and subscription-based service model transitions to capture recurring revenue.
Within the diversified medical technology tier, Hill-Rom Services Inc. and Rauland-Borg Corporation exemplify contrasting strategic positions. Hill-Rom occupies a position emphasizing integrated delivery network penetration and service revenue capture from legacy installed bases. Rauland-Borg represents specialized acute-care workflow expertise and education-focused market positioning. Honeywell International Inc. anchors the building-automation convergence archetype, extending nurse call functionality into broader facility management platforms rather than clinical workflow specialization.
| Leading Market Players |
|---|
| Hill-Rom Services Inc. |
| Rauland-Borg Corporation |
| Honeywell International Inc. |
| Ascom Holding AG |
| Stanley Healthcare |
| Cornell Communications |
| TekTone Sound and Signal Mfg., Inc. |
| Jeron Electronic Systems, Inc. |
| Critical Alert Systems LLC |
| Others |
Pricing and Supply Chain Analysis
Ethernet backbone substitution for copper-loop infrastructure simultaneously concentrates component sourcing in East Asian electronics manufacturing corridors and compresses hardware margin pools toward software-defined recurring revenue models. IP-native system architectures eliminate dedicated wiring harnesses while elevating cybersecurity certification and HL7 interoperability to primary price determinants.
Pricing Analysis
Cost-plus contracts with copper and semiconductor indexation dominate multi-year hospital system agreements. Three-tier pricing structure across premium IP-native platforms, standard hybrid configurations, and economy wired retrofits stratifies procurement pathways. Pricing pressure stems from subscription-model displacement of capital expenditure purchasing as CFOs favor operational expenditure treatment. Senior care communities exhibit highest price sensitivity due to Medicaid reimbursement ceilings, while Level I trauma centers prioritize redundancy specifications over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail for standardized Ethernet switches and PoE injectors, while strategic stockpiling governs FDA-cleared wireless peripherals with extended 510(k) clearance timelines. Component sourcing draws from Taiwan for semiconductor fabrication, Mexico for cable assembly, and China for Bluetooth beacon manufacturing. Raw material dependencies center on copper cathodes, FR-4 printed circuit board substrates, and lithium-ion cells for wireless endpoints. Single-source vulnerability concentrates in specialized medical-grade power supply units. Distribution runs through group purchasing organizations for nursing facilities and direct manufacturer relationships for integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IP-networking specialist scarcity across biomedical engineering departments constrains deployment velocity and elevates vendor service attach rates as decisive competitive differentiators.
For Market Incumbents: Consolidate installed base leverage through subscription-model transitions that capture recurring revenue from legacy copper-loop infrastructure. Acquire specialized workflow software vendors to fill EHR interoperability gaps before Epic and Cerner consolidation tightens. Defend against building-automation conglomerates by deepening clinical workflow expertise in acute-care telemetry integration. For New Entrants and Emerging Players: Post-acute workflow optimization gaps in skilled nursing facilities present white-space opportunities where incumbents under-serve Medicaid documentation requirements. Target Texas and Arizona senior housing developers with modular cloud-managed platforms that eliminate on-premise server infrastructure. Pursue direct sales relationships with regional senior care developers rather than GPO channel dependence. For Investors and Strategic Acquirers: The market sits at a substitution-phase inflection that favors platform-software specialists over hardware-centric legacy vendors. Long-term viability across the projection horizon hinges on recurring revenue attachment rates and cybersecurity certification depth. Monitor Joint Commission patient safety metric adoption as the signal for predictive analytics procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Submission | Premarket documentation of threat modeling and SBOM disclosure satisfies California and Massachusetts procurement preconditions. |
| Epic Interoperability Module Development | HL7 messaging integration positions nurse call data as reimbursable clinical documentation under CMS Conditions of Participation. |
| Bluetooth Low Energy Platform Launch | Sub-meter location precision enables wander-management integration that unifies resident safety and facility security budgets. |
| Micro-Hospital Cloud Partnership | Modular deployments without on-premise servers capture Texas exurb emergency department construction pipelines. |
| Predictive Analytics Acquisition | Response-time forecasting capabilities align procurement scorecards with Joint Commission patient safety metric requirements. |
Research Methodology
Initial hypotheses were tested against primary input from hospital biomedical engineers, senior care facility operations directors, GPO contracts managers, and low-voltage installation contractors and refined through secondary validation across FDA 510(k) databases, CMS Conditions of Participation documentation, hospital procurement records, and state Department of Health licensing filings. Bottom-up triangulation of unit installation costs and top-down reconciliation against health system capital expenditure disclosures anchored volume estimates.
Variance decomposition across system type, technology protocol, application setting, and end-user purchasing authority structured the analytical framework. CAGRs were derived from logistic adoption curves fitted to IP-native platform penetration rates and wireless retrofit installation velocities. Forecast inputs incorporated Joint Commission accreditation timeline shifts and Sun Belt senior housing construction permit data.
Forecasts assume regulatory continuity in FDA medical device classification and CMS reimbursement frameworks; material policy shifts would require re-modeling. Supply chain disruption from semiconductor allocation constraints or copper price volatility represent specific revision triggers. Revision becomes warranted when IP-networking specialist wage inflation crosses thresholds that accelerate vendor-managed service outsourcing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Dermatome Device Market
Medical Devices
North America and Europe Medical Technology Market
Medical Devices
China General Surgical Devices Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Water Flosser Market
Medical Devices
Polymer-Based Prefilled Syringe Market
Medical Devices
Ostomy Drainage Systems Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Global Otoscopes Market
Medical Devices
Condylar Plate Fixation System Market