
 Floor Scrubber Machine Market | 2026-2036
Floor Scrubber Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Scrubber Machine Market Insights
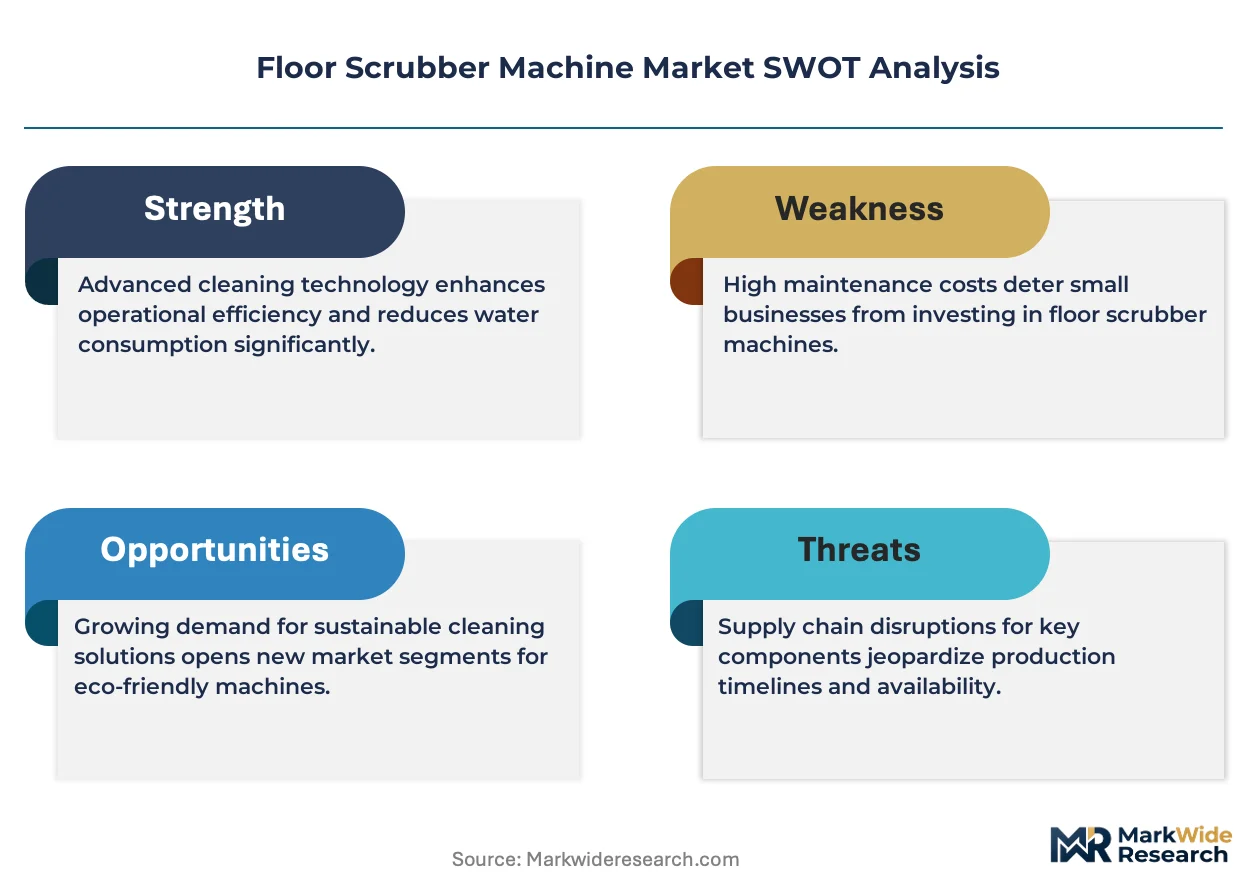
The capital-intensity divergence between players is collapsing as mid-tier manufacturers gain access to lithium-ion battery supply chains and brush-motor platforms that once required heavy balance-sheet investment. Tennant Company leverages its North American service infrastructure to sustain recurring revenue streams from fleet-management contracts. Nilfisk Group anchors its position through European distribution density and specialized applications in pharmaceutical cleanrooms. Kärcher competes on manufacturing scale, operating multi-continent production lines that undercut regional assemblers on unit economics.
A floor scrubber machine is a motorized cleaning appliance that combines brush agitation, detergent dispensing, and vacuum recovery to strip debris from hard flooring surfaces, typically operating at noise levels below seventy decibels for commercial compliance. Ride-on scrubbers dominate volume in warehouse and logistics settings where operator productivity per hour determines contract economics, while battery-powered walk-behind units represent the fastest-growing configuration as lithium chemistry replaces flooded lead-acid across janitorial services. Brush technology and microfiber cleaning systems concentrate margin pools at the premium tier, whereas spray-system commoditization pressures pricing in standard commercial applications.
OSHA workplace safety standards, the EU Green Deal emission benchmarks, and REACH chemical-registration requirements collectively shape product design, battery chemistry selection, and detergent formulation across all major supply corridors. Japan's METI energy-efficiency labeling and California's CARB emission rules further fragment certification burdens for manufacturers selling across multiple jurisdictions. Stakeholders must monitor regulatory divergence on battery end-of-life obligations and water-recovery thresholds, as these will determine which platform investments retain competitive validity through the forecast horizon.
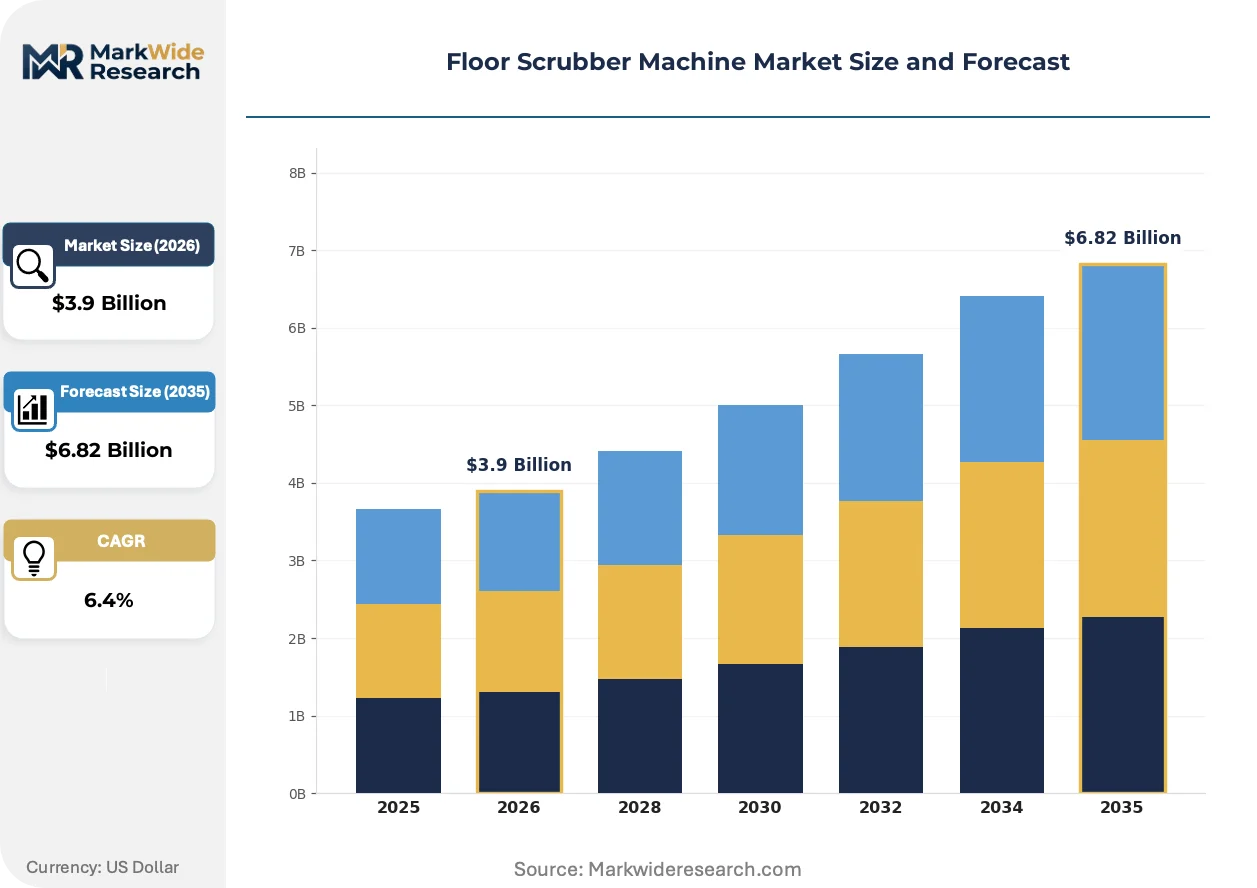
Market Dynamics
Lithium-ion battery chemistry is collapsing the capital barrier that once separated premium scrubber OEMs from regional assemblers, redistributing competitive leverage toward supply-chain control and service-network density.
Growth Catalysts
- Warehouse automation mandates:Third-party logistics operators in Germany and the United States are expanding mechanized cleaning fleets to maintain OSHA indoor air quality compliance and EU Green Deal emission thresholds.
- REACH chemical-registration protocols:Detergent formulation requirements are forcing reformulation toward biodegradable concentrates, opening margin pools for chemical-system integrators who bundle dispensing hardware with compliant chemistry.
- Brush-motor platform standardization:Modular drivetrain architectures are reducing R&D duplication, allowing mid-tier manufacturers to source subsystems from Shenzhen and Taichung suppliers.
Market Restraints
- Lithium carbonate price volatility:Battery pack input costs fluctuate with Chilean and Australian mining output, compressing margin predictability for OEMs locked into annual fleet-pricing contracts.
- European distribution concentration:Nilfisk and Kärcher anchor spare-parts availability through captive dealer networks, creating switching costs that delay competitive entry.
- Water-recovery technical ceilings:Vacuum-lift efficiency plateaus below ninety-five percent recovery rates in high-traffic retail environments, limiting detergent reduction claims.
Strategic Opportunities
- Indian pharmaceutical cleanrooms:CDSCO manufacturing standards are tightening particulate-count requirements, creating specification demand for HEPA-integrated ride-on scrubbers that exceed standard commercial configurations.
- Subscription-based fleet management:Telemetry-enabled machines allow hourly-usage billing models that transfer capital burden from janitorial contractors to OEM balance sheets.
- Japan METI energy-efficiency labeling:Tiered rating systems are creating procurement preference for brush-motor efficiency above IE4 thresholds, favoring early adopters of permanent-magnet synchronous designs.
Industry Challenges
- Electronics-technician scarcity:CAN-bus diagnostics and battery-management system troubleshooting require skill sets absent from traditional mechanical repair workforces, inflating field-service training costs.
- Multi-jurisdiction certification timelines:CARB emission rules, METI labeling, and CE machinery directives impose non-overlapping test protocols that delay product launches by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Scrubber Machine Market |
| Market Size in 2026 | $3.9 Billion |
| Market Size in 2035 | $6.82 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Walk-Behind Scrubbers, Ride-On Scrubbers, Battery-Powered Scrubbers, Automatic Scrubbers Technology: Brush Technology, Vacuum Suction, Spray Systems, Oscillating Pads, Microfiber Cleaning Application: Commercial Spaces, Warehouses, Educational Institutions, Transportation Facilities End User: Janitorial Services, Facility Management, Hospitality Services, Retail Chains |
| Companies Covered | Tennant Company, Nilfisk Group, Kärcher, Hako GmbH, Amano Corporation, Diversey, Inc., Dulevo S.p.A., Numatic International, Factory Cat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Scrubber Machine Market Trends and Innovations
Autonomous navigation and predictive maintenance telemetry are restructuring how facility managers contract cleaning operations, shifting value capture from equipment ownership toward uptime-guaranteed service models.
Lithium-iron-phosphate battery packs are bifurcating the powertrain market. Large distribution centers in the United States are adopting these cells for thermal stability during multi-shift operations. The chemistry is compressing lead-acid refurbishment revenue streams while enabling opportunity-charging infrastructure that eliminates battery-swap labor.
EU Green Deal emission benchmarks are tightening volatile organic compound limits for cleaning equipment operating in enclosed logistics facilities. Manufacturers serving Dutch and Belgian port-warehouse clusters are redesigning detergent-dispensing nozzles to reduce overspray. Pharmaceutical cleanroom operators are demanding third-party validation of zero-emission claims to satisfy ECHA documentation requirements.
Facility managers are consolidating vendor relationships around full-service contracts that bundle equipment, consumables, and labor. Janitorial service franchises in California and Texas are surrendering capital ownership to OEM captive-finance arms. The shift is most visible among grocery-retail chains operating thousand-plus store footprints where procurement standardization reduces administrative overhead.
Floor Scrubber Machine Market Segmentation
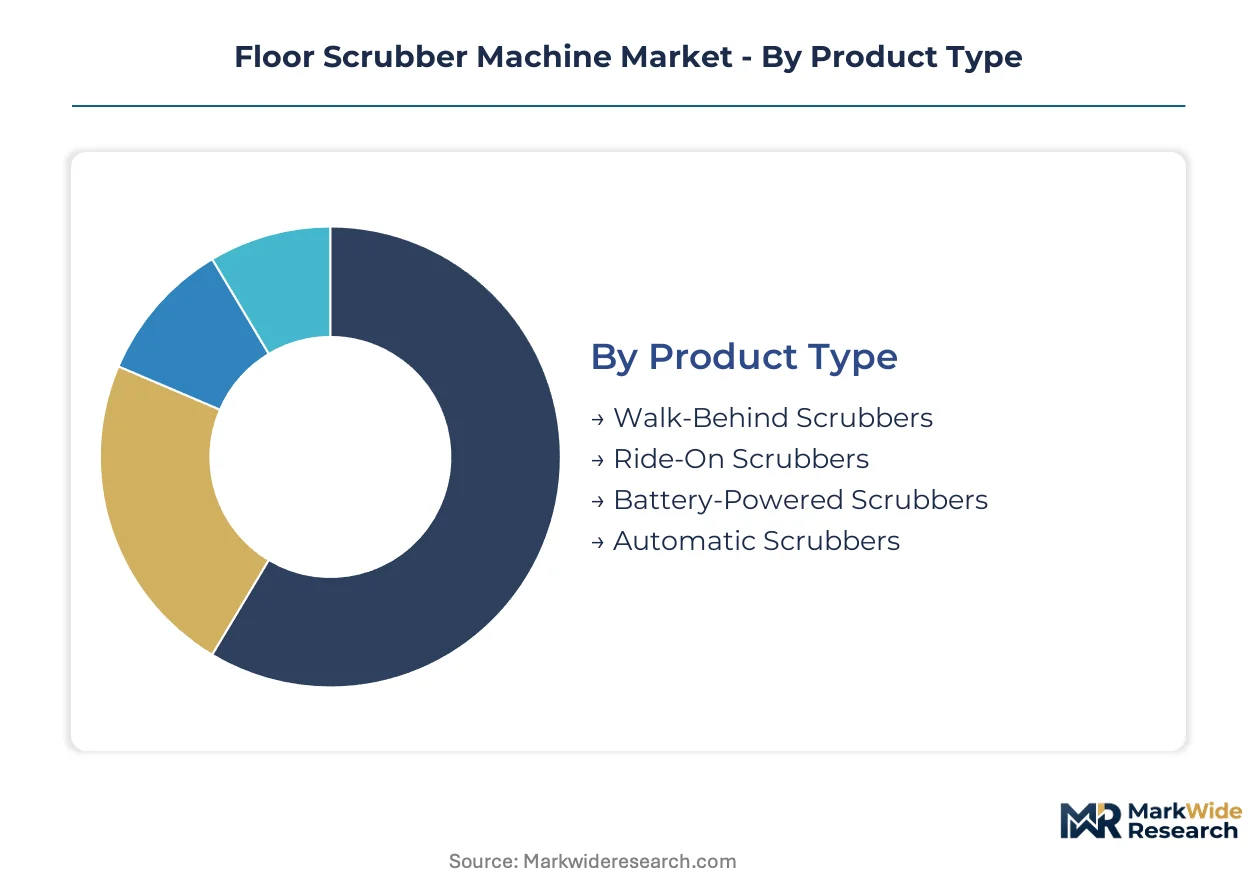
Floor scrubber procurement decisions split across operational scale, powertrain chemistry, and regulatory compliance tier. Facility managers weight capital recovery periods against OSHA air quality mandates and EU Green Deal emission thresholds when specifying machine configurations.
Product Type:
OSHA workplace safety standards and EU Green Deal protocols differentiate capital deployment across operator-mounted and autonomous configurations.
- Ride-On Scrubbers:Operator-seated platforms with 24-36 inch cleaning paths dominate warehouse and logistics contracts where productivity per labor hour determines vendor selection. Third-party logistics operators in Germany and the United States specify these units to maintain indoor air quality compliance across multi-shift operations.
- Walk-Behind Scrubbers:Maneuverable units with 17-20 inch decks serve retail corridors and educational facilities where space constraints limit machine footprint. Janitorial contractors in Japan favor compact lithium-ion variants for METI energy-efficiency compliance in mixed-use commercial buildings.
- Battery-Powered Scrubbers:Lithium chemistry configurations eliminate lead-acid maintenance cycles and enable opportunity charging during operator breaks.
- Automatic Scrubbers:Autonomous navigation platforms with LiDAR mapping reduce labor allocation in standardized environments like airport terminals.
Established volume favors ride-on configurations in warehouse logistics; emerging adoption favors battery-powered walk-behind units in janitorial services.
Technology:
Margin concentration follows cleaning mechanism sophistication, with brush-motor standardization collapsing R&D barriers for mid-tier assemblers.
- Brush Technology:Cylindrical and disc brush systems with modular drivetrain architectures concentrate specification demand in pharmaceutical cleanrooms where particulate control exceeds standard commercial thresholds. CDSCO manufacturing standards in India are tightening requirements for HEPA-integrated configurations.
- Microfiber Cleaning:Low-moisture pad systems reduce detergent volume and water recovery burden, capturing preference among EU Green Deal-compliant operators in Dutch and Belgian port-warehouse clusters.
- Vacuum Suction:Wet-dry recovery systems with 95 percent efficiency ceilings limit detergent reduction claims in high-traffic retail environments.
- Spray Systems:Pressurized nozzle architectures face commoditization pressure as regional assemblers source subsystems from Shenzhen suppliers.
- Oscillating Pads:High-frequency orbital motion strips finish without abrasive chemicals, satisfying REACH formulation requirements.
Brush technology commands premium specification in regulated cleanrooms; microfiber systems are climbing the fastest in emission-sensitive European logistics.
Application:
Facility type determines duty cycle intensity and corresponding machine durability requirements.
- Warehouses:High-bay distribution centers with epoxy-coated concrete specify ride-on lithium-iron-phosphate units for thermal stability across 18-hour operations. California CARB emission rules and EU Green Deal thresholds restrict propane-powered alternatives.
- Commercial Spaces:Mixed-use office complexes and healthcare facilities prioritize noise levels below 70 decibels for tenant compliance.
- Educational Institutions:K-12 and university campuses with seasonal occupancy patterns favor flexible leasing arrangements over capital purchase.
- Transportation Facilities:Airport terminals and rail stations with 24-hour traffic demand autonomous-capable platforms with predictive maintenance telemetry.
Procurement standardization concentrates in warehouse fleet contracts; flexibility requirements dominate educational institution purchasing.
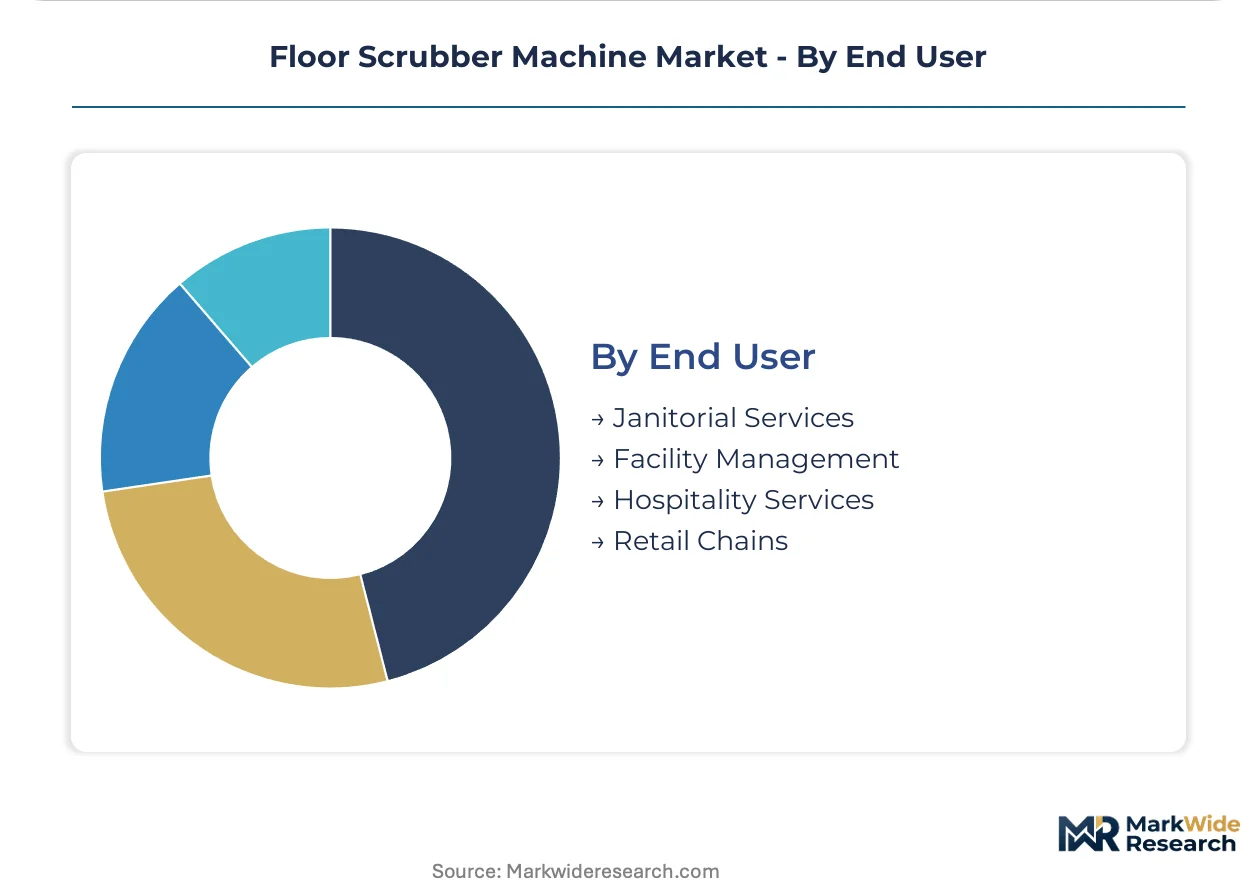
End User:
Customer organizational structure determines ownership model preference between capital purchase and subscription-based service.
- Janitorial Services:Independent contractors and regional franchises surrender equipment ownership to OEM captive-finance arms as telemetry-enabled hourly billing transfers capital burden. Texas and California operators lead this shift under consolidated vendor relationships.
- Retail Chains:Grocery and big-box operators with thousand-plus store footprints standardize procurement to reduce administrative overhead across state-level OSHA variations.
- Facility Management:Integrated service providers bundle equipment, consumables, and labor into full-service contracts with uptime guarantees.
- Hospitality Services:Hotel and resort operators with seasonal demand volatility favor short-term rental over depreciation-heavy asset ownership.
Janitorial services are expanding most quickly into subscription fleet models; retail chains anchor volume through standardized ownership structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where fleet-management contracts lock in multi-year service revenue, while Asian manufacturers compete on unit economics through Shenzhen and Taichung supply corridors.
United States
Third-party logistics operators in California and Texas are expanding mechanized cleaning fleets to satisfy OSHA indoor air quality mandates. CARB emission rules restrict propane-powered alternatives in high-bay distribution centers. The Inland Empire warehouse cluster east of Los Angeles specifies lithium-iron-phosphate ride-on units for thermal stability across 18-hour operations.
Germany
EU Green Deal emission benchmarks are tightening volatile organic compound limits for enclosed logistics facilities. REACH chemical-registration protocols force detergent reformulation toward biodegradable concentrates. The Rhine-Ruhr industrial corridor anchors spare-parts availability through captive dealer networks that delay competitive entry.
Japan
METI energy-efficiency labeling creates procurement preference for brush-motor efficiency above IE4 thresholds. Mixed-use commercial buildings in Tokyo and Osaka favor compact lithium-ion walk-behind variants. Kansai region facility managers are consolidating vendor relationships around telemetry-enabled hourly billing models.
India
CDSCO manufacturing standards are tightening particulate-count requirements for pharmaceutical cleanrooms. BIS certification delays product launches by eight to fourteen months for multi-jurisdiction OEMs. Maharashtra's pharmaceutical manufacturing belt generates specification demand for HEPA-integrated ride-on scrubbers.
Netherlands
Port-warehouse clusters in Rotterdam and Antwerp are redesigning detergent-dispensing nozzles to reduce overspray under EU Green Deal protocols. Dutch facility managers prioritize microfiber low-moisture systems that reduce water recovery burden. The Randstad logistics corridor leads European adoption of subscription-based fleet management.
Floor Scrubber Machine Market Competitive Landscape
Concentration sits with diversified cleaning-equipment conglomerates and specialized floor-care OEMs that control distribution density and service-network reach. The vendor base spans three tiers: premium-tier players with captive finance arms, mid-tier assemblers leveraging modular drivetrain architectures, and regional specialists serving single-country markets. Two competitive moves dominate: backward integration into lithium-ion battery supply chains and geographic expansion through telemetry-enabled fleet-management contracts.
Among North American and European anchors, Tennant Company and Nilfisk Group exemplify the premium-tier archetype through recurring revenue streams from service infrastructure and distribution density. Kärcher occupies a position representing manufacturing scale across multi-continent production lines. These three names sit within the consolidated upper tier where competitive leverage flows from supply-chain control rather than unit cost alone.
| Leading Market Players |
|---|
| Tennant Company |
| Nilfisk Group |
| Kärcher |
| Hako GmbH |
| Amano Corporation |
| Diversey, Inc. |
| Dulevo S.p.A. |
| Numatic International |
| Factory Cat |
| Others |
Pricing and Supply Chain Analysis
Multi-continent manufacturing scale at Kärcher compresses unit economics for standard commercial configurations while Tennant's North American service infrastructure sustains premium pricing through captive fleet-management contracts. This divergence between assembly-cost floors and service-augmented ceilings shapes procurement decisions across warehouse operators and janitorial contractors.
Pricing Analysis
The customization-premium spread separates configured-to-order HEPA-integrated ride-on units for Indian pharmaceutical cleanrooms from standard walk-behind models sourced through Shenzhen suppliers. Pricing stratifies across premium, standard, and economy tiers based on brush-motor efficiency certification and after-sales telemetry bundling. Cost compression in the standard tier intensifies as mid-tier assemblers gain lithium-ion battery supply access. Janitorial services in Texas and California demonstrate highest price sensitivity through subscription-model adoption, while pharmaceutical operators in Maharashtra accept premium positioning for CDSCO compliance.
Supply Chain Analysis
Inventory lead times for lithium-iron-phosphate cells fluctuate with Chilean and Australian mining output, compressing margin predictability for OEMs locked into annual fleet-pricing contracts. Brush-motor subsystems concentrate manufacturing in Shenzhen and Taichung, while final assembly anchors in Germany and the United States to satisfy CE marking and OSHA proximity requirements. Distribution runs through captive dealer networks in the Rhine-Ruhr corridor and Inland Empire warehouse clusters. Single-source vulnerability in battery-grade lithium carbonate represents the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronics-technician scarcity for CAN-bus diagnostics and battery-management system troubleshooting inflates field-service training costs, creating a capability gap that separates service-network incumbents from assembly-only competitors.
For Market Incumbents: Compound service-network density through telemetry-enabled predictive maintenance contracts that transfer capital burden from janitorial contractors to OEM balance sheets. Deepen backward integration into lithium-iron-phosphate supply chains to buffer Chilean mining volatility. Prioritize brush-motor efficiency certification above IE4 thresholds to capture Japan METI procurement preference. For New Entrants and Emerging Players: Differentiate on subscription-based fleet management models targeting educational institutions with seasonal occupancy patterns that resist capital purchase. Penetrate the Indian pharmaceutical cleanroom segment where CDSCO tightening exceeds standard commercial configurations. Lead with HEPA-integrated ride-on specifications bundled through regional distribution partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors OEMs with captive finance arms and telemetry infrastructure over pure-play manufacturers. Long-term viability hinges on service-revenue attachment rates rather than unit shipment volume. Watch lithium carbonate price volatility as the inflection indicator for margin compression across battery-dependent configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-iron-phosphate sourcing buffers OEMs against Chilean mining volatility. |
| Telemetry-Enabled Fleet Management | Hourly-usage billing transfers capital burden from Texas janitorial contractors to OEM balance sheets. |
| HEPA-Integrated Cleanroom Certification | CDSCO-compliant configurations capture premium specification in Maharashtra pharmaceutical corridors. |
| Brush-Motor Efficiency Investment | IE4-threshold designs secure procurement preference under Japan METI labeling systems. |
| Captive Dealer Network Expansion | Rhine-Ruhr and Inland Empire density creates switching costs that delay competitive entry. |
Research Methodology
The analysis maps ride-on configurations, walk-behind variants, battery chemistry tiers, and autonomous platforms, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with facility managers in California, Texas, Germany, and Japan combined with secondary validation from SEC filings, customs/trade data, and OSHA compliance documentation. Bottom-up segment sizing and top-down market triangulation cross-checked projections against observed fleet-deployment patterns.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled product type, powertrain chemistry, application intensity, and regulatory compliance tier. CAGRs derived from segment-level growth trajectory analysis incorporating lithium-ion substitution rates, warehouse automation mandates, and multi-jurisdiction certification timelines as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained lithium carbonate supply stability or accelerated EU Green Deal enforcement would require recalibration. Forecasts reflect documented assumptions regarding brush-motor standardization and telemetry adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Spiral Fitting Machines Market
Material Handling Equipment
Cable Conduit Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
ASEAN Conveyor System Market
Material Handling Equipment
Heavy Loader Market
Material Handling Equipment
Heavy Duty Loading Ramps Market
Material Handling Equipment
Conveying Equipment Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Pipe Wrapping Machines Market
Material Handling Equipment
Industrial Racking Systems Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Crawler Crane Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Shiplifts & Transfer Systems Market
Material Handling Equipment
Europe Forklift Truck Market