
 Gas Chromatography Systems Market | 2026-2036
Gas Chromatography Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Chromatography Systems Market Intelligence
A widening gap in R&D investment for hyphenated and micro-GC systems is reorganizing the competitive landscape. Large-scale providers like Agilent Technologies leverage extensive service networks to secure contracts in the pharmaceutical sector. Shimadzu Corporation competes on instrument reliability and a strong presence within academic institutions. Thermo Fisher Scientific differentiates through its leadership in mass spectrometry detectors for complex sample analysis.
Gas chromatography is an analytical technique used to separate and analyze compounds that can be vaporized without decomposition. It uses a carrier gas to move a sample through a column, separating components based on their interaction with a stationary phase. Bench-top systems constitute the largest product segment, but portable units are gaining traction for on-site environmental testing. Mass spectrometry detectors command a premium, essential for high-sensitivity needs in pharmaceutical development and forensics.
Regulatory bodies like the US FDA and the European Medicines Agency (EMA) mandate stringent purity and safety testing, directly driving instrument sales. Compliance with standards from the EPA in the United States and similar environmental agencies in China for pollutant monitoring requires certified analytical methods. Instrument manufacturers must decide whether to prioritize R&D for high-margin hyphenated systems or focus on the volume market for modular bench-top units.
Market Dynamics
The central dynamic shaping the gas chromatography market is the dual pressure from stringent environmental mandates and the increasing complexity of pharmaceutical development. This forces investment in more sensitive, specialized GC systems to meet compliance demands from regulators like the EPA and EMA.
Growth Catalysts
- Stringent Food Safety Mandates:The EU's regulations on pesticide residues and contaminants, enforced by bodies like EFSA, require more frequent and precise GC-MS testing across the food supply chain.
- Biopharmaceutical Expansion:Growth in complex biologics in United States research hubs necessitates advanced GC for impurity profiling and process monitoring, guided by FDA protocols for product purity.
- Process Analytical Technology (PAT):The adoption of PAT initiatives in pharmaceutical manufacturing drives demand for online and at-line GC systems to ensure real-time quality control, moving analysis from the lab to the production floor.
Market Restraints
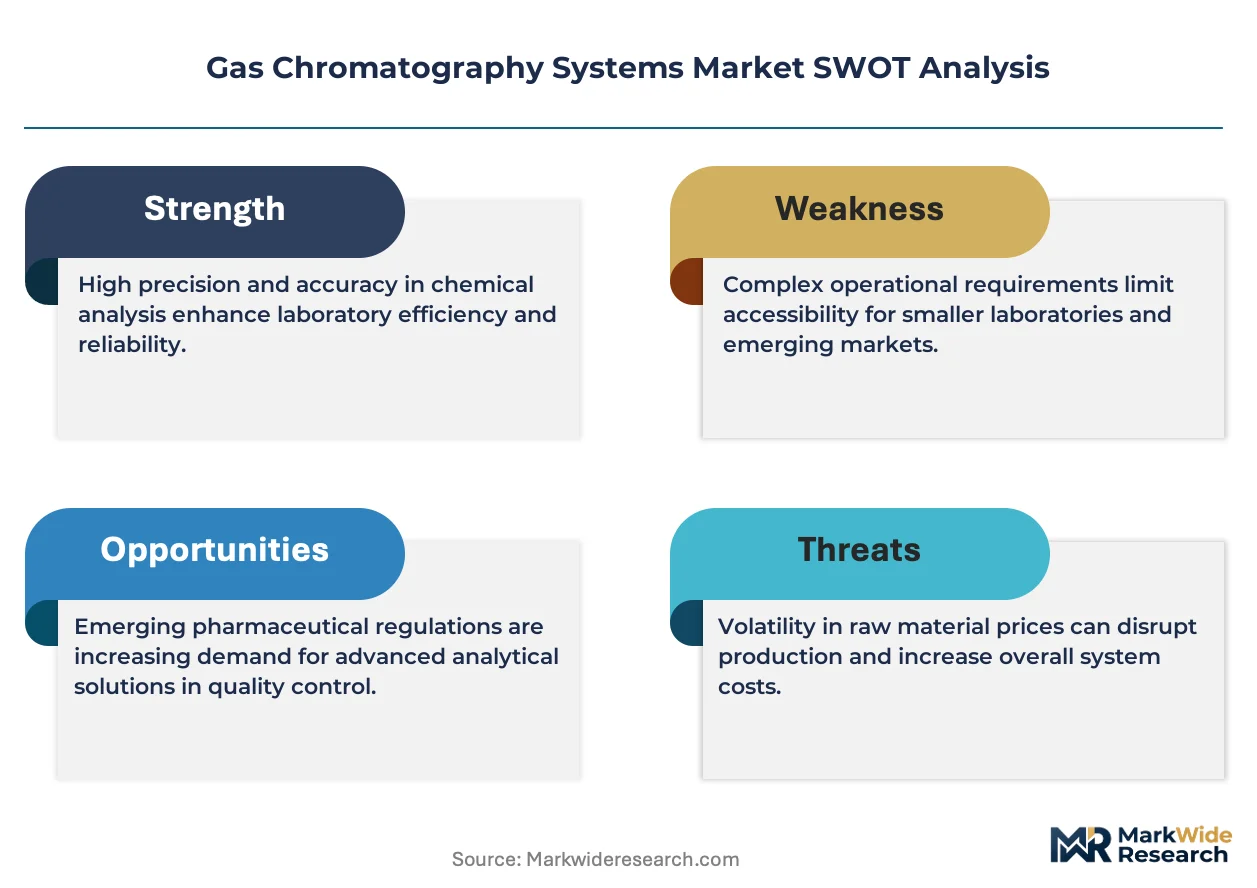
- High Capital Outlay:The significant upfront cost of high-resolution hyphenated systems, such as GC-MS/MS, limits adoption by smaller academic labs and budget-constrained testing facilities in emerging economies.
- Sample Preparation Complexity:Many environmental and biological samples require extensive, time-consuming preparation before GC analysis, creating a major workflow bottleneck that instrumentation alone cannot solve.
- Competition from LC:For non-volatile or thermally unstable large molecules, particularly in biopharma, liquid chromatography (LC) and LC-MS present a strong alternative analytical technique, limiting GC's addressable applications.
Strategic Opportunities
- Contract Lab Growth in India:The expansion of contract research organizations in India, supported by policies like the PLI scheme, creates an opportunity for specialized GC systems tailored to generic drug and API testing.
- Environmental Monitoring in China:China's "dual carbon goals" and strict MEE enforcement on volatile organic compounds (VOCs) create a significant opportunity for portable GC systems for on-site air and water quality analysis.
- Micro-GC for Process Control:Integrating micro-GC systems into industrial processes like natural gas quality monitoring offers a new frontier for real-time, automated analytical control beyond traditional laboratory settings.
Industry Challenges
- Skilled Operator Scarcity:A shortage of trained chromatographers who can develop methods, interpret complex data from hyphenated systems, and perform instrument maintenance is a critical operational constraint across all regions.
- Data System Interoperability:Ensuring seamless integration of new chromatography data systems (CDS) with existing laboratory information management systems (LIMS) is a persistent technical challenge for end-users.
- Validation Timelines:The lengthy process of validating new instruments and methods to comply with GMP or ISO 17025 standards delays the deployment of new technology in regulated environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Chromatography Systems Market |
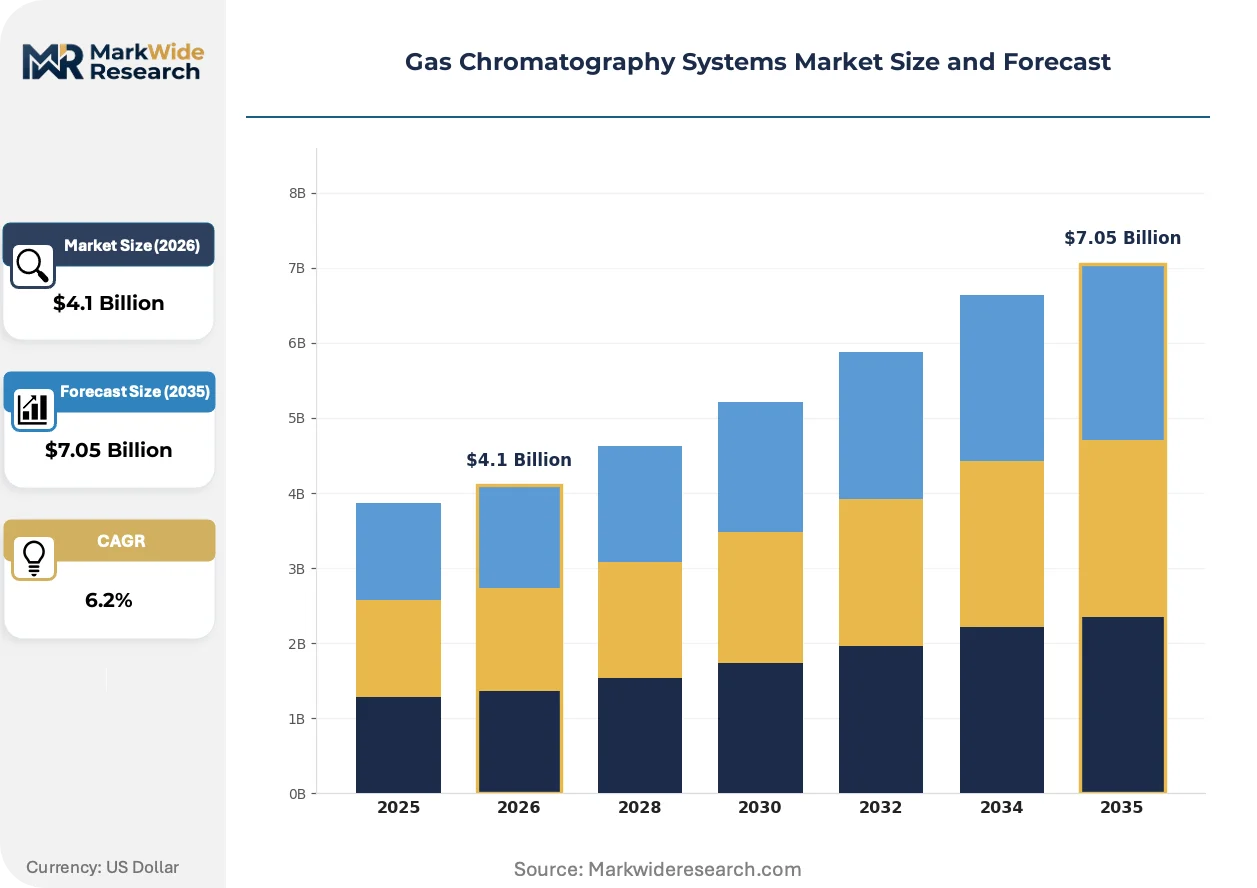
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.05 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-Top, Portable, Hyphenated, Micro, Modular Detection Technology: Flame Ionization Detector, Thermal Conductivity Detector, Electron Capture Detector, Mass Spectrometry Detector, Flame Photometric Detector Application: Environmental Testing, Petrochemical Analysis, Food Safety, Pharmaceutical Development, Forensic Investigation End User: Contract Research Organizations, Chemical Manufacturers, Academic Institutions, Quality Control Laboratories |
| Companies Covered | PerkinElmer, Merck KGaA, Agilent Technologies, Restek Corporation, Bruker Corporation, Thermo Fisher Scientific, Waters Corporation, LECO Corporation, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Chromatography Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a push towards decentralization and automation, moving analytical capabilities from specialized central labs to on-site and in-line applications. This shift prioritizes speed and accessibility, altering the value proposition of traditional bench-top systems.
Micro-electro-mechanical systems (MEMS) technology enables the creation of compact, chip-based GC components like injectors and columns. Environmental monitoring agencies and industrial process control operators are the primary adopters, valuing portability and rapid analysis times. This trend is miniaturizing analytical instrumentation, allowing for the development of handheld, portable GC systems for real-time field analysis.
European Union's REACH regulation continues to expand its list of Substances of Very High Concern (SVHC), requiring rigorous chemical safety assessments. This mandate forces chemical manufacturers and importers to conduct extensive testing to prove compliance, directly increasing the workload for analytical laboratories. The consumer goods and chemical sectors are most affected, investing in high-throughput GC-MS systems to screen for restricted compounds.
End-users in the pharmaceutical and food testing sectors are increasingly favoring leasing models and comprehensive service contracts over outright capital purchases. This model disrupts the traditional one-time sales cycle, shifting the focus to long-term partnerships that include maintenance, software updates, and application support. The shift is most prominent in North America and Europe, where large contract testing organizations seek to manage operational costs.
Gas Chromatography Systems Market Segmentation
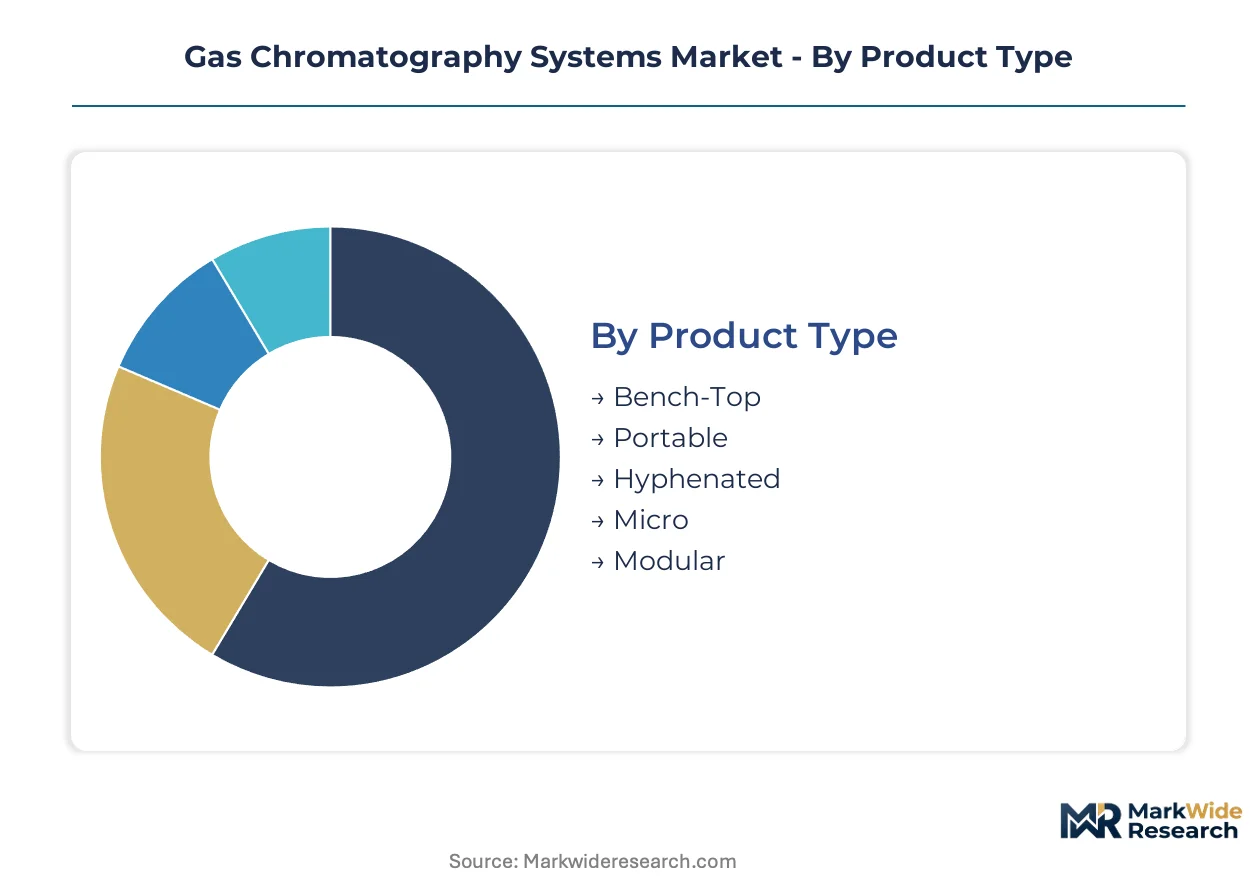
The gas chromatography market's structure reflects diverse user needs and technological advancements. Understanding these segments clarifies where manufacturers concentrate R&D efforts and sales strategies. Analytical techniques vary significantly across different applications and user types, driving specialized product development.
Product Type:
The distribution channels for gas chromatography systems are shaped by the functional requirements of different product types.
- Bench-Top:These systems are standard laboratory instruments, offering high precision for routine and research applications. Demand concentrates in quality control laboratories and academic institutions across Europe and the United States, driven by established analytical protocols.
- Portable:Compact and often battery-powered units designed for on-site analysis, providing rapid results outside traditional lab settings. Environmental monitoring agencies and industrial process control operators in China value portability and rapid analysis times.
- Hyphenated:Combining GC with other analytical techniques, typically mass spectrometry, these systems provide enhanced sensitivity and specificity. Pharmaceutical development in US research hubs requires these advanced systems for impurity profiling, mandated by FDA protocols.
- Micro:Miniaturized GC systems leveraging MEMS technology for ultra-compact, chip-based components. This segment offers potential for integration into process analytical technology (PAT) workflows, reducing footprint and accelerating analysis.
- Modular:Systems allowing users to customize configurations with different injectors, columns, and detectors. This flexibility appeals to research laboratories and contract testing facilities needing adaptable analytical solutions.
By volume, Bench-Top systems lead. By growth pace, Micro systems are ahead.
Detection Technology:
The capital investment profiles for detection technologies vary significantly, influencing adoption rates across different market tiers.
- Flame Ionization Detector:A common and robust detector for organic compounds, it measures ions produced by burning the sample in a hydrogen flame. Petrochemical analysis and environmental monitoring widely utilize this detector for its reliability and broad applicability.
- Thermal Conductivity Detector:A universal detector sensitive to all compounds except the carrier gas, operating by measuring changes in thermal conductivity. This detector is frequently used for permanent gases and simple inorganic compounds in industrial process monitoring.
- Electron Capture Detector:Highly sensitive to halogenated compounds and other electron-capturing species, making it ideal for trace analysis of pesticides and environmental contaminants. Its specificity makes it valuable for regulatory compliance testing in Europe.
- Mass Spectrometry Detector:These detectors provide highly sensitive and selective compound identification through molecular fragmentation analysis. High-sensitivity needs in pharmaceutical development and forensics drive their premium pricing and adoption in specialized testing facilities.
- Flame Photometric Detector:Specific for sulfur and phosphorus-containing compounds, this detector is crucial for analyzing pollutants and additives in the petrochemical and environmental sectors. It provides targeted detection in complex matrices.
Higher-margin opportunities exist with Mass Spectrometry Detectors. Broader market penetration comes from Flame Ionization Detectors.
Application:
End-user requirements dictate the specific gas chromatography configurations chosen for various analytical applications.
- Environmental Testing:Focused on analyzing pollutants in air, water, and soil matrices, including volatile organic compounds (VOCs) and pesticides. EPA standards in the United States and MEE enforcement in China necessitate precise and often portable GC solutions.
- Petrochemical Analysis:This application involves characterizing crude oil, natural gas, and refined products for composition, purity, and quality control. GC systems ensure compliance with industry standards for fuel quality and process efficiency.
- Food Safety:Involves detecting pesticide residues, contaminants, and additives in food products to comply with regulatory mandates. EU regulations on pesticide residues, enforced by EFSA, require frequent and precise GC-MS testing.
- Pharmaceutical Development:This application involves impurity profiling, residual solvent analysis, and drug substance characterization for new drug entities. Stringent FDA and EMA purity regulations in the United States and Europe drive demand for advanced GC-MS systems.
- Forensic Investigation:Utilizes GC for analyzing evidence such as illicit drugs, arson accelerants, and toxicology samples. High-sensitivity mass spectrometry detectors are essential for identifying trace compounds in complex forensic matrices.
Regulatory mandates from bodies like the EPA and EMA heavily influence application segment growth. Innovation in portable GC systems targets rapid on-site analysis needs.
End User:
The scale and operational models of end-user organizations significantly influence their procurement strategies for gas chromatography systems.
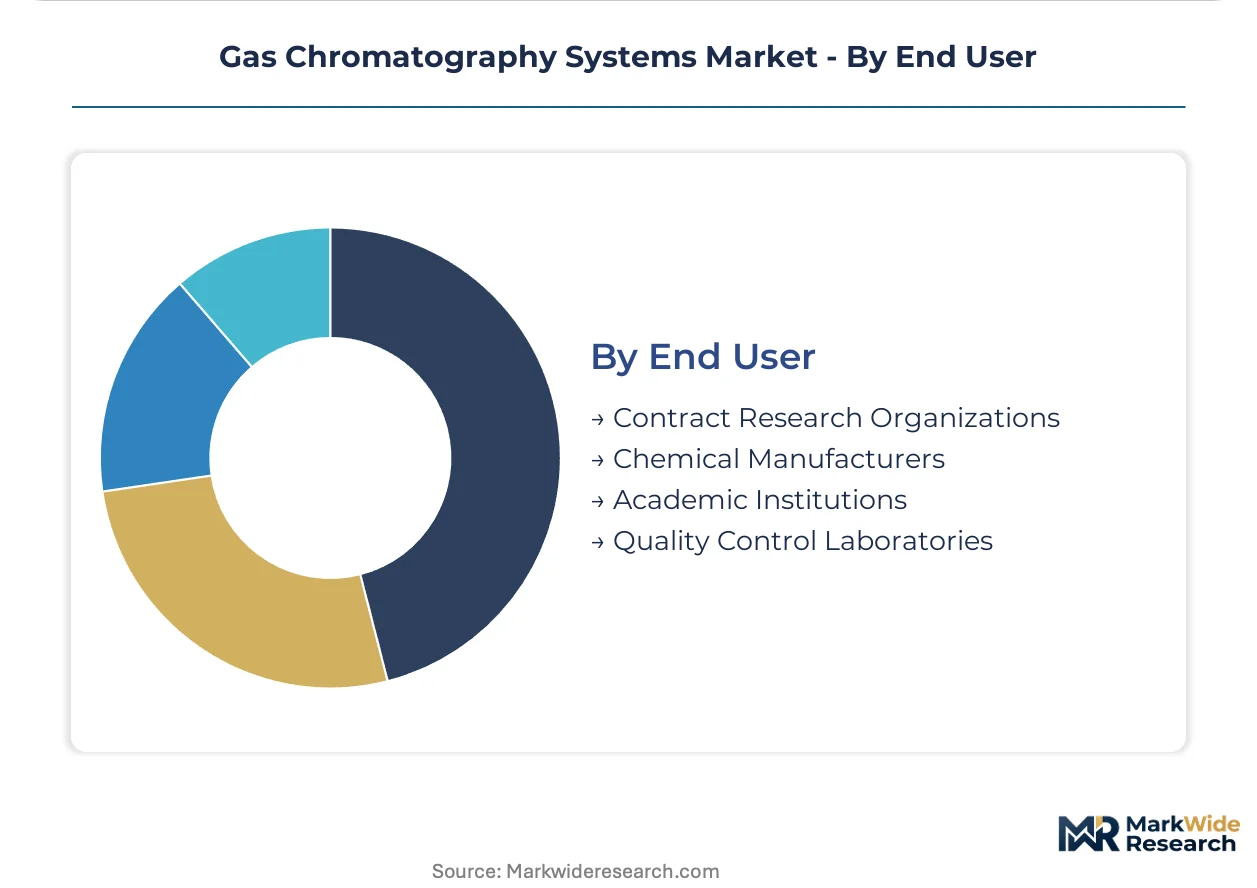
- Contract Research Organizations:These organizations perform outsourced analytical testing for pharmaceutical, chemical, and food industries. Growth in India's contract testing sector, supported by policies like the PLI scheme, creates significant opportunities for specialized GC systems.
- Chemical Manufacturers:Utilize GC for quality control of raw materials, in-process monitoring, and final product analysis to ensure purity and compliance. Demand is consistent for robust, high-throughput systems for routine analysis.
- Academic Institutions:Employ GC for research, teaching, and method development in chemistry, environmental science, and biochemistry departments. Instrument reliability and comprehensive service contracts are important considerations for these users.
- Quality Control Laboratories:Found within manufacturing facilities across various industries, these labs ensure product compliance with specifications and regulatory standards. Consistent demand stems from the need for routine batch release testing in pharmaceutical and chemical production.
Investment in GC technology by Contract Research Organizations is expanding. Academic Institutions prioritize instrument reliability and educational capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for gas chromatography systems varies significantly, with some markets prioritizing high-sensitivity, specialized systems regardless of cost. Other regions seek more budget-friendly, robust solutions. This divergence reflects differing regulatory pressures, industrial maturity, and R&D investment priorities across global economies.
United States
Pharmaceutical development in US research hubs drives demand for advanced hyphenated GC systems. The FDA mandates stringent impurity profiling and residual solvent analysis for new drug entities. Pharmaceutical clusters in Massachusetts and California invest in high-sensitivity GC-MS. This supports premium instrument sales and comprehensive service contracts.
Germany
European Union regulations, including REACH and EFSA mandates, shape the GC market in Germany. Chemical manufacturers and food safety laboratories require precise analytical testing for compliance. Academic institutions in Bavaria and North Rhine-Westphalia contribute to demand for reliable GC systems. These entities adopt both established bench-top units and new micro-GC technologies.
China
China's stringent MEE enforcement on volatile organic compounds (VOCs) and "dual carbon goals" boost demand for environmental testing. This creates opportunity for portable and micro-GC systems for on-site air and water quality analysis. Industrial hubs in the Yangtze River Delta require continuous process monitoring. Chinese laboratories also adopt advanced GC for food safety.
India
Contract research organizations in India are expanding rapidly, fueled by policies like the PLI scheme for pharmaceutical manufacturing. This growth generates demand for specialized GC systems tailored to generic drug and API testing. Major testing facilities in Gujarat and Telangana seek cost-effective, reliable analytical solutions. Indian labs balance capital outlay with instrument performance requirements.
Japan
Japanese pharmaceutical companies and academic institutions emphasize precision and reliability in analytical instrumentation. The PMDA's strict purity regulations for drug substances necessitate advanced GC-MS systems for impurity detection. Research clusters in Kanto and Kansai drive innovation and adoption of new GC technologies. Environmental monitoring also requires specialized GC applications.
Gas Chromatography Systems Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the gas chromatography market. The competitive landscape shows a tiered structure, with established multinational corporations dominating the high-end, specialized system segments. Niche players and regional manufacturers often compete on price and specific application expertise. Companies frequently pursue portfolio diversification and strategic partnerships to strengthen their market positions.
On the premium-tier vector, Agilent Technologies exemplifies a market leader leveraging extensive service networks to secure contracts across the pharmaceutical sector. This multinational corporation demonstrates the strategy of offering comprehensive support alongside advanced instrumentation. Thermo Fisher Scientific occupies a strong position through its leadership in mass spectrometry detectors, essential for complex sample analysis in critical applications like forensics and biopharma. This company represents an archetype focused on integrating advanced detection technologies. Shimadzu Corporation anchors the market with instrument reliability and a strong presence within academic institutions, showcasing a balanced approach to market penetration through robust product offerings and educational outreach. These players collectively shape the high-value segments of the gas chromatography market.
| Leading Market Players |
|---|
| PerkinElmer |
| Merck KGaA |
| Agilent Technologies |
| Restek Corporation |
| Bruker Corporation |
| Thermo Fisher Scientific |
| Waters Corporation |
| LECO Corporation |
| Shimadzu Corporation |
| Others |
Cost & Logistics Intelligence
Long-term service contracts for gas chromatography systems lock in both supply access for critical components and predictable pricing for end-users. This model helps manage operational costs for large contract testing organizations in North America and Europe.
Pricing Analysis
Extended service contracts and software updates represent a significant after-sales revenue tier, driving substantial lifetime value for gas chromatography system manufacturers. The dominant pricing structure for high-end systems is value-based, reflecting advanced capabilities like mass spectrometry detectors and specialized application support. Price differentiation stems from detector sensitivity (e.g., MS vs. FID) and certification level for regulatory compliance (e.g., FDA-validated systems). Pricing softness affects modular bench-top units due to increasing competition from regional manufacturers. Academic institutions are the most price-sensitive buyers, while pharmaceutical development hubs prioritize performance regardless of cost.
Supply Chain Analysis
Specialized MEMS component manufacturing in Japan underpins miniaturized GC systems, creating a potential single-source vulnerability for micro-GC producers. The supply chain for gas chromatography systems draws from electronics manufacturing in China and precision engineering in Germany. Key component dependencies include high-purity carrier gases, specialized column materials, and detector chips. Tariffs on imported electronic components pose a structural risk to overall system costs. Distribution runs through a combination of direct sales channels for large enterprises and a network of regional distributors for smaller labs and academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas chromatography systems market presents a defensive-moat story for established players, primarily due to high switching costs associated with validated methods and extensive operator training. This entrenchment secures long-term revenue streams for incumbent manufacturers.
For Market Incumbents: Secure long-term service contracts and application support agreements with pharmaceutical and environmental testing labs to counter margin pressure from new modular system entrants. Invest in R&D for hyphenated systems, leveraging existing service networks to maintain a competitive edge against substitute LC-MS technologies. Deepen vertical integration into specialized detector manufacturing to control critical component supply. Expand training programs for chromatographers to address the skilled operator scarcity, reinforcing customer loyalty.
For New Entrants and Emerging Players: Differentiate on micro-GC and portable system innovations, targeting rapid on-site analysis needs in environmental monitoring. Focus on the Chinese environmental testing market, which demands agile and cost-effective solutions for VOCs. Offer modular systems with open-source software integration, appealing to budget-constrained academic labs seeking flexible configurations. A go-to-market angle could involve leasing models with comprehensive support, reducing upfront capital outlay for smaller facilities.
For Investors and Strategic Acquirers: Specialized software and data analytics firms offering chromatography data systems (CDS) present an attractive acquisition target archetype for enhancing ecosystem value. This market demonstrates long-term viability over the next decade, driven by persistent regulatory compliance needs and pharmaceutical innovation. Acquiring firms with strong intellectual property in MEMS technology for micro-GC systems could unlock future growth. The signal to watch is the rate of adoption of process analytical technology (PAT) in biopharmaceutical manufacturing.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Micro-GC R&D | Accelerates development of portable systems for China's environmental monitoring and industrial process control. |
| Strengthen Service Networks | Secures long-term contracts with pharmaceutical research hubs and contract testing organizations. |
| Integrate Mass Spectrometry Detectors | Addresses high-sensitivity requirements for complex biologics and forensic applications. |
| Develop PAT-Enabled Solutions | Supports real-time quality control in pharmaceutical manufacturing, aligning with FDA protocols. |
| Form Academic Partnerships | Ensures instrument reliability and provides educational capabilities for future chromatographers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews to gather qualitative insights and validate quantitative findings. Key stakeholders included pharmaceutical R&D executives, environmental agency analysts, laboratory managers, and GC instrument engineers. Secondary data sources, such as EPA reports, EMA guidelines, and industry association publications, provided foundational market intelligence. A rigorous bottom-up and top-down triangulation approach reconciled market sizing and forecast projections.
The market forecast across the analysis window utilized a robust analytical framework integrating historical trends with future projections. Segmentation dimensions modeled included product type, detection technology, application area, and end-user type, alongside regional regulatory compliance frameworks. Compound Annual Growth Rates were derived from segment-specific expansion rates. Forecast inputs considered the increasing complexity of pharmaceutical development and evolving environmental mandates.
Material uncertainties, such as unforeseen regulatory shifts or disruptive technological advancements, sit outside the modeled envelope. Forecasts reflect assumptions regarding stable geopolitical conditions and sustained R&D investment. Practitioners should keep alternative scenarios live as global economic conditions and scientific breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
ESR Analyzer Market
Analytical Instruments
Atomic Spectroscopy Market
Analytical Instruments
Mass Spectrometer Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Global Infrared Thermography Market
Analytical Instruments
Microfluidic Devices Market
Analytical Instruments
Fluorescence Spectroscopy Market
Analytical Instruments
Global Ion Mobility Spectrometry Market
Analytical Instruments
Dioxin Analyzer Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
Benchtop Ph Meters Market
Analytical Instruments
Array Instruments Market
Analytical Instruments
Potentiometric Titrators Market
Analytical Instruments
Battery Analyzer Market
Analytical Instruments
XRF Analyzer Market