
 Illuminometer Market | 2026-2036
Illuminometer Market Size, Share, and Industry Trends Forecast 2026-2036
Illuminometer Market Foresight
Silicon photodiode arrays is rebalancing cost-performance trade-offs across mid-tier illuminometer portfolios. Konica Minolta Sensing Americas leverages its optical heritage to dominate laboratory-grade calibration workflows. Testo SE anchors its position through channel density in HVAC-lighting crossover applications. Sekonic specializes in cinematography and photographic metering niches where color-temperature accuracy commands premium positioning.
An illuminometer measures luminous flux per unit area in lux or foot-candles, typically employing photodiodes, photomultipliers, or charge-coupled devices with spectral response corrected to the CIE photopic curve for precision alignment with human visual perception. Portable illuminometers lead volume shipments due to facility-maintenance mobility requirements, while laboratory illuminometers capture margin pools through NIST-traceable certification and multi-channel spectral analysis. LED-based sensors represent the fastest-expanding technology segment as solid-state lighting retrofits multiply verification protocols across manufacturing and exhibition environments.
The International Commission on Illumination (CIE) defines measurement geometries that manufacturers must follow for cross-border equipment acceptance, while the International Electrotechnical Commission (IEC) governs electromagnetic compatibility and safety classifications for handheld electronic instruments. In the United States, OSHA workplace lighting standards and the EPA's energy efficiency mandates shape industrial procurement specifications. Stakeholders must monitor how spectral sensor fusion and wireless calibration logging alter service-revenue models versus traditional hardware replacement cycles.
Market Dynamics
Solid-state lighting retrofits are forcing verification protocol upgrades across manufacturing and exhibition environments, compressing replacement cycles for legacy photometric equipment.
Growth Catalysts
- CIE photopic curve alignment mandates:Cross-border equipment acceptance rules under International Commission on Illumination standards are accelerating metrology-grade procurement in Germany and Japan.
- LED testing laboratory expansion:Commercial and residential sector compliance requirements are strengthening demand for NIST-traceable calibration workflows.
- Photoelectric sensor miniaturization:Silicon photodiode arrays are rebalancing cost-performance trade-offs and shifting procurement toward handheld form factors.
Market Restraints
- Precision optics supply concentration:Germany, Japan, and the United States dominate metrology-grade component manufacturing, creating single-source vulnerabilities.
- Spectral sensor fusion R&D costs:Multi-channel integration requires capital intensity that mid-tier portfolios struggle to absorb.
- Electromagnetic compatibility certification:IEC safety classifications for handheld electronic instruments extend time-to-market for new entrants.
Strategic Opportunities
- HVAC-lighting crossover applications:Building automation integration creates white space for dual-function instruments serving facility maintenance mobility requirements.
- Wireless calibration logging:Bluetooth-enabled data transmission is expanding into service-revenue models that displace traditional hardware replacement cycles.
- Cinematography color-temperature accuracy:Premium positioning in photographic metering niches commands margin pools distinct from industrial commoditization.
Industry Challenges
- NIST-traceable technician certification:Laboratory-grade calibration workflows face talent scarcity in spectral analysis and photometric standard maintenance.
- Legacy system integration complexity:Existing facility-management software architectures resist seamless incorporation of cloud-connected illuminometer fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Illuminometer Market |
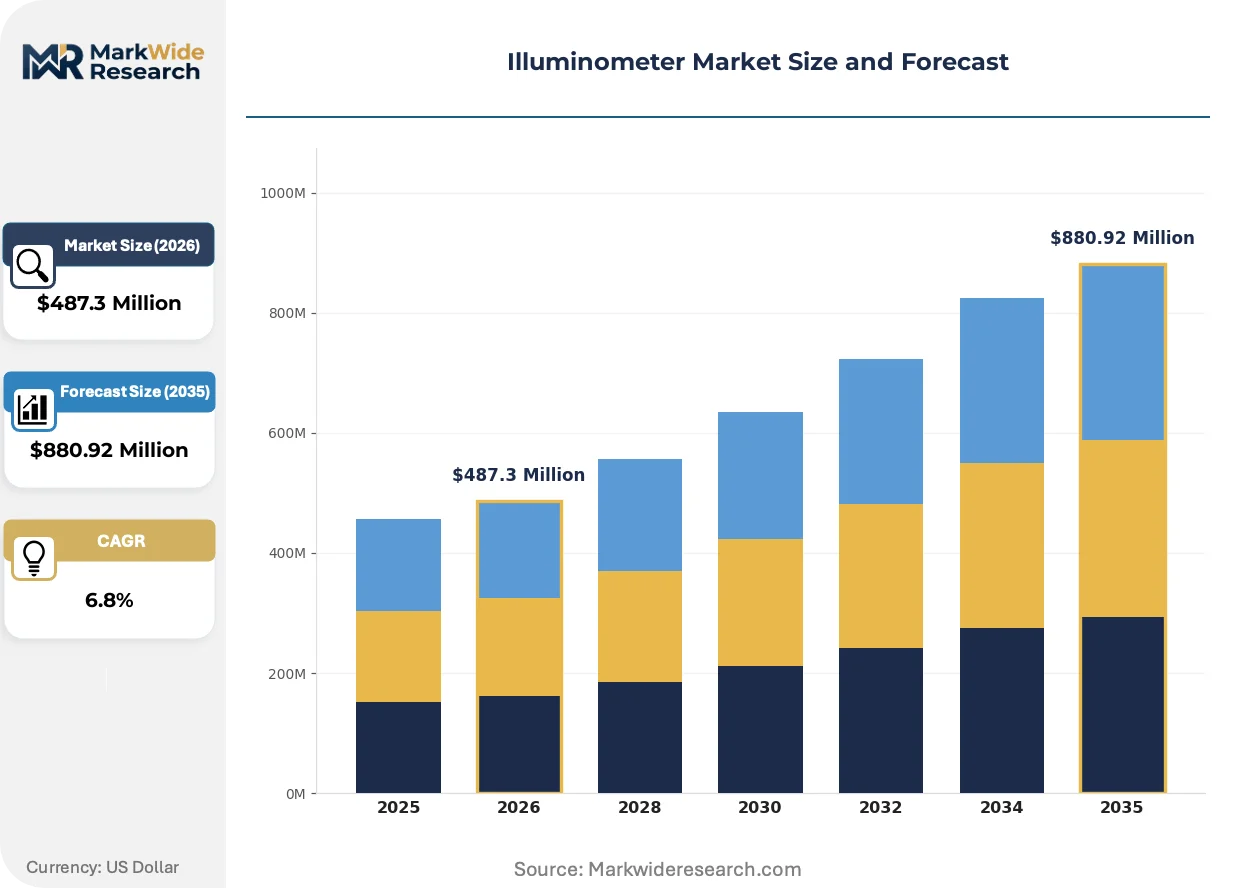
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Illuminometers, Desktop Illuminometers, Laboratory Illuminometers, Advanced Illuminometers End User: Research Labs, Industrial Facilities, Educational Institutions, Environmental Monitoring Technology: Digital Sensors, Analog Sensors, LED-Based Sensors, Photoelectric Sensors Application: Quality Control, Environmental Assessment, LED Testing, Exhibition Lighting |
| Companies Covered | Konica Minolta Sensing Americas, FLIR Systems, Sekonic, Testo SE, Hioki, Amprobe, KERN & SOHN, B&K Precision, Line Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Illuminometer Market Shifts & Advancements
Sensor fusion architectures and connectivity protocols are compressing the boundary between field instrumentation and laboratory-grade verification, altering how value migrates through equipment lifecycles.
Silicon photodiode arrays are expanding into mid-tier illuminometer portfolios by delivering CIE-corrected spectral response at reduced unit economics. Facility maintenance teams in commercial real estate are adopting these sensors for rapid lux verification during LED retrofit commissioning. The technology is expanding into applications previously reserved for photomultiplier-based laboratory systems, compressing the premium tier's addressable market.
EPA energy efficiency mandates are tightening procurement specifications for industrial lighting audits, requiring documented luminous flux measurements for rebate qualification. Manufacturing facilities must now maintain calibrated illuminometer records spanning fixture installation through operational verification. The regulation is reshaping equipment specification sheets, with OSHA workplace lighting standards adding parallel documentation burdens in US industrial verticals.
Service unbundling is separating hardware ownership from calibration certification, with end-users subscribing to traceable verification rather than purchasing capital equipment. LED testing laboratories are leading this shift, outsourcing metrology-grade confirmation to accredited mobile service providers. Japan's precision instrument ecosystem exhibits the most advanced adoption, where METI industrial standards encourage outcome-based photometric compliance over asset accumulation.
Illuminometer Market Segmentation
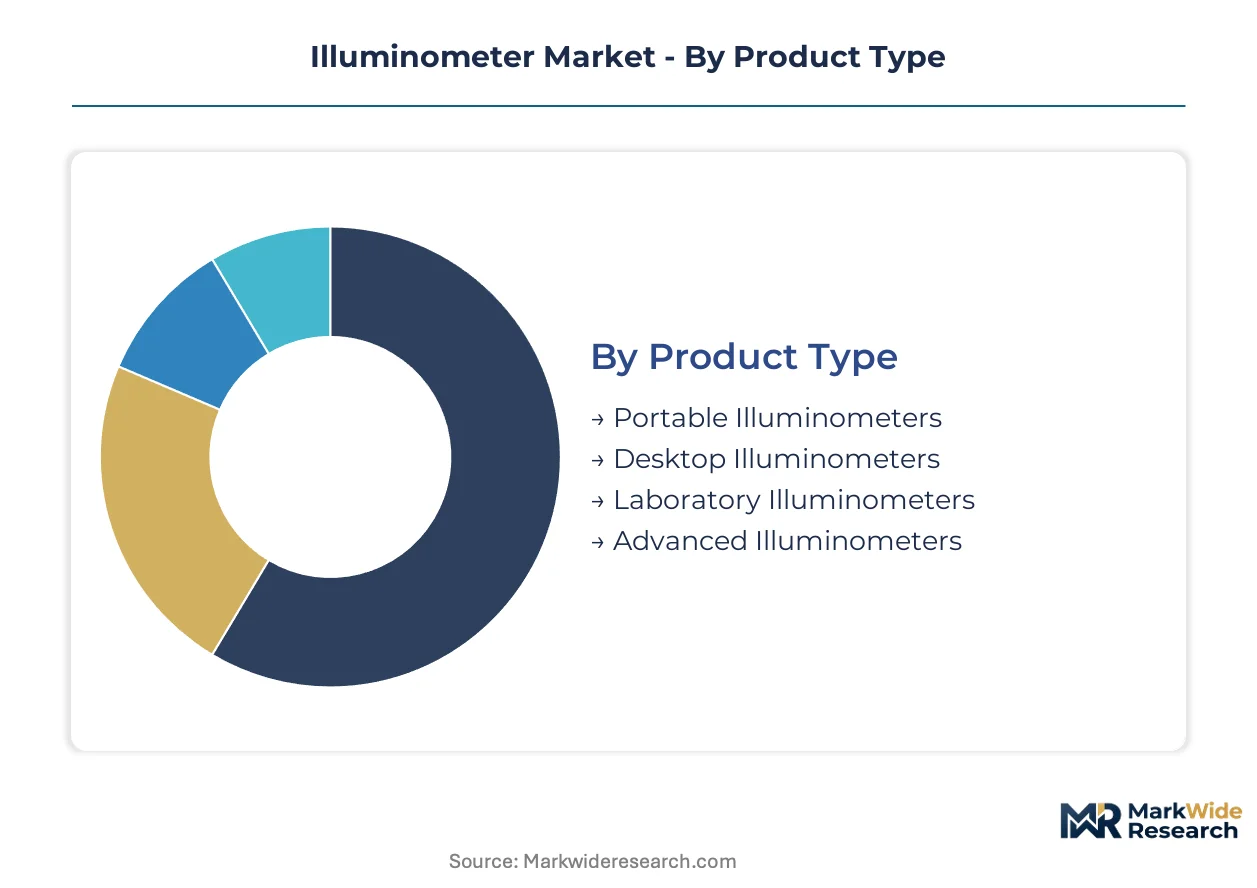
Illuminometer procurement patterns diverge sharply between volume-driven facility maintenance and precision-grade laboratory certification. Understanding these splits reveals where silicon photodiode economics reshape competitive positioning and where NIST-traceable workflows defend margin pools.
Product Type:
Portable units dominate shipment volumes while laboratory systems capture premium pricing through calibration complexity.
- Portable Illuminometers:Handheld units employ silicon photodiode arrays with CIE-corrected spectral response for facility maintenance mobility. Demand concentrates in commercial real estate LED retrofit commissioning across Germany and the United States, driven by OSHA workplace documentation mandates. Today's leader: Portable Illuminometers. Tomorrow's challenger: Advanced Illuminometers.
- Laboratory Illuminometers:These systems integrate photomultiplier tubes or charge-coupled devices with multi-channel spectral analysis for NIST-traceable certification. Procurement clusters in Japan's METI-regulated industrial standards environment and German metrology institutes, constrained by technician scarcity in photometric standard maintenance.
- Desktop Illuminometers:Mid-tier fixed installations serve quality control stations with simplified calibration protocols.
- Advanced Illuminometers:Sensor fusion architectures with wireless logging capabilities target building automation integration.
Form factor decisions increasingly hinge on whether compliance requires asset ownership or outcome-based verification subscriptions.
End User:
Research infrastructure commands calibration premiums while industrial verticals drive replacement cycle compression.
- Research Labs:Academic and government facilities require IEC-compliant electromagnetic compatibility with documented uncertainty budgets. Japan's precision instrument ecosystem leads adoption of service-unbundled verification models.
- Industrial Facilities:Manufacturing plants combine EPA energy efficiency audit requirements with OSHA lighting standard documentation. LED testing laboratories within this segment are climbing the fastest as solid-state lighting retrofits multiply.
- Educational Institutions:Budget-constrained procurement favors silicon photodiode-based portable units for undergraduate photometry instruction.
- Environmental Monitoring:Field-deployable units with ruggedized enclosures serve ecological research stations requiring spectral data logging.
Industrial Facilities currently anchor replacement demand. Research Labs are shifting fastest toward subscription-based calibration services.
Technology:
Digital architectures displace analog legacy while LED-based sensing creates new performance tiers.
- LED-Based Sensors:Solid-state detection elements matched to CIE photopic curves deliver cost-performance breakthroughs for mid-tier portfolios. Demand concentrates in LED testing laboratories verifying commercial and residential fixture compliance, constrained by spectral sensor fusion R&D capital requirements.
- Digital Sensors:Microprocessor-corrected silicon photodiode arrays with Bluetooth-enabled data transmission expand into HVAC-lighting crossover applications.
- Analog Sensors:Legacy photodiode circuits persist in budget-sensitive educational procurement.
- Photoelectric Sensors:Vacuum tube and semiconductor photomultiplier systems retain dominance in cinematography color-temperature accuracy niches where premium positioning resists commoditization.
LED-Based Sensors are gaining share fastest through retrofit verification protocols. Photoelectric Sensors defend margin pools in specialized metrology.
Application:
Quality control standardization creates volume anchors while exhibition lighting demands spectral precision.
- Quality Control:Manufacturing line integration requires documented luminous flux measurements for fixture validation. German automotive and electronics plants lead procurement of IEC-classified handheld units.
- LED Testing:Solid-state lighting verification protocols span installation through operational audit, with EPA rebate qualification reshaping specification sheets.
- Environmental Assessment:Ecological field studies employ portable units for rapid lux mapping of habitat light pollution.
- Exhibition Lighting:Museum and gallery applications demand color-rendering index correlation with illuminance measurement, commanding premium sensor configurations.
Quality Control anchors current procurement volumes. LED Testing exhibits the steepest expansion trajectory as compliance frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision optics corridor anchors illuminometer manufacturing concentration. Japan's METI-regulated industrial standards environment drives metrology-grade procurement. The United States concentrates laboratory-grade demand through OSHA workplace documentation mandates.
United States
EPA energy efficiency audit requirements and OSHA workplace lighting standards compress equipment replacement cycles. Industrial facilities in Michigan and Ohio automotive corridors procure IEC-classified handheld units for fixture validation documentation. LED testing laboratories in Greater Boston and Silicon Valley lead service-unbundled verification adoption.
Germany
Automotive and electronics manufacturing clusters demand NIST-traceable calibration workflows for quality control integration. The country's national metrology institute enforces CIE photopic curve alignment for cross-border equipment acceptance. Bavaria's precision instrument ecosystem concentrates photomultiplier tube manufacturing for laboratory-grade systems.
Japan
METI industrial standards encourage outcome-based photometric compliance over asset accumulation. The Kanto region's precision instrument ecosystem exhibits the most advanced service-unbundled verification adoption. Photoelectric sensor miniaturization R&D concentrates in Nagoya's industrial automation corridor.
China
GB standards for solid-state lighting verification multiply retrofit commissioning protocols across manufacturing facilities. The Yangtze River Delta's electronics manufacturing belt drives demand for silicon photodiode-based portable units. Shenzhen's LED testing laboratories expand capacity for commercial fixture compliance verification.
South Korea
Seoul Capital Area's semiconductor fabrication facilities require electromagnetic compatibility-certified instruments for cleanroom lighting audits. The national semiconductor regulator enforces spectral data logging for energy efficiency rebate qualification. Busan-Ulsan's industrial corridor anchors HVAC-lighting crossover application procurement.
Illuminometer Market Competitive Landscape
Portfolio diversification dominates the current landscape as participants rebalance between laboratory-grade calibration services and handheld volume shipments. The vendor base stratifies across three tiers: precision optics heritage houses, HVAC instrumentation generalists, and photographic metering specialists. Two strategic archetypes occupy distinct positions: metrology-grade certification defenders leveraging NIST-traceable workflows, and silicon photodiode cost-optimizers targeting facility maintenance mobility. M&A activity concentrates in sensor fusion capabilities, while geographic expansion targets LED testing laboratory clusters in East Asia.
Within the precision optics heritage tier, Konica Minolta Sensing Americas and Sekonic exemplify divergent specialization strategies. Testo SE anchors the HVAC-lighting crossover archetype through channel density in building automation integration. These three entities collectively represent the spectrum from laboratory-grade calibration dominance to facility maintenance volume capture.
| Leading Market Players |
|---|
| Konica Minolta Sensing Americas |
| FLIR Systems |
| Sekonic |
| Testo SE |
| Hioki |
| Amprobe |
| KERN & SOHN |
| B&K Precision |
| Line Seiki |
| Others |
Supply & Pricing Matrix
Family-owned precision optics specialists in Bavaria and Nagoya anchor component manufacturing, their multi-generational capital structures enabling patient R&D cycles that defend premium pricing tiers against silicon photodiode commoditization. Their ownership concentration limits price transparency, forcing mid-tier buyers into long-term calibration service contracts rather than transactional equipment purchases.
Pricing Analysis
Photodiode array cost curves determine pass-through elasticity across tiered equipment portfolios. Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable laboratory systems from handheld facility maintenance units and educational procurement. Cost compression in silicon photodiode manufacturing is intensifying because wafer-scale integration reduces die-level economics, pressuring mid-tier margins. Educational institutions exhibit highest price sensitivity, while cinematography color-temperature accuracy niches resist downward negotiation.
Supply Chain Analysis
CIE photopic curve certification gates component qualification, extending supplier onboarding timelines for photomultiplier tube and precision photodiode arrays. Manufacturing concentrates in Germany, Japan, and the United States for metrology-grade optics, with Taiwan and South Korea supplying silicon wafer substrates. Raw material dependencies span rare-earth phosphors, high-purity silicon, and vacuum-grade glass envelopes. Single-source vulnerability concentrates in German precision optics corridors. Distribution runs through metrology-certified channel partners serving laboratory and industrial verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The illuminometer market reads as a late-cycle quality story where LED testing laboratory expansion shifts procurement toward NIST-traceable specifications that resist commoditization. Solid-state lighting retrofit mandates across commercial and residential sectors are accelerating this premium migration.
For Market Incumbents: Anchor calibration service density in LED testing laboratory clusters before silicon photodiode miniaturization erodes laboratory-grade margins. Deepen backward integration into photodiode array manufacturing to capture cost compression benefits. Defend against HVAC instrumentation generalists by certifying dual-function illuminometer-HVAC instruments under IEC electromagnetic compatibility standards. For New Entrants and Emerging Players: Building automation integrators represent the most accessible channel pathway for wireless-enabled advanced illuminometers. White space concentrates in HVAC-lighting crossover applications where facility maintenance teams seek single-instrument mobility. Target South Korea's semiconductor fabrication corridor for electromagnetic compatibility-certified cleanroom lighting audit procurement. Pursue sensor fusion partnerships rather than in-house R&D to circumvent spectral integration capital intensity. For Investors and Strategic Acquirers: Precision instrument conglomerates are the most active acquirer in this space, consolidating photometric calibration capabilities across industrial verticals. Long-term viability hinges on service-revenue model transition from hardware replacement to subscription-based traceable verification. Acquisition targets should demonstrate METI or NIST accreditation pipelines. Monitor Japan's service-unbundled verification adoption rates as inflection indicator for global model migration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Architecture Development | Multi-channel spectral integration compresses field-laboratory verification boundaries for building automation. |
| Wireless Calibration Logging Platform | Bluetooth-enabled data transmission expands service-revenue models displacing hardware replacement cycles. |
| Backward Integration into Photodiode Manufacturing | Wafer-scale silicon economics defend mid-tier margins against educational procurement price sensitivity. |
| HVAC-Lighting Crossover Certification | IEC electromagnetic compatibility classification opens facility maintenance mobility requirements to dual-function instruments. |
| LED Testing Laboratory Service Unbundling | Outcome-based photometric compliance contracts under METI standards reduce customer capital expenditure barriers. |
Research Methodology
Coverage spans Germany, Japan, the United States, China, and South Korea, with primary inputs from each region's precision instrument manufacturing clusters and LED testing laboratory networks. The analysis combines structured interviews with photometric calibration technicians, HVAC facility maintenance directors, semiconductor fabrication lighting auditors, and building automation system integrators with secondary validation from IEC standards documentation, EPA energy efficiency audit protocols, OSHA workplace lighting guidelines, and METI industrial standards publications. Bottom-up equipment shipment analysis triangulates against top-down retrofit verification protocol expansion models.
Granularity extends to product type, end user, technology, and application dimensions, with additional modeling of certification tier and connectivity protocol adoption. CAGRs derive from equipment replacement cycle compression rates and service-revenue model transition velocity across the projection horizon. Forecast inputs incorporate solid-state lighting retrofit mandates, NIST-traceable technician scarcity trajectories, and silicon photodiode cost curve slopes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to spectral sensor fusion R&D breakthroughs and regulatory harmonization between CIE and IEC standards. The analysis reflects assumptions regarding LED penetration rates and metrology-grade component supply stability. A model refresh is warranted upon material change in EPA or OSHA documentation mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Near-Infrared Spectroscopy Market
Analytical Instruments
Handheld XRF Analyzers Market
Analytical Instruments
Ultraviolet (UV) Analyzer Market
Analytical Instruments
Portable Chromatography Systems Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Global Terahertz and Infrared Spectroscopy Market
Analytical Instruments
Seawater Refractometers Market
Analytical Instruments
Wireless Handheld Spectrometer Market
Analytical Instruments
Handheld Laser Measuring Instrument Market
Analytical Instruments
Infrared Spectroscopy Devices Market
Analytical Instruments
Spectroscopy Software Market
Analytical Instruments
Headspace Gas Analyzers Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Europe Surface Analysis Market
Analytical Instruments
Automated Microplate Handling Systems Market