
 Global Ultrapycnometer Market | 2026-2036
Global Ultrapycnometer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultrapycnometer Market Foresight
Direct distribution from manufacturers to material testing labs is reshaping how ultrapycnometer vendors reach end users. Anton Paar leverages its Austrian headquarters to sustain premium positioning across European research institutions. Micromeritics Instrument Corporation anchors North American demand through deep relationships with pharmaceutical quality control departments. Quantachrome Instruments competes in ceramics testing with specialized gas-displacement configurations.
An ultrapycnometer measures the true density of solids and powders via gas-displacement pycnometry, typically achieving precision within 0.02% using helium as the displacing medium at controlled temperature and pressure. The instrument eliminates errors from closed pores and surface roughness, making it essential for pharmaceutical tablet characterization, catalyst support analysis, and additive manufacturing powder qualification. Gas-displacement systems dominate revenue due to their universality across porous and non-porous materials, while automated configurations capture the fastest growth as labs seek throughput gains in high-volume quality control environments. Helium pycnometry leads technology adoption where absolute accuracy matters, though nitrogen alternatives gain traction in cost-sensitive geologies and ceramics testing applications.
FDA guidelines on solid oral dosage form physical characterization and EMA quality standards for porosity measurement shape product development priorities for vendors seeking market access. REACH compliance in Europe and EPA chemical handling requirements in the United States add certification complexity that favors established manufacturers with regulatory affairs infrastructure. Stakeholders must monitor how evolving ISO standards for density measurement harmonize with regional pharmacopeial requirements to avoid compliance fragmentation.
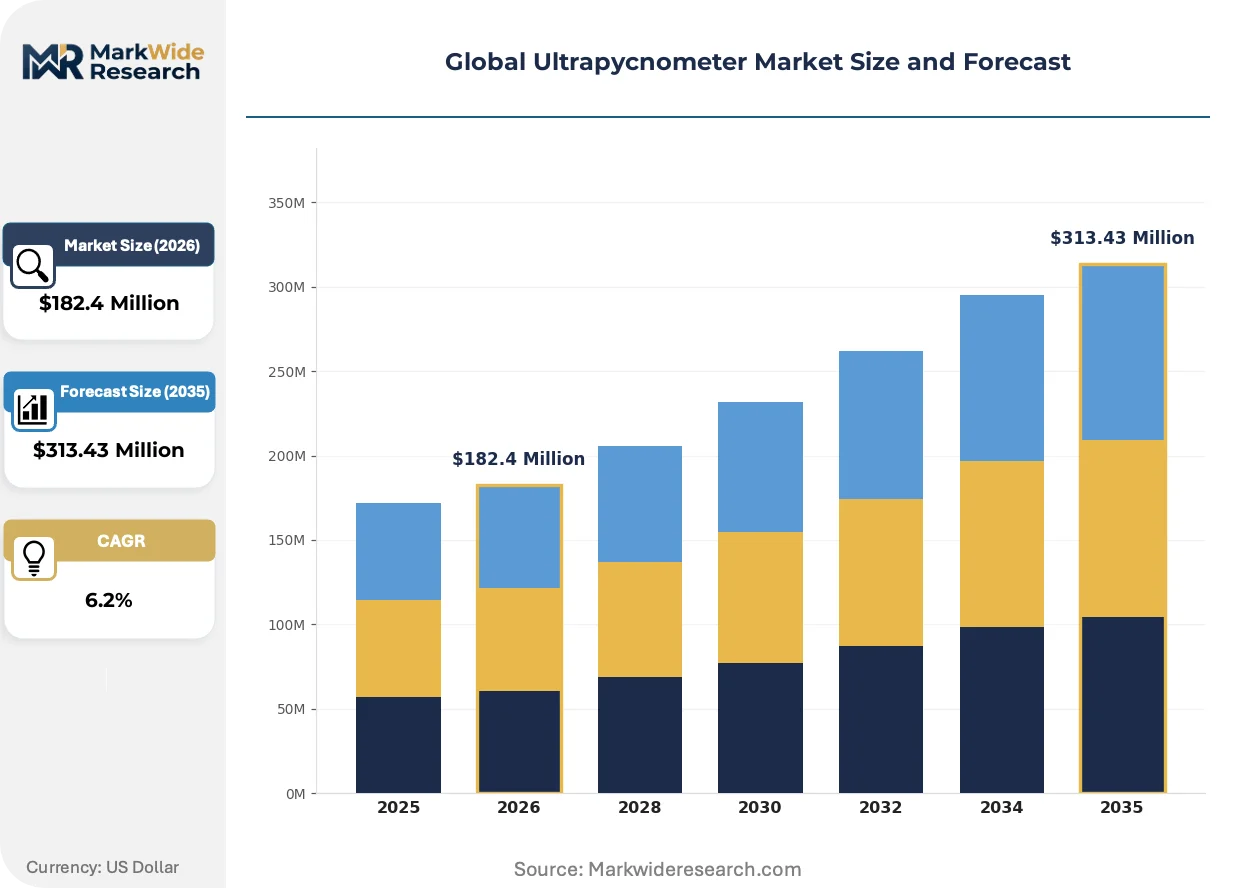
Market Dynamics
Helium supply volatility and tightening pharmacopeial density standards are compressing equipment replacement cycles while forcing vendors to certify nitrogen-compatible configurations for cost-sensitive buyers.
Growth Catalysts
- FDA Solid Dosage Characterization Guidelines:Updated physical testing requirements for tablet porosity and true density verification mandate helium pycnometry in US pharmaceutical QC labs, accelerating equipment procurement timelines.
- Additive Manufacturing Powder Qualification:Aerospace and medical device manufacturers require precise density verification for titanium and cobalt-chrome powders, expanding addressable demand beyond traditional ceramics and pharma testing.
- Germany:Automotive lightweighting programs in Baden-Württemberg and Bavaria drive density testing for aluminum-lithium alloys and carbon-fiber composites in supplier material labs.
Market Restraints
- Helium Cost Volatility:US Bureau of Land Management helium auction price fluctuations and Qatar supply disruptions inflate operating costs for high-throughput labs running continuous analysis cycles.
- Technical Limitation:Closed-pore measurement uncertainty in microporous activated carbons and metal-organic frameworks restricts application scope for standard gas-displacement configurations without mercury intrusion backup.
- REACH Compliance Burden:ECHA chemical handling documentation requirements for helium and nitrogen systems add certification costs that disadvantage smaller European testing laboratories.
Strategic Opportunities
- India:CDSCO's phased implementation of physical characterization standards for generic solid oral dosages creates first-mover positioning for automated pycnometry vendors in Mumbai and Hyderabad pharma clusters.
- Battery Materials Testing:Cathode powder density verification for lithium iron phosphate and nickel-cobalt-manganese formulations represents an emerging application vector as cell manufacturers internalize QC capabilities.
- Remote Diagnostics Integration:IoT-enabled predictive maintenance and automated calibration reporting reduce field service dependency, opening subscription revenue streams for instrument vendors.
Industry Challenges
- Metrology Skill Shortage:Gas pycnometry operation and thermal equilibration protocol expertise concentrates among senior technicians, constraining lab expansion in high-growth geographies.
- Multi-Instrument Integration Complexity:Synchronizing ultrapycnometer data streams with laser diffraction particle size analyzers and mercury porosimeters requires custom LIMS middleware that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultrapycnometer Market |
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $313.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas-Displacement, Liquid-Displacement, Automated, Manual Technology: Helium Pycnometry, Nitrogen Pycnometry, Thermal Conductivity Sensor, Ultrasonic Measurement Application: Pharmaceuticals, Geology, Ceramics Testing, Metallurgy Analysis, Food Quality End User Industry: Research Institutions, Material Testing Labs, Chemical Manufacturing, Aerospace Components, Academic Laboratories |
| Companies Covered | Xihua Instrument (Beijing) Technology, Anton Paar, Gilson, Mettler-Toledo, Quantachrome Instruments, Micromeritics Instrument Corporation, Porotech, 3P Instruments, Bel Japan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultrapycnometer Market Shifts & Advancements
Automation and multi-gas flexibility are displacing manual helium-only systems as buyers prioritize throughput resilience against supply shocks and evolving material portfolios.
Multi-gas pycnometry is hybridizing helium precision with nitrogen cost efficiency through programmable switching protocols that adapt displacement medium to sample porosity and required accuracy tier. Pharmaceutical contract manufacturers in Switzerland and New Jersey are piloting these configurations to hedge helium price exposure without sacrificing USP compliance for high-value drug products. The technology is hybridizing equipment specifications across premium and mid-market tiers, compressing the traditional performance-cost tradeoff that segmented the installed base.
REACH F-Gas Regulation amendments and EPA Significant New Alternatives Policy evaluations are accelerating refrigerant-grade helium recovery and recycling mandates for industrial gas users. European analytical labs face mandatory closed-loop helium capture systems by 2027, redirecting capex toward auxiliary infrastructure rather than core measurement capability. German and French research institutions are responding with shared-service gas recovery networks that pool equipment costs across regional consortia.
Service unbundling is fragmenting the traditional instrument-plus-maintenance bundle as buyers favor à la carte calibration contracts and remote technical support subscriptions over comprehensive service agreements. Academic and government labs in Japan and South Korea are driving this pattern, pressured by frozen capital budgets and preference for operational expenditure treatment. The shift compresses vendor recurring revenue visibility while opening third-party metrology service entry points.
Global Ultrapycnometer Market Segmentation
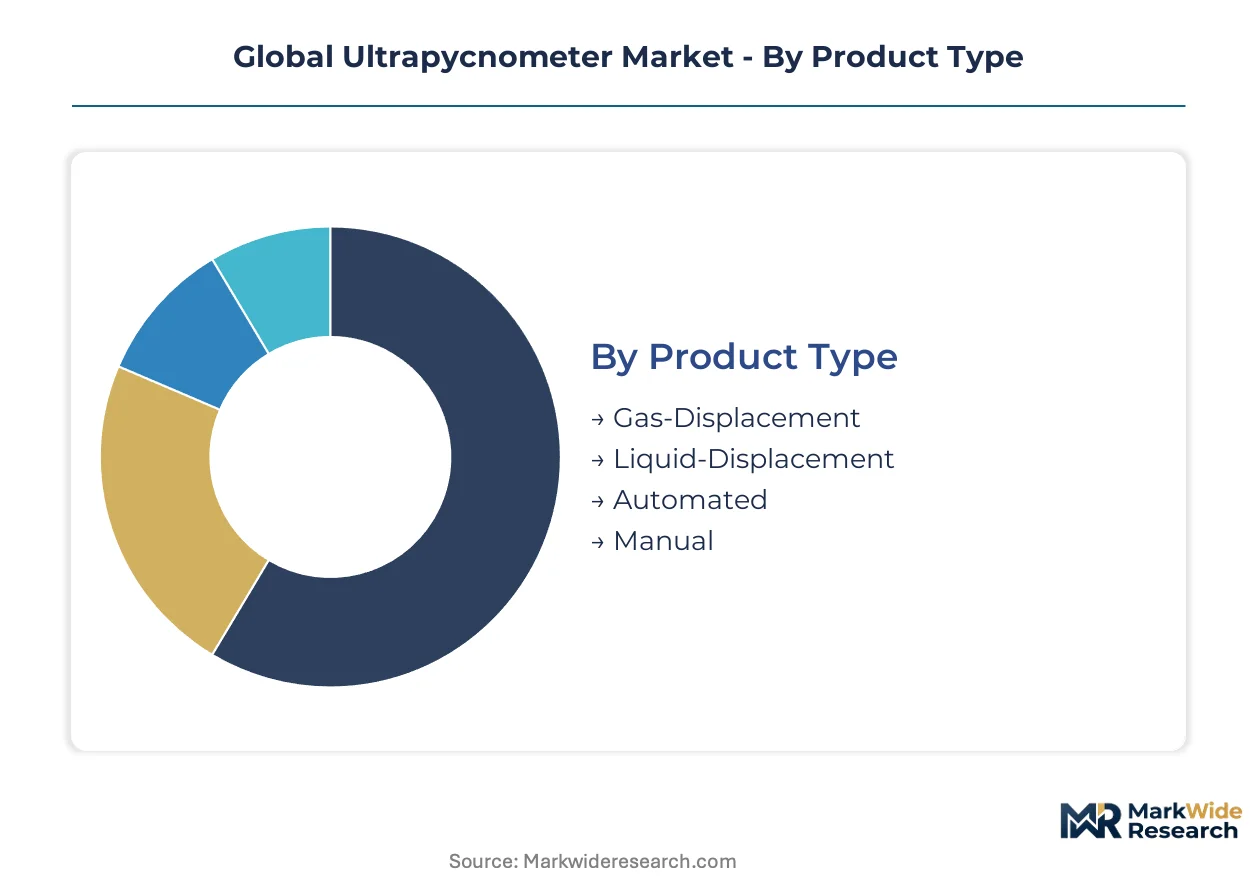
Ultrapycnometer demand fragments across measurement principles, gas media, and end-use requirements that dictate precision thresholds, throughput needs, and regulatory compliance burdens. Vendors configure product portfolios around these intersecting demands rather than pursuing horizontal coverage.
Product Type:
Use-case spectrum spans high-throughput pharmaceutical QC requiring unattended batch processing to budget-constrained academic labs prioritizing manual operation over capital efficiency.
- Gas-Displacement:Helium or nitrogen displacement at controlled temperature and pressure delivers true density independent of surface roughness or closed porosity. Pharmaceutical manufacturers in Germany and the United States specify these systems for USP density verification of tablet cores and granulations. The dominant share belongs to Gas-Displacement, while Automated is closing the gap fastest.
- Automated:Robotic sample changers and integrated data handling enable overnight batch runs of 50+ samples with LIMS connectivity. Swiss contract manufacturers deploy these configurations to meet FDA data integrity requirements while minimizing technician presence. Automated configurations are expanding most quickly as labor costs rise in North American and European QC environments.
- Liquid-Displacement:Archimedes principle using fluorinated fluids suits samples incompatible with gas media, including reactive metal powders and moisture-sensitive pharmaceuticals. Limited to specialized metallurgy and pyrophoric material applications where gas penetration risks sample degradation.
- Manual:Single-sample loading with operator-controlled equilibration protocols serves teaching laboratories and low-volume R&D settings in Indian and Brazilian academic institutions where capital constraints override throughput requirements.
Automation investments concentrate where labor arbitrage has eroded and regulatory data trails are mandatory.
Technology:
Cost tier stratification separates absolute accuracy requirements from budget-sensitive screening applications, with gas choice directly determining operating expenditure profiles.
- Helium Pycnometry:Monoatomic gas penetrates micropores down to 0.3 nm diameter, achieving precision within 0.02% for pharmaceutical porosity standards and catalyst support characterization. EMA quality guidelines and FDA physical testing requirements mandate helium for regulatory submissions in solid dosage forms. Helium Pycnometry commands the installed base, though Nitrogen Pycnometry is climbing the fastest as supply volatility forces hedging strategies.
- Nitrogen Pycnometry:Diatomic alternative reduces operating costs by 60-70% for ceramics testing and geological screening where sub-percent precision satisfies specification limits. Indian geology labs and Chinese ceramics manufacturers are standardizing nitrogen configurations to insulate budgets from helium auction price spikes.
- Thermal Conductivity Sensor:Gas composition detection enables rapid purity verification in multi-gas systems, supporting programmable switching between helium and nitrogen displacement media.
- Ultrasonic Measurement:Non-gas alternative for slurry density and liquid-immersed samples in food quality applications where gas displacement risks moisture loss or oxidation.
Multi-gas flexibility is compressing the traditional premium-mid-economy equipment tiers into overlapping capability bands.
Application:
Volume concentration tracks regulatory enforcement intensity and material qualification stringency across pharmaceutical, aerospace, and advanced materials supply chains.
- Pharmaceuticals:Tablet true density and porosity verification for dissolution prediction and coating uniformity. FDA solid dosage characterization guidelines and EMA quality standards mandate helium pycnometry in release testing protocols for US and European markets. Pharmaceuticals holds the revenue concentration, while Ceramics Testing is gaining share fastest.
- Ceramics Testing:Sintered density verification for structural ceramics, refractories, and electronic substrates. German automotive suppliers and Japanese semiconductor equipment manufacturers require sub-0.1% precision for thermal management components.
- Geology:Core plug porosity and grain density for reservoir characterization. Cost-sensitive mining operations in Australia and Canada favor nitrogen configurations for exploration-stage screening.
- Metallurgy Analysis:Powder bed fusion feedstock qualification for titanium and nickel superalloys in aerospace additive manufacturing. Boeing and Airbus supply chains in France and the United States internalizing density QC to reduce qualification timelines.
- Food Quality:Solid fat content and aerated structure analysis for confectionery and baked goods. Limited penetration outside Swiss and Belgian chocolate manufacturers with premium positioning requirements.
Application mix is shifting toward powder qualification as additive manufacturing scales and battery cathode production internalizes metrology capabilities.
End User Industry:
Customer type determines procurement authority, service contract preferences, and upgrade cadence, with commercial labs outpacing academic institutions in replacement frequency.
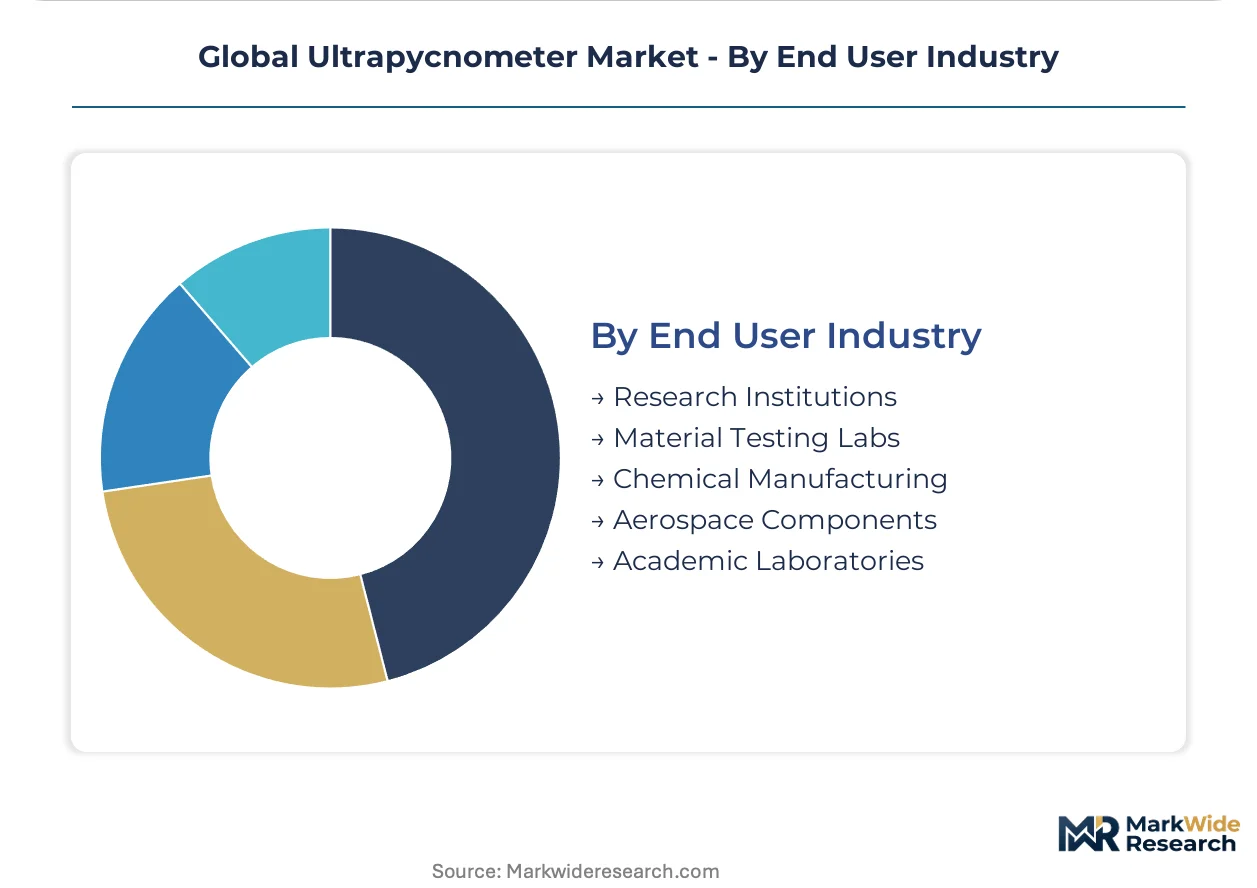
- Material Testing Labs:Third-party certification bodies serving automotive and aerospace supply chains in Baden-Württemberg, Michigan, and Toulouse. ISO 17025 accreditation requirements drive 5-7 year replacement cycles and comprehensive service contracts. Material Testing Labs anchor current demand, while Aerospace Components is accelerating most rapidly.
- Aerospace Components:Tier-1 and OEM internal metrology departments qualifying titanium, Inconel, and aluminum-lithium powders for laser powder bed fusion. GE Aviation and Safran facilities in Cincinnati and Bordeaux deploying automated systems for 100% lot release testing.
- Research Institutions:Max Planck Institutes, DOE national laboratories, and CNRS units pursuing method development and reference material certification. Preference for manual configurations with maximum flexibility over throughput optimization.
- Chemical Manufacturing:Catalyst support characterization and polymer density verification. BASF and Dow facilities in Ludwigshafen and Midland integrating pycnometry with particle size and surface area workflows.
- Academic Laboratories:University teaching and thesis research in Mumbai, São Paulo, and Seoul. Frozen capital budgets favor refurbished equipment and third-party calibration services over comprehensive vendor agreements.
End user mix is tilting toward captive industrial labs as supply chain qualification burdens shift upstream from OEMs to material suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA solid dosage characterization guidelines anchor demand in the United States, where pharmaceutical quality control departments drive equipment procurement timelines. Material testing labs across Germany, Japan, India, and Switzerland respond to parallel regulatory pressures while serving automotive, aerospace, and ceramics supply chains.
United States
Pharmaceutical manufacturers in New Jersey and North Carolina expand helium pycnometry capacity for tablet porosity verification. FDA physical testing requirements for solid oral dosage forms mandate true density measurement in release protocols. Boston-area biotech clusters and Midwest automotive material labs in Michigan sustain dual demand streams for precision density instrumentation.
Germany
Automotive lightweighting programs in Baden-Württemberg and Bavaria require density testing for aluminum-lithium alloys and carbon-fiber composites. REACH F-Gas Regulation amendments accelerate closed-loop helium recovery mandates for analytical labs by 2027. Stuttgart and Munich material testing facilities deploy shared-service gas recovery networks to pool infrastructure costs across regional consortia.
Japan
Academic and government labs in Tokyo and Osaka favor service unbundling and operational expenditure treatment over comprehensive vendor agreements. Frozen capital budgets drive preference for à la carte calibration contracts and remote technical support subscriptions. National institute clusters in Tsukuba and Nagoya pursue method development with manual configurations prioritizing flexibility.
India
CDSCO phased implementation of physical characterization standards for generic solid oral dosages creates procurement windows in Mumbai and Hyderabad pharma clusters. Cost-sensitive geology labs standardize nitrogen pycnometry configurations to insulate budgets from helium price volatility. Contract manufacturers in Gujarat and Karnataka pilot multi-gas systems to balance precision requirements against operating expenditure constraints.
Switzerland
Contract manufacturers in Basel and Geneva pilot multi-gas pycnometry configurations to hedge helium price exposure without sacrificing USP compliance. Swissmedic quality standards for high-value drug products sustain premium equipment specifications. Chocolate manufacturers in Vevey and Bern deploy density verification for solid fat content analysis in premium confectionery positioning.
Global Ultrapycnometer Market Competitive Landscape
Precision instrumentation specialists and diversified analytical platform providers split the market between dedicated density measurement capability and integrated particle characterization workflows. The installed base concentrates among vendors with established regulatory affairs infrastructure capable of navigating FDA, EMA, and REACH certification complexity. Two archetypes dominate: Austrian and German precision engineering houses with deep European research institution relationships, and North American platform players leveraging pharmaceutical quality control integration. Competitive moves center on multi-gas configuration development and predictive maintenance service models.
Within the precision engineering tier, Anton Paar exemplifies premium positioning sustained through Austrian headquarters proximity to European research institutions. Among North American platform providers, Micromeritics Instrument Corporation and Quantachrome Instruments occupy positions anchored by pharmaceutical and ceramics testing relationships respectively. Xihua Instrument (Beijing) Technology represents the Chinese specialist archetype serving cost-sensitive academic and industrial markets. These three company types illustrate geographic and application-based segmentation rather than direct horizontal competition.
| Leading Market Players |
|---|
| Xihua Instrument (Beijing) Technology |
| Anton Paar |
| Gilson |
| Mettler-Toledo |
| Quantachrome Instruments |
| Micromeritics Instrument Corporation |
| Porotech |
| 3P Instruments |
| Bel Japan |
| Others |
Supply & Pricing Matrix
Helium supply volatility between Qatar and the United States determines both the premium commanded by multi-gas configurations and the geographic shape of vendor distribution networks. Equipment pricing spreads widen as buyers hedge against commodity-driven operating cost spikes through nitrogen-compatible system investments.
Pricing Analysis
The customization-premium spread separates configured-to-order automated systems from standard manual configurations by a factor reflecting robotics integration and LIMS connectivity. Pricing stratifies across premium helium-precision tiers, standard multi-gas flexibility tiers, and economy nitrogen-only tiers based on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Chinese academic buyers prioritize capital efficiency over throughput. Contract manufacturers in Switzerland and New Jersey exhibit the least price sensitivity, while geology labs in Australia and Canada drive procurement through total cost of ownership calculations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for sensor assemblies and precision pressure transducers. Manufacturing concentrates in Germany, Austria, and the United States for high-precision gas handling components, while China supplies machined enclosures and electronic subassemblies. Raw material dependencies rest on helium gas sourcing from Qatar and the US Bureau of Land Management reserves, specialty steel alloys from Sweden, and ceramic sensor substrates from Japan. Distribution runs through direct manufacturer-to-lab channels in North America and Europe, with third-party analytical equipment distributors serving price-sensitive Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
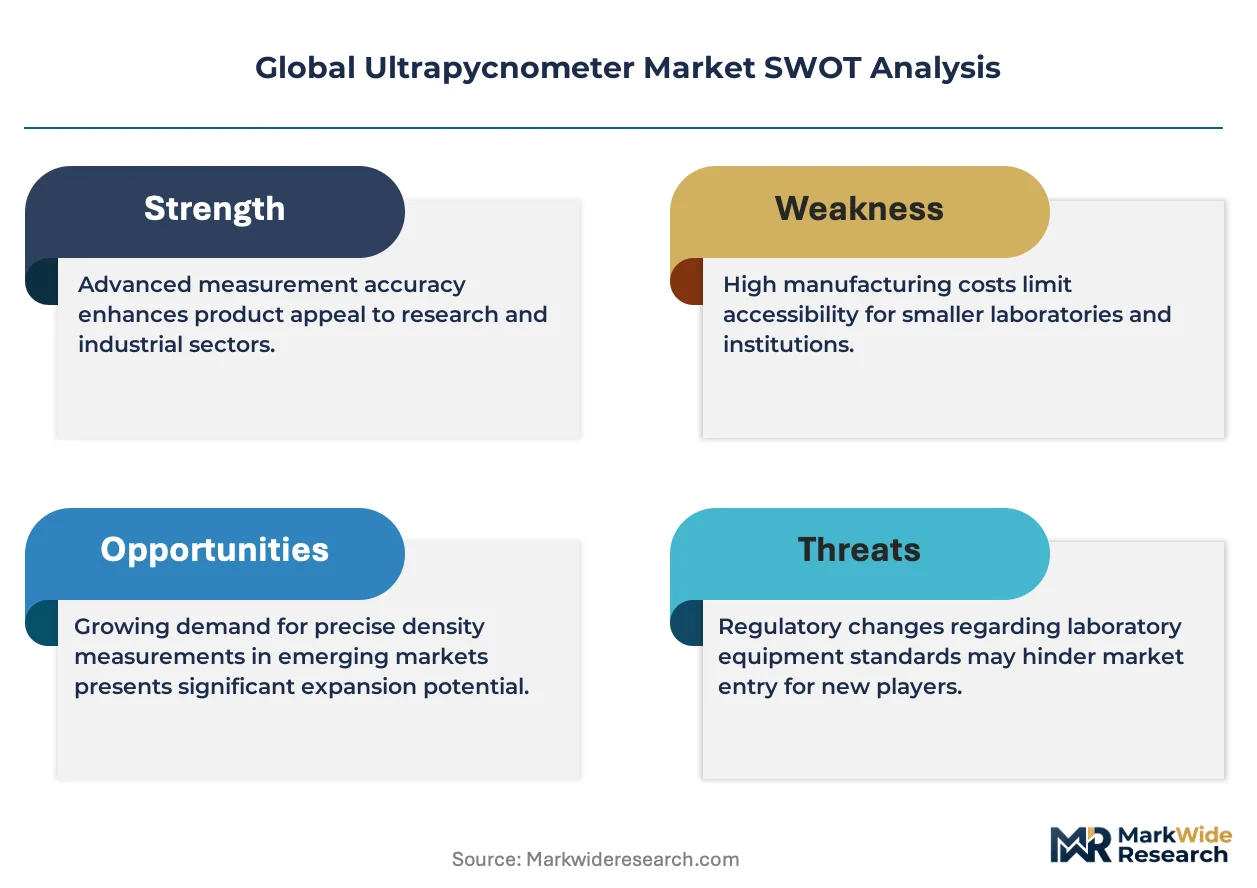
The ultrapycnometer market is recovering from a cyclical trough as pharmaceutical capital expenditure budgets rebound post-pandemic and additive manufacturing qualification protocols mature.
For Market Incumbents: Insulate recurring revenue streams by embedding predictive maintenance subscriptions and remote calibration services that reduce third-party metrology entry points. Deepen backward integration into helium recovery system partnerships to capture auxiliary infrastructure spending mandated by REACH F-Gas Regulation amendments. Defend against nitrogen-priority challengers by certifying dual-gas configurations that preserve precision advantages while matching competitor operating cost positions. For New Entrants and Emerging Players: Establish a beachhead in battery materials testing by targeting cathode powder density verification workflows at cell manufacturers internalizing QC capabilities. Penetrate the Indian contract manufacturing segment through nitrogen-first configurations that align with CDSCO phased implementation timelines and local budget constraints. Pursue academic lab clusters in Brazil and South Korea with refurbished equipment programs and unbundled service contracts that convert capital expenditure to operational expenditure treatment. For Investors and Strategic Acquirers: ECHA's 2027 closed-loop helium capture mandate reshapes the acquisition landscape toward vendors with regulatory affairs infrastructure capable of navigating certification complexity. Long-term viability centers on automated multi-gas platforms serving pharmaceutical and aerospace captive labs rather than manual configurations dependent on academic replacement cycles. Target acquisition archetypes include precision engineering specialists with established European research institution relationships and IoT-enabled service platforms. The signal to watch is CDSCO enforcement intensity in Mumbai and Hyderabad as a leading indicator of emerging market equipment procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Gas Configuration Development | Programmable helium-nitrogen switching hedges commodity exposure while preserving FDA compliance pathways. |
| Predictive Maintenance Service Launch | IoT-enabled remote diagnostics reduce field service dependency and open subscription revenue streams. |
| Helium Recovery Infrastructure Partnership | Closed-loop capture systems address REACH mandates and redirect capex toward vendor-controlled auxiliary equipment. |
| Battery Materials Application Development | Cathode powder density verification captures emerging demand from cell manufacturer internalization of QC. |
| Academic Market Service Unbundling | À la carte calibration contracts align with frozen capital budgets in Japanese and South Korean institutions. |
Research Methodology
A spread of perspectives from pharmaceutical quality control directors, aerospace materials engineers, analytical lab procurement managers, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary field engagement with instrument vendors and end-user facilities was combined with secondary validation against FDA guidance documents, EMA quality standards, ISO density measurement protocols, and trade data from analytical equipment customs classifications. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates across the projection horizon.
Demand-supply-balance framing anchored the forecast framework, with equipment procurement timelines modeled against pharmaceutical capital expenditure cycles, additive manufacturing qualification protocol maturation, and battery cell manufacturing capacity buildouts. Segmentation dimensions included product type, gas media technology, application vertical, and end-user industry tier. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of regulatory enforcement intensity. Industry-specific inputs incorporated helium auction price volatility scenarios and CDSCO implementation phase schedules.
Stress conditions across helium supply disruption, tariff escalation on Chinese-sourced components, and accelerated regulatory timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding replacement cycle compression and multi-gas adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Micro Balances Market
Analytical Instruments
Global Scanning Probe Microscopes (Spm) Market
Analytical Instruments
Global Electron Microscopy and Sample Preparation Market
Analytical Instruments
Electron Microscope Sample Preparation Market
Analytical Instruments
Global PH Electrochemical Electrodes Market
Analytical Instruments
ICP-OES Spectrometer Market
Analytical Instruments
Melt Flow Meter Market
Analytical Instruments
Flame Photometer Market
Analytical Instruments
Complexion Analysis System Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
X-Ray Fluorescence Analyzer Market
Analytical Instruments
Handheld XRF Spectrometer Market
Analytical Instruments
North America Analytical Instrumentation Market
Analytical Instruments
Universal Probe Library Market
Analytical Instruments
Spectroscopy Equipment and Supplies Market
Analytical Instruments
Microfluidic Modulation Spectroscopy Market