
 Analytical Instrumentation for Food Applications Market | 2026-2036
Analytical Instrumentation for Food Applications Market Size, Share, and Industry Trends Forecast 2026-2036
Analytical Instrumentation for Food Applications Market Insights
Modular instrument configurations is broadening buyer choice across the food testing landscape. Thermo Fisher Scientific leverages its chromatography portfolio to anchor high-throughput nutritional analysis workflows for multinational food manufacturers. Agilent Technologies competes through specialized mass spectrometry platforms designed for pesticide residue quantification at trace levels. PerkinElmer sustains its position in near-infrared spectroscopy systems that dominate at-line quality control installations in dairy and grain processing facilities.
Analytical instrumentation for food applications encompasses chromatographs, spectrometers, and electrochemical devices engineered to detect contaminants, verify nutritional content, and authenticate product composition with detection thresholds reaching parts-per-billion precision. These systems serve industrial laboratories, regulatory enforcement bodies, and research institutions tasked with ensuring food safety compliance and supply chain integrity. Mass spectrometers command premium positioning due to their indispensable role in multi-residue pesticide screening and mycotoxin confirmation workflows. Chromatographs represent the most mature installed base, though liquid chromatography segments are gaining share as polar compound analysis expands beyond traditional gas chromatography domains. Spectrophotometers occupy a volume-driven tier where near-infrared technology is displacing slower wet-chemistry methods in grain and dairy receiving stations.
The FDA's Food Safety Modernization Act preventive controls framework and the EU's updated Contaminants Regulation are compelling food manufacturers to upgrade from spot-check sampling to continuous analytical verification protocols. China's SAMR national food safety standards and Japan's MHLW positive list system for agricultural chemicals are creating parallel compliance burdens for exporters serving multiple jurisdictions. Laboratories and manufacturers must decide whether to consolidate testing platforms around multi-technique workstations or maintain dedicated instruments aligned with specific regulatory filing requirements.
Market Dynamics
Regulatory convergence across export corridors is compressing testing protocol cycles and forcing instrument standardization decisions at multinational food manufacturers operating across multiple compliance jurisdictions.
Growth Catalysts
- EU Contaminants Regulation tightening:Germany's dairy processors are expanding quality assurance budgets for mycotoxin and heavy metal detection systems ahead of stricter maximum residue limits.
- Modular instrument configurations:Food testing laboratories in China's eastern seaboard cities are adopting reconfigurable platforms that pivot between pesticide screening and nutritional analysis workflows.
- Export certification harmonization:Demand concentrates where food producers must simultaneously satisfy FDA preventive controls, EU food safety standards, and Japan's positive list requirements.
Market Restraints
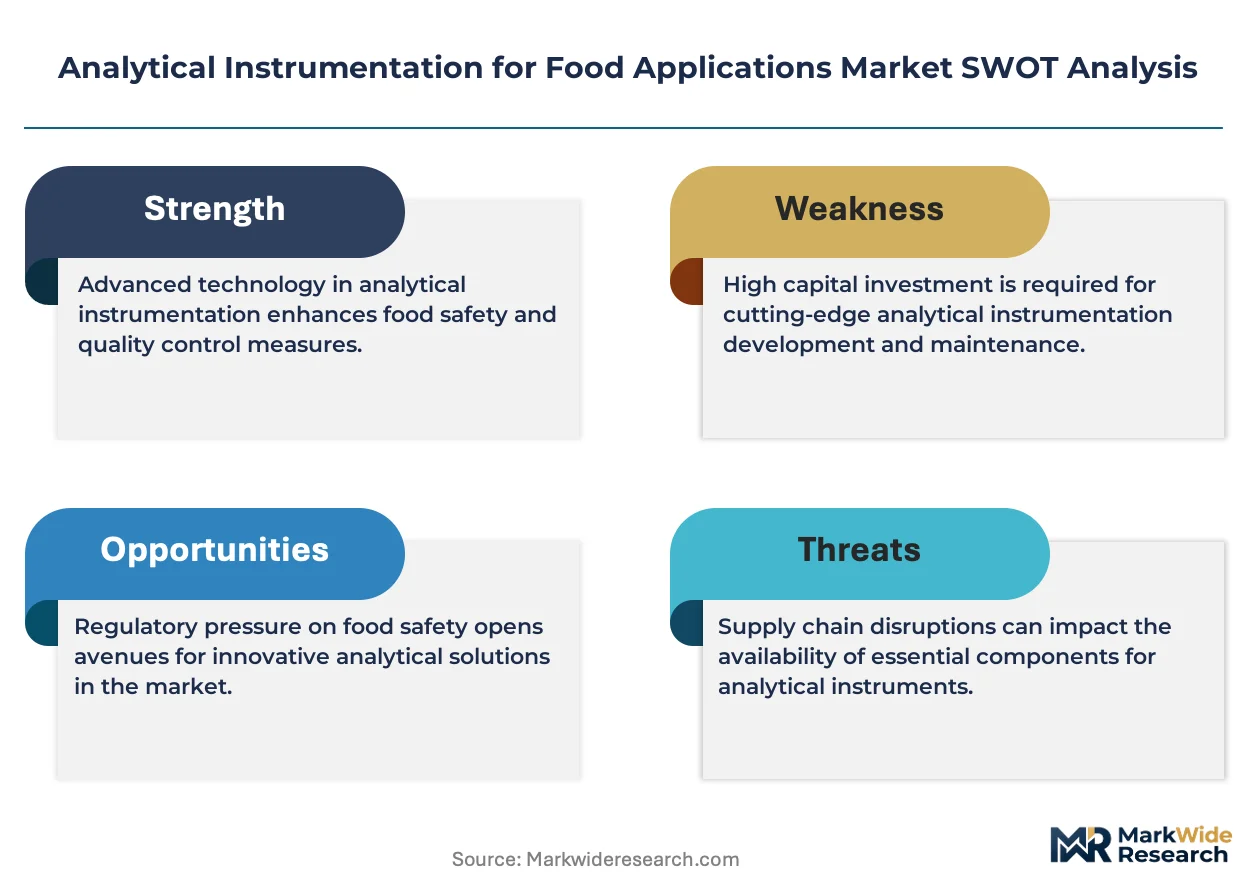
- Helium supply volatility:Gas chromatography operations face input cost pressure as helium shortages constrain carrier gas availability for high-throughput pesticide screening.
- Reference material scarcity:Certified standards for emerging contaminants lack commercial availability, delaying method validation for laboratories pursuing multi-residue expansion.
- Capital intensity threshold:Mass spectrometry platforms require facility investments that exclude mid-tier contract testing laboratories from mycotoxin confirmation workflows.
Strategic Opportunities
- At-line spectroscopy penetration:Near-infrared systems are displacing wet-chemistry methods in grain receiving stations and dairy processing facilities where speed trumps laboratory precision.
- Cloud-connected instrument networks:Remote diagnostics and predictive maintenance capabilities are opening service revenue streams for installed chromatography and spectrometry bases.
- Cell-based protein testing protocols:Novel food categories require adapted analytical methods for amino acid profiling and allergen verification beyond traditional livestock matrices.
Industry Challenges
- Mass spectrometry operator scarcity:Specialized skill requirements for method development and data interpretation constrain laboratory expansion timelines.
- Legacy chromatography integration:Gas chromatography installations face workflow friction when laboratories attempt hybrid liquid-gas screening protocols for polar compound analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analytical Instrumentation for Food Applications Market |
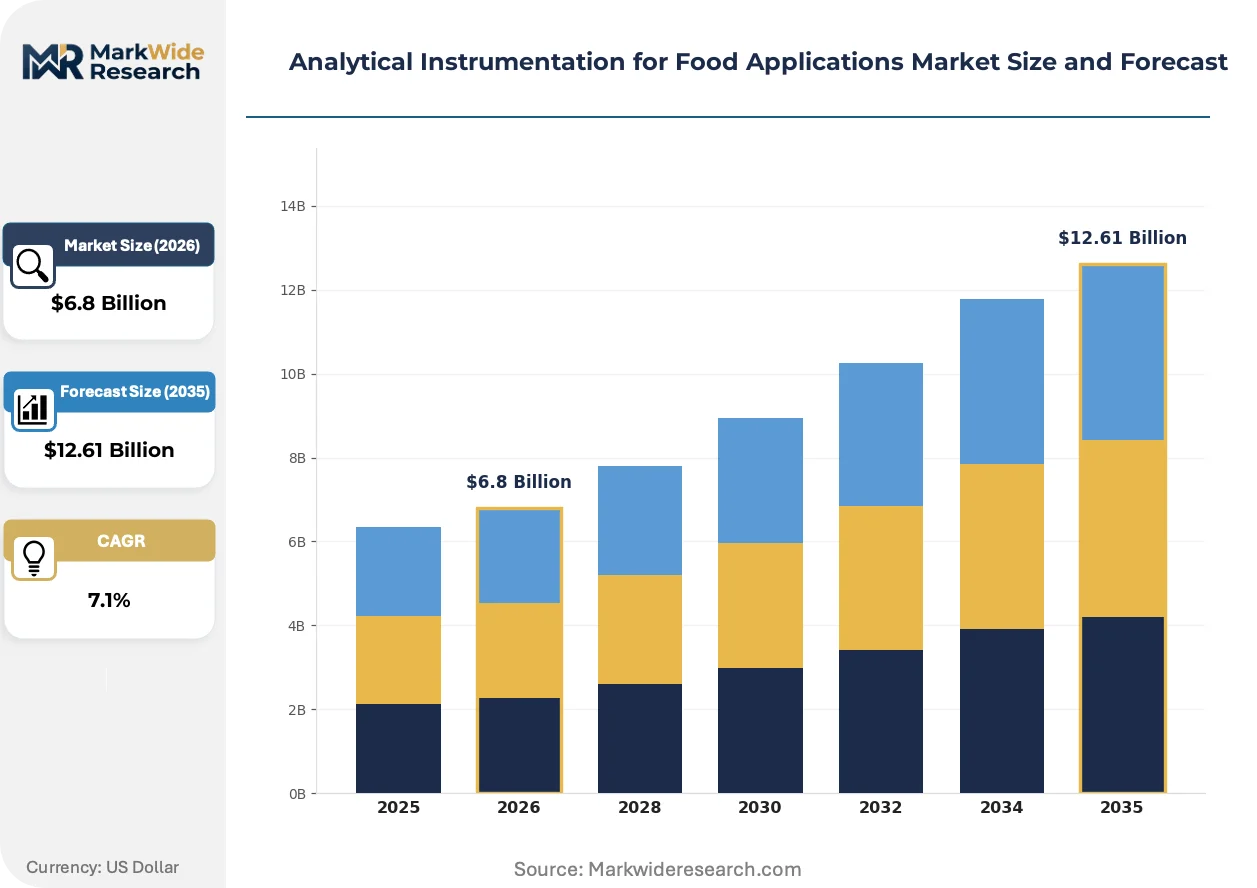
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.61 Billion |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mass Spectrometers, Chromatographs, Spectrophotometers, pH Meters Application: Quality Control, Nutritional Analysis, Contaminant Detection, Flavor Profiling End User: Food Manufacturers, Research Institutions, Quality Assurance Labs, Regulatory Bodies Technology: Gas Chromatography, Liquid Chromatography, Near-Infrared Spectroscopy, Nuclear Magnetic Resonance |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, PerkinElmer, Mettler Toledo, Waters Corporation, Shimadzu Corporation, Bruker Corporation, Horiba, FOSS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analytical Instrumentation for Food Applications Market Trends and Innovations
Portable and miniaturized detection platforms are redistributing analytical capacity from central laboratories to production floors and field inspection points, compressing decision cycles for food safety verification.
Handheld Raman spectrometers equipped with spectral libraries for adulterant detection are decentralizing authentication workflows from centralized quality control laboratories to receiving docks and border inspection stations. Grain elevators and dairy cooperatives in export-intensive regions are deploying these units for rapid incoming material screening. The technology is decentralizing geographic concentration of testing expertise and reducing sample transit dependency for time-sensitive perishables.
China's SAMR national food safety standards are mandating expanded multi-residue screening scopes for imported agricultural commodities, compelling exporters to upgrade from single-analyte methods to comprehensive pesticide panels. Food manufacturers serving Chinese markets must validate liquid chromatography-tandem mass spectrometry workflows covering hundreds of active ingredients. The regulation is accelerating instrument procurement cycles for contract testing laboratories in major export economies.
Service unbundling is separating hardware ownership from method development and regulatory compliance support, with instrument vendors offering subscription-based access to updated spectral libraries and validated protocols. Multinational food manufacturers are shifting from capital purchase models to operational expenditure structures that transfer obsolescence risk. This restructuring is most pronounced in North American and European markets where laboratory outsourcing trends concentrate analytical demand at fewer, larger service providers.
Analytical Instrumentation for Food Applications Market Segmentation
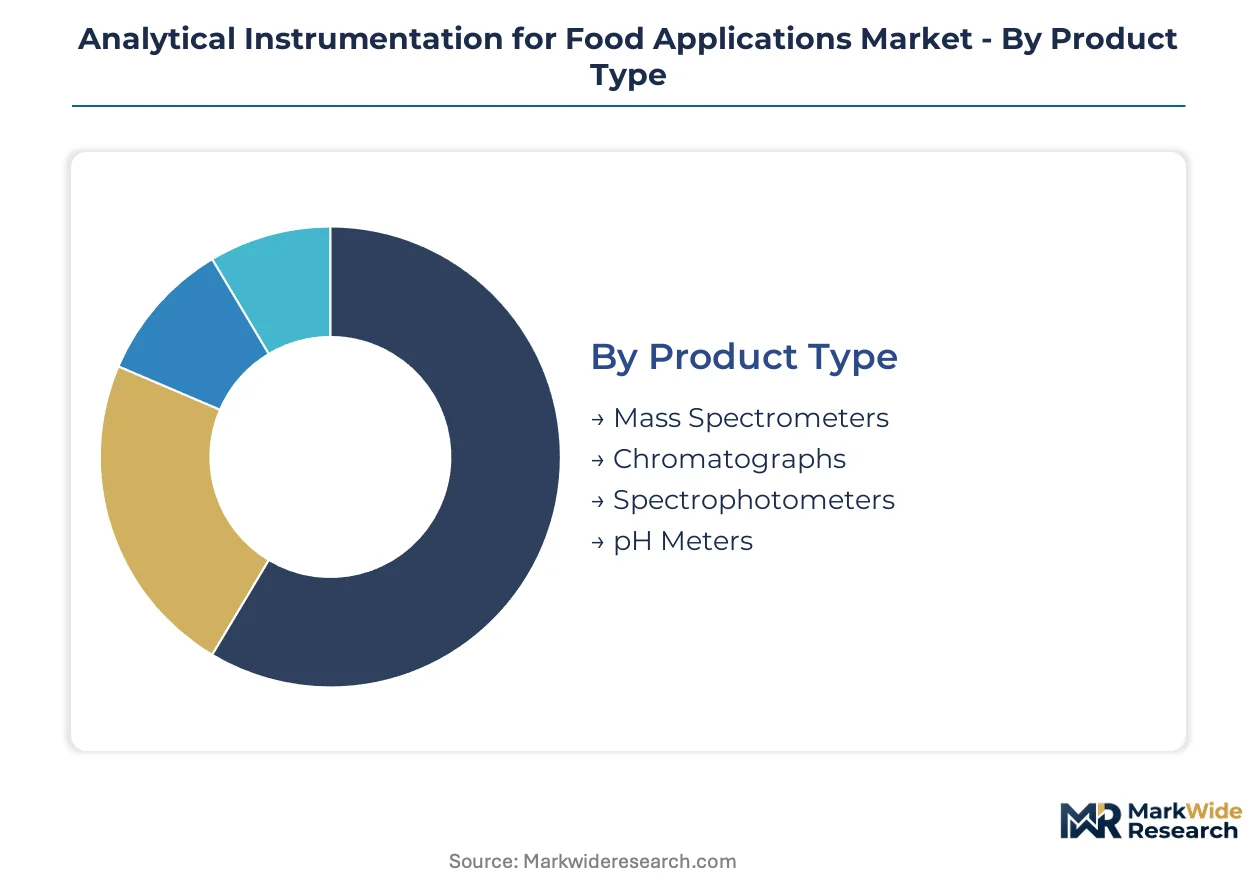
Segmentation in analytical instrumentation for food applications reveals distinct procurement patterns across technology tiers and end-use environments. Buyers prioritize detection thresholds, throughput capacity, and regulatory compliance scope when selecting platforms for specific workflows.
Product Type:
Supply concentration in high-precision detection technologies creates tiered procurement dynamics across laboratory and production environments.
- Mass Spectrometers:These platforms achieve parts-per-billion detection thresholds through ionization and mass-to-charge ratio analysis. Demand concentrates at contract testing laboratories in Germany and the Netherlands serving EU export certification requirements for multi-residue pesticide panels.
- Chromatographs:Separation systems utilizing stationary and mobile phases to isolate food matrix components. Food manufacturers in China's eastern seaboard cities are expanding liquid chromatography installations ahead of SAMR-mandated expanded screening scopes for imported agricultural commodities.
- Spectrophotometers:Optical absorption systems for quantitative concentration measurements.
- pH Meters:Electrochemical devices for acidity verification in dairy and beverage processing lines.
Today's leader: Mass Spectrometers. Tomorrow's challenger: Chromatographs.
Application:
Cost tier differentiation separates preventive control investments from reactive testing expenditures across food safety budgets.
- Contaminant Detection:Workflows targeting mycotoxins, heavy metals, pesticide residues, and adulterants with regulatory-driven validation requirements. Dairy processors across Bavaria and Lower Saxony are expanding quality assurance budgets for mycotoxin and heavy metal detection systems ahead of stricter EU maximum residue limits.
- Quality Control:At-line and in-process verification of physical, chemical, and sensory attributes. Grain elevators in export-intensive regions are deploying near-infrared spectroscopy for rapid incoming material screening where speed supersedes laboratory precision.
- Nutritional Analysis:Macronutrient and micronutrient quantification for label compliance.
- Flavor Profiling:Volatile compound characterization for product development and consistency monitoring.
Regulatory pressure elevates Contaminant Detection budgets fastest, while Quality Control commands the largest installed base.
End User:
Customer type determines capital intensity tolerance and service contract preferences across the procurement landscape.
- Food Manufacturers:Industrial laboratories integrated into production facilities with at-line and near-line testing requirements. Multinational manufacturers operating across FDA, EU, and Japan jurisdictions face compressed testing protocol cycles forcing instrument standardization decisions.
- Quality Assurance Labs:Independent and captive facilities serving third-party certification and supplier verification. Contract testing laboratories in major export economies are accelerating instrument procurement cycles to validate liquid chromatography-tandem mass spectrometry workflows.
- Research Institutions:Academic and government laboratories developing novel methodologies for emerging contaminants.
- Regulatory Bodies:Enforcement laboratories conducting surveillance sampling and confirmatory analysis.
Food Manufacturers drive volume demand. Quality Assurance Labs capture margin expansion through service unbundling.
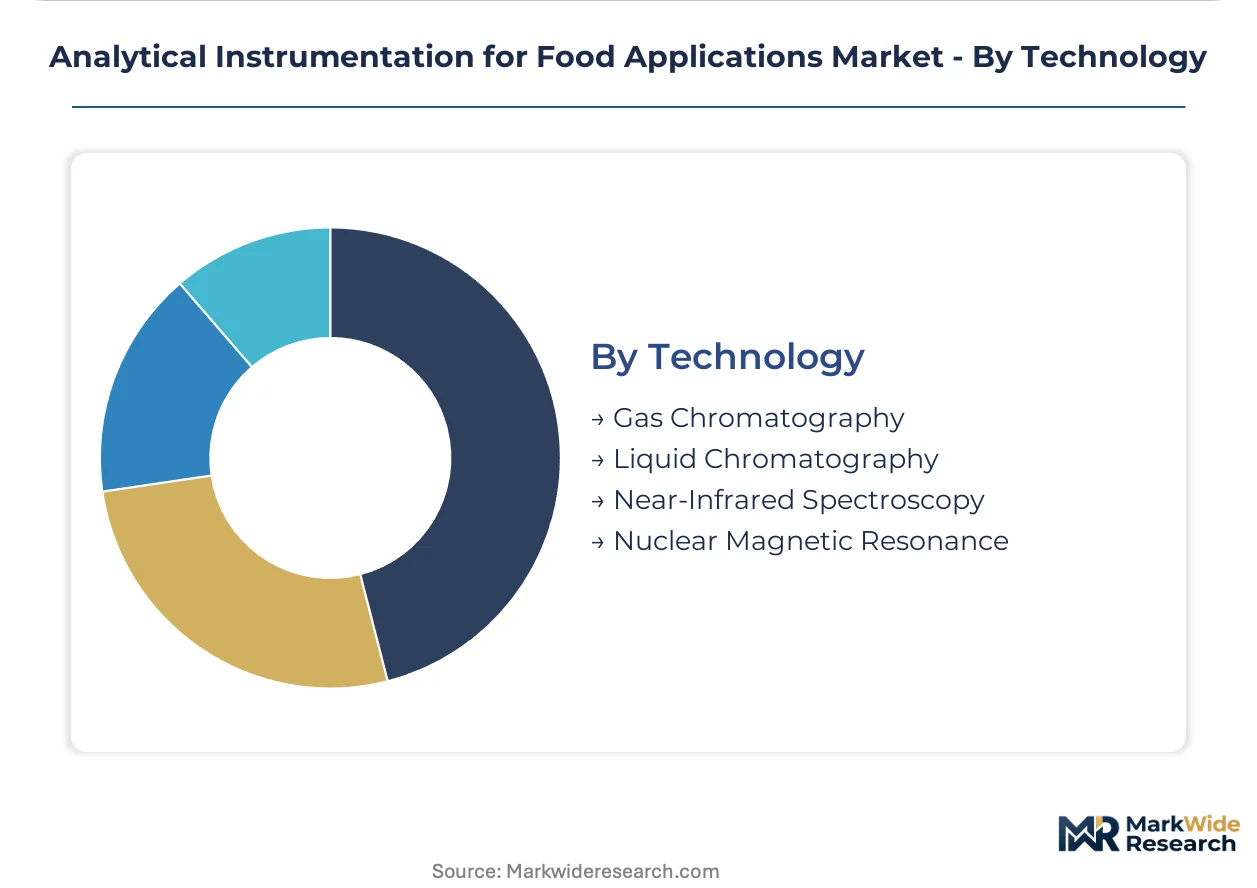
Technology:
Maturity curves separate established gas-phase methods from expanding liquid and spectroscopic domains.
- Liquid Chromatography:Polar compound separation systems gaining share as analysis expands beyond traditional gas chromatography domains. Laboratories pursuing multi-residue expansion require liquid chromatography-tandem mass spectrometry for comprehensive pesticide panels covering hundreds of active ingredients.
- Near-Infrared Spectroscopy:Non-destructive optical analysis systems displacing wet-chemistry methods in grain receiving stations and dairy processing facilities. Dairy cooperatives and grain elevators are deploying these units for rapid incoming material screening.
- Gas Chromatography:Volatile and semi-volatile compound separation facing helium supply volatility constraints.
- Nuclear Magnetic Resonance:Structural elucidation platforms for authentication and novel food matrix characterization.
Liquid Chromatography is climbing the fastest as polar compound analysis expands. Near-Infrared Spectroscopy holds the steepest penetration trajectory in at-line installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered industrial-scale food analytical instrumentation during the 1970s, establishing chromatography manufacturing clusters that supplied quality control laboratories across Western Europe. Japanese precision engineering subsequently elevated mass spectrometry detection thresholds during the 1980s. Chinese coastal manufacturing zones now drive procurement volume as export certification requirements converge with EU and US standards.
Germany
Dairy processors in Bavaria and Lower Saxony are expanding quality assurance budgets for mycotoxin and heavy metal detection systems. The EU's updated Food Contaminant Regulation tightens maximum residue limits ahead of implementation deadlines. Instrument procurement concentrates in Stuttgart and Munich, where contract testing laboratories validate multi-residue pesticide panels for export certification.
United States
Multinational food manufacturers operating across FDA jurisdictions face compressed testing protocol cycles forcing instrument standardization decisions. The FDA's Food Safety Modernization Act preventive controls framework compels upgrades from spot-check sampling to continuous analytical verification. Chicago and Minneapolis industrial corridors host captive laboratories deploying near-infrared spectroscopy for at-line quality control in grain processing facilities.
China
Food testing laboratories in Shanghai and Guangzhou are adopting modular instrument configurations that pivot between pesticide screening and nutritional analysis workflows. SAMR national food safety standards mandate expanded multi-residue screening scopes for imported agricultural commodities. Procurement accelerates in the Yangtze River Delta as exporters validate liquid chromatography-tandem mass spectrometry covering hundreds of active ingredients.
Japan
Food manufacturers serving domestic markets must satisfy MHLW positive list requirements for agricultural chemicals alongside export jurisdiction standards. METI industrial policy supports precision instrument manufacturing clusters in Kyoto and Osaka. Regional laboratories concentrate in Kanto and Kansai metropolitan areas where contract testing demand exceeds specialized operator availability.
Netherlands
Rotterdam and Amsterdam harbor logistics hubs drive demand for rapid incoming material screening at grain elevators and dairy cooperatives. EFSA regulatory guidance influences instrument selection across EU export corridors. The Randstad region hosts independent quality assurance laboratories accelerating procurement of cloud-connected chromatography networks for predictive maintenance revenue streams.
Analytical Instrumentation for Food Applications Market Competitive Landscape
Premium-margin players sit above commodity-margin players across detection threshold specialization and regulatory validation depth. The vendor base stratifies between full-platform conglomerates anchoring multinational food manufacturer accounts and specialized boutiques capturing niche contaminant workflows. Three archetypes dominate: chromatography portfolio consolidators, mass spectrometry precision specialists, and spectroscopy volume suppliers. Competitive moves concentrate on service unbundling to operational expenditure models and cloud-connected instrument networks for recurring revenue capture.
Among precision instrumentation conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify the platform consolidation archetype through chromatography and mass spectrometry anchoring. PerkinElmer occupies a distinct position in near-infrared spectroscopy systems for at-line installations. Shimadzu Corporation represents Japanese precision engineering heritage in analytical workflows. These three entities illustrate how geographic origin and historical capability clusters shape competitive positioning across regulatory jurisdiction requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| PerkinElmer |
| Mettler Toledo |
| Waters Corporation |
| Shimadzu Corporation |
| Bruker Corporation |
| Horiba |
| FOSS |
| Others |
Pricing and Supply Chain Analysis
Multinational food manufacturers operating across FDA, EU, and Japan jurisdictions concentrate procurement power and enforce subscription-based service models that transfer obsolescence risk from capital expenditure to operational expenditure structures. This buyer concentration compresses pricing leverage for instrument vendors while elevating compliance bundling as the dominant value anchor.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by detection threshold capability and regulatory validation depth. Mass spectrometry platforms command premium positioning through FDA and EU multi-residue certification tiers, while near-infrared spectrophotometers compete on volume scale in grain receiving stations. Price erosion runs through gas chromatography segments as helium supply constraints elevate operating costs and compress capital budgets. Contract testing laboratories exhibit highest price sensitivity due to capital intensity thresholds, whereas captive laboratories at dairy processors show lowest sensitivity where speed-to-certification dominates procurement criteria.
Supply Chain Analysis
Freight costs for precision optical components and vacuum systems elevate landed costs for mass spectrometry platforms manufactured in Germany, Japan, and the United States. Ion source assemblies and detector arrays draw from specialized semiconductor fabrication clusters in Taiwan and South Korea. Single-source vulnerability concentrates in helium carrier gas supply chains where Qatar and Algeria production disruptions cascade into gas chromatography operating cost inflation. Distribution runs through authorized service networks that bundle installation validation with regulatory compliance support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory compliance burdens where the EU's updated Food Contaminant Regulation tightening maximum residue limits creates sustained instrument refresh cycles across export-oriented food manufacturers.
For Market Incumbents: Lock in cloud-connected instrument networks to capture predictive maintenance revenue streams from installed chromatography and spectrometry bases. Deepen backward integration into ion source manufacturing to mitigate Taiwan semiconductor supply exposure. Defend against modular platform entrants by anchoring multinational accounts with integrated regulatory filing support that smaller competitors cannot replicate at scale. For New Entrants and Emerging Players: SAMR national food safety standards in China open a window for portable Raman spectrometers at grain elevators and dairy cooperatives where rapid incoming material screening commands premium positioning. Target contract testing laboratories in the Yangtze River Delta with handheld platforms that bypass capital intensity thresholds blocking mass spectrometry adoption. Lead with spectral library subscription models that align with operational expenditure preferences spreading through North American and European markets. For Investors and Strategic Acquirers: Precision instrument conglomerates are the most active acquirer in this space, consolidating specialized boutiques that capture niche contaminant workflows. Five-to-ten year viability hinges on service revenue attachment rates exceeding hardware margins. Watch for inflection when cloud-connected instrument penetration crosses critical mass in contract testing laboratory networks, signaling recurring revenue model maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Service Unbundling to Subscription Models | Transfers obsolescence risk from food manufacturers to vendors while locking in recurring revenue streams. |
| Cloud-Connected Instrument Networks | Enables predictive maintenance capabilities that open service revenue from installed chromatography bases. |
| Portable Raman Platform Development | Decentralizes authentication workflows from centralized laboratories to grain receiving docks and border stations. |
| Liquid Chromatography-Tandem Mass Spectrometry Expansion | Validates comprehensive pesticide panels covering hundreds of active ingredients for SAMR compliance. |
| Helium-Free Carrier Gas Alternatives | Mitigates supply volatility constraints compressing gas chromatography operating margins. |
Research Methodology
Multiple input streams — regulatory filing databases, instrument procurement records, and trade flow documentation — were reconciled against primary interviews with food safety laboratory directors, quality assurance executives at dairy processors, chromatography service engineers, and regulatory affairs specialists at export certification bodies. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EFSA scientific opinions, SAMR national standards publications, and customs data on analytical instrument trade flows. Bottom-up procurement modeling and top-down market sizing triangulated volume estimates across the analysis window.
Data-stream reconciliation anchored the forecast framework across product type, application workflow, end-user category, and technology platform dimensions. CAGRs were derived from instrument replacement cycle analysis and regulatory mandate implementation timelines. Helium supply elasticity coefficients and multi-residue screening scope expansion rates informed scenario-weighted projections throughout the forecast period.
Revisions become necessary when helium supply disruptions intensify, SAMR accelerates screening scope mandates, or portable platform detection thresholds achieve laboratory-grade precision. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Scientific Instruments Market
Analytical Instruments
Global Handheld LCR Meters Market
Analytical Instruments
Laser-Induced Breakdown Spectroscopy Market
Analytical Instruments
Metal Analyzers Market
Analytical Instruments
Thermoluminescent Dosimeter (TLD) System Market
Analytical Instruments
Infrared Thermometers Market
Analytical Instruments
Microfluidics Market
Analytical Instruments
Energy Dispersive X-Ray Spectrometer Market
Analytical Instruments
Global Raman Spectroscopy Market
Analytical Instruments
Portable Gas Analyzer Market
Analytical Instruments
Simultaneous-Functionality Analyzers Market
Analytical Instruments
Middle East and Africa Dissolved Gas Analyzer Market
Analytical Instruments
Spectrum Analyzer Market
Analytical Instruments
Life Science and Analytical Instruments Market
Analytical Instruments
Global Particle Size Analyzer Market
Analytical Instruments
Dioxin Analyzer Market