
 Construction Lubricants Market | 2026-2036
Construction Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Lubricants Market Intelligence
The EU Green Deal's focus on circular economy principles is expanding the market for higher-performance and longer-lasting construction lubricants. Shell plc leverages its global distribution network to supply diverse construction projects from urban redevelopment to remote infrastructure. TotalEnergies SE specializes in developing advanced synthetic and bio-based lubricant formulations. FUCHS Petrolub SE competes on its strong R&D focus for application-specific industrial fluids that meet new OEM specifications.
Construction lubricants are specialized formulations engineered to reduce friction, wear, and corrosion in heavy machinery. These products are defined by their viscosity index, load-carrying capacity, and specific additive packages for anti-wear and extreme pressure performance. Bio-based lubricants, a key technology segment, are seeing accelerated adoption due to new environmental standards. Hydraulic fluids and engine oils remain the dominant product types, critical for the operation of excavators and dump trucks.
Regulatory frameworks from the US EPA, Europe's ECHA under REACH, and China's MEE through GB standards dictate product composition. These agencies set stringent limits on chemical substances and promote the use of environmentally acceptable lubricants. The primary challenge for formulators is balancing equipment protection requirements with increasingly strict environmental compliance mandates across different jurisdictions.
Market Dynamics
The market's structure is defined by the tension between heavy machinery performance requirements and tightening environmental regulations. This dynamic forces lubricant formulators to innovate while navigating disparate rules from Europe's ECHA and China's Ministry of Ecology and Environment (MEE).
Growth Catalysts
- EU Green Deal Implementation:Circular economy principles promote lubricants with extended drain intervals, directly benefiting sales of high-performance synthetic and semi-synthetic products.
- Bio-Based Lubricant Viability:Formulations with improved thermal stability and load-carrying capacity are gaining traction among fleet operators adhering to new environmental standards.
- Infrastructure Investment in China:State-led spending on public works and urban development creates sustained demand for hydraulic fluids and engine oils in heavy equipment.
Market Restraints
- Base Oil Price Volatility:Fluctuations in the cost of Group II and III base oils create margin pressure for formulators and price instability for end-users.
- Divergent Regulatory Frameworks:Conflicting substance limits between Europe's REACH and China's GB standards increase compliance costs and complexity for global manufacturers.
- Bio-Lubricant Performance Gaps:Some bio-based fluids show lower oxidative stability than mineral oils, limiting their use in high-temperature, long-drain applications.
Strategic Opportunities
- Southeast Asian Infrastructure Growth:Nations like Indonesia and Vietnam are launching large-scale projects, opening new markets for specialized lubricants beyond the current focus on China.
- Electric Construction Equipment Fluids:The electrification of compact excavators and loaders creates a new segment for specialized dielectric fluids, coolants, and greases.
- Digital Fleet Service Models:Online platforms for direct sales and predictive maintenance services bypass traditional distributors to reach large equipment fleet operators.
Industry Challenges
- Formulation Balancing Act:Chemists face the technical challenge of developing lubricants that meet new OEM specifications for wear protection while also complying with stricter environmental substance bans from agencies like the EPA and ECHA.
- Supply Chain Resilience:Securing a stable supply of critical additives and high-quality base oils is a constant operational challenge, complicated by geopolitical instability and shifting trade policies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Lubricants Market |
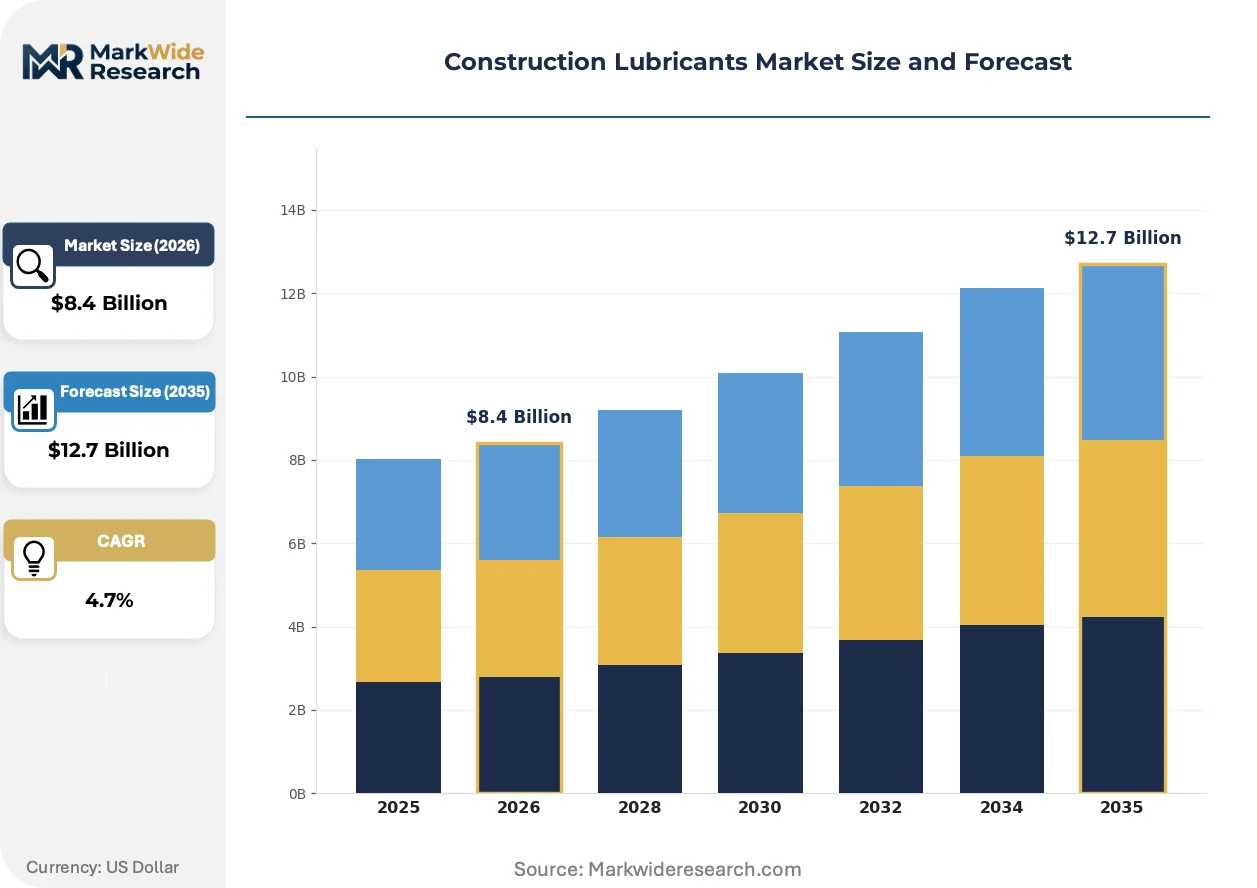
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.7 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oils, Hydraulic Fluids, Gear Oils, Greases, Compressor Oils, Chain Oils Technology: Synthetic, Mineral, Semi-Synthetic, Bio-Based, Nano-Lubricants, Ester-Based Application: Excavators, Cranes, Concrete Mixers, Bulldozers, Dump Trucks, Pavers End User: General Contractors, Heavy Equipment Operators, Rental Companies, Road Builders, Civil Engineers |
| Companies Covered | Shell plc, ExxonMobil Corporation, BP p.l.c., Chevron Corporation, TotalEnergies SE, FUCHS Petrolub SE, Sinopec Corp., PetroChina Company Limited, Indian Oil Corporation Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Lubricants Market Strategic Shifts & Innovations
Market evolution is moving beyond simple friction reduction towards integrated solutions that combine material science with digital monitoring. This shift emphasizes total cost of ownership and asset longevity, driven by both economic and regulatory pressures.
Smart lubricants, incorporating microscopic tracers or sensors, provide real-time data on fluid condition and equipment health. Heavy equipment fleet managers and large-scale mining operations are early adopters, seeking to optimize maintenance schedules. This technology is unifying the previously separate domains of fluid analysis and predictive maintenance into a single, data-driven workflow for asset management.
Europe's ECHA continues to expand its list of restricted substances under the REACH regulation. This action compels formulators to phase out specific anti-wear additives and corrosion inhibitors, accelerating R&D into safer alternatives. Hydraulic fluid and gear oil segments are most affected, with producers reformulating entire product lines to maintain market access in the EU.
Large construction contractors are shifting from transactional product purchases to comprehensive fluid management service contracts. This model displaces traditional distributors, as lubricant suppliers now provide on-site fluid analysis, inventory management, and waste oil disposal. This trend is most visible in North America and Europe among large civil engineering firms managing extensive, multi-site equipment fleets.
Construction Lubricants Market Segmentation
The Construction Lubricants Market requires precise segmentation to understand the diverse needs of heavy machinery and operational environments. Different equipment types, technological advancements, and regulatory pressures drive distinct product and application demands. This detailed breakdown clarifies where specialized formulations and service models are most impactful.
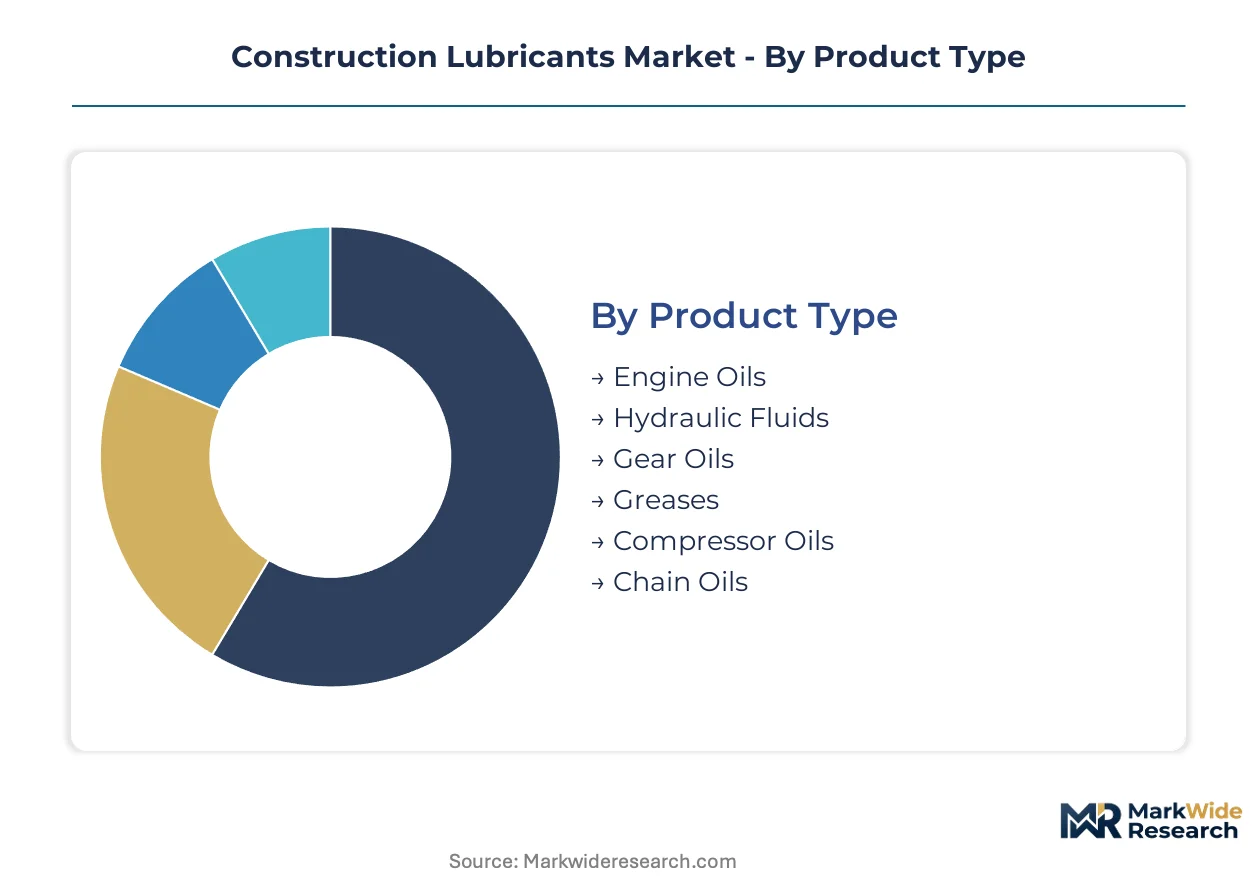
Product Type:
The product type segmentation highlights the balance between highly specialized lubricants for critical components and standardized formulations for general applications.
- Engine Oils:Engine oils protect internal combustion engines, formulated with anti-wear and detergent additives to manage heat and reduce friction. Heavy equipment operators globally prioritize these oils to extend machinery life and minimize maintenance downtime.
- Hydraulic Fluids:Hydraulic fluids transmit power and lubricate systems, featuring high viscosity indexes and extreme pressure capabilities for heavy lifting. Demand concentrates in China's public infrastructure projects, where excavators and dump trucks require reliable fluid performance.
- Gear Oils:Gear oils lubricate transmissions and differentials, providing high load-carrying capacity for heavy-duty construction vehicles.
- Greases:Greases offer long-lasting lubrication for bearings and chassis points, resisting water washout in harsh environments.
- Compressor Oils:Compressor oils ensure efficient operation of air compressors, maintaining viscosity stability under varying temperatures.
- Chain Oils:Chain oils provide adhesion and anti-wear protection for drive chains on specialized construction equipment.
Leading the category by volume: Hydraulic Fluids. Growing fastest: Engine Oils.
Technology:
Technology segmentation reflects the diverse performance requirements and environmental mandates influencing lubricant formulation strategies.
- Synthetic:Synthetic lubricants are chemically synthesized for superior thermal stability and oxidative resistance, offering extended drain intervals. Heavy machinery operators in North America use these products to optimize maintenance schedules and reduce total cost of ownership.
- Mineral:Mineral lubricants, derived from crude oil, offer cost-effective protection for standard construction equipment.
- Semi-Synthetic:Semi-synthetic lubricants blend mineral and synthetic base oils, balancing performance and cost for various applications.
- Bio-Based:Bio-based lubricants derive from renewable resources, offering biodegradability and reduced environmental impact, meeting specific performance criteria. European ECHA regulations drive accelerated adoption among construction fleets aiming for stricter environmental compliance.
- Nano-Lubricants:Nano-lubricants incorporate nanoparticles to enhance anti-wear properties and reduce friction in critical components.
- Ester-Based:Ester-based lubricants provide excellent high-temperature stability and solvency, often used in specialized synthetic formulations.
The segment Mineral dominates, while Bio-Based exhibits the steepest expansion trajectory.
Application:
Application segmentation details the specific machinery types where construction lubricants are deployed, each with unique operational demands.
- Excavators:Excavators rely on robust hydraulic fluids and engine oils for powerful digging and lifting under extreme loads. Large-scale infrastructure projects in Southeast Asia drive demand for lubricants protecting these versatile machines.
- Cranes:Cranes demand specialized greases and hydraulic fluids for precision lifting and stable operation at height.
- Concrete Mixers:Concrete mixers need durable gear oils and greases to withstand abrasive materials and continuous rotation.
- Bulldozers:Bulldozers utilize heavy-duty engine oils and track greases for earthmoving and site preparation activities.
- Dump Trucks:Dump trucks require high-performance engine oils and gear oils for heavy hauling and continuous operation across diverse terrains. Their use in mining and road construction in Australia creates consistent demand for durable lubricants.
- Pavers:Pavers require high-temperature resistant hydraulic fluids and engine oils for road surfacing applications.
Demand is highest from Excavators, with Dump Trucks showing significant expansion.
End User:
End-user segmentation clarifies the different procurement behaviors and service expectations across the construction industry value chain.
- General Contractors:General contractors oversee diverse construction projects, demanding versatile lubricants suitable for varied equipment and operational scales. Urban redevelopment initiatives in Germany create a consistent need for reliable lubricant supply across job sites.
- Heavy Equipment Operators:Heavy equipment operators manage extensive machinery fleets, prioritizing lubricants offering extended drain intervals and lower total cost of ownership. Large civil engineering firms in North America adopt advanced fluid management services to optimize asset longevity.
- Rental Companies:Rental companies require robust, standardized lubricants to ensure equipment reliability across multiple users and sites.
- Road Builders:Road builders use specialized lubricants for asphalt pavers and rollers, focusing on high-temperature stability and durability.
- Civil Engineers:Civil engineers influence lubricant specifications for large-scale infrastructure, focusing on performance and environmental compliance.
The largest purchasing volumes originate from Heavy Equipment Operators, while Rental Companies are rapidly increasing their procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global construction lubricants market exhibits a distinct consumption pattern, driven by varying infrastructure development paces and regulatory landscapes. While production capabilities are globally distributed, demand concentration shifts significantly across key regions. Major construction activity in Asia and North America dictates primary consumption trends.
China
China's immense public infrastructure investments and new urban construction projects generate substantial demand for construction lubricants. The Ministry of Ecology and Environment (MEE) through its GB standards dictates product composition and environmental compliance. Major construction hubs in the Yangtze River Delta and Pearl River Delta drive high consumption of hydraulic fluids and engine oils.
United States
United States heavy equipment operators prioritize lubricants extending machinery life and reducing maintenance downtime. The US Environmental Protection Agency (EPA) sets strict limits on chemical substances in lubricants, promoting environmentally acceptable solutions. Large civil engineering firms in major metropolitan areas utilize advanced fluid management services to optimize asset longevity.
Germany
Germany's urban redevelopment initiatives consistently need reliable lubricant supplies for diverse construction projects. The EU Green Deal and ECHA's REACH regulations expand the market for higher-performance, longer-lasting construction lubricants. Bavarian and North Rhine-Westphalian construction sectors adopt advanced bio-based formulations for stricter environmental compliance.
Australia
Australia's extensive mining operations and road construction projects create consistent demand for durable lubricants in dump trucks. National environmental standards increasingly influence lubricant specifications, pushing for more sustainable options. Western Australia and Queensland's mining regions require high-performance engine oils and gear oils for continuous heavy equipment operation.
Indonesia
Indonesia's large-scale infrastructure projects, including new roads and urban development, drive significant demand for specialized construction lubricants. Local environmental regulations are influencing the adoption of more compliant and efficient fluid solutions. Major construction sites around Jakarta and other growing urban centers heavily utilize robust hydraulic fluids and engine oils for excavators.
Construction Lubricants Market Key Industry Players
The competitive structure tilts toward integrated energy majors leveraging extensive global distribution networks. This market also includes specialized lubricant manufacturers focusing on advanced formulations and application-specific industrial fluids. Key strategic archetypes include global diversified players, niche innovators, and regional specialists. Dominant competitive moves involve portfolio diversification into bio-based solutions and strategic partnerships for technology development.
Within the global diversified player archetype, Shell plc, a UK-domiciled public limited company, represents extensive reach across diverse construction projects. TotalEnergies SE, a French-based European company, occupies a position focused on advanced synthetic and bio-based lubricant formulations. FUCHS Petrolub SE, a German-domiciled European company, anchors the market segment for application-specific industrial fluids, emphasizing strong research and development capabilities. These entities exemplify the varying approaches to market penetration and product specialization within the construction lubricants industry.
| Leading Market Players |
|---|
| Shell plc |
| ExxonMobil Corporation |
| BP p.l.c. |
| Chevron Corporation |
| TotalEnergies SE |
| FUCHS Petrolub SE |
| Sinopec Corp. |
| PetroChina Company Limited |
| Indian Oil Corporation Limited |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's focus on circular economy principles gates qualified lubricant supply and premium-tier pricing access for compliant products. This mandate compels formulators to invest in advanced R&D, influencing both production costs and market valuation for environmentally acceptable lubricants.
Pricing Analysis
Value-based pricing, tied to machinery uptime and extended drain intervals, defines the premium segment. Price differentiation stems from superior performance in extreme conditions and adherence to stringent environmental certifications like ECHA REACH. Pricing softness affects conventional mineral oils due to base oil price volatility, creating margin pressure for formulators. Heavy equipment operators, prioritizing total cost of ownership, exhibit lower price sensitivity for high-performance synthetic lubricants, while rental companies seek cost-effective, standardized options.
Supply Chain Analysis
Logistics and freight costs significantly influence the landed price of construction lubricants, particularly for specialized additives. The supply chain relies heavily on Group II and III base oils, primarily sourced from major refining hubs in Asia and the Middle East, alongside specialized anti-wear additives from global chemical producers. Geopolitical instability and shifting trade policies present a structural risk to base oil and additive availability. Distribution for premium products increasingly bypasses traditional channels, favoring direct sales and comprehensive fluid management service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECHA REACH regulation in Europe creates a significant cost-of-compliance story for the construction lubricants market, establishing a barrier-to-entry moat for compliant players.
For Market Incumbents: Anticipate continued regulatory tightening by investing proactively in bio-based and advanced synthetic formulations. Leverage extensive global distribution networks to maintain market share against niche innovators. Expand digital fleet management service offerings to capture higher-value contracts, mitigating margin pressure from base oil price volatility and increasing competition in standard product segments.
For New Entrants and Emerging Players: Europe's ECHA regulations open a window for specialized bio-based lubricant manufacturers. Target the rapidly expanding electric construction equipment segment with specialized dielectric fluids and greases. Focus on Southeast Asian infrastructure projects, offering advanced environmentally compliant lubricants with strong technical support. Digital platforms for direct sales and predictive maintenance services provide an effective go-to-market angle.
For Investors and Strategic Acquirers: Accelerated adoption of bio-based lubricants in Europe is the leading indicator that environmental compliance will drive future market value. Focus on acquiring niche innovators specializing in advanced bio-based formulations or digital fluid management technologies. Long-term viability, spanning the next decade, favors companies capable of balancing equipment protection with increasingly strict environmental mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Based R&D | Develop formulations meeting ECHA standards and reducing environmental impact. |
| Expand Digital Fleet Services | Optimize maintenance schedules and reduce total cost of ownership for operators. |
| Develop Electric Equipment Fluids | Address the emerging segment of battery-powered construction machinery. |
| Target Southeast Asian Markets | Capitalize on large-scale infrastructure investments in growing economies. |
| Secure Additive Supply Agreements | Mitigate supply chain risks from geopolitical instability and price volatility. |
Research Approach
Industry association publications, government regulatory documents from the US EPA, Europe's ECHA, and China's MEE, alongside academic research, formed the secondary backbone of this study. This was triangulated with primary interviews conducted with heavy equipment operators, construction contractors, lubricant formulators, and regulatory compliance officers. The analysis integrates both bottom-up market sizing and top-down validation.
A bottom-up analytical lens, informed by top-down validation, was applied to quantify market segments. This approach modeled market size across the analysis window by Product Type, Technology, Application, End User, and Regional Outlook. Compound annual growth rates were derived from historical trends and projected infrastructure investment pipelines and evolving environmental regulatory timelines.
The model assumes a particular technology adoption path; alternative pathways for electric construction equipment fluids would alter the outlook. Forecasts reflect assumptions concerning raw material availability and geopolitical stability. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Cutting Fluid Market
Lubricants
Mining Lubricants Market
Lubricants
Singapore Commercial Vehicles Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Norway Automotive Lubricants Market
Lubricants
Global Friction Modifiers Market
Lubricants
Polyurea-Based Greases Market
Lubricants
Forestry Lubricants Market
Lubricants
Italy Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
China Refrigeration Lubricants Market
Lubricants
Textile Machine Lubricants Market
Lubricants
Poland Lubricants Market
Lubricants
Perfluoropolyether Fluorinated Fluids Market