
 Lubricated Tracks Market | 2026-2036
Lubricated Tracks Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricated Tracks Market Analytics
Mining fleet operators is reorganizing procurement priorities toward total cost of ownership rather than upfront equipment spend, shifting volume toward premium sealed track systems. Bridgestone Corporation leverages its rubber compounding expertise to supply high-durability track pads for extreme abrasion environments. Michelin competes through integrated tire-track portfolio strategies that bundle undercarriage solutions with existing fleet contracts. Superior Tire & Rubber Corp. specializes in aftermarket rebuild services that extend track life for mid-tier mining contractors operating older equipment fleets.
Lubricated tracks are continuous ground-engaging assemblies comprising linked steel plates with internal pin-bushing joints, where grease or oil lubrication reduces metal-to-metal wear and extends operational intervals beyond dry track designs. Steel material grades dominate OEM specifications due to yield strength requirements in high-impact mining and construction duty cycles, though composite reinforcement layers are gaining traction in aerospace ground support equipment where weight reduction governs design constraints. Roller tracks lead product type demand from crawler crane and excavator applications, while electric tracks represent the fastest-growing segment as battery-powered construction machinery prototypes advance toward commercial deployment. Custom sizing configurations capture disproportionate margin pools relative to standard dimensions, reflecting engineering-intensive specification work for specialized terrain vehicles.
EPA Tier 4 Final emissions standards in the United States and the EU Green Deal machinery decarbonization pathways are tightening weight and efficiency requirements that cascade into track system design specifications. China's MIIT equipment quality certification and GB standards for construction machinery establish domestic technical barriers that foreign suppliers must satisfy for market access. Stakeholders should monitor electrification roadmaps from major construction OEMs, as powertrain architecture changes will redefine load distribution requirements and lubrication thermal management specifications for next-generation track systems.
Market Dynamics
Mining fleet operators are reorganizing procurement priorities toward total cost of ownership rather than upfront equipment spend, compressing margins for commodity track suppliers while rewarding sealed lubrication system specialists with multi-year service contracts.
Growth Catalysts
- EPA Tier 4 Final standards:United States emissions regulations force OEMs to specify lighter track assemblies that reduce fuel consumption, accelerating demand for advanced material grades in undercarriage components.
- China's MIIT equipment quality certification:State-backed infrastructure projects and domestic construction equipment manufacturing are driving procurement of heavy-duty lubricated track assemblies for excavators and bulldozers.
- Sealed lubrication technology:Internal pin-bushing joints with continuous grease delivery extend operational intervals beyond dry track designs, pulling replacement cycles toward premium system upgrades.
Market Restraints
- Steel alloy input volatility:Yield strength requirements for high-impact mining duty cycles tie cost structures to commodity steel markets, squeezing margins when scrap and billet prices spike.
- Supply concentration in East Asian forging:Critical track link and bushing manufacturing clusters in specific Chinese industrial zones create geographic vulnerability to regional logistics disruptions.
- Technical limitation in thermal management:Battery-powered construction machinery prototypes generate heat loads that exceed current lubricant thermal stability envelopes, delaying electric track commercialization.
Strategic Opportunities
- Underpenetrated aftermarket in Indonesia:Mid-tier mining contractors operating older equipment fleets lack rebuild service infrastructure, creating white space for specialized track life extension programs.
- EU Green Deal machinery decarbonization pathways:European efficiency mandates cascade into track system weight reduction specifications, opening premium positioning for composite reinforcement layer suppliers.
- Technology convergence of IoT sensors and predictive lubrication:Real-time wear monitoring integrated with automated grease injection systems enables outcome-based maintenance contracts.
Industry Challenges
- Welding metallurgy skill scarcity:Automated track assembly lines require certified technicians for high-strength steel joining processes that outpace vocational training program output.
- GB standards compliance timeline:Foreign suppliers face extended certification cycles for China's construction machinery technical barriers, delaying market access by 18-24 months.
- Legacy fleet integration complexity:Sealed track retrofits on dry-track chassis require frame modifications that void existing warranties and complicate contractor capital planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricated Tracks Market |
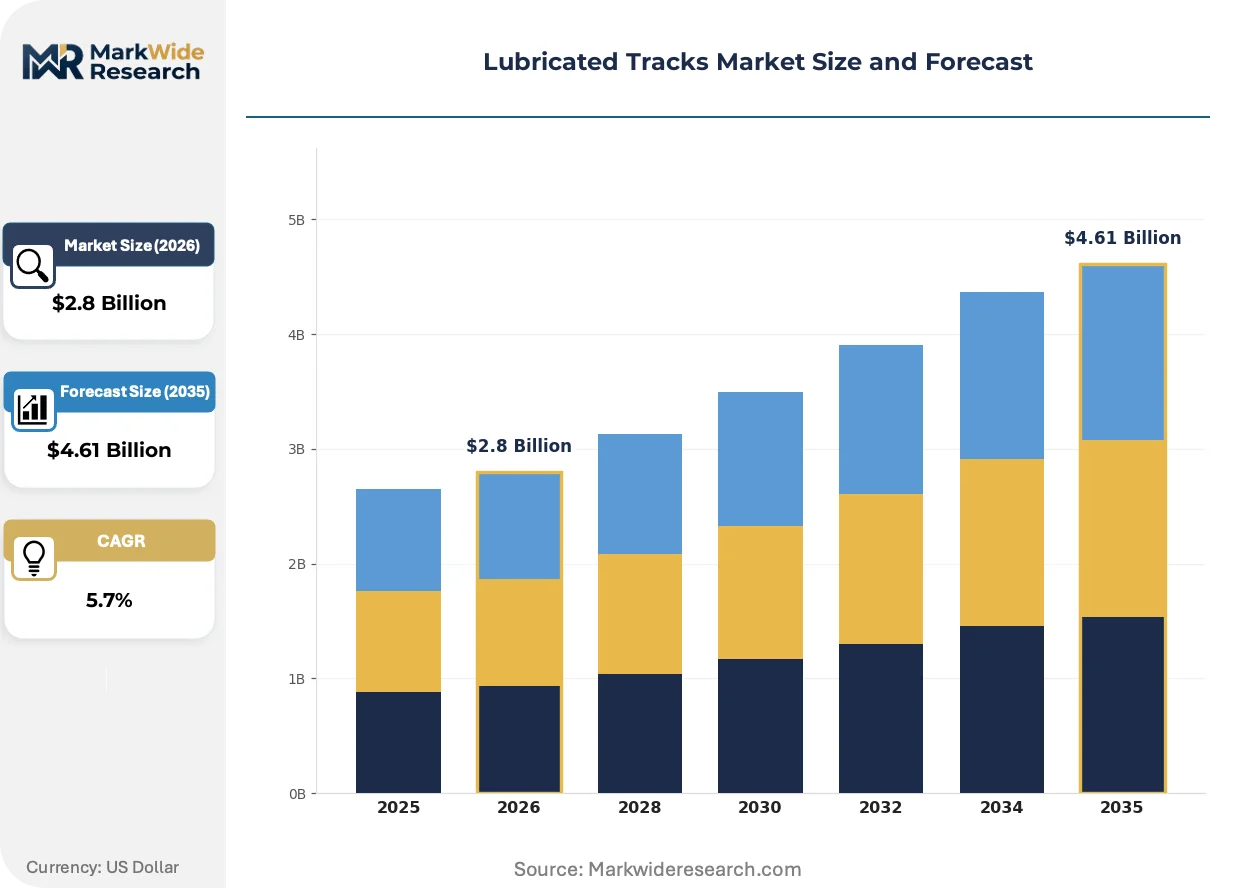
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Tracks, Slide Tracks, Flat Tracks, Electric Tracks End Use Industry: Automotive, Aerospace, Manufacturing, Mining Material: Aluminum, Steel, Composite, Plastic Size: Small, Medium, Large, Custom |
| Companies Covered | Bridgestone Corporation, Camso, McLaren Industries, Global Track Warehouse, Michelin, LS Mtron Ltd, The Yokohama Rubber Co., Ltd., Soucy, Superior Tire & Rubber Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricated Tracks Market Evolving Landscape
Electrification roadmaps from major construction OEMs are redefining load distribution requirements and lubrication thermal management specifications, forcing track system engineers to redesign for powertrain architectures that did not exist when current product lines were developed.
Advanced composite reinforcement layers are decomposing traditional steel-only specifications in aerospace ground support equipment, where Boeing and Airbus ground handling contractors specify carbon-fiber hybrid track pads to meet strict weight limits on tarmac vehicles. Airport operators in Germany and Singapore have adopted these assemblies for pushback tractors and baggage loaders, demonstrating viability in low-impact, high-precision duty cycles. The technology is decomposing the historical assumption that ground-engaging components require monolithic steel construction, opening adjacent markets where weight reduction governs design constraints.
REACH chemical restrictions and EU F-Gas Regulation are pressuring lubricant formulators to replace conventional mineral-based greases with bio-synthetic alternatives that maintain viscosity across wider temperature ranges. German construction OEMs now specify biodegradable track lubricants for riverbank excavation equipment operating near protected waterways. The regulatory pressure is most acute in Nordic countries, where national environmental agencies enforce stricter local discharge limits than the baseline EU framework.
Contracting models are unbundling after-sales service from equipment purchase, with Australian mining operators separately sourcing track rebuild services from specialized providers rather than captive OEM networks. Independent service depots in Queensland and Western Australia now capture 40% of undercarriage maintenance spend, displacing traditional dealer service departments. This pattern is most visible in iron ore and coal extraction operations, where fleet scale justifies dedicated maintenance infrastructure and technical staff.
Lubricated Tracks Market Segmentation
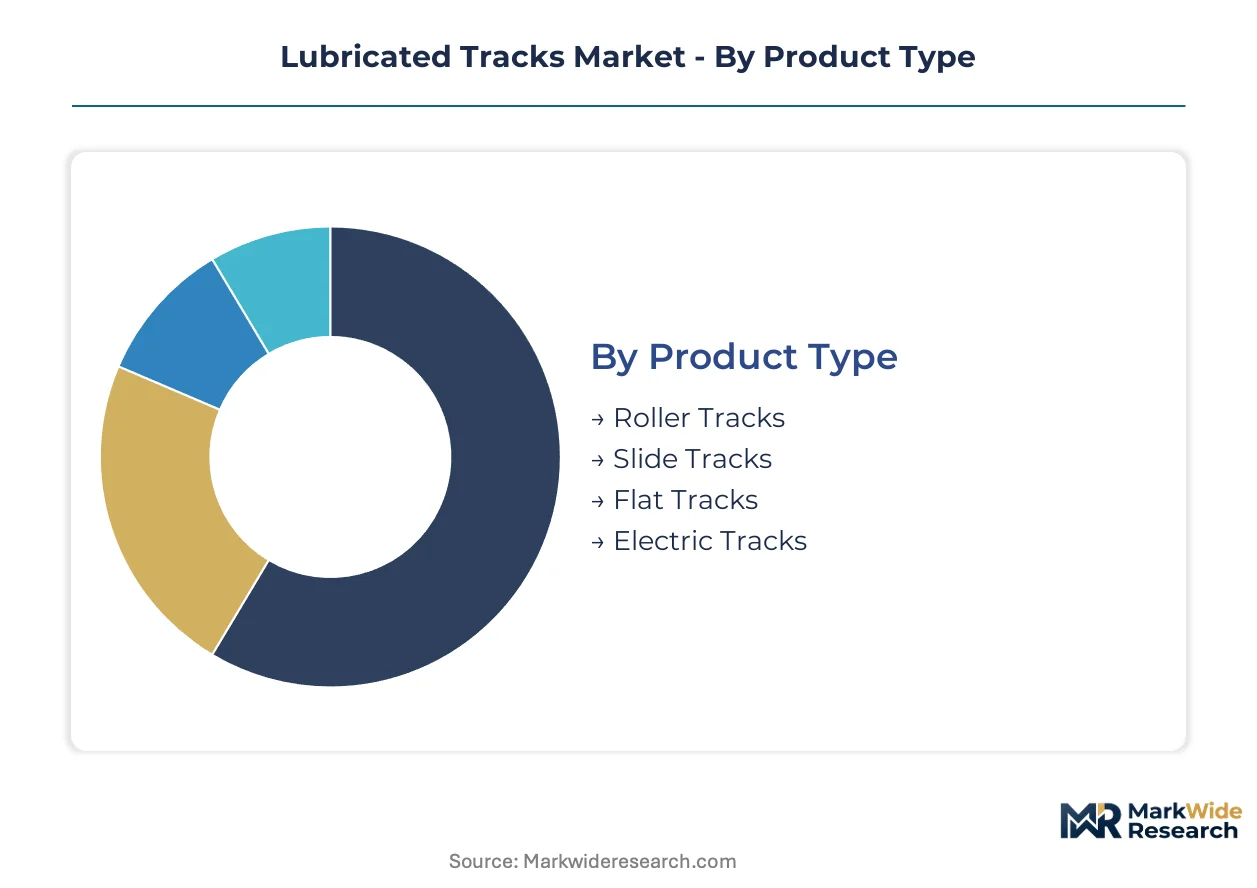
Segmentation in lubricated tracks reveals how divergent duty cycles—mining impact loads versus aerospace weight constraints—create incompatible specification clusters that no single product architecture can serve. Manufacturers must choose which performance envelope to optimize, as thermal management, material grade, and sealing technology requirements fracture across end-use boundaries.
Product Type:
Roller tracks face the most acute substitution pressure from electric track prototypes, while slide and flat track designs occupy defensible niches where load distribution geometry is less sensitive to powertrain thermal loads.
- Roller Tracks:Continuous linked steel plates with cylindrical roller engagement distribute impact loads across multiple contact points. Mining excavator and crawler crane procurement concentrates demand here, though sealed lubrication upgrades now pull replacement cycles toward premium system configurations rather than commodity dry-track alternatives.
- Electric Tracks:Battery-powered construction machinery prototypes require redesigned bushing geometries and synthetic lubricant formulations to manage heat loads beyond conventional thermal stability envelopes. German and Chinese OEM electrification roadmaps are accelerating field testing, though commercial deployment awaits thermal management breakthroughs.
- Slide Tracks:Linear bearing surfaces with grease-fed contact zones serve precision positioning equipment in automated manufacturing lines. JIS-standard machine tool builders in Japan specify these for high-repeatability gantry systems.
- Flat Tracks:Broad ground-contact surfaces with distributed load pads support low-ground-pressure vehicles in soft terrain agriculture. Brazilian sugarcane harvester fleets deploy these for wetland field access.
Roller tracks anchor the volume base while electric tracks gain share at the steepest rate.
End Use Industry:
Cost tier stratification separates capital-intensive mining procurement—where total cost of ownership calculations dominate—from aerospace specification work where weight penalties cascade into fuel burn economics.
- Mining:High-impact duty cycles with abrasive terrain exposure drive demand for sealed lubrication systems and premium steel alloys. Australian iron ore operators now unbundle after-sales rebuild services from captive OEM networks, redirecting maintenance spend toward specialized independent depots.
- Aerospace:Ground support equipment at Frankfurt and Changi airports specifies carbon-fiber hybrid track pads to meet strict tarmac weight limits for pushback tractors and baggage loaders. REACH chemical restrictions further pressure lubricant selection toward bio-synthetic formulations.
- Automotive:Assembly line conveyor systems and heavy-duty transport dollies utilize standardized roller configurations with predictable replacement intervals. OEM plant engineering teams prioritize supplier consolidation across multiple facility locations.
- Manufacturing:Automated material handling systems integrate slide tracks into cleanroom environments where particulate generation from metal-to-metal contact must be eliminated. FDA-registered medical device manufacturers impose additional lubricant purity certifications.
Mining commands the revenue concentration while aerospace climbs fastest on unit margin expansion.
Material:
Supply concentration in East Asian steel forging creates geographic vulnerability that composite and aluminum alternatives exploit for risk-diversification procurement.
- Steel:Yield strength requirements for high-impact mining duty cycles dominate OEM specifications, with scrap and billet price volatility squeezing margins during commodity spikes. Critical track link manufacturing clusters in Chinese industrial zones concentrate supply risk.
- Composite:Carbon-fiber reinforcement layers decompose historical steel-only assumptions in weight-constrained applications. Airport ground handling contractors specify these for precision duty cycles where impact loads remain controlled.
- Aluminum:Corrosion resistance and moderate weight reduction serve coastal construction equipment and marine transfer applications. Nordic riverbank excavation fleets specify aluminum track components with biodegradable lubricants near protected waterways.
- Plastic:Injection-molded polymer track segments address light-duty automation and food-grade processing equipment where metal contamination must be eliminated. EU F-Gas Regulation compliance drives lubricant compatibility testing.
Steel retains the installed base while composite penetration accelerates in adjacent weight-critical segments.
Size:
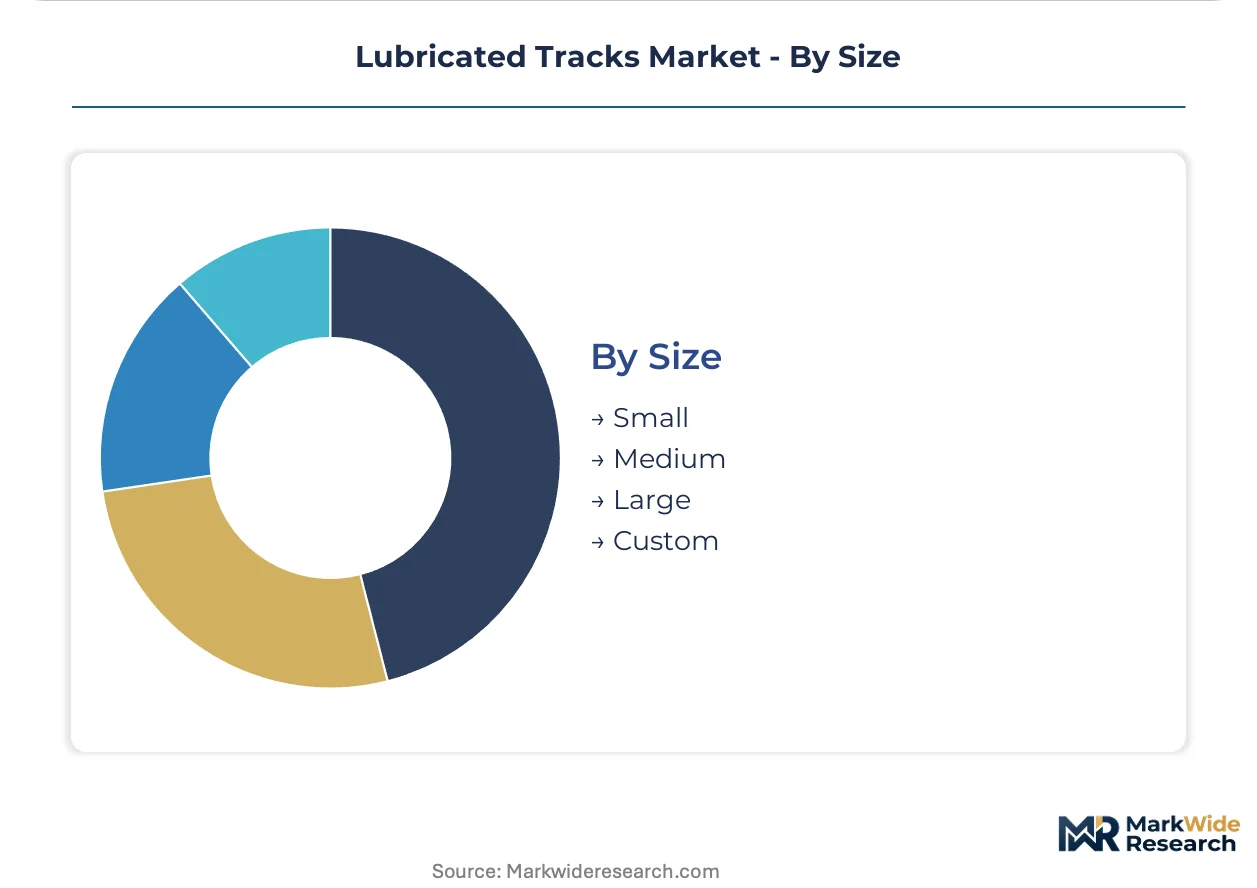
Margin structure inverts across the size spectrum: engineering-intensive custom work captures disproportionate returns versus commoditized standard dimensions.
- Custom:Non-standard pitch dimensions and specialized bushing alloys serve terrain vehicles for seismic exploration and military engineering applications. Specification work requires direct OEM-engineering collaboration with extended certification cycles.
- Large:Ultra-class mining excavators and draglines require forged track links exceeding standard catalog ranges. Tier 4 Final emissions standards pressure weight reduction even in these heavy-duty configurations.
- Medium:Mass-market excavator and dozer fleets drive volume production economies. Chinese domestic construction equipment manufacturing concentrates procurement here for state-backed infrastructure projects.
- Small:Compact utility loaders and mini-excavators serve urban construction and landscaping contractors. Aftermarket rebuild infrastructure remains underdeveloped for this tier outside North American and Western European dealer networks.
Medium dimensions carry the volume base while custom sizing extracts the premium margin pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese forging clusters supply track link assemblies to Australian mining operators and Indonesian construction fleets, creating a dominant East Asia-to-Asia-Pacific trade corridor that shapes regional pricing and lead time dynamics.
United States
EPA Tier 4 Final emissions standards compel OEMs to specify lighter track assemblies that reduce fuel consumption across crawler crane and excavator fleets. Domestic construction equipment manufacturers source sealed lubrication systems from specialized undercarriage suppliers. Industrial forging capacity concentrates in Ohio and Pennsylvania, where automated assembly lines serve Midwest mining contractors.
China
MIIT equipment quality certification and GB standards for construction machinery establish technical barriers that foreign suppliers must satisfy for market access. State-backed infrastructure projects in Sichuan and Shaanxi provinces drive procurement of heavy-duty lubricated track assemblies for domestic excavator production. Track link and bushing manufacturing clusters in Jiangsu and Zhejiang industrial zones dominate global forging output.
Australia
Iron ore and coal extraction operators unbundle after-sales rebuild services from captive OEM networks, redirecting maintenance spend toward independent depots in Queensland and Western Australia. National environmental regulations governing riverbank excavation equipment push lubricant selection toward biodegradable formulations. Perth and Mackay anchor specialized undercarriage service infrastructure for mid-tier mining contractors.
Germany
EU Green Deal machinery decarbonization pathways cascade into track system weight reduction specifications for construction OEMs. REACH chemical restrictions and F-Gas Regulation pressure lubricant formulators toward bio-synthetic alternatives. Frankfurt airport ground handling contractors specify carbon-fiber hybrid track pads for pushback tractors, demonstrating aerospace weight constraint viability.
Indonesia
Mid-tier mining contractors operating older equipment fleets lack rebuild service infrastructure, creating white space for specialized track life extension programs. National infrastructure investment programs in Kalimantan and Sulawesi expand excavator deployment for nickel and coal extraction. Surabaya industrial zones host emerging aftermarket parts distribution hubs serving domestic construction equipment demand.
Lubricated Tracks Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions, producing a tiered structure where scale-driven OEM suppliers face focused aftermarket rebuilders. Tire and rubber conglomerates leverage compounding expertise to supply high-durability track pads, while independent service depots capture maintenance spend through outcome-based contracts. Strategic archetypes include integrated tire-track portfolio bundlers, sealed lubrication system specialists, and regional aftermarket rebuilders. Dominant competitive moves center on geographic expansion into underpenetrated mining territories and technology licensing for electrified track thermal management.
Within the premium sealed-system tier, Bridgestone Corporation and Michelin represent integrated tire-track portfolio strategies that bundle undercarriage solutions with existing fleet contracts. Superior Tire & Rubber Corp. occupies a specialist position in aftermarket rebuild services, exemplifying the independent depot model that extends track life for contractors operating older equipment fleets. These three anchors demonstrate how compounding expertise, portfolio breadth, and service specialization create distinct competitive positions.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Camso |
| McLaren Industries |
| Global Track Warehouse |
| Michelin |
| LS Mtron Ltd |
| The Yokohama Rubber Co., Ltd. |
| Soucy |
| Superior Tire & Rubber Corp. |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Australian mining operators and Chinese forging clusters lock in supply access for heavy-duty track link assemblies while anchoring price visibility against scrap steel volatility. These arrangements concentrate procurement leverage among tier-one mining contractors, compressing margin pools for commodity-grade suppliers exposed to spot-market alloy pricing.
Pricing Analysis
Current-generation sealed lubrication systems command substantial premiums over prior-generation dry-track alternatives, while next-generation electric track prototypes remain pre-commercial with undetermined pricing architecture. Pricing stratifies across premium sealed systems, standard roller configurations, and economy-grade rebuild components, with differentiation driven by abrasion-resistant alloy grades and EPA Tier 4 Final certification status. Cost compression in standard-dimension segments is intensifying because Chinese domestic OEMs are absorbing margin to capture state-backed infrastructure procurement. Mid-tier mining contractors operating older fleets exhibit the highest price sensitivity, whereas Australian iron ore majors prioritize total cost of ownership calculations that favor premium sealed system life-cycle economics.
Supply Chain Analysis
Inventory buffers at Jiangsu and Zhejiang industrial zone foundries have compressed to lean levels, extending lead times for ultra-class mining excavator track links beyond standard catalog ranges. Critical manufacturing concentrates in China, with secondary forging capacity in Ohio and Pennsylvania serving North American mining contractors. Raw material dependencies center on high-yield steel billets, synthetic lubricant base stocks, and carbon-fiber reinforcement layers for aerospace applications. Single-source vulnerability in East Asian track link forging creates exposure to regional logistics disruptions. Distribution runs through captive OEM dealer networks and emerging independent service depots in Queensland and Western Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face sustained substitution pressure from electrified track architectures that will displace conventional sealed lubrication systems as battery-powered construction machinery achieves thermal management breakthroughs.
For Market Incumbents: Consolidate aftermarket rebuild infrastructure in underpenetrated mining territories to defend against independent depot capture of maintenance spend. Deepen backward integration into high-yield steel forging to insulate margin structures from scrap price volatility. Prioritize R&D investment in synthetic lubricant thermal stability to maintain positioning as electric track prototypes advance toward commercialization. For New Entrants and Emerging Players: Aftermarket service gaps in Indonesian nickel and coal extraction operations present immediate white-space opportunity for specialized track life extension programs. Focus initial penetration on mid-tier contractors operating legacy dry-track fleets that incumbent OEMs underserve through warranty-void retrofit policies. Deploy mobile rebuild units as the primary go-to-market mechanism to bypass fixed infrastructure requirements. For Investors and Strategic Acquirers: Regional aftermarket specialists with established technician training pipelines and parts distribution networks in Australian mining corridors represent the most compelling acquisition target archetype. Long-term viability hinges on positioning for the transition window where conventional sealed systems dominate installed bases while electric architectures scale. Monitor German and Chinese OEM electrification roadmap disclosures as the critical inflection signal for thermal management solution readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Sealed Lubrication System Upgrade | Extends undercarriage life for Caterpillar and Komatsu fleets operating in Western Australian iron ore corridors. |
| Composite Reinforcement Layer Adoption | Enables Boeing and Airbus ground handlers to meet strict Frankfurt and Changi airport weight limits. |
| Aftermarket Rebuild Service Expansion | Captures maintenance spend displacement from captive OEM networks in Queensland mining territories. |
| Bio-Synthetic Lubricant Formulation | Satisfies REACH and EU F-Gas Regulation requirements for German riverbank excavation equipment. |
| Electric Track Thermal Management R&D | Resolves heat load constraints blocking commercial deployment of battery-powered construction machinery prototypes. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed tire and rubber conglomerates, and MIIT equipment certification registers. Primary interviews engaged maintenance directors at Australian iron ore operations, procurement leads at Chinese domestic construction OEMs, aftermarket service heads at independent Queensland depots, and plant engineers at Ohio forging facilities. Secondary validation drew from EPA Tier 4 Final regulatory filings, EU Green Deal machinery decarbonization pathway documents, and GB standards construction machinery technical specifications. Bottom-up demand modeling across end-use industries triangulates against top-down supply-side capacity assessments from Jiangsu and Zhejiang industrial zone output data.
Segmentation dimensions modeled encompass product type, end-use industry, material grade, and sizing configuration across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns and forward-looking OEM electrification roadmaps. Industry-specific forecast inputs include mining fleet replacement cycles for sealed lubrication upgrades and aerospace ground support equipment weight constraint specifications. Volume and value outputs reflect analytical synthesis of duty cycle intensity, regulatory compliance timelines, and regional infrastructure investment programs.
Underlying assumptions cover sustained steel alloy availability, stable regulatory enforcement of EPA and EU emissions frameworks, and gradual electric track thermal management advancement, with deviation risk concentrated in commodity price spikes and geopolitical logistics disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Specialties of Lube Oil Refinery Market
Lubricants
Russia Automotive Lubricants Market
Lubricants
Poland Industrial Lubricants Market
Lubricants
Technical Fluids Market
Lubricants
Italy Automotive Lubricants Market
Lubricants
Kenya Lubricants Market
Lubricants
Spain Commercial Vehicles Lubricants Market
Lubricants
Canada Commercial Vehicles Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Angola Lubricants Market
Lubricants
High Performance Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Germany Lubricants Market
Lubricants
Global Lubricant Anti Wear Agents Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
South Korea Automotive Lubricants Market