
 Russia Automotive Lubricants Market | 2026-2036
Russia Automotive Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Automotive Lubricants Market Analytics
Service station networks is reshaping how automotive lubricants reach end users across Russia's vast territory. Gazpromneft-Lubricants Ltd. leverages its captive crude supply and downstream integration to dominate retail fuel-and-lube bundling at company-owned stations. Lukoil sustains broad geographic coverage through an extensive branded service center network stretching from European Russia into Siberia. Shell Plc competes by positioning its synthetic product lines toward premium vehicle owners in major urban centers.
Automotive lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in powertrain components operating across extreme temperature ranges from minus fifty to plus forty degrees Celsius. Their primary commercial purpose centers on extending engine and transmission service life while maintaining fuel efficiency under severe Russian climatic and road conditions. Engine oil captures the dominant value pool given high replacement frequency and synthetic upgrade trends among passenger vehicle owners, while gear oil generates concentrated margins from commercial and heavy-duty truck applications where load protection requirements are most stringent. Distribution through service stations leads volume throughput, though online channels are gaining traction for DIY consumers in metropolitan areas.
Russia's GOST R standards system, administered by Rosstandart, mandates specific viscosity grades and performance classifications that all marketed lubricants must satisfy before legal sale. The EAEU technical regulations on oil safety further harmonize requirements across the customs union, directly influencing formulation decisions by domestic and foreign suppliers alike. Stakeholders must monitor how evolving emissions norms for the Russian vehicle parc redirect demand toward lower-viscosity, fuel-economy-certified lubricant grades.
Market Dynamics
Rosstandart's tightening GOST R viscosity and performance mandates are forcing reformulation across the entire Russia automotive lubricants supply base, compressing product lifecycles while elevating compliance costs for blenders without captive base oil supply.
Growth Catalysts
- Extended drain interval technology:Synthetic and semi-synthetic formulations certified under GOST R 54283 enable commercial fleet operators to push service intervals beyond fifteen thousand kilometers, reducing total cost of ownership and locking in bulk procurement contracts.
- EAEU technical regulation harmonization:Unified safety and performance standards across the customs union eliminate duplicate testing burdens for suppliers distributing into Belarus and Kazakhstan from Russian production facilities.
- Central Federal District vehicle density:Moscow's concentration of premium passenger vehicles and authorized service centers generates disproportionate demand for high-margin synthetic engine oils relative to national population distribution.
Market Restraints
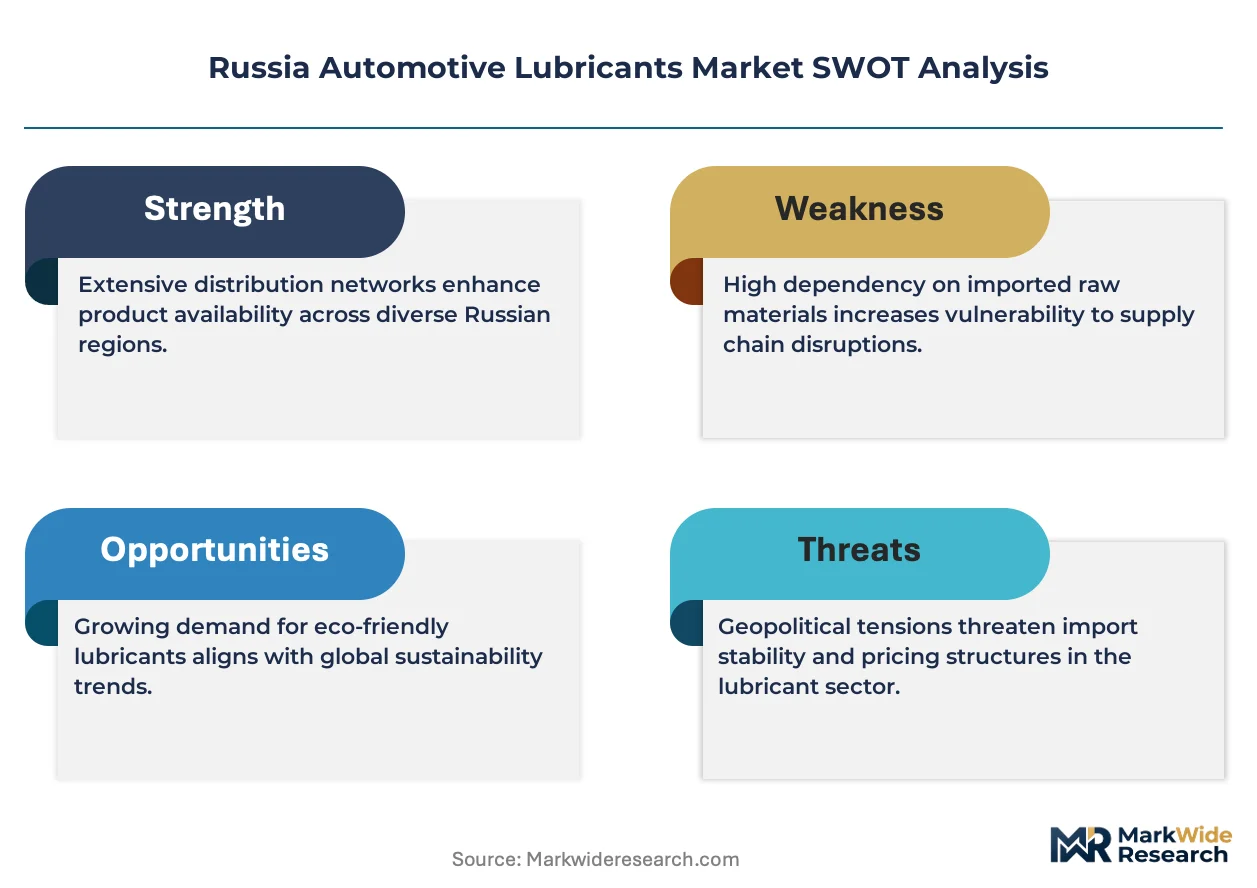
- Base oil supply concentration:Domestic production of Group II and III base stocks clusters at a limited number of refinery complexes, exposing blenders to feedstock allocation disruptions and transfer pricing leverage from integrated oil majors.
- Import substitution complexity:Sanctions-related restrictions on additive package sourcing from Western suppliers force rapid qualification of alternative formulation chemistries, extending product development timelines.
- Climate-driven viscosity grade fragmentation:Extreme temperature differentials between Yakutsk and Sochi necessitate maintaining fifteen-plus SKU variants, eroding production scale economies and complicating inventory management.
Strategic Opportunities
- Siberian and Far Eastern Federal Districts:Underpenetrated service infrastructure in cities such as Krasnoyarsk and Vladivostok presents first-mover potential for mobile lubricant delivery and on-site fleet servicing models.
- Electric vehicle thermal fluid crossover:Formulation expertise in heat transfer and dielectric properties positions established lubricant suppliers to capture emerging demand from battery electric vehicle cooling systems and e-axle greases.
- Digital B2B procurement platforms:Industrial marketplace adoption by mid-sized logistics operators enables direct manufacturer-to-fleet relationships, disintermediating traditional wholesale distributors.
Industry Challenges
- Additive chemist talent scarcity:Specialized formulation expertise in friction modifier and detergent chemistry concentrates at legacy Soviet-era research institutes, constraining product innovation velocity for independent blenders.
- GOST R certification timeline compression:Accelerated revision cycles for performance classifications force repeated bench and field testing investments, straining R&D budgets without guaranteed commercial uptake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Automotive Lubricants Market |
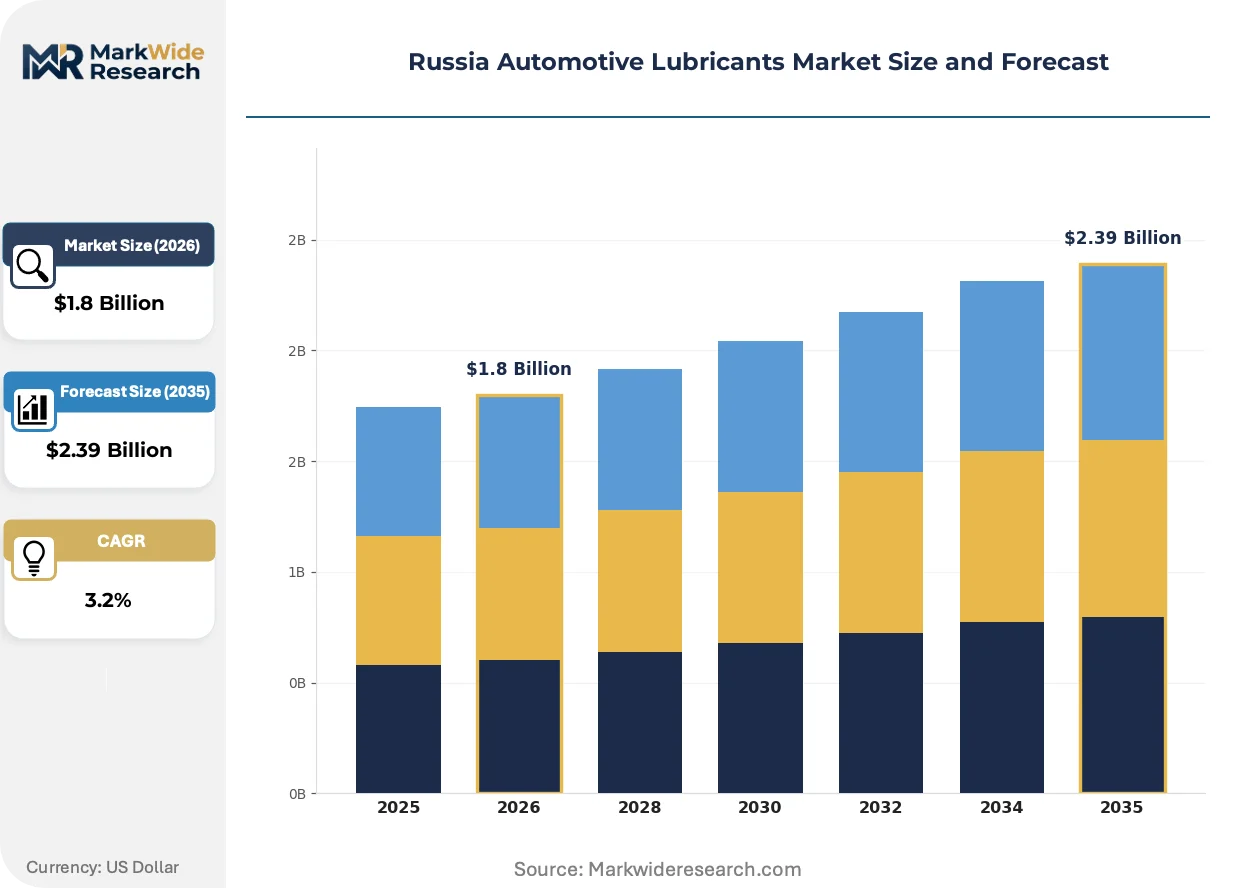
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Brake Fluid, Grease End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Two-Wheelers Distribution Channel: Retail, Online, Wholesalers, Service Stations Application: Automotive, Industrial, Marine, Others |
| Companies Covered | Shell Plc, Exxon Mobil Corporation, Gazpromneft-Lubricants Ltd., Fuchs Petrolub, TotalEnergies, Lukoil, BP plc, Chevron, Rosneft, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Automotive Lubricants Market Evolving Landscape
Digital integration across lubricant supply chains is compressing information asymmetries between manufacturers and end users, while regulatory stringency and procurement model evolution reshape competitive positioning.
Sensor-enabled oil condition monitoring is digitizing fleet maintenance decision-making. Telematics providers embed viscosity and particulate sensors directly into commercial vehicle powertrains, transmitting real-time degradation data to fleet management platforms. Large trucking operators in the Central Federal District are adopting these systems fastest, enabling condition-based drain intervals that override manufacturer recommendations and compress traditional scheduled maintenance revenue pools.
Rosstandart's 2024 amendments to GOST R 54283 introduced fuel economy testing protocols modeled on European ACEA sequences. Domestic blenders must now demonstrate measurable CO2 reduction in standardized engine dynamometer tests to claim efficiency certifications. Premium synthetic lines targeting Moscow's luxury vehicle parc are reformulating first, while economy mineral grades face margin compression from testing cost absorption.
Direct procurement from lubricant manufacturers is displacing layered wholesale distribution for mid-size fleet operators. Digital tender platforms enable transparent price discovery and specification matching, collapsing traditional distributor markups. This pattern concentrates in the Volga Federal District where regional logistics companies aggregate sufficient volume to negotiate manufacturer-direct terms, forcing independent distributors to pivot toward technical advisory and last-mile delivery services.
Russia Automotive Lubricants Market Segmentation
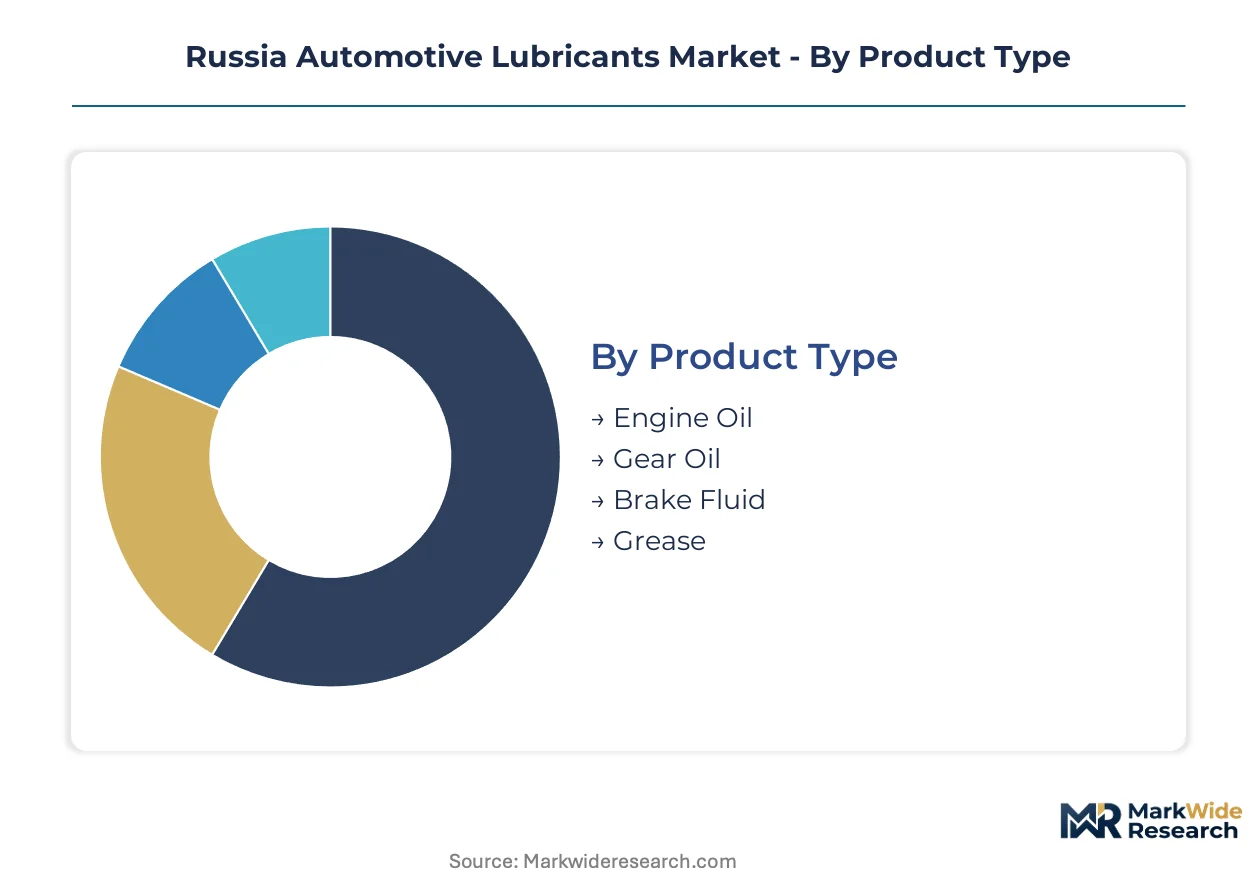
Segmentation in Russia's automotive lubricants market reveals how formulation requirements, fleet economics, and climatic extremes fragment demand across distinct product tiers and customer profiles. Understanding these divisions exposes where margin pools concentrate and where supply infrastructure must adapt.
Product Type:
Mature categories dominate volume throughput while emerging formulations capture technology premiums.
- Engine Oil:Formulated from Group II/III base stocks with detergent-dispersant additive packages to manage soot loading and oxidation in gasoline and diesel powertrains. Demand clusters heaviest in Moscow's Central Federal District where synthetic upgrade rates among premium passenger vehicles exceed national averages, driven by extended drain interval marketing and GOST R 54283 fuel economy certification requirements.
- Gear Oil:Extreme-pressure lubricants fortified with sulfur-phosphorus compounds to protect hypoid gear sets under high-torque, high-load conditions. Commercial vehicle fleets in the Volga Federal District generate concentrated procurement volumes for heavy-duty transmission and axle applications, with bulk purchasing agreements locking in multi-year supply relationships with integrated oil majors.
- Brake Fluid:Glycol-ether or silicone-based hydraulic fluids meeting DOT 3/4/5.1 specifications for thermal stability and moisture resistance.
- Grease:Thickened lubricants combining base oil with metallic soap or complex thickeners for chassis, wheel bearing, and universal joint applications.
Engine Oil handles the majority of throughput; Gear Oil is the fastest mover on share.
End User:
Customer type segmentation tracks vehicle parc composition and operating intensity across Russia's climatic zones.
- Passenger Vehicles:Private owners of cars and light SUVs operating under personal use duty cycles with variable maintenance discipline. Moscow and St. Petersburg metropolitan areas concentrate demand for synthetic and semi-synthetic grades, with authorized dealer service networks pushing OEM-approved lubricant specifications over aftermarket alternatives.
- Commercial Vehicles:Light and medium-duty trucks, vans, and buses operated by fleet entities with centralized procurement and maintenance protocols. Regional logistics operators in the Central and Volga Federal Districts are adopting telematics-enabled condition monitoring to extend drain intervals, compressing traditional scheduled maintenance revenue while raising specification requirements for oil quality.
- Heavy-Duty Trucks:Long-haul tractors and construction equipment subjected to severe load factors and extended operating hours.
- Two-Wheelers:Motorcycles and scooters with small-displacement engines requiring specialized low-ash, high-detergent formulations.
Passenger Vehicles anchor absolute volume; Commercial Vehicles are expanding most quickly as fleet professionalization accelerates.
Distribution Channel:
Channel structure reflects the tension between physical infrastructure coverage and digital procurement efficiency.
- Service Stations:Fuel-and-lube bundling at integrated oil major retail networks captures the highest volume throughput through captive customer traffic and immediate availability. Gazpromneft and Lukoil station networks dominate geographic coverage from European Russia into Siberia, leveraging crude supply integration to control pricing and product placement.
- Online:E-commerce platforms and manufacturer-direct portals serve DIY consumers and small fleet operators with specification transparency and competitive pricing. Metropolitan areas around Moscow and St. Petersburg show fastest channel growth as digital procurement habits penetrate automotive maintenance categories.
- Retail:Automotive parts stores and hypermarket chains stocking consumer-packaged lubricants for self-service purchase.
- Wholesalers:Regional distributors aggregating volume for independent service centers and smaller fleet accounts.
Service Stations maintain the dominant share position; Online is climbing the fastest as urban DIY adoption spreads.
Application:
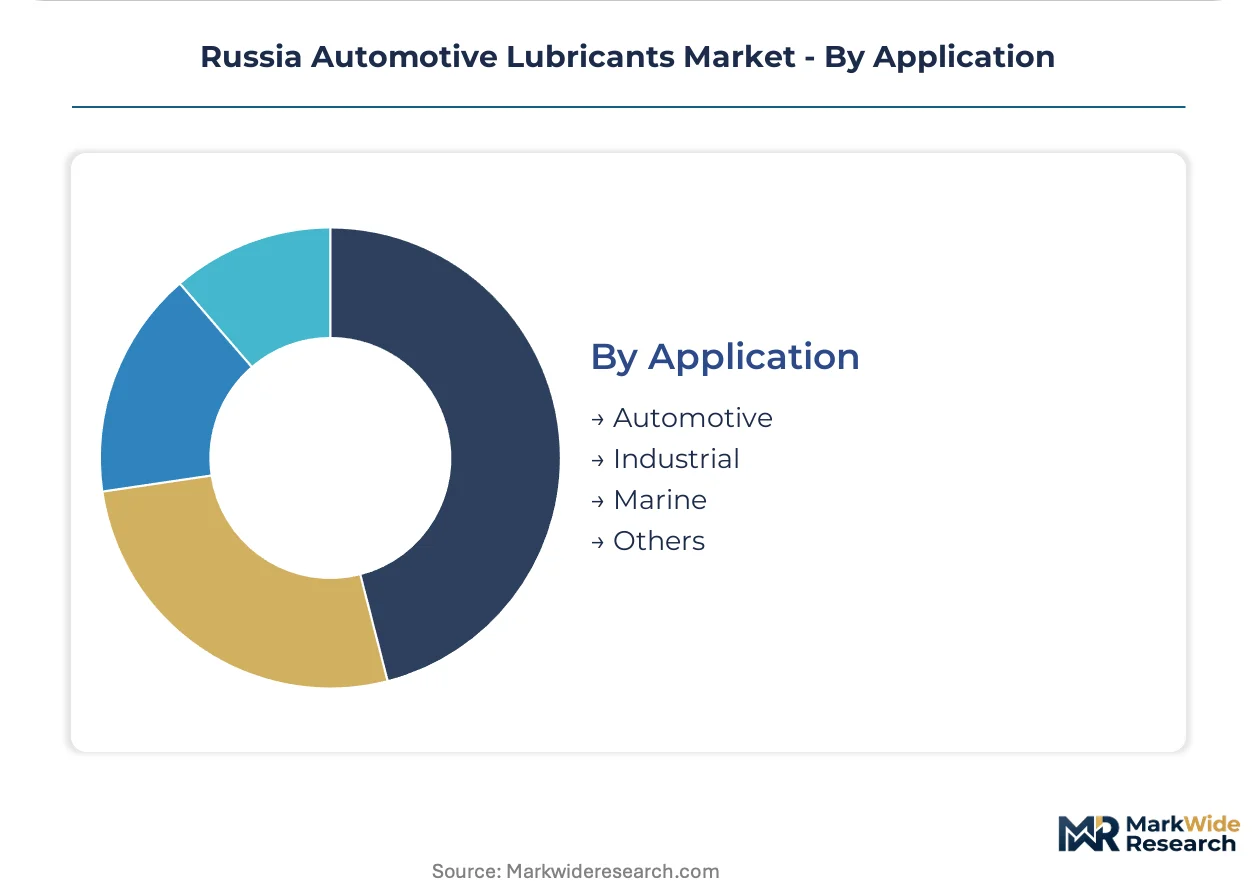
Application segmentation separates automotive core demand from industrial diversification opportunities.
- Automotive:Powertrain, chassis, and auxiliary system lubrication for on-road vehicles across passenger and commercial categories. This segment absorbs the overwhelming majority of formulated lubricant volume in Russia, with specification evolution tracking GOST R tightening and EAEU technical regulation harmonization.
- Industrial:Manufacturing equipment, compressors, and hydraulic systems requiring rust-inhibited and anti-wear formulations. Demand from machine-building clusters in the Ural Federal District provides diversification for blenders with surplus capacity, though pricing pressure from industrial procurement tenders compresses margins relative to automotive grades.
- Marine:Stern tube, diesel engine, and deck machinery lubricants for inland waterway and coastal vessels.
- Others:Agricultural machinery, aviation ground support, and specialty equipment applications with bespoke formulation requirements.
Automotive commands the volume base; Industrial is gaining share fastest as suppliers seek capacity utilization beyond core vehicle demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Siberian Railway and pipeline networks connecting Western Siberian refineries to European distribution hubs underpin Russia's lubricant logistics architecture. Base oil production clusters around Samara, Nizhny Novgorod, and Omsk, with finished lubricant blending facilities positioned near major vehicle population centers. Federal District-level demand patterns reflect temperature extremes, fleet density, and service infrastructure maturity.
Central Federal District
Moscow's vehicle parc exceeds four million registered units, generating concentrated demand for synthetic engine oils and premium service formats. Rosstandart's GOST R certification laboratories in the capital accelerate product approval timelines for domestic blenders. The Moscow Ring Road corridor hosts the densest concentration of authorized service centers, where OEM-approved lubricant specifications dominate aftermarket sales.
Volga Federal District
Commercial fleet operators in Tatarstan and Samara Oblast anchor bulk procurement volumes for heavy-duty gear oils and extended-drain formulations. The Kama River manufacturing cluster supports integrated supply chains from base oil production through finished lubricant blending. Kazan's logistics hub position enables efficient distribution into the Ural and Siberian Federal Districts.
Siberian Federal District
Krasnoyarsk and Novosibirsk face acute underpenetration of branded service infrastructure across vast territories. Extreme cold-start requirements in Irkutsk and Yakutsk drive demand for 0W-40 and 5W-40 viscosity grades unavailable through informal channels. Mobile lubricant delivery models are testing last-mile economics in cities separated by thousands of kilometers of federal highway.
Northwestern Federal District
St. Petersburg's port infrastructure handles imported additive packages and base oil feedstocks subject to sanctions-related supply chain restructuring. The Baltic Pipeline System termination point at Primorsk creates feedstock allocation leverage for regional blenders. Fleet professionalization in the Leningrad Oblast logistics corridor is compressing traditional wholesale distribution margins.
Southern Federal District
Rostov-on-Don and Krasnodar experience milder temperature profiles that sustain year-round demand for mineral and semi-synthetic grades. Agricultural machinery fleets in the Kuban grain belt generate seasonal grease and hydraulic fluid procurement spikes. Black Sea port access supports alternative import routes for formulation components restricted through Baltic corridors.
Russia Automotive Lubricants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in base oil and additive supply. Russia's automotive lubricants sector exhibits tiered consolidation around integrated oil majors with captive refinery assets, mid-scale independent blenders dependent on merchant feedstock, and foreign multinationals competing through premium positioning. Three archetypes dominate: vertically integrated energy majors controlling retail fuel-and-lube bundling, formulation-focused independents serving industrial accounts, and global brand licensors targeting synthetic upgrade segments. Competitive dynamics center on backward integration into Group II/III base oil production and digital procurement platform deployment to disintermediate wholesale distributors.
Among Russia-based integrated producers, Gazpromneft-Lubricants Ltd. and Lukoil exemplify the captive-refinery archetype, leveraging pipeline-connected feedstock supply to control cost structures. Shell Plc occupies a position within the premium synthetic tier, competing on formulation certification and brand equity rather than vertical integration. These three anchors illustrate how competitive advantage derives from either upstream resource control or downstream specification authority, with limited middle ground for undifferentiated blenders.
| Leading Market Players |
|---|
| Shell Plc |
| Exxon Mobil Corporation |
| Gazpromneft-Lubricants Ltd. |
| Fuchs Petrolub |
| TotalEnergies |
| Lukoil |
| BP plc |
| Chevron |
| Rosneft |
| Others |
Value Network & Pricing Analysis
Overcapacity in Group II base oil refining across the Volga Federal District is compressing feedstock margins while forcing integrated producers to prioritize captive blending over merchant sales, reshaping pricing power across formulation tiers.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships, with fleet operators capturing 15-20% price advantages on bulk synthetic orders versus retail service station pricing. Price differentiation rests on GOST R certification grade and geographic delivery cost, with Moscow-sourced premium synthetics commanding substantial premiums over regional mineral grades. Cost compression in the economy mineral tier is intensifying because Rosstandart's 2024 testing mandates force margin absorption. Commercial fleet operators exhibit highest price sensitivity, while authorized dealer networks serving premium passenger vehicles show lowest elasticity.
Supply Chain Analysis
Export-control regimes restricting Western additive package technology are forcing rapid requalification of friction-modifier chemistries from Asian suppliers. Geographic supply concentration centers on Russia for base oil production, China for alternative additive sourcing, and Kazakhstan for cross-border blending capacity. Raw material dependencies include Group II/III base stocks, detergent-dispersant packages, and viscosity-index improvers. Single-source vulnerability in specialized anti-wear chemistry creates procurement risk. Distribution runs through integrated oil major retail networks with captive fuel-and-lube bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as telematics-enabled condition monitoring splinters fleet procurement into specification-specific niches, rewarding suppliers with formulation agility over scale.
For Market Incumbents: Entrench market position through backward integration into Group III base oil capacity additions in Samara Oblast and accelerated GOST R 54283 fuel-economy certification investment. Channel control via digital fleet procurement platforms defends against distributor disintermediation threatening traditional wholesale margins. For New Entrants and Emerging Players: Mid-sized logistics operators in the Siberian Federal District lacking authorized service infrastructure represent the most penetrable entry point for mobile lubricant delivery and on-site fleet servicing models. Krasnoyarsk-based regional distributors with established cold-chain logistics capabilities offer partnership pathways for synthetic-grade market entry. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-integrated fleet service providers with multi-year bulk supply contracts. Long-term viability favors blenders with captive base oil supply and additive formulation independence. Watch for Rosstandart certification timeline compression as inflection signal forcing R&D consolidation among independent blenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III Base Oil | Samara and Omsk refinery expansions reduce feedstock cost volatility for integrated producers. |
| Telematics Platform Partnership | Sensor-enabled condition monitoring locks fleet customers into data-integrated lubricant procurement. |
| GOST R Fuel-Economy Certification Acceleration | Rosstandart's 2024 testing protocols favor early movers in synthetic reformulation. |
| Siberian Mobile Delivery Infrastructure | Krasnoyarsk and Vladivostok service gaps enable first-mover fleet servicing models. |
| Additive Package Supplier Diversification | Asian friction-modifier qualification reduces Western technology dependency risks. |
Research Methodology
A standing panel of lubricant blending plant managers, commercial fleet procurement directors, Rosstandart certification laboratory technicians, and regional wholesale distributors provided ongoing calibration across the study period. Primary interview data combined with secondary validation from customs trade records, EAEU technical regulation harmonization documents, base oil production disclosures, and vehicle registration databases. Bottom-up volume modeling triangulated against top-down value estimates derived from refinery throughput and retail fuel-and-lube bundling revenue.
Scenario-bracketing framed the analytical approach across the projection horizon, with CAGRs derived from elasticity modeling against vehicle parc growth and synthetic penetration trajectories. Segmentation dimensions included product type, end-user category, distribution channel, and Federal District-level demand clustering. Industry-specific inputs incorporated GOST R revision timelines, EAEU regulatory harmonization progress, and telematics adoption curves among commercial fleet operators.
Practitioners should monitor Rosstandart certification cycle acceleration and additive package import substitution progress for early signals of supply base restructuring. Forecasts reflect assumptions regarding EAEU technical regulation stability and base oil refinery utilization rates. Material shifts in sanctions regime stringency or GOST R performance classification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
United Kingdom Automotive Lubricants Market
Lubricants
Africa Lubricants Market
Lubricants
Morocco Lubricants Market
Lubricants
Food Grade Lubricant Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
Specialty Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Indonesia Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Europe Metalworking Fluids Market
Lubricants
Offshore Lubricants Market
Lubricants
Global Independent Lubricant Manufacturers Market
Lubricants
Russia Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Lubricated Tracks Market