
 Chile Gastric Cancer Treatment Market | 2026-2036
Chile Gastric Cancer Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Gastric Cancer Treatment Market Outlook
Oncology biologics manufacturing capacity across Latin America is hardening as regional fill-finish networks expand. Roche leverages its established HER2-targeted portfolio to anchor therapeutic positioning in Santiago's tertiary hospital networks. Bristol-Myers Squibb competes through immuno-oncology development programs aligned with Chile's expanding clinical research infrastructure. AstraZeneca differentiates via biomarker-driven patient selection protocols that match regional pathology laboratory capabilities.
Gastric cancer treatment encompasses multimodal therapeutic interventions combining surgical resection, systemic cytotoxic agents, ionizing radiation, and molecularly targeted biologics designed to eliminate or control malignant gastric epithelial cell proliferation. The primary purpose is to extend survival and preserve quality of life through stage-appropriate intervention protocols. Surgery and chemotherapy occupy the dominant share of current treatment volumes, reflecting established reimbursement pathways under Chile's public health framework. Immunotherapy represents the fastest-expanding technology segment as checkpoint inhibitors gain inclusion in national cancer protocols. Targeted therapy concentrates margin pools where biomarker testing infrastructure supports premium therapeutic selection.
Chile's Ministry of Health administers the GES program mandating timely access to defined cancer treatments, while the national pharmaceutical regulator oversees product registration and pharmacovigilance standards for oncology therapeutics. These frameworks shape demand by specifying eligible procedures and creating predictable procurement volumes for approved therapies. Stakeholders must monitor biomarker testing infrastructure expansion and GES protocol updates to align portfolio investments with reimbursable treatment categories.
Market Dynamics
The Explicit Health Guarantees program is expanding coverage criteria for molecularly targeted therapies, redirecting procurement volumes toward biomarker-driven treatment protocols across Santiago's tertiary hospital networks.
Growth Catalysts
- GES Protocol Expansion:Chile's Ministry of Health updates cancer pathway coverage to include checkpoint inhibitors, creating predictable reimbursement for immunotherapy agents.
- Santiago Cluster Density:Concentration of specialized oncology centers in the Metropolitan Region generates referral gravity that consolidates demand for advanced therapeutic modalities.
- Biomarker Testing Infrastructure:Pathology laboratory capabilities in Valparaíso and Biobío regions now support HER2 and PD-L1 testing, enabling patient selection for targeted biologics.
Market Restraints
- Biologics Cold Chain Costs:Temperature-controlled distribution requirements for monoclonal antibodies impose logistics premiums that strain regional hospital pharmacy budgets.
- Specialized Workforce Scarcity:Medical oncology fellowship programs produce insufficient clinicians to staff expanding treatment centers in Antofagasta and La Araucanía.
- Import Dependency:Active pharmaceutical ingredients for cytotoxic agents concentrate in Asian manufacturing hubs, exposing supply continuity to shipping lane volatility.
Strategic Opportunities
- Maule and Ñuble Underservice:These central valley provinces maintain gastric cancer incidence above national average with limited access to multidisciplinary tumor boards.
- Telemedicine-Enabled Second Opinions:Remote consultation platforms connect regional hospitals to Santiago-based specialists, expanding eligible patient pools for complex protocols.
- Clinical Trial Infrastructure:Expanded regulatory alignment with ICH-GCP standards positions Chilean sites for immuno-oncology development programs.
Industry Challenges
- Pathologist Certification Bottlenecks:Extended training timelines for molecular diagnostics specialists delay biomarker test result turnaround in public hospital laboratories.
- Legacy EMR Integration:Hospital information systems in regional facilities require costly upgrades to support electronic prescribing for biologics and adverse event reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Gastric Cancer Treatment Market |
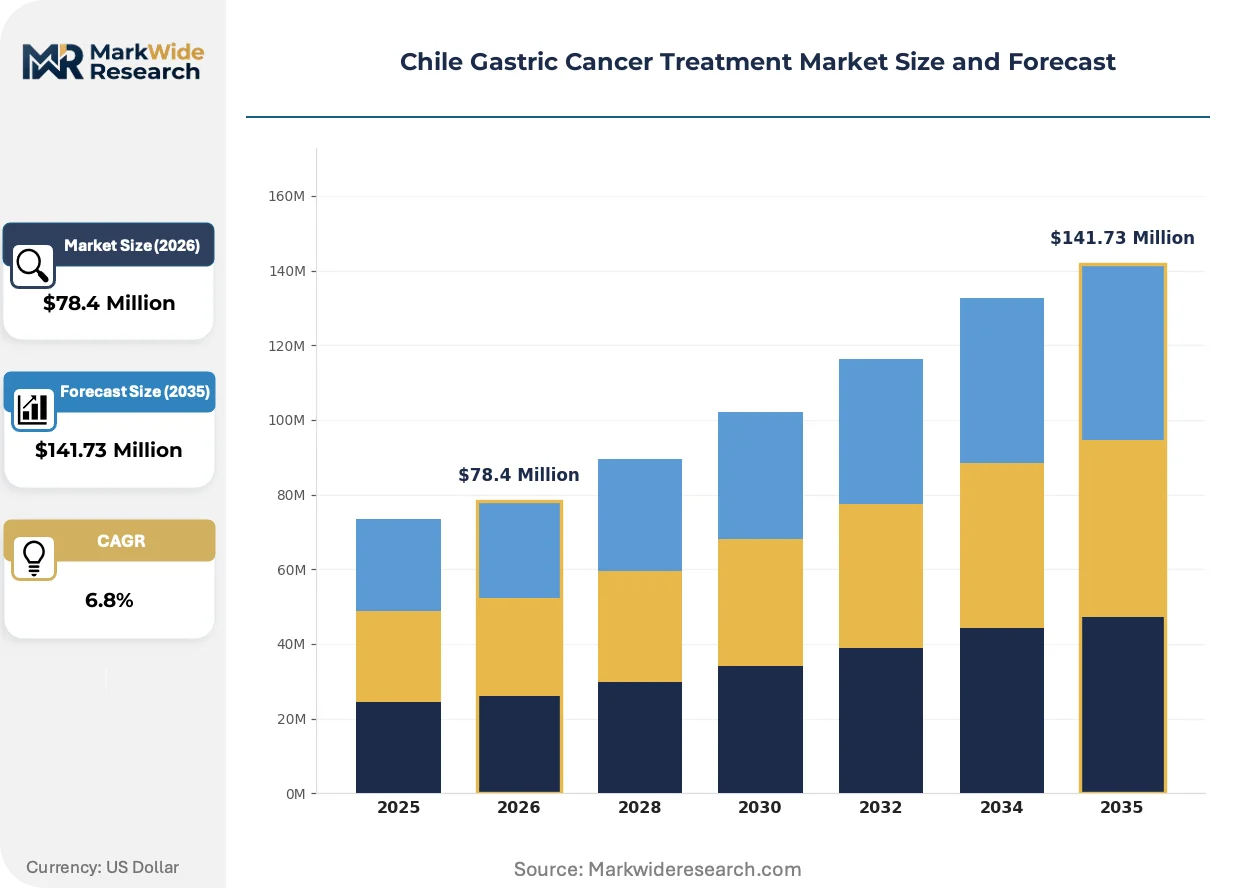
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $141.73 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Chemotherapy, Radiation Therapy, Targeted Therapy Technology: Immunotherapy, Biologics, Chemotherapy Agents, Radiopharmaceuticals End User: Hospitals, Clinics, Outpatient Centers, Research Institutions Treatment Stage: Early Stage, Advanced Stage, Palliative Care, Post-operative Care |
| Companies Covered | Roche, Bristol-Myers Squibb, AstraZeneca, Merck & Co., Novartis AG, Pfizer, Eli Lilly and Company, Teva Pharmaceutical Industries Ltd, Celltrion Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Gastric Cancer Treatment Market Strategic Shifts
Multimodal treatment protocols are integrating real-time genomic profiling into first-line decision trees, compressing the interval between diagnosis and targeted therapy initiation across Chile's public hospital networks.
Next-generation sequencing platforms are converging with liquid biopsy workflows to enable circulating tumor DNA monitoring without repeat endoscopic procedures. Oncology departments at Hospital Clínico Universidad de Chile and Hospital Base Valdivia are adopting these platforms to track treatment response. This convergence is compressing the role of traditional imaging-based staging in favor of molecular residual disease assessment.
Chile's national pharmaceutical regulator has streamlined pharmacovigilance reporting requirements for oncology therapeutics, reducing post-market study initiation timelines. Manufacturers now face accelerated safety data submission obligations. Biologics sponsors with established Santiago distribution networks are responding by embedding dedicated drug safety officers within local affiliate operations.
Hospital pharmacy committees are consolidating purchasing decisions through centralized regional tenders rather than facility-level procurement. The Coquimbo and Atacama health service networks have adopted this model for cytotoxic agents. Private oncology clinics in Concepción are now the primary channel where direct manufacturer engagement still occurs.
Chile Gastric Cancer Treatment Market Segmentation
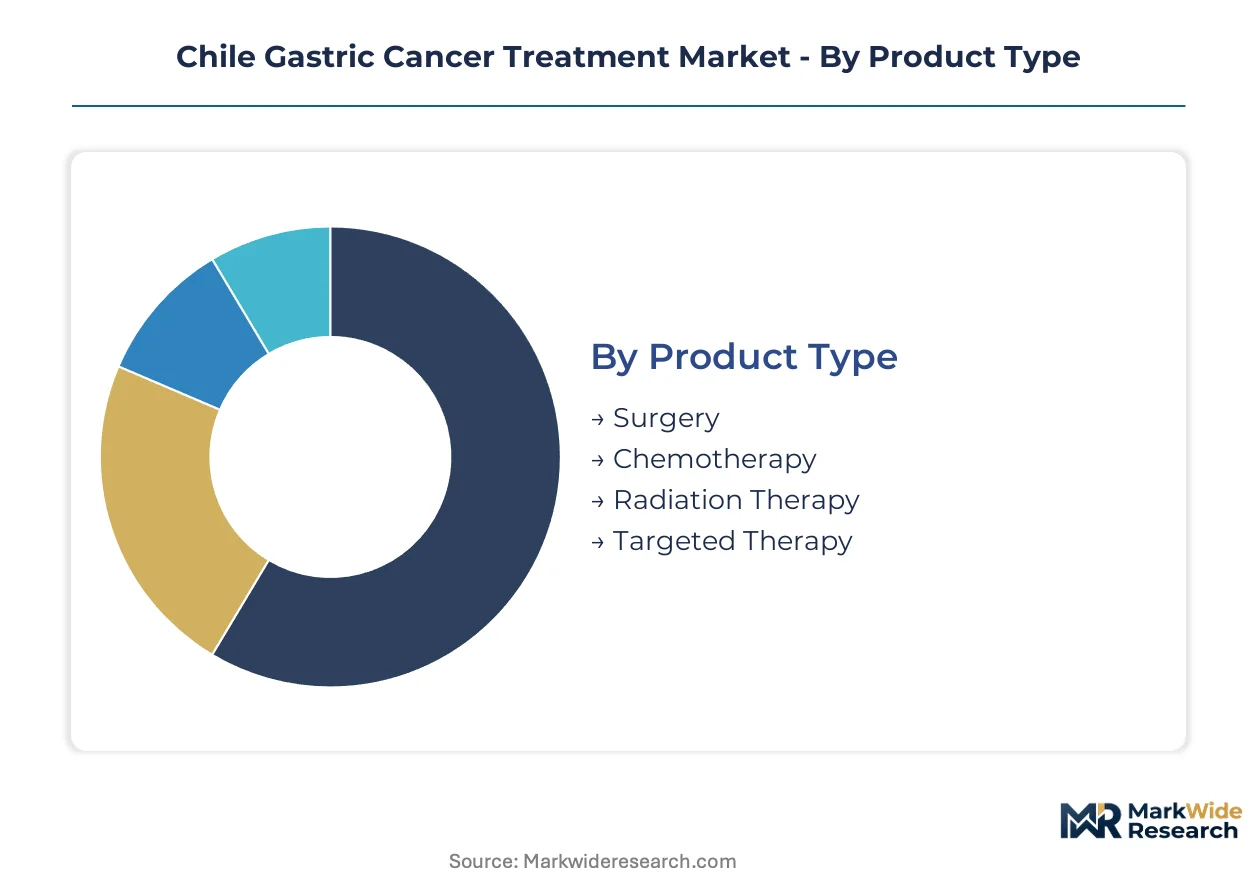
Treatment modality selection in Chile's gastric cancer market hinges on GES reimbursement eligibility, biomarker availability, and regional hospital capabilities. Segmentation reveals where public procurement concentrates versus where private oncology clinics capture premium patient flows.
Product Type:
Surgical resection protocols and systemic agent administration define the technical axis around which Chilean oncologists structure first-line decisions.
- Surgery:Gastrectomy with lymphadenectomy remains the curative foundation for resectable disease. Santiago's Hospital Clínico Universidad de Chile and Hospital Base Valdivia perform the highest volumes of D2 dissections, drawing referrals from Maule and Ñuble provinces where specialized surgical oncology is scarce.
- Chemotherapy:Platinum-fluoropyrimidine doublets dominate adjuvant and neoadjuvant protocols under GES coverage. Regional hospital networks in Valparaíso and Biobío regions procure these agents through centralized tenders, compressing margins for distributors.
- Radiation Therapy:Adjuvant chemoradiation follows INT-0116 protocols for selected patients. Linear accelerator capacity concentrates in the Metropolitan Region, limiting access in La Araucanía.
- Targeted Therapy:HER2-directed monoclonal antibodies and VEGF inhibitors command premium pricing where biomarker testing infrastructure supports patient selection.
Mature deployment sits with Surgery. Newer deployment is concentrated in Targeted Therapy.
Technology:
Mechanism of action and manufacturing complexity separate established cytotoxic platforms from emerging immuno-oncology modalities.
- Immunotherapy:Checkpoint inhibitors targeting PD-1/PD-L1 pathways are gaining GES inclusion for advanced gastric cancer. Hospital pharmacy committees in the Metropolitan Region are expanding formulary access as PD-L1 testing becomes routine.
- Biologics:Trastuzumab and ramucirumab anchor the targeted segment. Cold chain distribution requirements favor sponsors with established Santiago-based logistics networks over regional competitors.
- Chemotherapy Agents:Generic oxaliplatin and capecitabine formulations dominate volume procurement through regional health service tenders.
- Radiopharmaceuticals:Diagnostic imaging agents for staging and response assessment see concentrated demand at nuclear medicine facilities in Antofagasta and Coquimbo.
Volume leadership belongs to Chemotherapy Agents. Steepest expansion trajectory is Immunotherapy.
End User:
Facility type determines procurement channel, reimbursement pathway, and patient complexity handled.
- Hospitals:Public oncology departments account for the majority of gastric cancer case volumes. The Explicit Health Guarantees program mandates treatment timelines, creating predictable demand patterns for approved therapies.
- Clinics:Private oncology centers in Concepción and Santiago capture patients seeking accelerated access to non-GES protocols and clinical trial enrollment.
- Outpatient Centers:Infusion facilities for stable patients receiving maintenance chemotherapy are expanding in the Metropolitan Region to decompress inpatient wards.
- Research Institutions:Academic medical centers at Universidad de Chile and Universidad de Concepción anchor immuno-oncology development programs.
Patient volume concentrates in Hospitals. Margin capture is strongest in Clinics.
Treatment Stage:
Disease extent at presentation shapes therapeutic intensity, curative intent, and palliative resource allocation.
- Early Stage:Endoscopic resection for T1a lesions and perioperative chemotherapy for locally advanced disease dominate curative protocols. Screening program gaps in rural provinces delay diagnosis.
- Advanced Stage:First-line systemic therapy with biomarker-directed selection is standard. PD-L1 and HER2 testing infrastructure in Valparaíso enables precision approaches.
- Palliative Care:Symptom management and best supportive care concentrate in regional hospitals lacking multidisciplinary tumor boards.
- Post-operative Care:Surveillance protocols and recurrence monitoring drive ongoing imaging and laboratory service demand.
Resource intensity peaks in Advanced Stage. Underservice is most acute in Palliative Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining revenues from the Atacama Desert and lithium extraction in the Salar de Atacama anchor northern Chile's capacity to fund specialized healthcare infrastructure. These resource-driven fiscal flows concentrate procurement authority in Santiago while creating geographic disparities in cancer care access.
Metropolitan Region
Santiago's Hospital Clínico Universidad de Chile and Instituto Nacional del Cáncer handle the majority of gastric cancer surgical volumes. Chile's Ministry of Health directs GES program implementation from the capital, standardizing reimbursement protocols across public oncology departments. The metropolitan cluster attracts referrals from six surrounding provinces, consolidating demand for trastuzumab and checkpoint inhibitors.
Valparaíso Region
Pathology laboratory expansion in Viña del Mar now supports routine HER2 and PD-L1 testing for patient selection. The regional health service participates in centralized tenders for platinum-fluoropyrimidine chemotherapy agents. Hospital Carlos Van Buren anchors multidisciplinary tumor board capacity for central Chile's coastal provinces.
Biobío Region
Concepción's private oncology clinics capture patients seeking accelerated access to non-GES protocols and clinical trial enrollment. Universidad de Concepción maintains academic medical center status for immuno-oncology development programs. Regional hospital networks here struggle with cold chain logistics for monoclonal antibody distribution.
Maule and Ñuble Regions
These central valley provinces report gastric cancer incidence above the national average with limited access to specialized surgical oncology. The Ministry of Health has designated these areas for telemedicine-enabled second opinion programs connecting regional hospitals to Santiago specialists. Workforce scarcity in medical oncology fellowship-trained clinicians constrains expansion of multidisciplinary care.
Chile Gastric Cancer Treatment Market Competitive Environment
Global biopharmaceutical majors compete with regional distribution specialists across procurement channel access and cold chain logistics capability. Market structure concentrates around sponsors with established Santiago-based affiliate operations and dedicated hospital pharmacy relationships. Three archetypes dominate: multinational innovators with HER2 and immuno-oncology portfolios, regional distributors managing temperature-controlled supply networks, and biosimilar developers targeting tender-driven chemotherapy substitution. Competitive moves center on GES protocol inclusion lobbying and pathology laboratory co-development partnerships.
Among Switzerland-based innovators, Roche anchors the targeted therapy segment through trastuzumab positioning. Bristol-Myers Squibb occupies the immuno-oncology development tier with checkpoint inhibitor programs aligned to Chile's clinical research infrastructure. AstraZeneca exemplifies the biomarker-driven selection archetype, matching therapeutic protocols to regional pathology capabilities. These three represent distinct competitive positioning vectors rather than interchangeable market presence.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb |
| AstraZeneca |
| Merck & Co. |
| Novartis AG |
| Pfizer |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries Ltd |
| Celltrion Inc. |
| Others |
Value Chain & Pricing Dynamics
Centralized regional tenders for platinum-fluoropyrimidine chemotherapy agents are compressing distributor margins and forcing biologics sponsors toward direct hospital pharmacy engagement. Chile's Ministry of Health procurement consolidation redirects supply relationships toward sponsors with established Santiago-based cold chain infrastructure.
Pricing Analysis
Warranty and service bundling separates branded biologics from unbundled generic chemotherapy agents in procurement negotiations. Three-tier pricing structure across premium HER2-directed monoclonal antibodies, standard checkpoint inhibitors, and economy generic cytotoxics reflects biomarker testing availability and GES reimbursement status. Pricing pressure stems from regional health service tender consolidation in Valparaíso and Biobío. Public hospital networks exhibit highest price sensitivity; private oncology clinics in Concepción demonstrate lowest sensitivity due to non-GES protocol access.
Supply Chain Analysis
Active pharmaceutical ingredient supply rests on manufacturing concentration in India and China for cytotoxic agents, with biologics fill-finish capacity anchored in Singapore and South Korea. Cold chain logistics for monoclonal antibodies hinge on temperature-controlled distribution networks from Santiago to regional hospital pharmacies. Single-source vulnerability concentrates in Asian API manufacturing hubs exposed to shipping lane volatility. Distribution runs through centralized regional health service tenders for public hospitals and direct manufacturer relationships for private clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over biomarker testing infrastructure and cold chain logistics determines competitive durability. Sponsors securing pathology laboratory partnerships gain preferential patient selection access.
For Market Incumbents: Anchor formulary positioning through embedded drug safety officers and dedicated hospital pharmacy relationships. Defend against biosimilar substitution by deepening biomarker testing co-development partnerships in Valparaíso and Biobío. Prioritize cold chain infrastructure investment in Antofagasta and La Araucanía to preempt regional distributor consolidation. For New Entrants and Emerging Players: Capture the Maule and Ñuble telemedicine-enabled second opinion channel where multidisciplinary tumor board access remains scarce. Target clinical trial enrollment infrastructure at Universidad de Concepción as the most penetrable entry point. Deploy biomarker-agnostic immuno-oncology protocols to bypass HER2 testing infrastructure gaps. For Investors and Strategic Acquirers: The window for entry favors regional distribution specialists with temperature-controlled logistics networks and established GES procurement relationships. Long-term viability hinges on sponsors' ability to secure pathology laboratory partnerships ahead of GES protocol expansion. Watch PD-L1 testing penetration rates in public hospital laboratories as the primary inflection signal for immunotherapy volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker Testing Infrastructure Partnership | Pathology laboratory co-development with Hospital Carlos Van Buren accelerates patient selection for targeted biologics. |
| Cold Chain Distribution Network Expansion | Temperature-controlled logistics investment in La Araucanía secures monoclonal antibody access for underserved provinces. |
| GES Protocol Inclusion Lobbying | Regulatory engagement with Chile's Ministry of Health creates predictable reimbursement for checkpoint inhibitors. |
| Clinical Trial Site Activation | ICH-GCP alignment at Universidad de Chile positions sponsors for immuno-oncology development programs. |
| Telemedicine Platform Integration | Remote consultation infrastructure connects Maule regional hospitals to Santiago-based multidisciplinary tumor boards. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, hospital procurement managers, formulary directors, and regulatory affairs specialists combined with ANVISA submissions, GES protocol documentation, and hospital procurement databases. Bottom-up therapeutic volume modeling and top-down healthcare expenditure triangulation validated segmentation outputs.
Granularity-level modeling operated at treatment modality, technology mechanism, and end-user facility type dimensions across the analysis window. CAGRs derived from historical GES expenditure patterns, biomarker testing expansion trajectories, and immunotherapy protocol adoption curves. Patient population epidemiology and regional health service procurement volumes informed forecast boundaries.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to GES coverage expansion timing and pathology laboratory certification bottlenecks. Forecasts reflect documented assumptions regarding biomarker testing infrastructure deployment and cold chain logistics investment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Digestive Health Market
Gastroenterology
Duodenal Ulcer Treatment Market
Gastroenterology
Global Gastrointestinal Bleeding Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Diverticular Disease Therapeutics Market
Gastroenterology
Gluten Intolerance Treatment Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Necrotic Enteritis Treatment Market
Gastroenterology
Gastroesophageal Junction Adenocarcinoma Therapeutics Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Malignant Ascites Market
Gastroenterology
Intestinal Pseudo-Obstruction Treatment Market
Gastroenterology
High Definition Ultrasound Gastroscope Market
Gastroenterology
Hyperemesis Gravidarum Treatment Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
Pouchitis Treatment Market