
 Hyperemesis Gravidarum Treatment Market | 2026-2036
Hyperemesis Gravidarum Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperemesis Gravidarum Treatment Market Analytics
Fixed-dose combination packaging is hardening as the preferred configuration for antiemetic therapy in hyperemesis gravidarum, bundling ondansetron with pyridoxine-doxylamine to reduce pill burden and improve adherence. Merck & Co., Inc. leverages its established antiemetic portfolio to anchor hospital formulary positioning. Pfizer Inc. competes through injectable formulation scale and cold-chain reliability. Bayer AG specializes in nutritional adjunct therapies that complement core pharmacological regimens.
Hyperemesis gravidarum treatment encompasses interventions targeting severe pregnancy-related nausea and vomiting, typically involving serotonin antagonists, antihistamines, corticosteroids, and fluid-electrolyte restoration administered via oral, intravenous, or transdermal routes; therapeutic efficacy hinges on gestational-stage-appropriate dosing and teratogenic risk stratification. Pharmacological modalities dominate current revenue pools, though intravenous delivery commands premium positioning due to emergency department dependency and inpatient monitoring requirements. Home care segments expand fastest as subcutaneous pump technologies and telemedicine protocols enable outpatient dehydration management.
FDA pregnancy labeling rules under the PLLR framework reshape clinical trial design and prescriber communication standards, while EMA pharmacovigilance directives across Europe impose post-market maternal-fetal safety monitoring obligations. The WHO essential medicines list inclusion criteria for antiemetics influence procurement patterns in low-resource settings. Stakeholders must monitor evolving teratogenicity data and regulatory divergence between stringent and emerging health authorities to align portfolio investments with shifting access pathways.
Market Dynamics
FDA pregnancy labeling reforms under the PLLR framework are compressing clinical trial timelines and forcing sponsors to restructure teratogenicity data collection protocols, fundamentally altering how antiemetic therapies reach prescribers.
Growth Catalysts
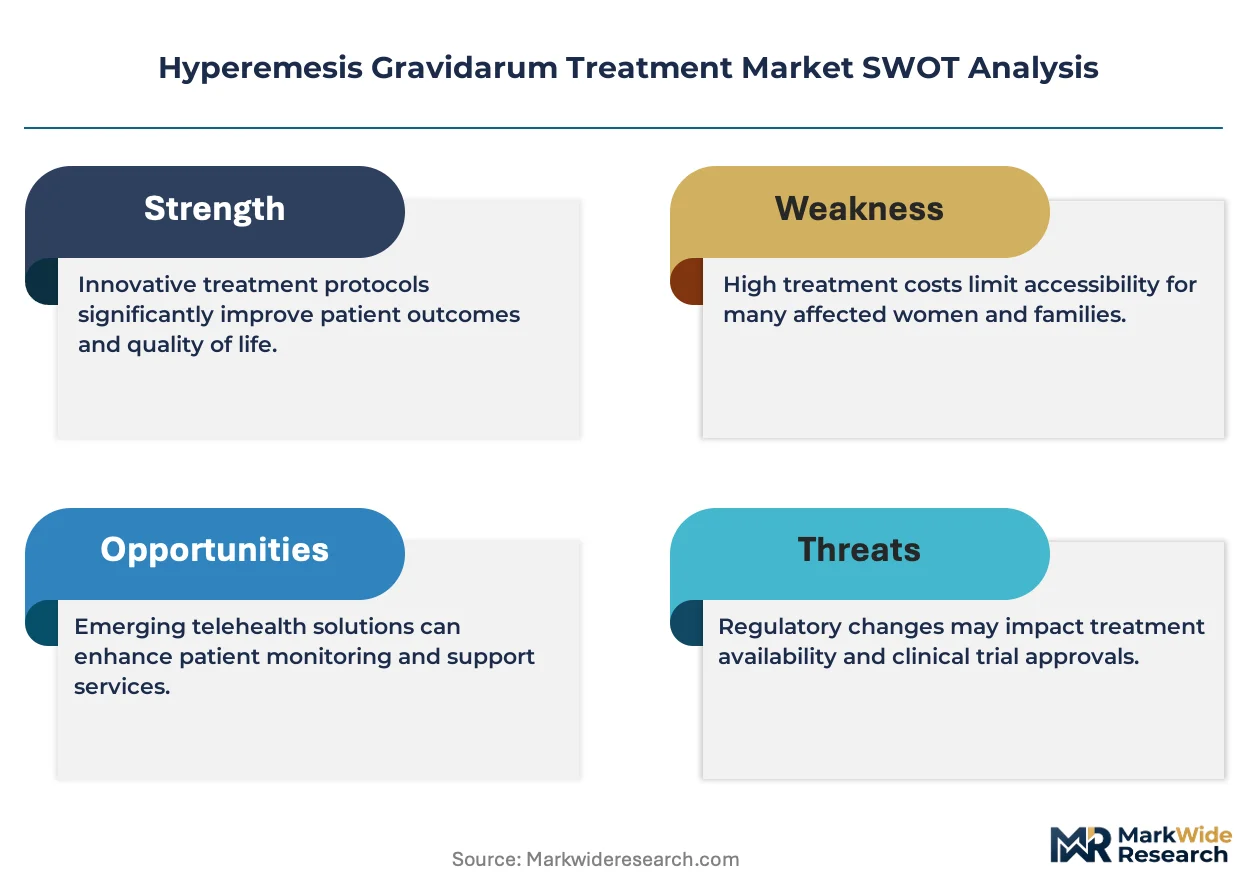
- PLLR Framework Implementation:The FDA's Pregnancy and Lactation Labeling Rule mandates standardized risk summaries, accelerating prescriber confidence in serotonin antagonist utilization during first-trimester care.
- Subcutaneous Pump Technology:Ambulatory infusion devices enable home-based fluid-electrolyte restoration, reducing emergency department dependency and expanding addressable patient populations.
- United States Maternal Health Infrastructure:Specialized nausea management protocols in tertiary care centers drive hospital formulary adoption of combination antiemetic therapies.
Market Restraints
- Teratogenicity Data Scarcity:Ethical constraints on enrolling pregnant patients in controlled trials limit the robustness of safety databases for newer pharmacological agents.
- Cold-Chain Distribution Costs:Injectable antiemetic formulations require continuous temperature monitoring, elevating logistics expenditure and constraining rural pharmacy stocking decisions.
- Generic Ondansetron Saturation:Patent expiration has flooded hospital procurement channels with low-cost alternatives, compressing branded product margin structures.
Strategic Opportunities
- Telemedicine Protocol Integration:Remote monitoring platforms enable real-time symptom tracking, creating subscription revenue streams alongside pharmaceutical sales.
- Nutritional Adjunct Positioning:Micronutrient repletion therapies address thiamine and electrolyte deficiencies, capturing ancillary spend adjacent to core antiemetic regimens.
- WHO Essential Medicines List Inclusion:Antiemetic procurement criteria for low-resource settings open institutional purchasing pathways in Sub-Saharan African and South Asian markets.
Industry Challenges
- Maternal-Fetal Medicine Specialist Shortage:Limited fellowship-trained physicians constrain prescriber education and protocol standardization across community hospital networks.
- EMA Pharmacovigilance Compliance Burden:Post-market safety monitoring obligations impose data infrastructure costs that disproportionately affect mid-cap sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperemesis Gravidarum Treatment Market |
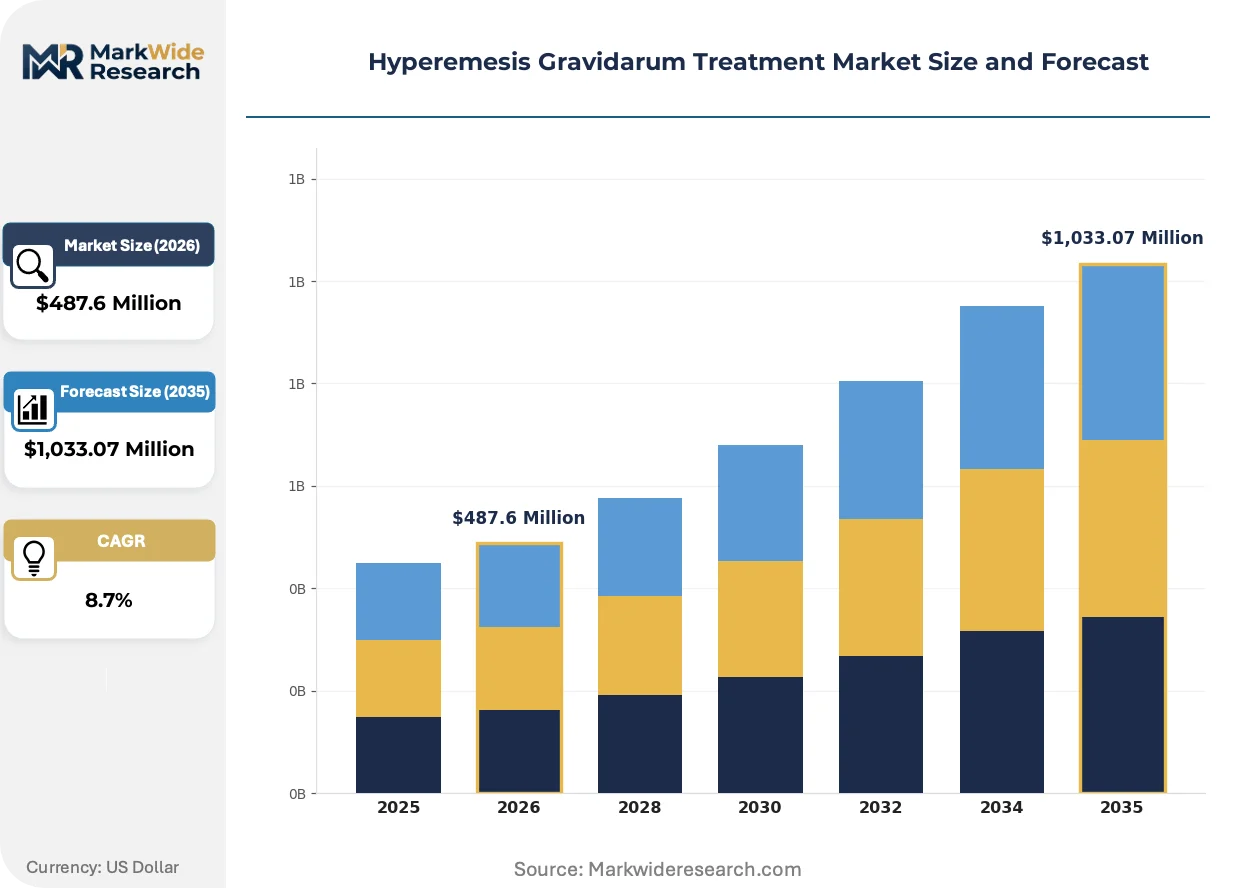
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmacological, Nutritional Support, Homeopathic, Herbal Remedies Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Maternity Clinics, Home Care, Rehabilitation Centers Usage Frequency: Daily, Weekly, As Needed, Periodic |
| Companies Covered | Merck & Co., Inc., Bristol-Myers Squibb Company, Johnson & Johnson, NGM Bio, Bayer AG, Pfizer Inc., Biogen, Shionogi & Co., Ltd., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperemesis Gravidarum Treatment Market Evolving Landscape
Fixed-dose combination packaging and ambulatory delivery technologies are compressing site-of-care requirements, enabling patient-managed therapy outside traditional inpatient settings.
Transdermal antiemetic delivery systems are expanding into hyperemesis gravidarum management through controlled-release scopolamine and granisetron patches. Obstetric emergency departments in the United States and Germany are piloting these modalities for patients with refractory vomiting. The technology is expanding into home care protocols by eliminating intravenous access requirements and reducing nursing labor intensity.
EMA pharmacovigilance directives now mandate prospective maternal-fetal outcome registries for all newly approved antiemetics used in pregnancy. Drug sponsors must establish independent safety boards and submit quarterly cumulative reviews. Hospital pharmacy committees across France, Italy, and Spain are delaying formulary additions until 18-month post-launch safety data accumulates.
Hospital-at-home reimbursement codes in the United States now cover subcutaneous antiemetic infusion and remote hydration monitoring. Obstetric practices are unbundling emergency department services into discrete home-based episodes. This shift is most visible in California and Texas, where Medicaid managed care organizations have authorized per-diem payments for outpatient hyperemesis management.
Hyperemesis Gravidarum Treatment Market Segmentation
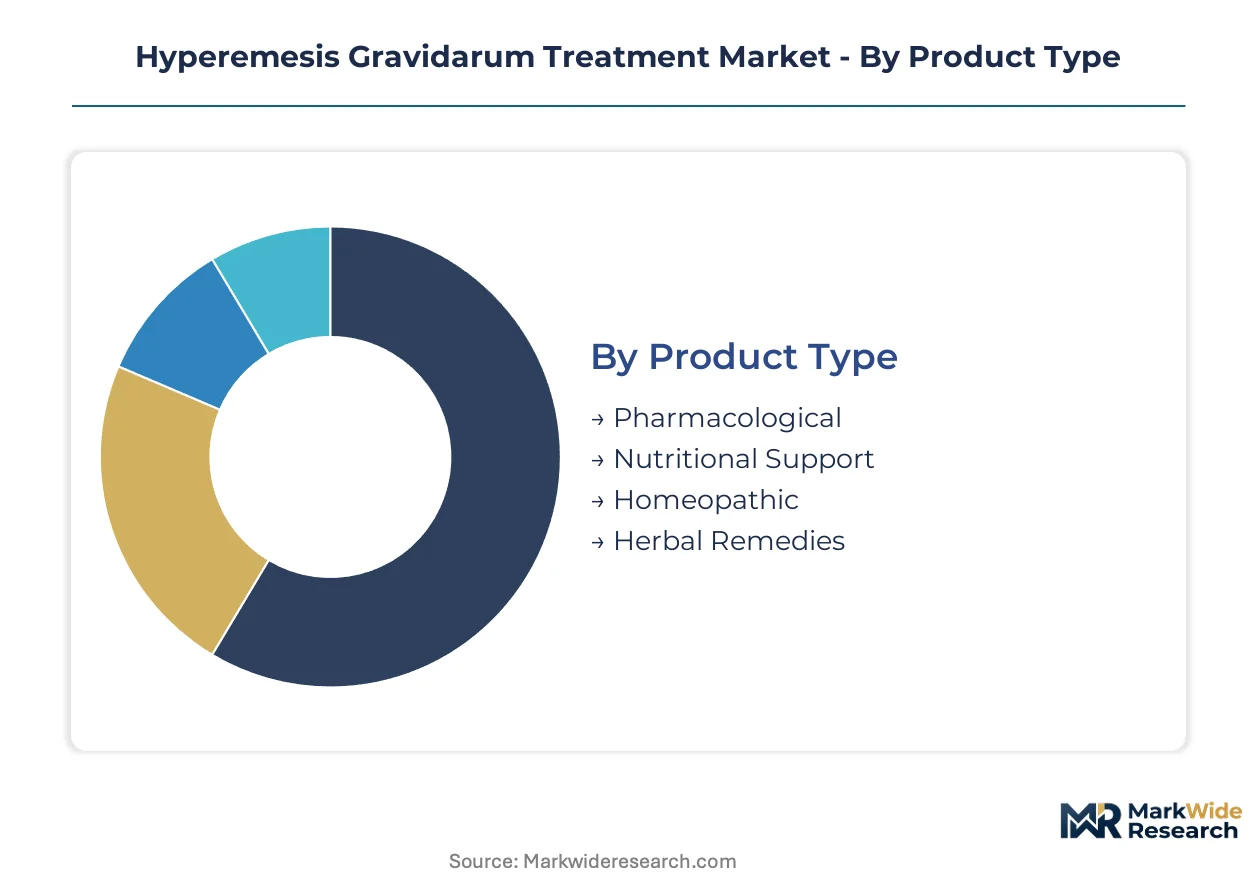
Segmentation in hyperemesis gravidarum treatment reveals how clinical severity, care setting economics, and patient mobility constraints shape procurement patterns across pharmacological and non-pharmacological modalities. Understanding these divisions enables stakeholders to align formulation development with site-of-care reimbursement codes and patient adherence profiles.
Product Type:
Replacement cycles in hyperemesis gravidarum therapy accelerate as fixed-dose combinations displace standalone generics and nutritional protocols expand beyond acute rescue into maintenance regimens.
- Pharmacological:Serotonin antagonists, antihistamines, and corticosteroids constitute the core therapeutic arsenal, with ondansetron-pyridoxine-doxylamine combinations commanding hospital formulary preference due to PLLR-aligned labeling and reduced pill burden. Demand concentrates in United States tertiary care centers where maternal-fetal medicine specialists drive protocol standardization.
- Nutritional Support:Thiamine repletion, electrolyte restoration, and parenteral nutrition address dehydration sequelae and Wernicke encephalopathy prevention. Home care segments in California and Texas are adopting ambulatory infusion protocols that bundle nutritional adjuncts with antiemetic delivery, creating subscription-based revenue models alongside pharmaceutical sales.
- Homeopathic:Diluted preparations targeting nausea triggers through alternative therapeutic frameworks, with adoption concentrated among patient populations seeking non-pharmacological first-line options.
- Herbal Remedies:Ginger-based formulations and peppermint derivatives serve as over-the-counter adjuncts, though teratogenicity data gaps limit prescriber endorsement in formal clinical pathways.
Pharmacological modalities sit at the top of the volume ranking, with nutritional support climbing the fastest as hospital-at-home reimbursement codes expand coverage for outpatient hydration management.
Delivery Mode:
Cost tier stratification across delivery modes separates premium intravenous hospital administration from economy oral generics and mid-tier subcutaneous pump systems that bridge acute and ambulatory care.
- Oral:First-line administration for mild-to-moderate symptoms, encompassing tablet, capsule, and dissolvable film formulations. Generic ondansetron saturation has compressed margin structures, driving branded manufacturers toward fixed-dose combination packaging to defend positioning.
- Injectable:Intramuscular and subcutaneous routes enable rapid symptom control when oral intake is compromised, with cold-chain reliability requirements elevating logistics expenditure and constraining rural pharmacy stocking decisions.
- Intravenous:Emergency department and inpatient settings depend on IV antiemetics and fluid-electrolyte restoration for severe dehydration, commanding premium reimbursement due to monitoring intensity and site-of-care infrastructure.
- Transdermal:Controlled-release scopolamine and granisetron patches eliminate vascular access requirements, with pilot programs in United States and German obstetric emergency departments expanding into home care protocols to reduce nursing labor intensity.
Intravenous delivery dominates acute revenue pools, though transdermal systems are gaining share fastest as patient-managed therapy outside traditional inpatient settings compresses site-of-care requirements.
End User:
Customer type fragmentation separates high-acuity hospital episodes from recurring maternity clinic visits and emerging home care subscriptions that unbundle emergency department services into discrete outpatient episodes.
- Hospitals:Tertiary care centers and community hospital networks manage severe hyperemesis gravidarum through emergency department admission and inpatient monitoring, with specialized nausea management protocols driving formulary adoption of combination antiemetic therapies.
- Maternity Clinics:Outpatient obstetric practices provide first-line assessment and moderate symptom management, serving as gatekeepers to hospital escalation and maintaining longitudinal patient relationships across gestational stages.
- Home Care:Ambulatory infusion services and telemedicine-enabled remote monitoring enable subcutaneous antiemetic delivery and hydration management outside institutional settings, with Medicaid managed care organizations in California and Texas authorizing per-diem payments for outpatient protocols.
- Rehabilitation Centers:Post-acute facilities address nutritional recovery and functional restoration following prolonged hyperemesis episodes, though penetration remains limited compared to acute and ambulatory channels.
Hospitals retain the highest episode volume, with home care expanding most quickly as subcutaneous pump technologies and reimbursement code evolution enable patient-managed therapy.
Usage Frequency:
Maturity differentiation across frequency patterns separates established daily prophylactic regimens from emerging as-needed rescue protocols that align dosing with symptom fluctuation rather than fixed schedules.
- Daily:Scheduled administration for persistent symptoms, typical of first-trimester prophylaxis with pyridoxine-doxylamine combinations and corticosteroid tapering protocols.
- Weekly:Intermittent dosing for cyclical symptom patterns or maintenance following acute resolution, common in subacute management transitions.
- As Needed:Rescue dosing triggered by breakthrough vomiting, requiring rapid-onset formulations and patient education on threshold recognition to prevent dehydration escalation.
- Periodic:Situational administration tied to identified triggers such as travel, stress events, or dietary exposures, with demand concentrated among patients with predictable symptom patterns.
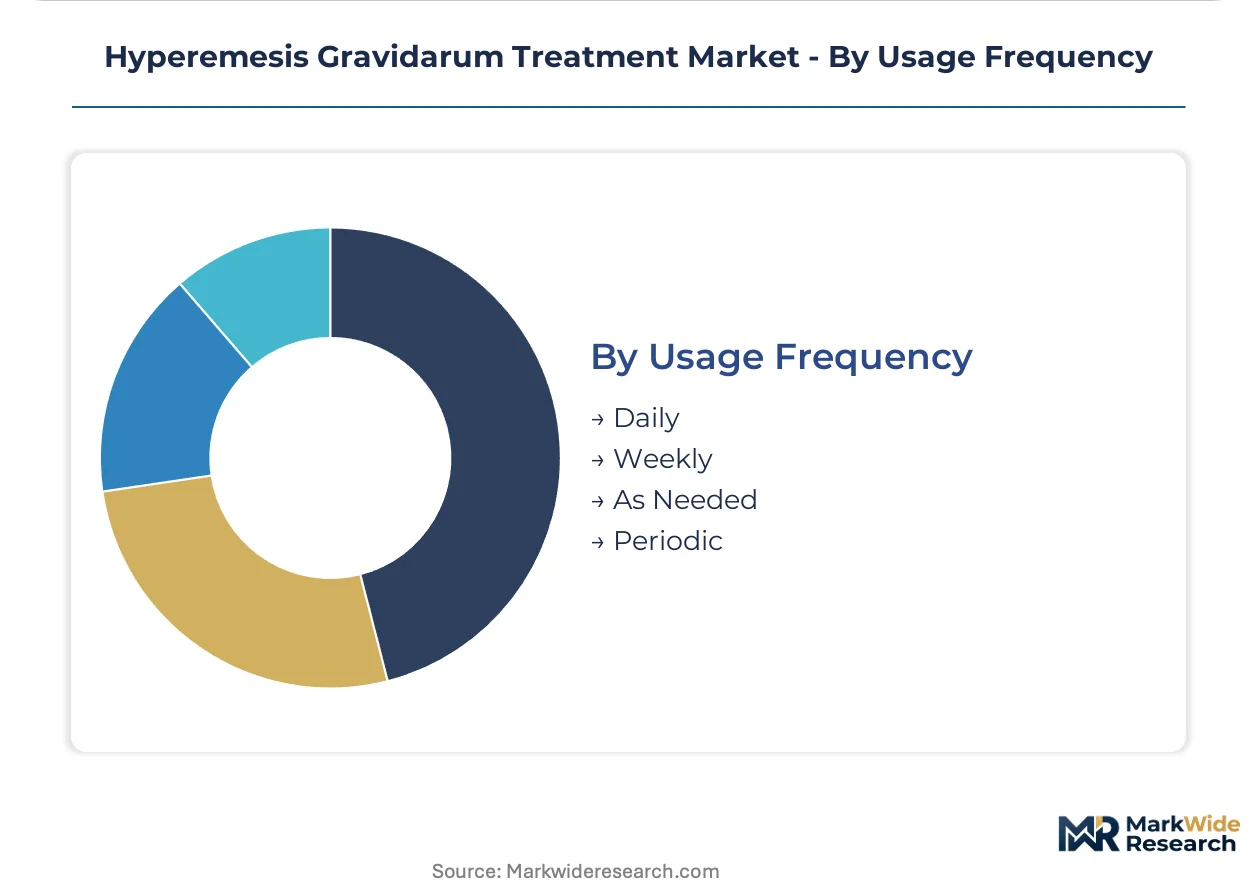
Daily regimens anchor prescription volume, with as-needed protocols showing the steepest expansion trajectory as fixed-dose combinations and subcutaneous rescue systems improve patient-directed management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hyperemesis gravidarum treatment industry traces its clinical foundations to mid-20th century obstetric research in the United Kingdom, where standardized antiemetic protocols first achieved widespread adoption before spreading to North American and Continental European healthcare systems.
United States
FDA PLLR framework implementation drives prescriber confidence in serotonin antagonist utilization during first-trimester care. Medicaid managed care organizations in California and Texas now authorize per-diem payments for outpatient hyperemesis management. The Greater Boston corridor hosts specialized maternal-fetal medicine research centers advancing subcutaneous pump protocols.
Germany
EMA pharmacovigilance directives mandate prospective maternal-fetal outcome registries for all newly approved antiemetics used in pregnancy. Hospital pharmacy committees across France, Italy, and Spain delay formulary additions until post-launch safety data accumulates. Bavarian obstetric emergency departments pilot transdermal granisetron patches for refractory vomiting cases.
United Kingdom
NHS specialized nausea management protocols in tertiary care centers drive formulary adoption of combination antiemetic therapies. The country's national pharmaceutical regulator aligns pregnancy labeling standards with European maternal-fetal safety monitoring obligations. London-based research institutions coordinate multicenter trials on ambulatory infusion technologies.
Japan
PMDA pregnancy drug labeling requirements reshape clinical trial design for obstetric antiemetics entering the Asian market. Metropolitan Tokyo hospitals integrate telemedicine-enabled remote monitoring for subcutaneous antiemetic delivery. Osaka-Kansai medical device manufacturers supply precision pump systems for home-based fluid-electrolyte restoration.
Australia
TGA pharmacovigilance protocols impose post-market maternal-fetal safety monitoring obligations on antiemetic sponsors. New South Wales and Victoria lead hospital-at-home reimbursement code expansion covering remote hydration monitoring. Sydney-based obstetric practices unbundle emergency department services into discrete home-based episodes.
Hyperemesis Gravidarum Treatment Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established antiemetic portfolios. Market concentration remains moderate, with hospital formulary positioning serving as the primary battleground for revenue capture. Two strategic archetypes dominate: legacy manufacturers leveraging injectable formulation scale and cold-chain reliability, and nutritional therapy specialists bundling micronutrient repletion with core pharmacological regimens. Competitive moves center on fixed-dose combination packaging development and telemedicine protocol integration to capture subscription revenue streams.
Among North American pharmaceutical conglomerates, Merck & Co., Inc. and Pfizer Inc. occupy positions anchored by hospital formulary relationships and injectable manufacturing infrastructure. Bayer AG exemplifies the nutritional adjunct archetype, complementing core antiemetic regimens with thiamine and electrolyte restoration therapies. Shionogi & Co., Ltd. represents the Asia-Pacific specialist contingent, while Novartis AG and Bristol-Myers Squibb Company sit within the diversified therapeutic portfolio tier competing across multiple obstetric indications.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| NGM Bio |
| Bayer AG |
| Pfizer Inc. |
| Biogen |
| Shionogi & Co., Ltd. |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Active pharmaceutical ingredient spot indices for ondansetron and granisetron cascade through three distinct pricing tiers, with cold-chain logistics costs amplifying spreads between hospital-grade injectables and oral generic alternatives. Procurement managers at United States health systems negotiate volume rebates against escalating temperature-controlled distribution expenditures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates patented fixed-dose combinations from branded single-agent therapies and commoditized ondansetron generics. Price differentiation hinges on FDA PLLR-aligned labeling tier and cold-chain reliability certification. Cost compression in the economy tier intensifies because patent expiration has flooded procurement channels with low-cost alternatives. Community hospital networks exhibit highest price sensitivity, while tertiary care maternal-fetal medicine centers prioritize formulation stability over acquisition cost.
Supply Chain Analysis
API supply for serotonin antagonists rests on Indian and Chinese specialty chemical manufacturers, with formulation finishing concentrated in United States and German pharmaceutical facilities. Finished dose production draws from pyridoxine-doxylamine precursor streams and sterile injectable capacity. Single-source vulnerability in scopolamine transdermal patch substrates creates procurement risk for emerging patch-based therapies. Distribution runs through hospital GPO contracts and specialty pharmacy channels serving home infusion services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA PLLR framework implementation compounds regulatory validation into commercial advantage, accelerating prescriber confidence and formulary access for compliant therapies. This regulatory milestone creates durable demand asymmetry between labeled and unlabeled antiemetic alternatives.
For Market Incumbents: Extend formulary positioning through fixed-dose combination packaging that bundles ondansetron with pyridoxine-doxylamine, defending against generic ondansetron saturation. Deepen backward integration into parenteral nutrition manufacturing to capture ancillary spend adjacent to core antiemetic regimens. Threat exposure concentrates in subcutaneous pump technology entrants unbundling emergency department services into home-based episodes.
For New Entrants and Emerging Players: Launch via telemedicine-enabled remote monitoring platforms that enable real-time symptom tracking and subscription revenue streams alongside pharmaceutical sales. White-space targets include Medicaid managed care organizations in California and Texas authorizing per-diem outpatient hyperemesis management, and WHO Essential Medicines List procurement pathways in Sub-Saharan African markets. Go-to-market angle centers on hospital-at-home reimbursement code compliance.
For Investors and Strategic Acquirers: Asymmetric upside sits with nutritional adjunct therapy specialists bundling thiamine repletion and electrolyte restoration with core pharmacological regimens. Long-term viability over the projection horizon favors sponsors with established maternal-fetal safety databases and EMA pharmacovigilance compliance infrastructure. Acquisition target archetype: mid-cap firms with subcutaneous pump technology and telemedicine protocol integration. Signal to watch: quarterly cumulative safety review submissions to European regulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Development | PLLR-aligned labeling reduces pill burden and secures hospital formulary preference. |
| Subcutaneous Pump Manufacturing Scale-Up | Ambulatory infusion devices expand addressable patient populations beyond emergency departments. |
| Telemedicine Protocol Integration | Remote monitoring platforms create subscription revenue streams alongside pharmaceutical sales. |
| WHO Essential Medicines List Inclusion | Antiemetic procurement criteria open institutional purchasing pathways in low-resource settings. |
| EMA Pharmacovigilance Compliance Infrastructure | Prospective maternal-fetal outcome registries satisfy post-market safety monitoring obligations. |
Research Methodology
Direct dialogue with maternal-fetal medicine specialists, hospital formulary directors, pharmaceutical regulatory affairs leads, and Medicaid managed care pharmacy benefit managers grounded qualitative insights. Secondary validation drew from FDA PLLR filings, EMA pharmacovigilance directives, ClinicalTrials.gov obstetric antiemetic protocols, and hospital GPO contract databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Bottom-up treatment episode enumeration by severity grade, delivery mode, and care setting anchored volume projections across the analysis window. Segmentation dimensions encompassed pharmacological modality, administration route, end-user facility type, and regional regulatory cluster. CAGRs derived from longitudinal formulary adoption curves and reimbursement code expansion trajectories. Forecast inputs incorporated subcutaneous pump technology penetration rates and telemedicine protocol reimbursement authorization patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA pharmacovigilance directive stringency shifts and maternal-fetal medicine specialist supply constraints. Forecasts reflect assumptions regarding PLLR framework stability and hospital-at-home reimbursement code permanence. Teratogenicity data scarcity and generic ondansetron pricing dynamics warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gastroenterology
Gastroretentive Drug Delivery Systems Outsourcing Market
Gastroenterology
Peptic Ulcer Market
Gastroenterology
Inflammatory Bowel Disease Treatment Market
Gastroenterology
Chronic Liver Diseases Therapeutics Market
Gastroenterology
US Gastroenterology Ambulatory Surgery Center Market
Gastroenterology
Hirschsprung Disease Treatment Market
Gastroenterology
Inflammatory Bowel Disease Market
Gastroenterology
Digestive Health Products Market
Gastroenterology
Intestinal Fistula Treatment Market
Gastroenterology
Gastritis Treatment Market
Gastroenterology
US Inflammatory Bowel Disease Treatment Market
Gastroenterology
Acute Pancreatitis Market
Gastroenterology
Polyps Market
Gastroenterology
Anal Fissure Treatment Market
Gastroenterology
Helicobacter Pylori Infections Treatment Market
Gastroenterology
Ulcerative Colitis (UC) Treatment Market