
 Chemical Processing Catalysts Market | 2026-2036
Chemical Processing Catalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Processing Catalysts Market Outlook
Specialty chemical manufacturers is reorganizing procurement priorities toward high-selectivity catalyst systems for fine chemical synthesis. BASF SE leverages its integrated catalyst-petrochemical technology platform to anchor long-term supply relationships with European refiners. Johnson Matthey competes through its hydrogenation and dehydrogenation expertise, while Haldor Topsoe dominates syngas and ammonia catalyst supply for energy sector clients.
Chemical processing catalysts are substances that accelerate reaction rates without permanent consumption, typically comprising supported metals, metal oxides, or molecular sieves manufactured through precipitation, impregnation, or sol-gel methods, and function primarily to improve yield, selectivity, and energy efficiency in industrial chemical transformations. Heterogeneous catalysts occupy the largest installed base across petrochemical crackers and refinery hydroprocessing units due to their separability and thermal stability. Biocatalysts represent the fastest-expanding product category as enzymatic processes displace traditional chemocatalysis in pharmaceutical intermediate production, while environmental applications command premium pricing tied to sulfur recovery and emissions control mandates.
EPA regulations under the Clean Air Act and REACH registration requirements in Europe are tightening permissible emissions thresholds, directly expanding retrofit demand for environmental application catalysts in refinery and chemical plant flue gas treatment. China's MEE enforces dual carbon compliance timelines that redirect capital toward lower-carbon catalytic processes in new petrochemical builds. Stakeholders must weigh R&D allocation between mature heterogeneous platforms and emerging biocatalyst portfolios as regulatory chemistry constraints diverge across North America, Europe, and Asia.
Market Dynamics
Dual carbon compliance timelines in China are redirecting capital flows toward lower-carbon catalytic processes, while specialty chemical manufacturers simultaneously reorganize procurement priorities around high-selectivity systems for fine chemical synthesis. This regulatory-industrial convergence is compressing legacy technology lifecycles and reshaping supplier-customer contracting structures.
Growth Catalysts
- REACH Registration Requirements:Tightening permissible emissions thresholds across European chemical plants is expanding retrofit demand for environmental application catalysts in refinery flue gas treatment systems.
- China's Petrochemical Capacity Expansion:State-directed investment in ethylene and propylene derivative complexes under MEE dual carbon enforcement is concentrating catalyst demand in coastal manufacturing clusters.
- Biocatalytic Process Platforms:Enzymatic displacement of traditional chemocatalysis in pharmaceutical intermediate production is creating new catalyst procurement categories with premium pricing structures.
Market Restraints
- Platinum Group Metal Price Volatility:Rhodium and palladium cost swings embedded in hydrogenation catalyst formulations are compressing margin predictability for catalyst manufacturers and end-users alike.
- Supply Concentration in Rare Earth Processing:China's dominance in lanthanide separation and refining creates chokepoint risk for fluid catalytic cracking catalyst supply chains serving North American refiners.
- Technical Limitation in High-Temperature Stability:Molecular sieve degradation above 650°C in steam environments restricts catalyst regeneration cycles in heavy oil upgrading units.
Strategic Opportunities
- India's Specialty Chemical Manufacturing Push:PLI scheme incentives for active pharmaceutical ingredient and agrochemical intermediate production are opening catalyst procurement relationships with domestic fine chemical producers.
- Carbon Capture Integration:Syngas catalyst systems paired with post-combustion carbon capture retrofits represent an emerging application category for ammonia and methanol plant operators.
- EPA Clean Air Act Tier 3 Alignment:Stricter sulfur content mandates in transportation fuels are accelerating sulfur recovery catalyst replacement cycles in US Gulf Coast refining complexes.
Industry Challenges
- Computational Catalysis Talent Scarcity:Shortage of professionals combining density functional theory expertise with industrial reactor engineering is delaying rational catalyst design pipelines.
- Multi-Jurisdictional Certification Timelines:Divergent EPA, REACH, and MEE approval pathways for novel catalyst formulations are extending commercialization cycles by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Processing Catalysts Market |
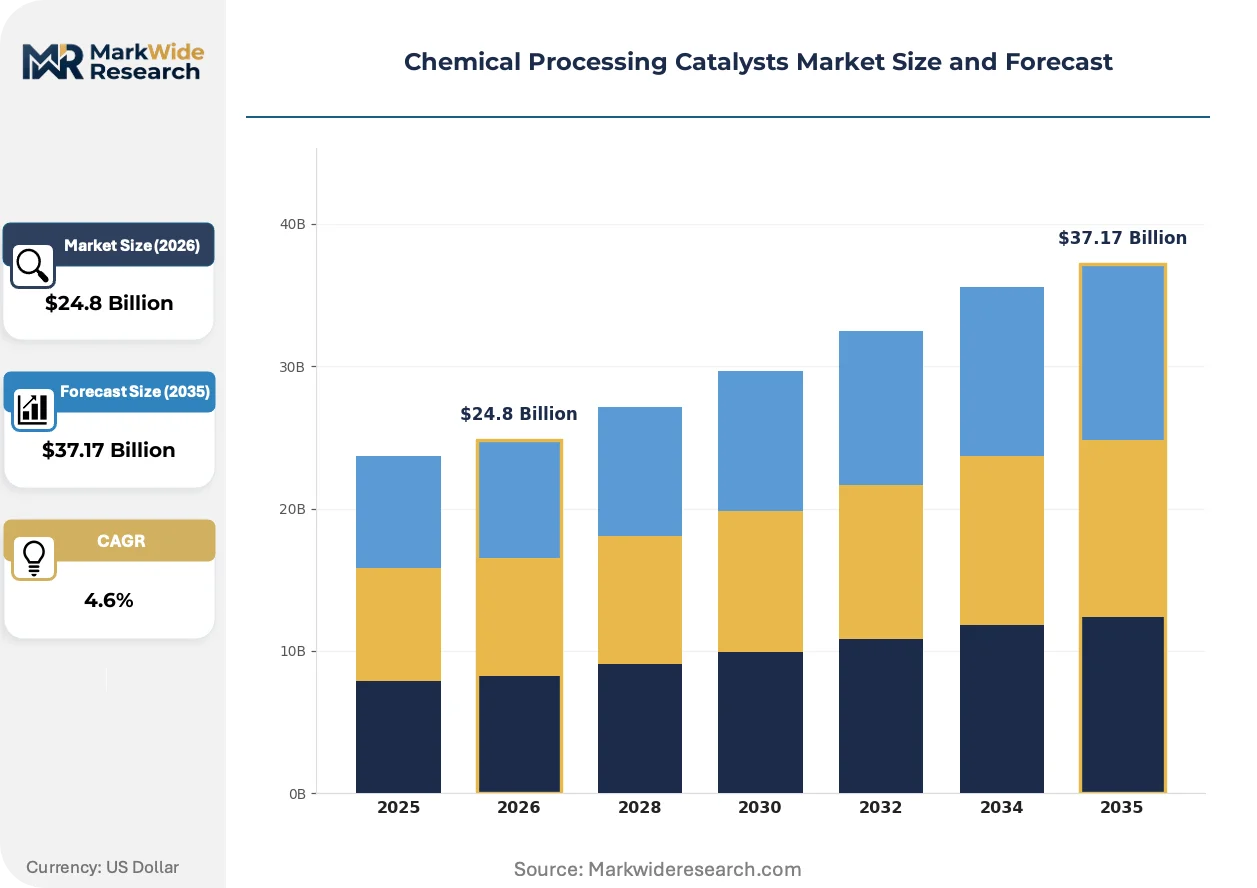
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $37.17 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heterogeneous Catalysts, Homogeneous Catalysts, Biocatalysts, Nanocatalysts Application: Petrochemical Production, Fine Chemicals, Polymer Production, Environmental Applications End User: Pharmaceuticals, Food & Beverage, Agriculture, Energy Distribution Channel: Online Retail, Direct Sales, Distributors, Others |
| Companies Covered | BASF SE, Johnson Matthey, Clariant, Albemarle Corporation, W. R. Grace & Co., Haldor Topsoe, Honeywell UOP, Evonik Industries, Axens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Processing Catalysts Market Strategic Shifts
Computational materials science and high-throughput experimentation are compressing catalyst development cycles, while regulatory chemistry constraints diverge across major manufacturing geographies. These forces are fragmenting technology roadmaps and rewarding modular, adaptable catalyst platforms.
Single-atom catalysis is supplanting traditional nanoparticle formulations in selective hydrogenation applications. Pharmaceutical manufacturers are adopting these systems at pilot scale within 18-month procurement cycles. The technology is supplanting established precious metal loadings and enabling continuous flow reactor designs that reduce solvent waste.
China's MEE enforcement of dual carbon compliance timelines is mandating lower-carbon intensity benchmarks for new petrochemical builds. This regulatory pressure is redirecting capital toward catalytic processes with superior carbon efficiency per unit output. Syngas-to-olefins and methanol-to-olefins catalyst systems are capturing disproportionate investment in Ningbo and Dalian chemical clusters.
Long-term catalyst leasing arrangements with performance guarantees are displacing traditional equipment purchase models in European refining. Maintenance service unbundling from catalyst supply is disrupting established distributor relationships. Germany's KBA emissions certification requirements are accelerating this shift by tying catalyst performance to operational permit compliance.
Chemical Processing Catalysts Market Segmentation
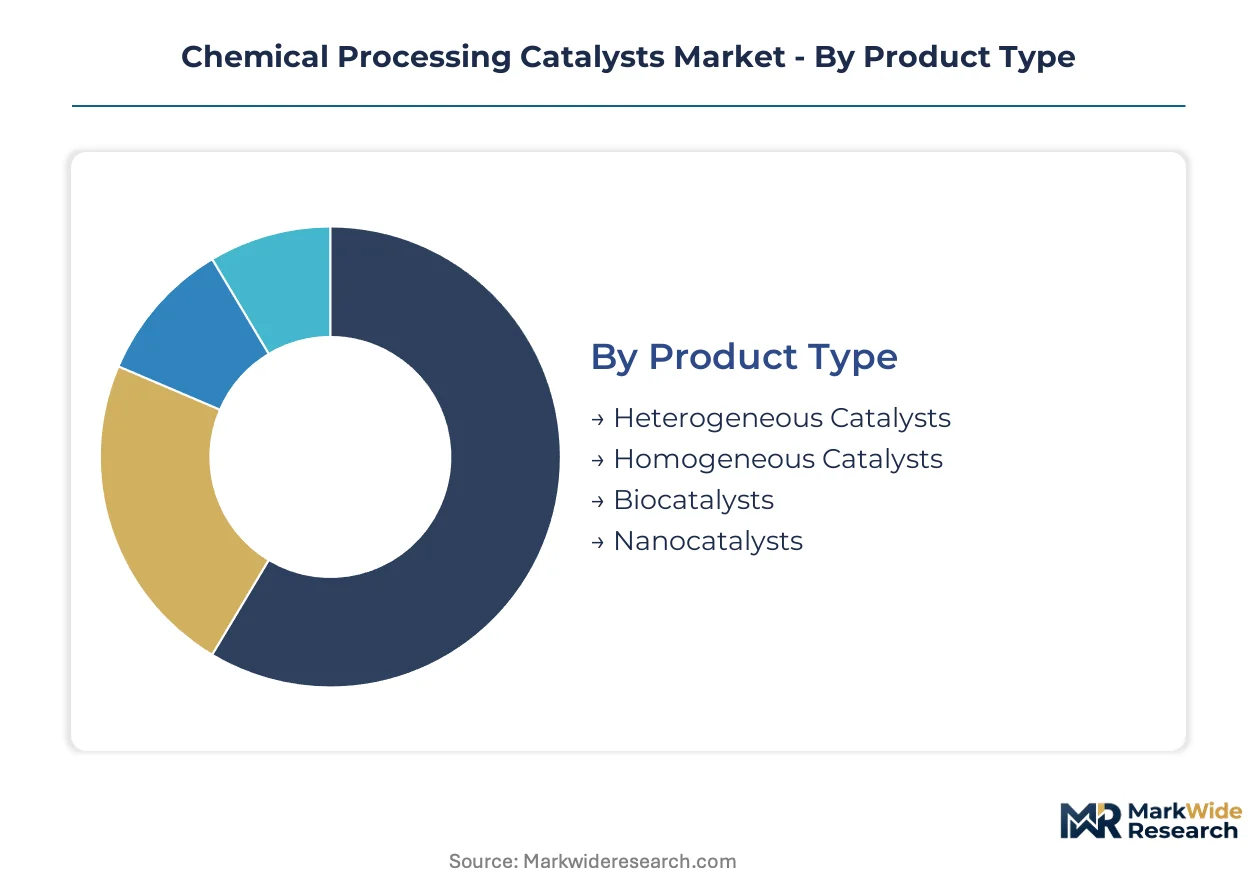
Catalyst selection determines regulatory compliance pathways and capital efficiency across chemical processing value chains. Segmentation reveals how heterogeneous platforms dominate installed capacity while biocatalysts capture premium procurement in pharmaceutical applications.
Product Type:
EPA Tier 3 sulfur mandates and REACH registration timelines differentiate catalyst procurement between refiners seeking regeneration cycles and pharmaceutical manufacturers prioritizing selectivity.
- Heterogeneous Catalysts:Supported metal and metal oxide formulations on alumina or zeolite carriers enable separation from reaction mixtures and thermal stability above 500°C. Demand concentrates in US Gulf Coast hydroprocessing units where EPA Clean Air Act compliance drives sulfur recovery catalyst replacement cycles.
- Biocatalysts:Enzyme-based systems derived from engineered microorganisms deliver stereoselectivity unattainable through chemocatalysis. Procurement is accelerating in Swiss and German pharmaceutical corridors where EMA quality guidelines favor enzymatic routes for active pharmaceutical intermediate production.
- Homogeneous Catalysts:Soluble metal complexes in liquid phase operate in fine chemical batch reactors requiring precise temperature control.
- Nanocatalysts:Sub-10nm particle architectures maximize surface area-to-volume ratios in emerging electrochemical applications.
Established volume favors heterogeneous platforms; emerging adoption favors biocatalysts.
Application:
Capital intensity and emissions exposure shape application-level procurement, with environmental mandates compressing technology lifecycles in flue gas treatment.
- Petrochemical Production:Fluid catalytic cracking and steam reforming catalysts process feedstocks into ethylene, propylene, and aromatics. China's MEE dual carbon enforcement redirects investment toward methanol-to-olefins systems in Ningbo and Dalian chemical clusters.
- Environmental Applications:Selective catalytic reduction and sulfur recovery catalysts neutralize NOx and SOx emissions from combustion processes. Retrofit demand is climbing in German refineries where KBA emissions certification ties catalyst performance to operational permit compliance.
- Fine Chemicals:High-selectivity systems enable complex multi-step syntheses for agrochemical and pharmaceutical precursors.
- Polymer Production:Ziegler-Natta and metallocene catalysts control molecular weight distribution in polyolefin manufacturing.
Regulatory retrofit cycles dominate environmental applications; process efficiency gains drive petrochemical procurement.
End User:
Risk tolerance and batch scale differentiate end-user procurement, with pharmaceutical buyers prioritizing certification over unit cost.
- Pharmaceuticals:cGMP-compliant catalyst systems require validated impurity profiles and traceable manufacturing records. US FDA and EMA chemistry manufacturing controls favor enzymatic processes for chiral intermediate production.
- Energy:Syngas and ammonia catalysts operate in continuous high-throughput environments where thermal stability determines regeneration economics. Haldor Topsoe and Johnson Matthey anchor long-term supply relationships with ammonia plant operators.
- Food & Beverage:Lipase and protease biocatalysts enable interesterification and protein hydrolysis under FSSAI and FDA food contact regulations.
- Agriculture:Fertilizer and pesticide intermediate production consumes base metal catalysts in high-volume commodity processes.
Pharmaceutical procurement commands premium pricing; energy sector procurement emphasizes throughput reliability.
Distribution Channel:
Service bundling and technical support requirements fragment channel structure, with performance guarantees displacing transactional purchasing.
- Direct Sales:Integrated catalyst-petrochemical technology platforms enable BASF SE and Clariant to anchor long-term supply relationships with European refiners through performance-based contracting.
- Distributors:Regional inventory positioning serves mid-scale fine chemical manufacturers requiring rapid catalyst replacement and technical troubleshooting.
- Online Retail:Catalog platforms facilitate standard catalyst procurement for research-scale and pilot-plant operations.
- Others:Leasing arrangements with maintenance unbundling are emerging in German refining under KBA emissions certification requirements.
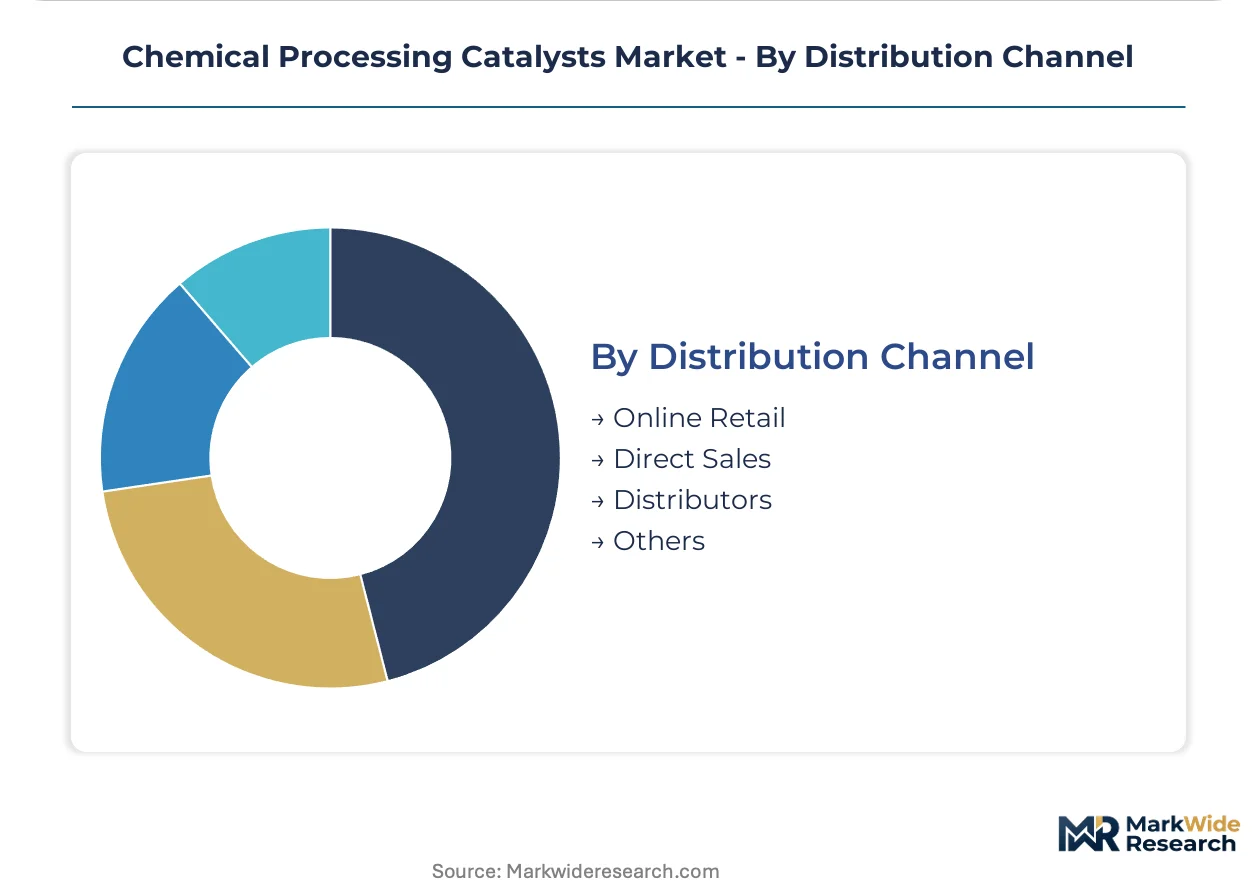
Direct sales capture high-value refinery contracts; distributor networks serve fragmented specialty chemical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refinery operators and specialty chemical manufacturers concentrate procurement decisions in jurisdictions with the strictest emissions enforcement and largest petrochemical capacity additions.
United States
EPA Clean Air Act Tier 3 sulfur mandates drive sulfur recovery catalyst replacement cycles across Gulf Coast refining complexes. The agency's tightening permissible emissions thresholds expand retrofit demand for environmental application catalysts in flue gas treatment systems. Houston and Corpus Christi anchor concentrated procurement activity where refinery operators negotiate performance-based catalyst contracts.
Germany
KBA emissions certification requirements tie catalyst performance directly to operational permit compliance for domestic refiners. REACH registration timelines and ECHA enforcement accelerate demand for environmental application catalysts in chemical plant flue gas treatment. The Rhine-Ruhr industrial corridor hosts the densest cluster of catalyst leasing arrangements with unbundled maintenance services.
China
MEE dual carbon enforcement redirects capital toward methanol-to-olefins and syngas-to-olefins systems in new petrochemical builds. State-directed investment in ethylene and propylene derivative complexes concentrates catalyst demand in coastal manufacturing clusters. Ningbo and Dalian chemical infrastructure captures disproportionate catalyst procurement volume under lower-carbon intensity benchmarks.
India
PLI scheme incentives for active pharmaceutical ingredient and agrochemical intermediate production open catalyst procurement relationships with domestic fine chemical producers. CDSCO and FSSAI quality guidelines favor enzymatic routes that accelerate biocatalyst adoption in pharmaceutical corridors. Gujarat and Maharashtra host expanding specialty chemical manufacturing clusters where high-selectivity catalyst systems command premium positioning.
Saudi Arabia
SABIC-affiliated petrochemical complexes drive continuous demand for fluid catalytic cracking and steam reforming catalysts in high-throughput environments. The national hydrocarbon regulator enforces emissions benchmarks that expand environmental catalyst retrofit cycles in existing facilities. Jubail Industrial City anchors the kingdom's densest concentration of syngas and ammonia catalyst procurement relationships.
Chemical Processing Catalysts Market Competitive Environment
Player mix skews toward integrated chemical conglomerates with captive catalyst technology platforms alongside specialized catalyst manufacturers with deep process expertise. Tiered competitive structure separates performance-guarantee suppliers serving refiners from catalog distributors addressing research-scale procurement. Strategic archetypes include integrated petrochemical-catalyst platforms, precious metal recovery specialists, and regional formulation houses. Capacity expansion in China's chemical clusters and strategic partnerships for carbon capture integration represent dominant competitive vectors.
Within the integrated platform tier, BASF SE and Clariant exemplify conglomerates leveraging backward integration into catalyst manufacturing to anchor long-term supply relationships. Johnson Matthey occupies a distinct position as a precious metal technology specialist with hydrogenation and dehydrogenation expertise. Haldor Topsoe represents the energy-sector focused archetype dominating syngas and ammonia catalyst supply relationships.
| Leading Market Players |
|---|
| BASF SE |
| Johnson Matthey |
| Clariant |
| Albemarle Corporation |
| W. R. Grace & Co. |
| Haldor Topsoe |
| Honeywell UOP |
| Evonik Industries |
| Axens |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at China's lanthanide separation facilities shapes global price floors for fluid catalytic cracking catalysts, concentrating supply leverage among state-controlled processors while forcing North American refiners to absorb metal oxide cost volatility through long-term offtake structures.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate procurement for platinum group metal formulations, embedding rhodium and palladium price swings directly into hydrogenation catalyst unit economics. Three-tier pricing structure across premium, standard, and economy levels separates performance-guaranteed refinery contracts from catalog biocatalyst sales and spot-market commodity grades. Pricing pressure stems from rare earth oxide cost inflation, with margins tightening most acutely for mid-tier heterogeneous catalyst suppliers serving commodity chemical producers. Pharmaceutical manufacturers exhibit lowest price sensitivity, prioritizing cGMP certification and validated impurity profiles over unit cost in enzymatic procurement decisions.
Supply Chain Analysis
Strait of Malacca transit underwrites seaborne lanthanide concentrate flows from Australian mines to Chinese separation plants, creating chokepoint exposure for North American FCC catalyst manufacturers. Supply concentration in China's Inner Mongolia and Jiangxi provinces, combined with South African platinum group metal refining, anchors upstream raw material dependencies. Molecular sieve precursors, alumina carriers, and engineered enzyme cultures constitute critical input categories. Single-source vulnerability in rare earth oxide supply generates structural risk for catalyst formulators dependent on spot-market metal procurement. Distribution runs through integrated petrochemical technology platforms for refinery clients, while regional distributors serve fragmented specialty chemical procurement with unbundled technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory chemistry constraints diverge across EPA, REACH, and MEE jurisdictions, creating specialized demand niches for modular catalyst platforms adaptable to multi-jurisdictional certification timelines.
For Market Incumbents: Compound defensive positioning through captive lanthanide processing partnerships that secure rare earth oxide supply against China's export quota volatility, while simultaneously anchoring long-term performance contracts with European refiners facing KBA emissions certification deadlines. Prioritize R&D allocation toward single-atom catalysis platforms that displace traditional nanoparticle loadings in pharmaceutical hydrogenation applications. For New Entrants and Emerging Players: Differentiate on computational catalysis capabilities combining density functional theory with reactor engineering expertise, targeting the talent-scarce rational design segment where incumbent pipelines lag. India's PLI scheme-driven specialty chemical manufacturing expansion offers the most penetrable geography, with Gujarat pharmaceutical corridors particularly receptive to enzymatic process partnerships. Pursue pilot-scale validation agreements with domestic fine chemical producers seeking EMA-compliant biocatalyst supply. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precious metal recovery specialists with integrated refining capabilities, as platinum group metal price volatility intensifies circular economy value capture across catalyst lifecycles. Long-term viability rests on exposure to carbon capture integration opportunities in ammonia and methanol plant retrofits. Watch MEE dual carbon enforcement intensity as the inflection signal for capital reallocation toward lower-carbon catalytic process technologies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Oxide Processing | Secures supply leverage against China's lanthanide export quotas for FCC catalyst manufacturers. |
| Single-Atom Catalysis Platform Development | Enables precious metal loading reduction in pharmaceutical hydrogenation applications under FDA scrutiny. |
| Long-Term Performance Contracting with European Refiners | Ties catalyst supply to KBA emissions certification compliance, displacing transactional purchasing models. |
| Carbon Capture Integration Partnerships | Positions syngas catalyst systems for ammonia plant retrofits under MEE dual carbon enforcement timelines. |
| Biocatalytic Process Licensing to Indian Fine Chemical Producers | Captures PLI scheme-driven demand for enzymatic routes in Gujarat pharmaceutical manufacturing clusters. |
Study Parameters
The analysis maps heterogeneous catalyst formulations, biocatalytic enzyme systems, and environmental application platforms, each validated through procurement directors at petrochemical complexes, technical R&D leads at catalyst manufacturers, and regulatory affairs specialists navigating multi-jurisdictional certification pathways. Primary interviews with plant managers at US Gulf Coast refiners, distribution channel partners in European chemical corridors, and fine chemical production heads in Indian pharmaceutical clusters combined with secondary validation from customs trade data, ACC and Cefic industry reports, and SEC 10-K filings. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs, with analytical framework modeling across product type, application category, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of historical capacity additions and forward-looking petrochemical buildout pipelines. Forecast inputs incorporated EPA Tier 3 sulfur mandate implementation timelines, MEE dual carbon compliance enforcement intensity, and REACH registration deadline clustering effects.
Material uncertainties — platinum group metal price volatility, rare earth export quota adjustments, and computational catalysis talent availability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and capital expenditure commitment levels in Chinese petrochemical capacity expansion. Practitioners should keep alternative scenarios live as MEE dual carbon policy implementation evolves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Chemical Catalyst Market
Catalysts
Industrial Catalyst Market
Catalysts
Global Phase Transfer Catalyst Market
Catalysts
Platinum-Based Catalysts Market
Catalysts
Fluid Catalytic Cracking Catalyst Market
Catalysts
Stationary Catalytic Systems Market
Catalysts
Biodiesel Catalyst Market
Catalysts
Natural Zeolites Market
Catalysts
North America Zeolite Market
Catalysts
Asia and Middle East Polyolefin Catalyst Market
Catalysts
Middle-East and Africa Refining Catalysts Market
Catalysts
Hydrogenation Catalyst Market
Catalysts
Polymerization Catalysts Market
Catalysts
Secondary Reforming Catalyst Market
Catalysts
Global Polypropylene Catalyst Market
Catalysts
Steam Methane Reforming Market