
 Aluminum-Nickel Catalyst Market | 2026-2036
Aluminum-Nickel Catalyst Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum-Nickel Catalyst Market Analysis
The EU Green Deal's industrial decarbonization targets are shifting procurement criteria toward longer-life catalyst systems that cut hydrogen consumption and reduce regeneration frequency. BASF SE anchors European supply through backward integration into alumina support production at its Ludwigshafen complex. Johnson Matthey leads in pharmaceutical-grade Raney nickel formulations for high-purity hydrogenation. W. R. Grace & Co. specializes in tailored pore structures for heavy feedstock processing in North American refineries.
Aluminum-nickel catalyst denotes a heterogeneous catalytic system comprising intermetallic Ni-Al phases, typically activated by caustic leaching to produce porous Raney nickel with surface areas exceeding 80 m²/g and bulk nickel content of 85-92 wt%. The material serves primarily as a hydrogenation and dehydrogenation promoter in batch and continuous-flow reactors across edible oil hardening, pharmaceutical intermediate synthesis, and petrochemical upgrading. Supported catalyst formulations command premium positioning due to controlled metal dispersion on engineered alumina or silica carriers that extend operational cycles in fixed-bed units. Powder and granule forms dominate volume throughput in slurry-phase hydrogenation, while pellet structures capture value in continuous-flow petrochemical trains where pressure-drop management determines reactor economics.
EPA emissions standards for refinery hydrogen plants and ECHA REACH authorization requirements for nickel compounds are tightening material sourcing and spent catalyst handling protocols. China's MEE enforces stricter discharge limits on leaching effluents from Raney nickel activation facilities. India's BIS certification mandates for imported catalysts are raising entry barriers for non-standard formulations. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with diverging compliance cost structures.
Market Dynamics
REACH authorization requirements for nickel compounds are forcing edible oil processors and pharmaceutical manufacturers to requalify catalyst suppliers, compressing procurement cycles and elevating documentation burdens across European hydrogenation facilities.
Growth Catalysts
- Hydrogenation demand from edible oil processors:Margarine and shortening manufacturers in Germany and the Netherlands are expanding hydrogenation capacity to meet reformulated product specifications for reduced trans-fat content.
- China's dual carbon goals:MEE discharge limits on leaching effluents are accelerating replacement of legacy Raney nickel systems with closed-loop activation technologies in Shandong and Jiangsu provinces.
- Pharmaceutical API manufacturing expansion:High-purity hydrogenation requirements for active pharmaceutical ingredients are driving specification upgrades at FDA-inspected facilities in India and Ireland.
Market Restraints
- Aluminum price volatility:Primary aluminum ingot costs fluctuate with LME trading patterns, compressing margin structures for catalyst manufacturers lacking long-term alumina supply agreements.
- Supplier concentration in Ludwigshafen:Backward-integrated alumina support production anchors European supply, creating vulnerability to localized production disruptions or force majeure events.
- Precious metal substitution threat:Palladium-on-carbon systems capture share in pharmaceutical hydrogenation where ultra-low nickel contamination thresholds apply.
Strategic Opportunities
- Brazilian biofuel hydrogenation:ANVISA-aligned catalyst qualification pathways open access to expanding renewable diesel and SAF production at Petrobras-operated refineries.
- Modular reactor integration:Skid-mounted continuous-flow hydrogenation units are creating demand for pelletized catalyst formats optimized for pressure-drop management.
- EU Green Deal industrial decarbonization:Longer-life catalyst systems that cut hydrogen consumption qualify for green transition financing instruments under the European Investment Bank's sustainability framework.
Industry Challenges
- Spent catalyst handling certification:ECHA REACH authorization for nickel compound recovery requires specialized logistics partnerships that extend compliance timelines by 12-18 months for new market entrants.
- Fixed-bed reactor integration complexity:Legacy slurry-phase hydrogenation facilities face capital-intensive retrofit requirements to accommodate supported catalyst pellet systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum-Nickel Catalyst Market |
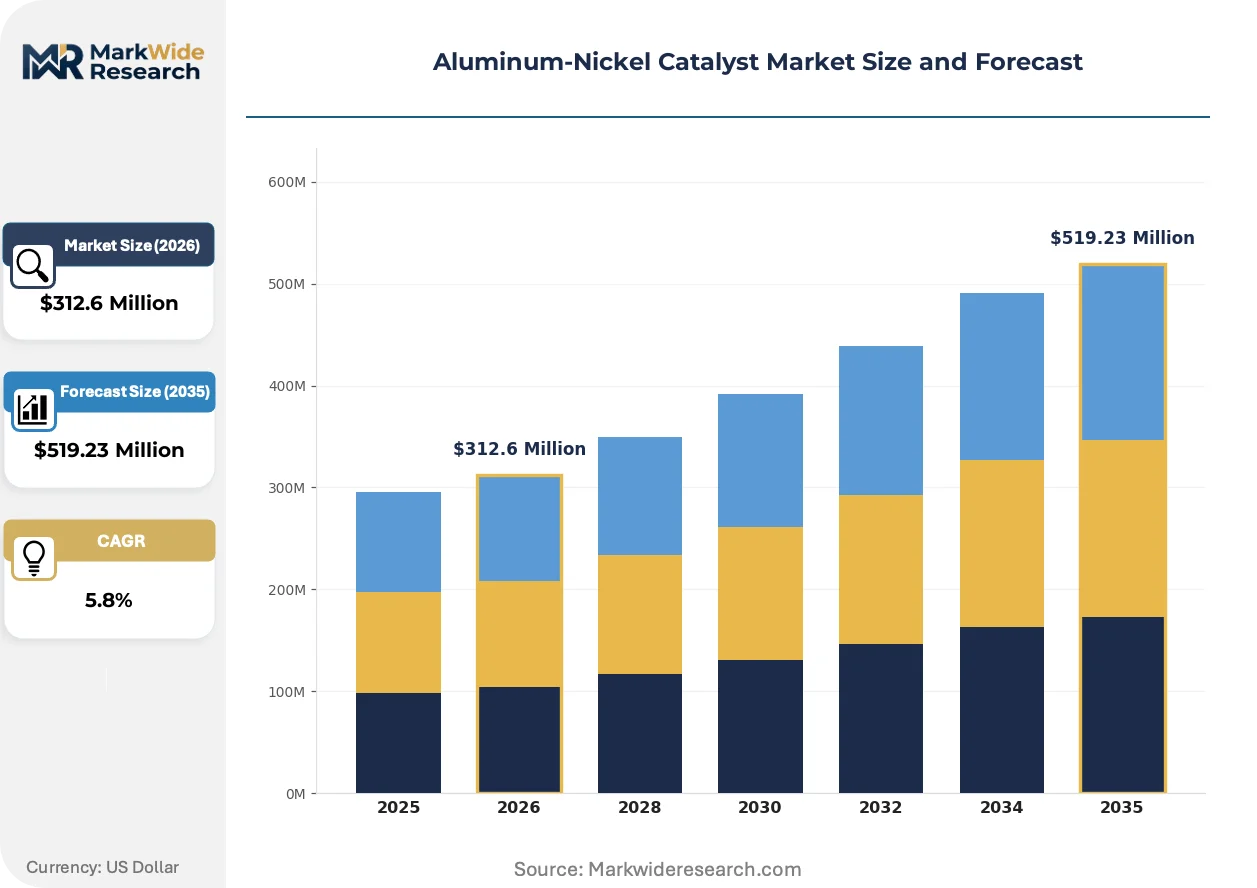
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supported Catalyst, Unsupported Catalyst, Reusable Catalyst, Single Component Usage Area: Chemical Manufacturing, Energy Production, Waste Treatment, Environmental Applications Catalyst Form: Powder, Granule, Pellet, Coated Application: Synthesis Reactions, Petrochemical Processing, Green Chemistry, Haber-Bosch Process |
| Companies Covered | W. R. Grace & Co., Axens, BASF SE, Albemarle Corporation, Clariant AG, Johnson Matthey, Haldor Topsoe A/S, Hangzhou Jiali Metal Technology, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum-Nickel Catalyst Market Emerging Trajectories
Reactor engineering and materials science advances are compressing catalyst replacement cycles while elevating performance specifications for hydrogen efficiency and metal leaching resistance across edible oil and pharmaceutical applications.
Engineered alumina supports with tailored pore structures are modularizing catalyst design architectures. Edible oil processors in Belgium and the United States are adopting these systems to extend operational cycles from 8,000 to 12,000 hours. This modularization is enabling rapid formulation swaps between heavy feedstock and light oil hydrogenation without full reactor shutdown.
REACH authorization requirements for nickel compounds are tightening spent catalyst tracking protocols. ECHA mandates cradle-to-grave documentation for nickel content exceeding 0.1% threshold concentrations. Pharmaceutical API manufacturers in Switzerland and Italy are responding by pre-qualifying dual-source catalyst suppliers to mitigate authorization renewal risks.
Specification-driven procurement is consolidating buyer power among multinational edible oil processors. Direct technical partnerships with catalyst formulators are displacing distributor-mediated purchasing in North American and European markets. This concentration is most visible at integrated refineries in Rotterdam and Houston where procurement teams negotiate multi-year performance guarantees.
Aluminum-Nickel Catalyst Market Segmentation
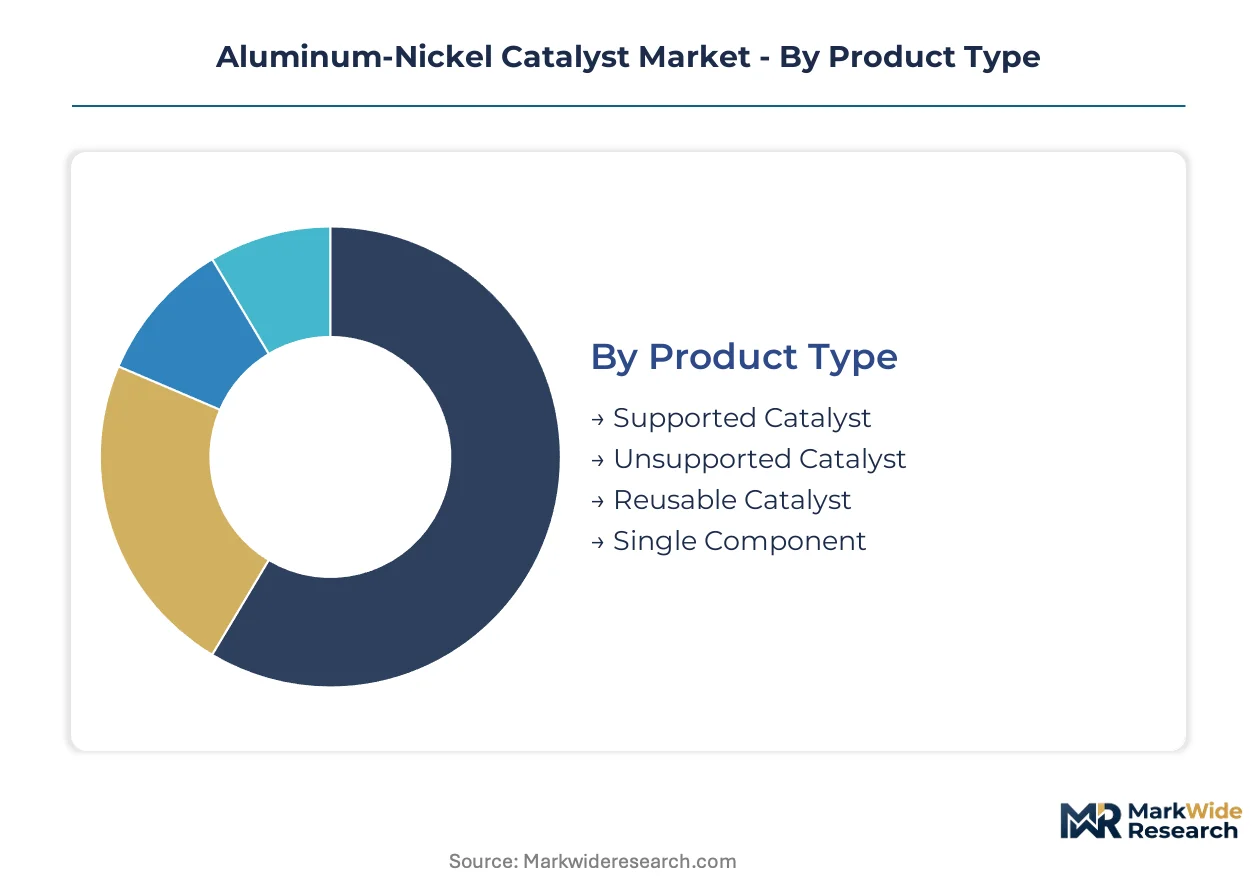
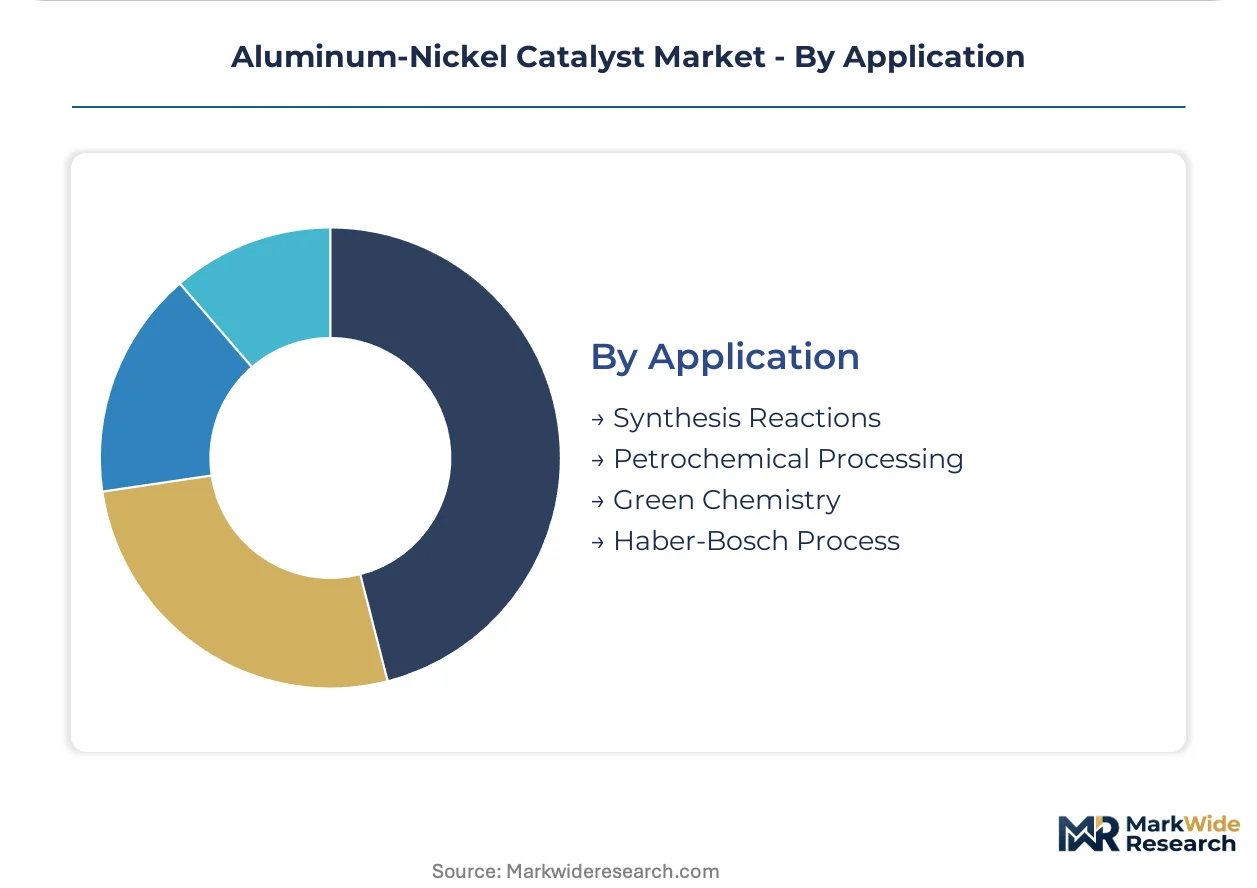
Aluminum-nickel catalyst procurement splits sharply between commodity hydrogenation operations and precision pharmaceutical manufacturing, with form factor and support architecture determining reactor compatibility and lifecycle economics across these divergent use cases.
Product Type:
Volume throughput concentrates in commodity unsupported formulations, while supported catalysts capture premium positioning through engineered carrier systems that extend operational cycles.
- Supported Catalyst:Nickel active sites dispersed on alumina or silica carriers with controlled pore structures between 8-15 nm. Edible oil processors in Germany and the Netherlands specify these systems for continuous-flow hydrogenation trains where 12,000-hour cycle lengths justify 40-60% price premiums over powder alternatives. REACH authorization requirements for nickel compound handling are accelerating documentation burdens for supported catalyst qualification.
- Unsupported Catalyst:Porous Raney nickel produced through caustic leaching of Ni-Al alloys, delivering surface areas exceeding 80 m²/g and bulk nickel content of 85-92 wt%. Batch hydrogenation facilities in India's specialty chemical sector favor unsupported formulations for flexibility in campaign-based production of pharmaceutical intermediates. BIS certification mandates for imported catalysts are raising entry barriers for non-standard formulations.
- Reusable Catalyst:Regenerable systems designed for multiple activation cycles through controlled oxidation-reduction protocols. Chemical manufacturers in Shandong province adopt closed-loop activation technologies to comply with MEE discharge limits on leaching effluents.
- Single Component:Homogeneous nickel salt precursors for specialized hydrogenation where catalyst recovery complexity outweighs heterogeneous system benefits. Pharmaceutical API manufacturers in Ireland deploy single-component systems for high-purity hydrogenation of complex molecular architectures.
Mature deployment sits with unsupported catalysts. Newer deployment is concentrated in supported catalysts.
Usage Area:
Application-driven procurement patterns separate process-scale chemical manufacturing from emerging environmental remediation markets, with energy production occupying an intermediate position on specification intensity.
- Chemical Manufacturing:Hydrogenation and dehydrogenation operations across commodity and specialty chemical production, spanning edible oil hardening, pharmaceutical intermediate synthesis, and fine chemical processing. BASF SE's Ludwigshafen complex anchors European demand through backward-integrated alumina support production for captive catalyst consumption.
- Energy Production:Biofuel upgrading and renewable diesel hydrogenation at integrated refinery sites. Petrobras-operated refineries in Brazil are expanding catalyst qualification pathways aligned with ANVISA standards for renewable diesel and SAF production.
- Waste Treatment:Catalytic reduction processes for industrial effluent remediation and hazardous waste neutralization. China's dual carbon goals are accelerating replacement of legacy systems with closed-loop activation technologies in Jiangsu province.
- Environmental Applications:Emissions control and pollution prevention systems, including refinery hydrogen plant optimization under EPA emissions standards. ECHA REACH authorization requirements are tightening spent catalyst tracking protocols for nickel content exceeding 0.1% threshold concentrations.
Chemical manufacturing retains the dominant procurement volume. Environmental applications are climbing the fastest on regulatory compulsion.
Catalyst Form:
Reactor engineering constraints dictate form selection, with pressure-drop management and mass transfer efficiency determining optimal geometries for batch versus continuous-flow operations.
- Powder:Finely divided Raney nickel with particle sizes typically 10-50 microns, optimized for slurry-phase hydrogenation with high external surface area. Margarine and shortening manufacturers specify powder forms for batch hydrogenation where rapid dispersion and filtration recovery are operational priorities.
- Granule:Intermediate particle sizes between powder and pellet structures, balancing surface area with handling characteristics. Waste treatment facilities favor granule forms for fixed-bed configurations where moderate pressure-drop tolerance meets ease of catalyst loading.
- Pellet:Engineered cylindrical or spherical structures with diameters 2-5 mm, designed for continuous-flow petrochemical trains. Skid-mounted modular reactor systems are creating demand for pelletized formats optimized for pressure-drop management and uniform flow distribution.
- Coated:Thin catalytic layers deposited on structured substrates such as monoliths or foams, enabling low-pressure-drop operation with minimal catalyst inventory. Energy production applications are adopting coated systems for compact reactor designs in renewable fuel upgrading.
Powder forms dominate current procurement volumes. Pellet structures are gaining share fastest on continuous-flow reactor expansion.
Application:
Process chemistry requirements separate high-volume commodity hydrogenation from precision synthesis operations, with green chemistry emerging as a distinct specification tier.
- Synthesis Reactions:Hydrogenation of pharmaceutical intermediates, fine chemicals, and specialty molecules requiring stereoselectivity and minimal metal contamination. FDA-inspected facilities in India and Ireland are driving specification upgrades for high-purity hydrogenation of active pharmaceutical ingredients.
- Petrochemical Processing:Heavy feedstock upgrading, hydrotreating, and hydrocracking operations at integrated refineries. W. R. Grace & Co. specializes in tailored pore structures for these applications in North American refineries where feedstock variability demands adaptive catalyst architectures.
- Green Chemistry:Catalytic processes designed to minimize waste, reduce solvent use, and enable renewable feedstock conversion. EU Green Deal industrial decarbonization targets are shifting procurement criteria toward longer-life catalyst systems that cut hydrogen consumption and reduce regeneration frequency.
- Haber-Bosch Process:Ammonia synthesis via catalytic hydrogenation of nitrogen, historically the dominant industrial application for promoted iron catalysts with aluminum oxide structural promoters. Aluminum-nickel systems occupy niche positions in ammonia plant startup and guard-bed applications.
Petrochemical processing anchors volume demand. Green chemistry is expanding most quickly on sustainability-linked financing availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and China while consumption spreads across pharmaceutical hubs in India and Ireland. This geographic split creates trade flows of activated catalysts and precursor alloys. Regulatory divergence between REACH in Europe and MEE discharge limits in China is fragmenting compliance architectures.
United States
Edible oil processors in the Midwest and Gulf Coast drive hydrogenation demand for margarine and shortening reformulation. EPA emissions standards for refinery hydrogen plants tighten spent catalyst handling protocols. Houston anchors North American procurement through integrated refineries negotiating multi-year performance guarantees with formulators.
Germany
BASF SE's Ludwigshafen complex consumes captive alumina support production for chemical manufacturing hydrogenation. ECHA REACH authorization requirements for nickel compounds compress procurement cycles and elevate documentation burdens. The chemical corridor between Ludwigshafen and Leverkusen concentrates European catalyst qualification and technical partnership activity.
China
Shandong and Jiangsu provinces accelerate replacement of legacy Raney nickel systems with closed-loop activation technologies. MEE discharge limits on leaching effluents force capital upgrades at activation facilities. The Yangtze River Delta hosts expanding pharmaceutical API manufacturing driving specification upgrades for high-purity hydrogenation.
India
FDA-inspected facilities in Maharashtra and Gujarat expand high-purity hydrogenation capacity for active pharmaceutical ingredients. BIS certification mandates for imported catalysts raise entry barriers for non-standard formulations. Mumbai-Pune chemical belt concentrates specialty chemical batch hydrogenation using unsupported Raney nickel for campaign-based production flexibility.
Brazil
Petrobras-operated refineries expand renewable diesel and SAF production requiring ANVISA-aligned catalyst qualification pathways. Biofuel hydrogenation demand creates access opportunities for pelletized catalyst formats in continuous-flow reactor trains. São Paulo state anchors South American procurement through integrated refining and biofuel upgrading complexes.
Aluminum-Nickel Catalyst Market Vendor Landscape
The competitive structure tilts toward backward-integrated chemical conglomerates with captive alumina supply and specialized catalyst formulators serving pharmaceutical purity requirements. Tiered positioning separates commodity hydrogenation suppliers from precision manufacturers. Three archetypes dominate: diversified chemical majors with integrated support production, specialty catalyst houses focused on pharmaceutical-grade formulations, and regional fabricators serving batch chemical processors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players navigate diverging regulatory compliance costs across jurisdictions.
Among European-based chemical majors, BASF SE and Johnson Matthey exemplify divergent strategic positions within the catalyst value chain. BASF SE anchors integrated supply through in-house alumina support production at its Ludwigshafen complex. Johnson Matthey occupies a specialist position in pharmaceutical-grade Raney nickel formulations for high-purity hydrogenation requirements. W. R. Grace & Co. represents the North American specialist archetype with tailored pore structure capabilities for heavy feedstock processing applications.
| Leading Market Players |
|---|
| W. R. Grace & Co. |
| Axens |
| BASF SE |
| Albemarle Corporation |
| Clariant AG |
| Johnson Matthey |
| Haldor Topsoe A/S |
| Hangzhou Jiali Metal Technology |
| Evonik Industries |
| Others |
Supply Flow & Price Mechanics
EU Green Deal industrial decarbonization targets gate qualified supply access and premium-tier pricing for longer-life catalyst systems that cut hydrogen consumption. Buyers in Germany's chemical corridor around Ludwigshafen and Leverkusen face compressed procurement cycles as REACH authorization requirements for nickel compounds elevate documentation burdens and supplier qualification costs.
Pricing Analysis
Performance-based pricing tied to operational cycle length anchors value capture in this market. Three-tier pricing structure across premium supported catalysts, standard unsupported formulations, and economy-grade reusable systems separates buyers by hydrogenation intensity and purity requirements. REACH compliance certification functions as the primary price differentiation driver alongside volume scale commitments. Cost compression in standard-grade Raney nickel intensifies as aluminum price volatility feeds through from LME trading patterns. Pharmaceutical API manufacturers in India and Ireland exhibit lowest price sensitivity due to FDA inspection requirements and contamination threshold specifications.
Supply Chain Analysis
Direct technical partnerships with formulators displace distributor-mediated purchasing for multinational edible oil processors in Rotterdam and Houston. Supply concentrates in Germany through BASF SE's captive alumina support production at Ludwigshafen, and in China through Shandong and Jiangsu province activation facilities. Raw material dependencies center on primary aluminum ingot, caustic soda for leaching operations, and engineered alumina carriers. Single-source vulnerability in European alumina support production creates exposure to localized force majeure events. Distribution runs through qualified logistics partnerships specializing in ECHA-compliant spent catalyst handling and cradle-to-grave nickel tracking documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained due to REACH authorization bottlenecks for nickel compound handling that compress qualified supplier pools and prop pricing power toward incumbent formulators with established ECHA documentation protocols.
For Market Incumbents: Anticipate palladium-on-carbon substitution threats in pharmaceutical hydrogenation by deepening captive alumina supply control and accelerating closed-loop activation technology deployment. Defend position by extending operational cycle guarantees from 8,000 toward 15,000 hours through engineered pore structure investments. Prioritize dual-source qualification partnerships with FDA-inspected facilities in India to mitigate authorization renewal concentration risks.
For New Entrants and Emerging Players: ANVISA-aligned catalyst qualification pathways in Brazil open a window for pelletized format specialists targeting Petrobras-operated renewable diesel and SAF production expansions. Target São Paulo state refining complexes with skid-mounted continuous-flow hydrogenation unit integration expertise. Pursue white-space capture in China's Jiangsu province closed-loop activation technology replacement cycle driven by MEE discharge limit enforcement.
For Investors and Strategic Acquirers: ECHA authorization renewal compression timelines extending 12-18 months for new market entrants is the leading indicator that qualified catalyst handling logistics capabilities will command scarcity premia. Position acquisition screening toward regional fabricators with established spent catalyst recovery partnerships and BIS certification for Indian market access. Monitor FDA inspection readiness scores at Maharashtra and Gujarat API facilities as inflection signals for high-purity hydrogenation specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Support Production | BASF SE's Ludwigshafen complex demonstrates captive supply security against force majeure disruption. |
| Closed-Loop Activation Technology Deployment | Shandong province adopters achieve MEE compliance while cutting effluent discharge liability exposure. |
| Pelletized Catalyst Format Development | Skid-mounted modular reactor integration in Rotterdam and Houston creates pressure-drop optimization demand. |
| Dual-Source Supplier Qualification | Swiss and Italian pharmaceutical manufacturers mitigate ECHA authorization renewal risk through pre-qualified redundancy. |
| Spent Catalyst Handling Logistics Partnership | ECHA cradle-to-grave documentation requirements extend compliance timelines 12-18 months without established recovery networks. |
Methodological Framework
Trade databases, SEC 10-K filings, and ECHA REACH authorization registries formed the secondary backbone for supply-side capacity and regulatory compliance mapping. Primary interviews with catalyst plant managers, edible oil processor procurement leads, pharmaceutical regulatory affairs directors, and specialty chemical distribution channel partners validated formulation demand patterns and qualification timeline assumptions. Bottom-up and top-down triangulation reconciled activation facility throughput estimates against downstream hydrogenation capacity expansion announcements.
Bottom-up modeling anchored volume projections in individual facility capacity announcements across Germany's Ludwigshafen-Leverkusen corridor, China's Shandong-Jiangsu belt, and India's Mumbai-Pune chemical cluster. Segmentation dimensions spanned product type tier, catalyst form geometry, application purity requirements, and regional regulatory framework clusters. CAGRs were derived from weighted average of facility-level expansion timelines and replacement cycle compression factors. Industry-specific forecast inputs included MEE discharge limit enforcement schedules and ANVISA biofuel qualification pathway opening dates.
Caveats apply where aluminum LME price volatility, ECHA authorization renewal delays, or FDA inspection backlogs could materially shift the outlook for catalyst demand and supplier qualification timelines. Periodic stress-testing of base assumptions against regulatory enforcement acceleration or feedstock substitution breakthroughs is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Catalysts
Global Zeolites Market
Catalysts
Industrial Catalyst Market
Catalysts
Global VOC Catalysts Market
Catalysts
North America Refining Catalysts Market
Catalysts
Solid Acid Catalysts Market
Catalysts
Global Boron Trifluoride Methanol Complex Market
Catalysts
Environmental Catalysts Market
Catalysts
Global Light Powered Catalyst Market
Catalysts
Rhodium Carbon Catalyst Market
Catalysts
Copper Bismuth Catalyst Market
Catalysts
Polyolefin Catalyst Market
Catalysts
Zeolite Molecular Sieve Market
Catalysts
Hydrodeoxygenation [HDO] Catalysts Market
Catalysts
Heavy Oil Cracking Catalyst Market
Catalysts
Polymer Catalyst Market
Catalysts
CO2 Reforming Catalysts Market