
 Oxide Dispersion Strengthened (ODS) Alloys Market | 2026-2036
Oxide Dispersion Strengthened (ODS) Alloys Market Size, Share, and Industry Trends Forecast 2026-2036
Oxide Dispersion Strengthened (ODS) Alloys Market Analytics
Nuclear energy operators is reorganizing procurement priorities toward radiation-resistant alloys for advanced reactor designs. VDM Metals leverages its European production footprint to supply specialized ODS grades for fusion and fission applications. Sandvik AB anchors Scandinavian supply chains through integrated powder metallurgy capabilities. Proterial Metals Ltd. competes on precision-controlled dispersion processing for thin-walled tubing.
Oxide Dispersion Strengthened alloys are precipitation-hardened metals containing uniformly distributed nanoscale oxide particles, typically yttria or alumina at 0.3-0.5 weight percent, manufactured through mechanical alloying followed by thermomechanical processing to achieve creep rupture strengths exceeding conventional superalloys by 30-50% at temperatures above 1000°C. ODS ferritic steels dominate current volume due to established nuclear qualification pathways, while ODS Ni-based alloys capture premium margins in aerospace turbine applications where oxidation resistance at 1100°C-plus regimes justifies unit cost premiums of three to five times over conventional cast equivalents. Powder metallurgy remains the incumbent production technology, though 3D printing adoption is accelerating for complex heat exchanger geometries that eliminate welded joints.
France's ASN and the US NRC impose distinct qualification protocols for reactor-grade ODS alloys, creating dual-track certification requirements that extend commercialization timelines by four to seven years for cross-border suppliers. REACH and the EU F-Gas Regulation indirectly shape demand by restricting alternative high-temperature coating chemistries, redirecting investment toward bulk ODS material solutions. Stakeholders must monitor regulatory divergence between Western and Chinese nuclear safety frameworks, as China's NNSA develops indigenous ODS standards that could fragment global qualification regimes and force technology-localization decisions.
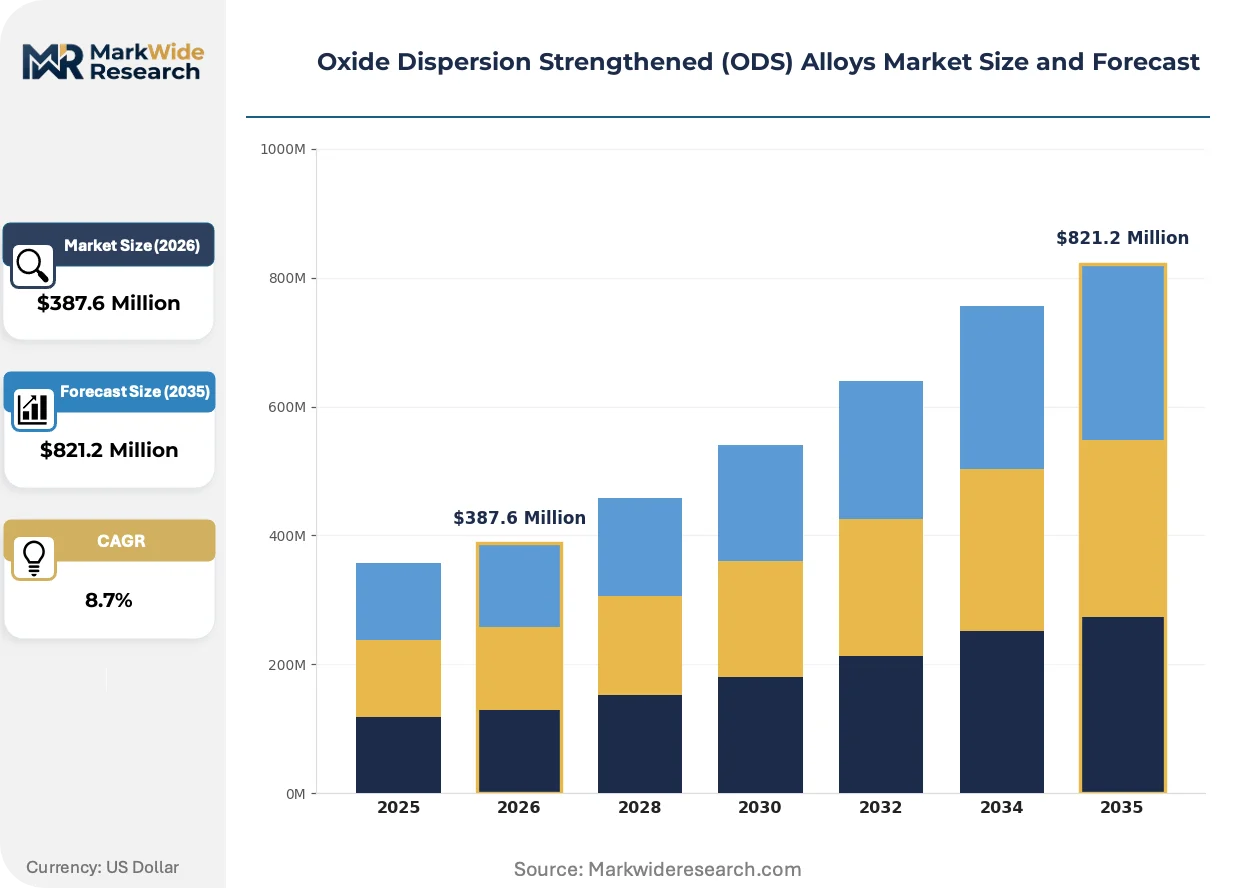
Market Dynamics
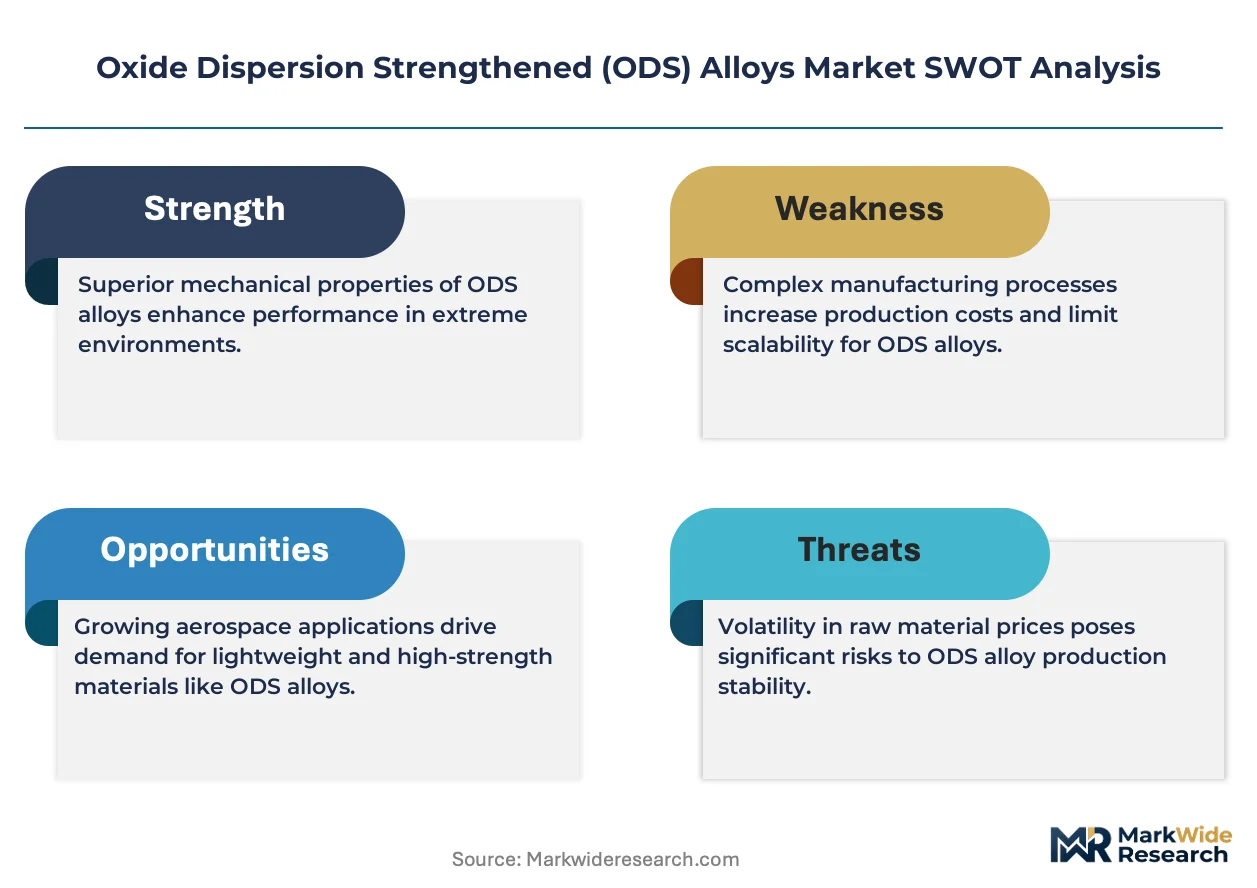
Nuclear qualification timelines stretching four to seven years are compressing supplier margins while fusion energy commercialization creates parallel certification tracks for ODS alloys. Powder metallurgy incumbents face capacity allocation decisions between established fission markets and speculative fusion demand.
Growth Catalysts
- EU Green Deal:The framework tightens material performance standards for next-generation reactors, mandating creep rupture strengths above 1000°C that only ODS alloys deliver. EDF's reactor modernization program in France anchors European procurement volume.
- Fusion energy commercialization:ITER and private reactor developers require radiation-resistant plasma-facing components. ODS ferritic steels qualify for first-wall and blanket module applications where neutron damage tolerance exceeds conventional materials.
- Mechanical alloying advances:Improved attritor milling and cryogenic processing achieve more uniform yttria dispersion. This reduces oxide agglomeration defects that previously limited thin-walled tubing yields.
Market Restraints
- Dual-track certification:France's ASN and the US NRC impose non-harmonized qualification protocols. Cross-border suppliers absorb extended commercialization timelines without revenue offset.
- Input concentration:High-purity yttria supply concentrates in Chinese rare earth processing. Price volatility in oxide precursors directly impacts mechanical alloying economics.
- Cast superalloy substitution:Directionally solidified Ni-based alloys with thermal barrier coatings compete in aerospace turbine applications below 1050°C, capping ODS premium pricing power.
Strategic Opportunities
- 3D printing adoption:Laser powder bed fusion enables complex heat exchanger geometries that eliminate welded joints. Additive manufacturing reduces thermomechanical processing steps for prototype fusion components.
- China's NNSA standards development:Indigenous ODS qualification frameworks create technology-localization requirements. Western suppliers can license dispersion processing IP rather than exporting finished material.
- REACH chemical restrictions:The regulation restricts alternative high-temperature coating chemistries containing hexavalent chromium. Bulk ODS solutions capture redirected investment from surface treatment markets.
Industry Challenges
- Metallurgical talent scarcity:Mechanical alloying requires specialized expertise in powder handling and thermomechanical processing. Universities have reduced physical metallurgy program enrollment over two decades.
- Fusion timeline uncertainty:Demonstration reactor schedules slip repeatedly. ODS suppliers face stranded capacity if commercial fusion deployment delays beyond 2040.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxide Dispersion Strengthened (ODS) Alloys Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ODS Ferritic Steels, ODS Ni-Based Alloys, ODS Cu-Based Alloys, ODS Co-Based Alloys End User: Aerospace, Power Generation, Nuclear Energy, Automotive Application: High-Temperature Components, Structural Materials, Heat Exchangers, Welding Consumables Technology: Powder Metallurgy, Arc Melting, Cast Metal Processes, 3D Printing |
| Companies Covered | VDM Metals, MBN Nanomaterialia S.p.A., ArcelorMittal, Powder Alloy Corporation, Proterial Metals Ltd., Precision Castparts Corp., Haynes International Inc., Kansai Pipe Industries Ltd., Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxide Dispersion Strengthened (ODS) Alloys Market Evolving Landscape
Advanced manufacturing methods are fragmenting the incumbent powder metallurgy paradigm while regulatory divergence between Western and Chinese nuclear frameworks forces parallel development tracks. Material qualification is becoming the primary competitive moat.
Additive manufacturing of ODS alloys is displacing conventional extrusion and forging for prototype fusion components. Commonwealth Fusion Systems and Tokamak Energy specify laser-deposited heat exchanger channels with internal lattice structures. This eliminates multi-step machining and diffusion bonding operations that previously consumed twelve to eighteen months.
REACH and the EU F-Gas Regulation restrict hexavalent chromium coatings and fluorinated greenhouse gases used in thermal spray processes. Aerospace OEMs in Germany and France now specify bulk ODS turbine blades rather than coated cast equivalents. The shift compresses supply chains by removing coating subcontractors from tier-2 procurement.
Buyers are consolidating qualified supplier lists to reduce qualification audit burden. EDF and Framatome now require single-source accountability for ODS cladding lots rather than multi-vendor qualification. French nuclear procurement concentrates on VDM Metals and a second European mill, marginalizing smaller mechanical alloying specialists without ASN pre-approval.
Oxide Dispersion Strengthened (ODS) Alloys Market Segmentation
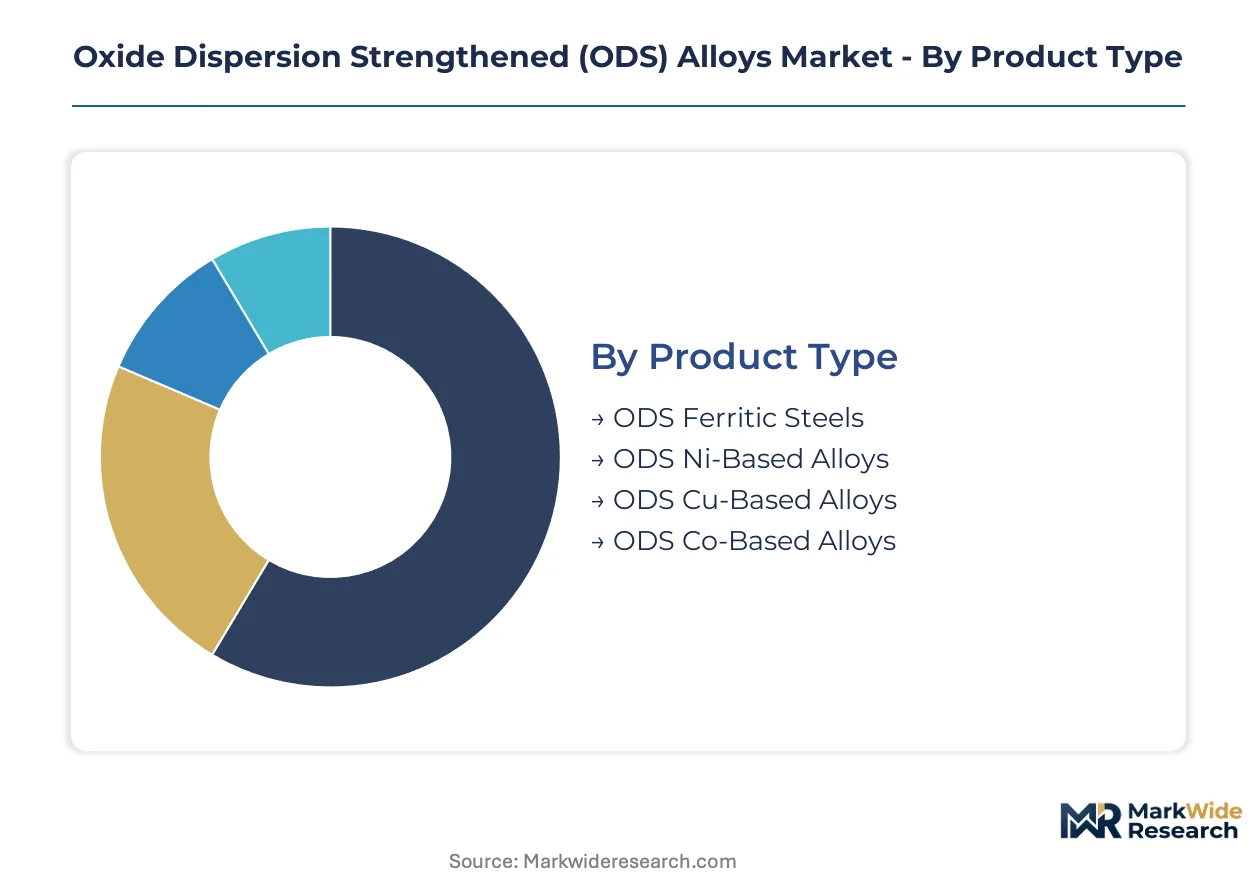
ODS alloy procurement patterns diverge sharply across product grades and end-use specifications. Nuclear qualification pathways favor established ferritic formulations, while aerospace buyers prioritize Ni-based variants for turbine applications above 1050°C.
Product Type:
Domestic production concentrates on ferritic grades for national reactor programs, whereas Ni-based alloys flow through specialized export channels serving aerospace OEMs.
- ODS Ferritic Steels:These chromium-tungsten compositions with 0.3% yttria dispersion achieve creep rupture strengths exceeding 100 MPa at 1000°C. French procurement through EDF and CEA anchors European volume, though ASN qualification timelines compress supplier margins. The segment commands the established base.
- ODS Ni-Based Alloys:Gamma-prime strengthened superalloys with alumina dispersions deliver oxidation resistance at 1100°C-plus regimes. Aerospace turbine blade demand in Germany and France justifies unit cost premiums three to five times above cast equivalents. The steepest expansion runs through this segment.
- ODS Cu-Based Alloys:Dispersion-strengthened copper with alumina particles serves high-heat-flux plasma-facing components in fusion reactor divertors.
- ODS Co-Based Alloys:Cobalt-chromium matrices with oxide dispersions target biomedical and specialized energy applications requiring wear resistance.
ODS ferritic steels retain volume leadership through nuclear qualification lock-in. Ni-based variants climb fastest as REACH restrictions redirect aerospace investment from coated cast alternatives.
End User:
Customer concentration follows regulatory intensity — nuclear and aerospace sectors absorb qualified supply while automotive remains peripheral.
- Nuclear Energy:Fuel cladding and core structural components require radiation damage tolerance exceeding 100 dpa. EDF's reactor modernization program in France concentrates procurement, with ASN and NRC dual-track certification extending supplier commercialization timelines.
- Aerospace:Turbine blade and combustor applications demand creep resistance above 1050°C. German and French OEMs specify bulk ODS solutions as REACH restricts hexavalent chromium thermal spray coatings.
- Power Generation:Ultra-supercritical steam turbines and advanced heat recovery systems utilize ODS tubing for service temperatures beyond nickel superalloy limits.
- Automotive:Exhaust valve and turbocharger applications remain niche due to cost-positioning against conventional superalloys and ceramic alternatives.
Nuclear energy locks in qualified capacity. Aerospace gains share fastest as coating substitution accelerates.
Application:
Functional requirements dictate manufacturing route — structural loads favor wrought products while thermal management needs drive additive adoption.
- High-Temperature Components:Turbine blades, combustor liners, and reactor internals require uniform oxide dispersion without agglomeration defects. Mechanical alloying with cryogenic attritor milling achieves the necessary yttria distribution.
- Heat Exchangers:Compact recuperators and fusion blanket modules specify complex internal geometries. Laser powder bed fusion eliminates welded joints and reduces lead times from eighteen months to under six.
- Structural Materials:Core support structures and pressure vessels prioritize ferritic ODS grades with established nuclear qualification databases.
- Welding Consumables:Filler wire and overlay deposits for repair and refurbishment of degraded high-temperature components.
High-temperature components dominate current procurement. Heat exchangers expand most quickly as fusion developers specify additively manufactured lattice structures.
Technology:
Process selection determines oxide dispersion uniformity and final component geometry capability.
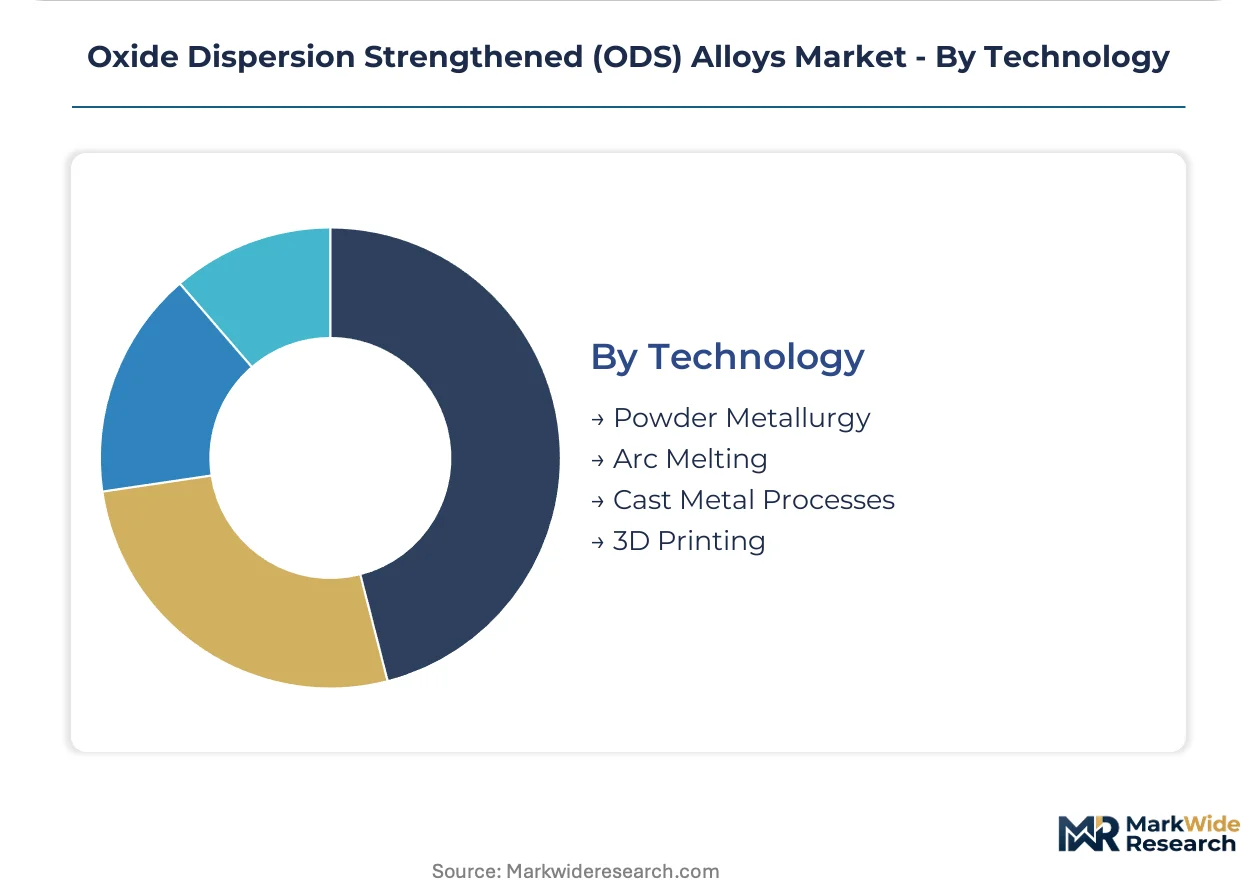
- Powder Metallurgy:Mechanical alloying followed by thermomechanical processing remains the incumbent route. VDM Metals and Sandvik AB anchor European supply through integrated attritor milling and extrusion capabilities.
- 3D Printing:Laser powder bed fusion and directed energy deposition enable prototype fusion components with internal cooling channels. Commonwealth Fusion Systems and Tokamak Energy specify these geometries for first-wall applications.
- Arc Melting:Vacuum arc remelting of pre-alloyed electrodes serves specialized Co-based and Cu-based compositions where mechanical alloying economics prove unfavorable.
- Cast Metal Processes:Directional solidification with in-situ oxide formation remains experimental, limited by agglomeration control challenges.
Powder metallurgy retains process leadership. 3D printing captures the fastest expansion trajectory as fusion commercialization accelerates prototype demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nuclear utilities and aerospace OEMs concentrate procurement in jurisdictions with established qualification frameworks. Regulatory divergence between safety regimes fragments supplier access across borders.
France
EDF's reactor modernization program and CEA research partnerships anchor European ODS consumption. ASN qualification protocols mandate creep rupture testing above 1000°C for fuel cladding applications. The Grenoble-Paris corridor houses specialized powder metallurgy facilities serving Framatome's supply chain.
United States
Next-generation reactor developers under the DOE's Advanced Reactor Demonstration Program specify radiation-resistant core components. NRC certification timelines extend four to seven years for ODS structural materials. Commonwealth Fusion Systems in Massachusetts drives prototype demand for additively manufactured heat exchangers.
Germany
Aerospace turbine OEMs specify bulk ODS blades as REACH restrictions eliminate hexavalent chromium coatings. The EU F-Gas Regulation redirects investment from thermal spray processes toward dispersion-strengthened substrates. Bavaria's precision engineering cluster supplies cryogenic milling equipment for mechanical alloying operations.
China
Indigenous fast reactor programs under the NNSA's indigenous standards framework stimulate domestic ODS production. High-purity yttria supply concentrates in rare earth processing hubs. Shanghai and Beijing host research institutes developing parallel qualification protocols distinct from Western regimes.
Japan
Fusion energy research under METI's roadmap generates demand for plasma-facing components. JIS standards for high-temperature structural materials influence procurement specifications. Osaka-based powder metallurgy specialists supply oxide dispersion processing equipment to domestic alloy producers.
Oxide Dispersion Strengthened (ODS) Alloys Market Competitive Landscape
Player mix skews toward integrated metallurgical conglomerates with captive powder production. The supplier base concentrates around three European and Japanese mills with established nuclear qualification databases. Strategic archetypes include vertically integrated specialty alloy producers, precision tubing specialists, and additive manufacturing technology licensors. Capacity expansion and technology licensing represent the dominant competitive moves as fusion commercialization accelerates.
Within the integrated European tier, VDM Metals and Sandvik AB occupy positions spanning powder metallurgy through finished component supply. Proterial Metals Ltd. exemplifies the precision-processing specialist archetype focused on thin-walled tubing applications. These three entities represent distinct strategic postures: continental-scale integrated production, Scandinavian powder-to-product integration, and Japanese precision dispersion control respectively.
| Leading Market Players |
|---|
| VDM Metals |
| MBN Nanomaterialia S.p.A. |
| ArcelorMittal |
| Powder Alloy Corporation |
| Proterial Metals Ltd. |
| Precision Castparts Corp. |
| Haynes International Inc. |
| Kansai Pipe Industries Ltd. |
| Sandvik AB |
| Others |
Value Network & Pricing Analysis
REACH-mandated substitution of hexavalent chromium thermal spray coatings with bulk ODS substrates is simultaneously redrawing European supply geography and compressing aerospace pricing premiums. German and French OEMs now specify dispersion-strengthened turbine blades directly, eliminating coating subcontractors and forcing mills to absorb former tier-2 margins into consolidated quotations.
Pricing Analysis
The powder-metallurgy-to-additive-manufacturing generation gap stratifies pricing across three performance tiers. Nuclear-qualified ferritic grades command contract-based long-term offtake structures anchored to ASN certification investment, while prototype fusion components trade at project-based premiums reflecting laser powder bed fusion yield uncertainty. Price differentiation hinges on certification database depth and volume scale, with EDF procurement consolidating around dual-source accountability that compresses smaller mills into economy-tier positioning. Cost compression in standard ferritic grades is intensifying as yttria price volatility feeds through mechanical alloying economics. Aerospace buyers exhibit lowest price sensitivity where REACH restrictions eliminate coated cast alternatives, whereas automotive exhaust valve applications face persistent substitution pressure from ceramic matrix composites.
Supply Chain Analysis
High-purity yttria refining in Chinese rare earth processing hubs constitutes a chokepoint that tethers Western mechanical alloying economics to NNSA trade policy shifts. Powder metallurgy capacity concentrates in Germany, Sweden, and Japan, with attritor milling equipment sourcing from Bavaria's precision engineering cluster. Raw material dependencies span yttria precursors, high-purity iron-nickel-chromium feedstock, and cryogenic milling media. Single-source vulnerability runs through Chinese oxide precursor supply, compounded by dual-track ASN-NRC qualification timelines that strand working capital without revenue offset. Distribution runs through direct mill-to-OEM contracts for nuclear applications, with aerospace channels employing specialized metals distributors holding AS9100 certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fusion energy commercialization is catalyzing a platform-economics inflection where qualification database interoperability between fission and plasma-facing component standards determines supplier survival. ITER and private reactor developers are converging on shared ODS specification frameworks that reward first-movers with cross-application certification leverage.
For Market Incumbents: Fortify nuclear qualification moats through captive attritor milling capacity in the Grenoble-Paris corridor, insulating Framatome supply commitments from yttria price volatility via backward integration into oxide precursor partnerships. Invest in parallel ASN-NRC certification tracks to compress four-to-seven-year commercialization timelines that currently cede prototype fusion orders to additive manufacturing specialists.
For New Entrants and Emerging Players: Anchor in laser powder bed fusion heat exchanger geometries for Commonwealth Fusion Systems and Tokamak Energy procurement, where eighteen-month lead time compression commands prototype premiums absent incumbent powder metallurgy lock-in. Target fusion first-wall applications as the most penetrable segment, exploiting qualification timeline asymmetry against established mills prioritizing EDF reactor modernization volume.
For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors vertically integrated specialty alloy producers with captive powder production and established nuclear qualification databases. Long-term viability hinges on certification interoperability across Western and Chinese regulatory regimes. The signal to watch is NNSA indigenous standards development, which could force technology-localization decisions and strand Western qualification investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Alloying Capacity Expansion | VDM Metals and Sandvik AB secure Framatome supply chain dominance through integrated attritor milling. |
| Dual-Track Certification Investment | Parallel ASN-NRC qualification compresses commercialization timelines for cross-border nuclear suppliers. |
| Additive Manufacturing Technology Licensing | Laser powder bed fusion IP monetization captures fusion prototype demand without finished material export. |
| Backward Integration into Oxide Precursors | Captive yttria supply partnerships insulate mechanical alloying economics from Chinese rare earth volatility. |
| Long-Term Supply Agreement with Fusion Developers | Commonwealth Fusion Systems and Tokamak Energy offtake commitments derisk stranded capacity from timeline slippage. |
Research Methodology
The analysis maps ODS ferritic steels, Ni-based superalloys, Cu-based plasma-facing materials, and Co-based biomedical grades, each validated through powder metallurgy plant managers, nuclear procurement officers at EDF and Framatome, aerospace technical directors at German turbine OEMs, and fusion energy supply chain leads. Primary interviews combined with secondary validation against ASN regulatory filings, NRC certification databases, EU REACH restriction updates, and customs trade data for yttria precursor flows. Bottom-up alloy-grade volume estimates triangulated against top-down nuclear reactor component demand models.
Consistency checks validated projections against IEA nuclear capacity forecasts, fusion energy demonstration reactor deployment schedules, and aerospace OEM thermal management material specifications across the projection horizon. Segmentation dimensions modeled include alloy matrix composition, end-use sector qualification requirements, manufacturing process technology, and regional regulatory framework clusters. CAGRs derived from installed base replacement cycles for EDF reactor modernization, fusion first-wall component refresh rates, and REACH-driven coating substitution timelines in European aerospace.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal nuclear investment and fusion commercialization proceeding without major demonstration reactor delays; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as NNSA indigenous ODS standards development and Chinese rare earth export policy evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Global Amorphous Alloy Band Market
Advanced Alloys
Welding Alloys Market
Advanced Alloys
Global Aluminum Alloys Market
Advanced Alloys
Tantalum Carbide Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
India Aluminum Extrusion Market
Advanced Alloys
US Green Steel Market
Advanced Alloys
Titanium Aluminide Market
Advanced Alloys
North America Green Steel Market
Advanced Alloys
Prepreg Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Powder Metallurgy Components Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Nickel Boride Alloy Market