
 Rigid Colored PU Foam Market | 2026-2036
Rigid Colored PU Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Colored PU Foam Market Outlook
Aftermarket refurbishment of insulation panels is reshaping margin pools away from virgin material sales toward service-led contracts. BASF SE leverages its integrated polyol supply chain to control feedstock quality across European production hubs. Huntsman Corporation anchors its competitive stance through specialized color-stable formulations for automotive seating applications. Wanhua Chemical Group Co., Ltd. dominates volume manufacturing in Asia through backward integration into MDI production.
Rigid colored PU foam denotes a closed-cell polyurethane thermoset material pigmented during the polymerization phase, typically exhibiting densities from 32 to 80 kg per cubic meter and thermal conductivity values near 0.022 W per meter-kelvin, engineered primarily for thermal insulation, structural core applications, and aesthetic surface finishing in industrial and consumer products. The application dimension shows insulation commanding the largest existing volume pool while automotive segments attract premium pricing for color-matched interior components. Among end users, construction maintains mature demand patterns whereas electronics represents a faster-growing channel driven by device miniaturization and thermal management requirements.
REACH regulations in Europe and GB standards administered by SAMR in China restrict aromatic amine content and volatile organic compound emissions from polyurethane systems, compelling reformulation investments across the supply base. EPA guidelines in the United States govern blowing agent transitions under SNAP program provisions, accelerating hydrofluoroolefin adoption. Stakeholders must monitor regulatory divergence between jurisdictions to avoid compliance cost fragmentation that could distort competitive positioning in cross-border supply arrangements.
Market Dynamics
Automotive OEMs are consolidating colored foam specifications across platform architectures, compressing supplier bases while elevating performance requirements for thermal stability and VOC emissions control.
Growth Catalysts
- REACH Phase-Out of Aromatic Amines:ECHA restrictions on certain curatives are accelerating reformulation toward aliphatic alternatives, opening premium positioning for compliant European producers.
- China's Dual Carbon Goals:MEE enforcement of lower-GWP blowing agents is retrofitting production lines and creating upgrade cycles for insulation-grade colored foam capacity.
- Automotive Interior Light-Weighting:Structural core applications in door panels and headliners are absorbing higher-density colored foam as steel substitution accelerates in electric vehicle platforms.
Market Restraints
- MDI Supply Concentration:Four producers control over 80 percent of Asian MDI supply, exposing compounders to feedstock allocation risk during maintenance turnarounds.
- Hydrofluoroolefin Cost Premium:HFO blowing agents trade at 3-4x legacy HFC prices, compressing margins on price-sensitive construction insulation contracts.
- Recyclability Ceiling:Thermoset cross-linking chemistry prevents mechanical reprocessing, limiting circular economy claims and ESG scoring in European public tenders.
Strategic Opportunities
- India's PLI Scheme for Auto Components:Domestic value-add requirements are incentivizing localized colored foam compounding for seating and trim applications.
- Electronics Thermal Management:Miniaturized 5G base stations and EV power electronics are creating demand for thin-profile, color-coded insulation cores with precise dielectric properties.
- Service-Contract Refurbishment:Industrial cold-chain operators are outsourcing insulation panel maintenance, shifting revenue from material sales to performance-guaranteed refurbishment cycles.
Industry Challenges
- Color-Matching Technical Talent:Formulation chemists capable of batch-to-batch consistency across temperature and humidity variations remain scarce in emerging manufacturing hubs.
- Multi-Jurisdiction Certification Burden:Separate fire-rating protocols for Germany (DIN), France (CSTB), and the United Kingdom (BSI) fragment product development timelines for pan-European suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Colored PU Foam Market |
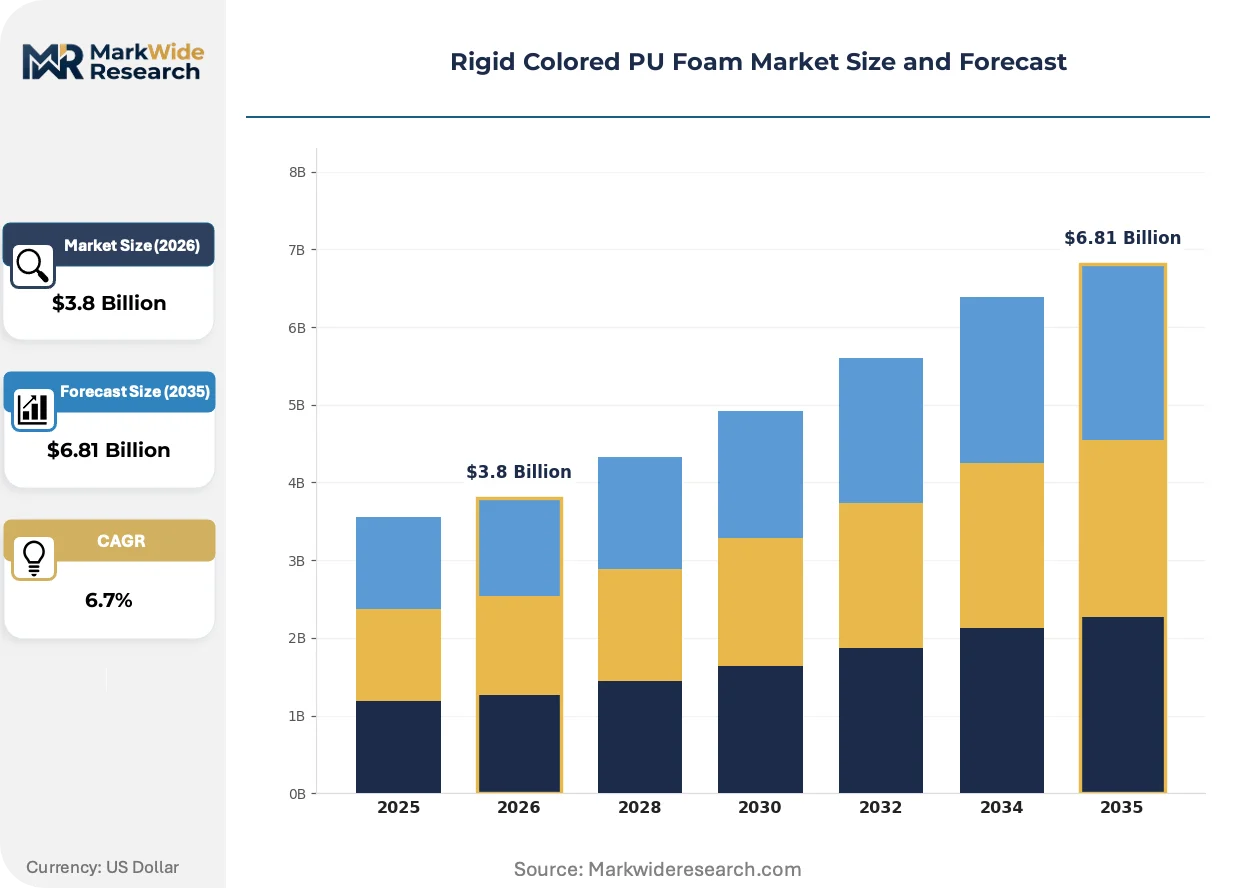
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Thermoset Foam, Rigid Foam, Structural Foam Application: Insulation, Packaging, Automotive, Furniture End User: Construction, Automotive OEMs, Electronics, Consumer Goods Form: Blocks, Sheets, Molds, Coatings |
| Companies Covered | BASF SE, Huntsman Corporation, Covestro AG, Rogers Corporation, The Dow Chemical Company, Recticel S.A., Saint-Gobain, Wanhua Chemical Group Co., Ltd., Owens Corning, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Colored PU Foam Market Strategic Shifts
Formulation science and process control are converging to enable mass-customization of aesthetic and functional properties without sacrificing the economies of scale essential to polyurethane chemistry.
Bio-based polyol content is migrating from niche certification premiums toward mainstream automotive specifications. Tier 1 seating suppliers in Germany and the United States are qualifying 20-30 percent renewable content grades for visible interior components. This migration from petrochemical dependence is compressing the cost gap with conventional formulations while satisfying OEM Scope 3 reporting requirements.
EPA SNAP program enforcement is accelerating the transition from HFC-245fa to HFO-1336mzz-Z blowing agents in U.S.-bound insulation products. The regulatory pressure is forcing capital deployment into reactor retooling and gas-handling infrastructure. Construction-grade producers serving the Pacific Northwest and Northeast corridors are absorbing the steepest compliance costs due to earlier state-level HFC phase-down deadlines.
Automotive procurement teams are consolidating colored foam specifications under platform-global contracts, displacing regional supplier fragmentation. Tier 1 seating and trim manufacturers in Michigan, Lower Saxony, and Guangdong are responding by qualifying fewer compounders per vehicle program. This concentration is most visible in premium electric vehicle architectures where color-matched interior themes span multiple continents.
Rigid Colored PU Foam Market Segmentation
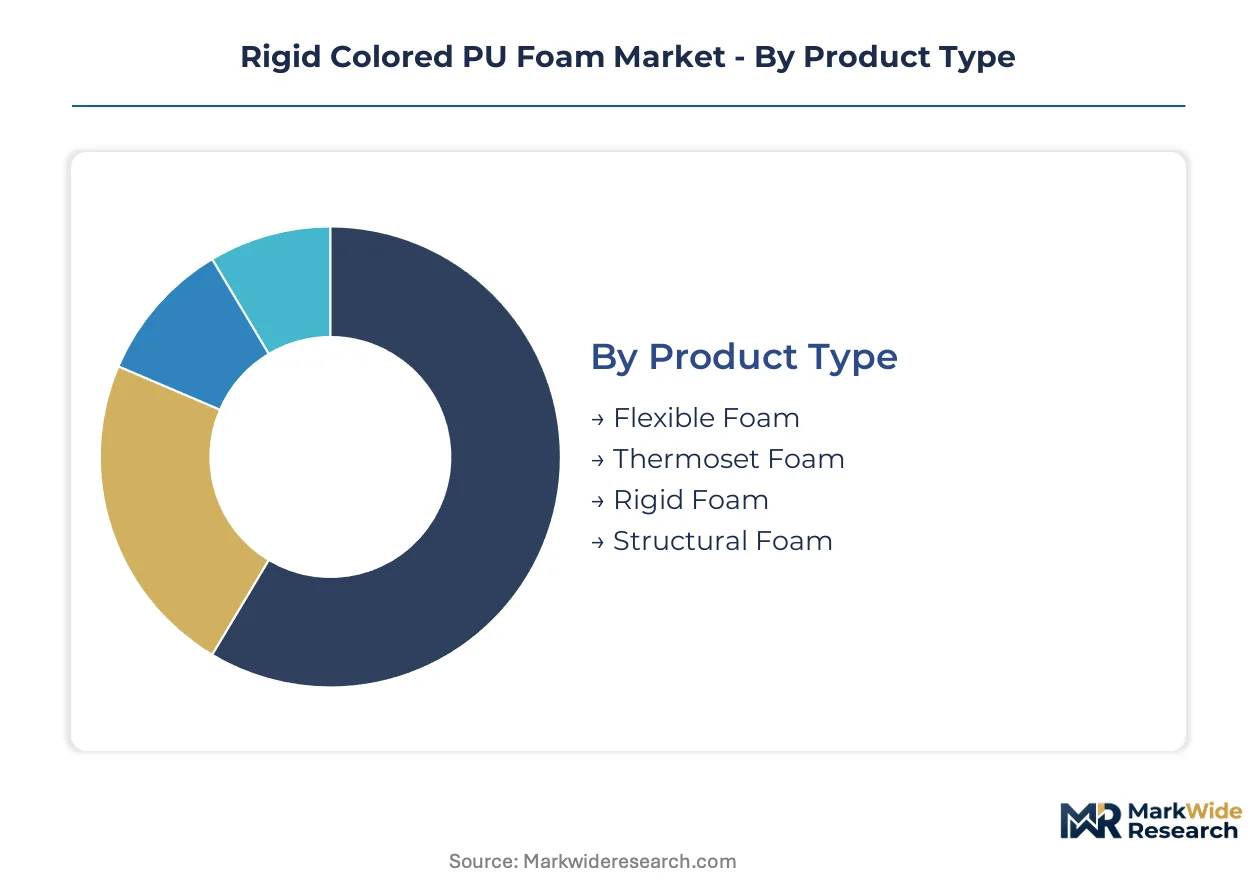
Segmentation in rigid colored PU foam reveals how formulation chemistry and delivery format determine service intensity across the value chain. After-sales refurbishment contracts cluster around specific product types and forms, reshaping vendor economics away from one-time material sales.
Product Type:
After-sales service intensity varies sharply across foam chemistries, with thermoset formulations locking in long-term maintenance relationships due to irreversible cross-linking.
- Thermoset Foam:Irreversible polymerization creates permanent dimensional stability for structural cores. German automotive OEMs specify thermoset grades for door panel inserts, generating decade-long refurbishment contracts as vehicles age in fleet service.
- Structural Foam:High-density variants (60-80 kg/m³) provide load-bearing capacity with integral coloration. Chinese EV manufacturers in Guangdong province specify structural foam for battery pack enclosures, where thermal runaway protection demands scheduled inspection protocols.
- Flexible Foam:Lower cross-link density permits some compression recovery; seating applications in furniture and automotive trim dominate procurement volumes with shorter replacement cycles.
- Rigid Foam:Standard insulation-grade formulations with closed-cell architecture serve construction and cold-chain applications where panel replacement drives aftermarket revenue.
Thermoset foam holds the largest share; momentum sits with structural foam as electric vehicle platforms multiply.
Application:
Cost tier stratification separates commodity insulation contracts from premium automotive specifications with diverging margin profiles.
- Automotive:Color-matched interior components command formulation precision for visible surfaces. Tier 1 suppliers in Michigan and Lower Saxony consolidate specifications under platform-global contracts, compressing qualified vendor lists while elevating VOC compliance requirements.
- Insulation:Construction-grade panels and cold-chain enclosures represent mature volume demand. EPA SNAP enforcement in the United States accelerates HFO-1336mzz-Z adoption, raising production costs for Pacific Northwest and Northeast corridor suppliers.
- Packaging:Protective dunnage for electronics and medical devices leverages colored foam for content identification and ESD control; shorter product lifecycles limit refurbishment potential.
- Furniture:Visible upholstery cores and accent pieces absorb pigmented formulations where aesthetic consistency drives batch-to-batch quality investment.
Insulation commands volume leadership; automotive climbs fastest on electrification-driven lightweighting.
End User:
Customer type determines procurement modality, with industrial buyers favoring service contracts and consumer channels remaining transactional.
- Construction:Cold-chain operators and building envelope specialists are outsourcing panel maintenance to compounders, shifting revenue from material sales to performance-guaranteed refurbishment cycles with multi-year terms.
- Automotive OEMs:Platform consolidation across Germany, China, and the United States reduces qualified suppliers per vehicle program while tightening thermal stability and color-matching specifications for premium electric architectures.
- Electronics:Miniaturized 5G base stations and EV power electronics demand thin-profile, color-coded insulation cores with precise dielectric properties; device manufacturers prioritize thermal management over refurbishment economics.
- Consumer Goods:Recreational equipment and household products absorb smaller batch volumes with less stringent performance certification, leaving refurbishment potential underdeveloped.
Construction anchors installed base revenue; electronics gains share fastest on thermal management proliferation.
Form:
Delivery format shapes supply chain configuration and customer touchpoint frequency, with molded geometries enabling deepest service integration.
- Molds:Complex geometries for automotive interior components and electronics housings require tool-specific expertise. BASF SE and Huntsman Corporation leverage mold design capabilities to embed sensors for predictive maintenance, extending customer relationships beyond initial shipment.
- Blocks:Bun stock for fabrication into custom shapes serves construction and packaging applications where on-site cutting and bonding creates localized value-add opportunities for distributors.
- Sheets:Laminated panels for building insulation and furniture cores travel through wholesale channels with limited direct manufacturer engagement, compressing margin capture.
- Coatings:Spray-applied or cast surface layers provide aesthetic finishing and protective skins; application equipment requirements create technical service dependencies for qualified installation networks.
Blocks dominate shipment volume; molds concentrate value capture through embedded service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys rigid colored PU foam predominantly for automotive interior acoustics and thermal cores, whereas China channels equivalent volumes into construction insulation and electric vehicle battery enclosures, revealing a consumption-mix divergence between industrialized and industrializing markets.
United States
Automotive OEMs in Michigan and the Southeast specify colored foam for electric vehicle headliners and door panels, prioritizing weight reduction. EPA SNAP program enforcement accelerates HFO-1336mzz-Z adoption, raising production costs for Pacific Northwest suppliers. Cold-chain operators in California and Texas are outsourcing insulation panel refurbishment to compounders under multi-year service contracts.
Germany
REACH restrictions on aromatic amine curatives compel reformulation toward aliphatic systems for visible interior components. Tier 1 seating suppliers in Lower Saxony consolidate specifications under platform-global contracts, compressing qualified vendor lists. BASF SE leverages its Ludwigshafen polyol supply chain to control feedstock quality across European production hubs.
China
MEE enforcement of lower-GWP blowing agents retrofits production lines for insulation-grade capacity. EV manufacturers in Guangdong province specify structural foam for battery pack enclosures, demanding scheduled inspection protocols. Wanhua Chemical Group Co., Ltd. anchors volume manufacturing through captive MDI production in Ningbo.
India
PLI scheme incentives for auto components localize colored foam compounding for seating and trim applications. BIS standards for fire-rated insulation panels tighten certification requirements for construction-grade formulations. Automotive clusters in Maharashtra and Tamil Nadu absorb growing volumes for domestic OEM platform launches.
Rigid Colored PU Foam Market Competitive Environment
Capability concentration sits with integrated chemical conglomerates possessing captive polyol supply chains; scale advantage sits with Asian producers leveraging backward integration into isocyanate feedstocks. The market structures around three archetypes: European formulation specialists commanding premium automotive specifications, Chinese volume manufacturers dominating construction insulation contracts, and diversified materials conglomerates spanning multiple polymer systems. Competitive moves center on reactor retooling for low-GWP blowing agent transitions and platform-global contract consolidation by automotive procurement teams.
Among European-based integrated producers, BASF SE and Covestro AG occupy positions defined by feedstock control and color-stable formulation expertise. Huntsman Corporation exemplifies the specialized tier focused on automotive seating applications with exacting VOC compliance requirements. Wanhua Chemical Group Co., Ltd. anchors the scale-driven segment through Ningbo-based MDI production serving Asian construction and EV markets.
| Leading Market Players |
|---|
| BASF SE |
| Huntsman Corporation |
| Covestro AG |
| Rogers Corporation |
| The Dow Chemical Company |
| Recticel S.A. |
| Saint-Gobain |
| Wanhua Chemical Group Co., Ltd. |
| Owens Corning |
| Others |
Value Chain & Pricing Dynamics
MDI supply concentration across Asian production hubs determines both pricing tier spreads and supply chain shape, compressing margin buffers for compounders during maintenance turnarounds while elevating premiums for qualified automotive specifications.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier 1 automotive suppliers and integrated compounders, insulating premium grades from spot volatility while construction insulation remains tethered to project-based bidding. Price differentiation hinges on REACH compliance certification and color-matching precision for visible interior components. Cost compression in standard insulation grades is intensifying because HFO-1336mzz-Z adoption raises input costs. Construction procurement teams exhibit highest price sensitivity; automotive OEMs prioritize thermal stability and VOC control over unit economics.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculations for European automotive compounders sourcing MDI from Ningbo production hubs. Feedstock supply concentrates in China, Germany, and the United States, with isocyanate production drawing from benzene and aniline derivatives. Single-source vulnerability persists for specialized aliphatic curatives compliant with ECHA restrictions. Distribution runs through qualified Tier 1 converter networks for automotive applications and regional distributor channels for construction-grade blocks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-global contract consolidation by automotive procurement teams is creating winner-take-most dynamics, rewarding compounders with cross-continental formulation consistency and embedded sensor capabilities for predictive maintenance.
For Market Incumbents: Build captive polyol supply moats through backward integration into propylene oxide and MDI production, defending against Wanhua Chemical's cost advantages in Asian construction markets. Anchor platform-global contracts by qualifying color-stable formulations across Michigan, Lower Saxony, and Guangdong clusters simultaneously. Prioritize reactor retooling for HFO-1336mzz-Z compliance ahead of EPA SNAP enforcement deadlines in Pacific Northwest and Northeast corridors. For New Entrants and Emerging Players: Pursue electronics thermal management white space where miniaturized 5G base stations and EV power electronics demand thin-profile, color-coded insulation cores with dielectric precision. India's PLI scheme for auto components offers the most penetrable entry point, with domestic value-add requirements forcing localization of seating and trim compounding. Lead with technical service bundling rather than price competition to bypass incumbent volume advantages. For Investors and Strategic Acquirers: REACH Phase-Out of aromatic amines reshapes the acquisition landscape toward aliphatic formulation specialists with existing automotive qualifications. Five-to-ten year viability favors compounders with demonstrated batch-to-batch color consistency across humidity and temperature variations. Target acquisition archetype: mid-scale European formulators with platform-global contracts and captive polyol supply agreements. The signal to watch is OEM consolidation of qualified supplier lists per vehicle program, which accelerates roll-up economics for compliant assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Production | Wanhua Chemical's Ningbo captive supply anchors cost leadership in Asian construction markets. |
| Reactor Retooling for HFO-1336mzz-Z | EPA SNAP enforcement in Pacific Northwest and Northeast corridors accelerates compliance capital deployment. |
| Platform-Global Contract Consolidation | Tier 1 seating suppliers in Michigan and Lower Saxony compress qualified vendor lists per electric vehicle architecture. |
| Embedded Sensor Integration for Predictive Maintenance | BASF and Huntsman leverage mold design capabilities to extend customer relationships beyond initial shipment. |
| Aliphatic Formulation Qualification | ECHA restrictions on aromatic amine curatives open premium positioning for compliant European producers. |
Study Parameters
Operator-level perspectives from plant managers at polyurethane compounding facilities, procurement leads at Tier 1 automotive seating suppliers, distribution channel partners serving construction insulation markets, and technical R&D directors specializing in color-stable formulations anchored the qualitative base. Primary interview findings were cross-validated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical conglomerates, and vehicle production databases from IHS Markit. Bottom-up volume modeling across formulation grades was triangulated with top-down market sizing from macro-industrial indicators.
Scenario-bracketing around blowing agent transition timelines and automotive electrification penetration shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include thermoset versus structural versus flexible foam chemistries, automotive versus insulation versus electronics applications, and molded versus block versus sheet delivery formats. CAGRs were derived from elasticity-adjusted demand curves incorporating OEM platform launch schedules and construction permit flows. Industry-specific forecast inputs encompassed MEE enforcement intensity for lower-GWP blowing agents in China and REACH aromatic amine restriction implementation pace in Europe.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, construction investment cycles, or isocyanate feedstock pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory phase-down schedules and platform-global contract consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Paper Processing Resins Market