
 Construction Polymer Market | 2026-2036
Construction Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Polymer Market Analysis
Skilled polymer compounding expertise is bifurcating the competitive landscape as formulation chemistry becomes decisive for thermal and mechanical performance. BASF SE leverages its integrated R&D pipeline across polyurethane systems to sustain technology leadership in insulation applications. Dow Inc. anchors North American supply chains through captive ethylene production and downstream construction polymer derivatives. Solvay S.A. differentiates via specialty thermosetting formulations that serve high-temperature infrastructure environments.
Construction polymers encompass thermoplastics, thermosetting polymers, blends, and composites engineered for load-bearing, weatherproofing, and thermal management functions in built structures, typically formulated with melt indices between 0.2 and 50 g/10 min and tensile strengths ranging from 20 to 80 MPa depending on end-use requirements. Polyvinyl chloride dominates piping and window profile applications due to decades of building code entrenchment and cost-efficient extrusion processing. Polyurethane captures expanding margin pools in spray-foam insulation and structural adhesives as energy-efficiency standards tighten across residential and commercial end users. Thermosetting polymers retain structural rigidity advantages in composite reinforcement for industrial infrastructure despite longer cure cycles and higher labor intensity.
REACH in Europe, the EPA under the Toxic Substances Control Act in the United States, and BIS certification requirements in India collectively restrict phthalate plasticizer content and mandate flame-retardant performance thresholds for interior applications. These frameworks compel reformulation investments and create compliance moats for producers with established testing infrastructure and regulatory affairs capabilities. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions and bio-based feedstock qualification standards as these emerging rules will determine polymer sourcing strategies and capital allocation priorities.
Market Dynamics
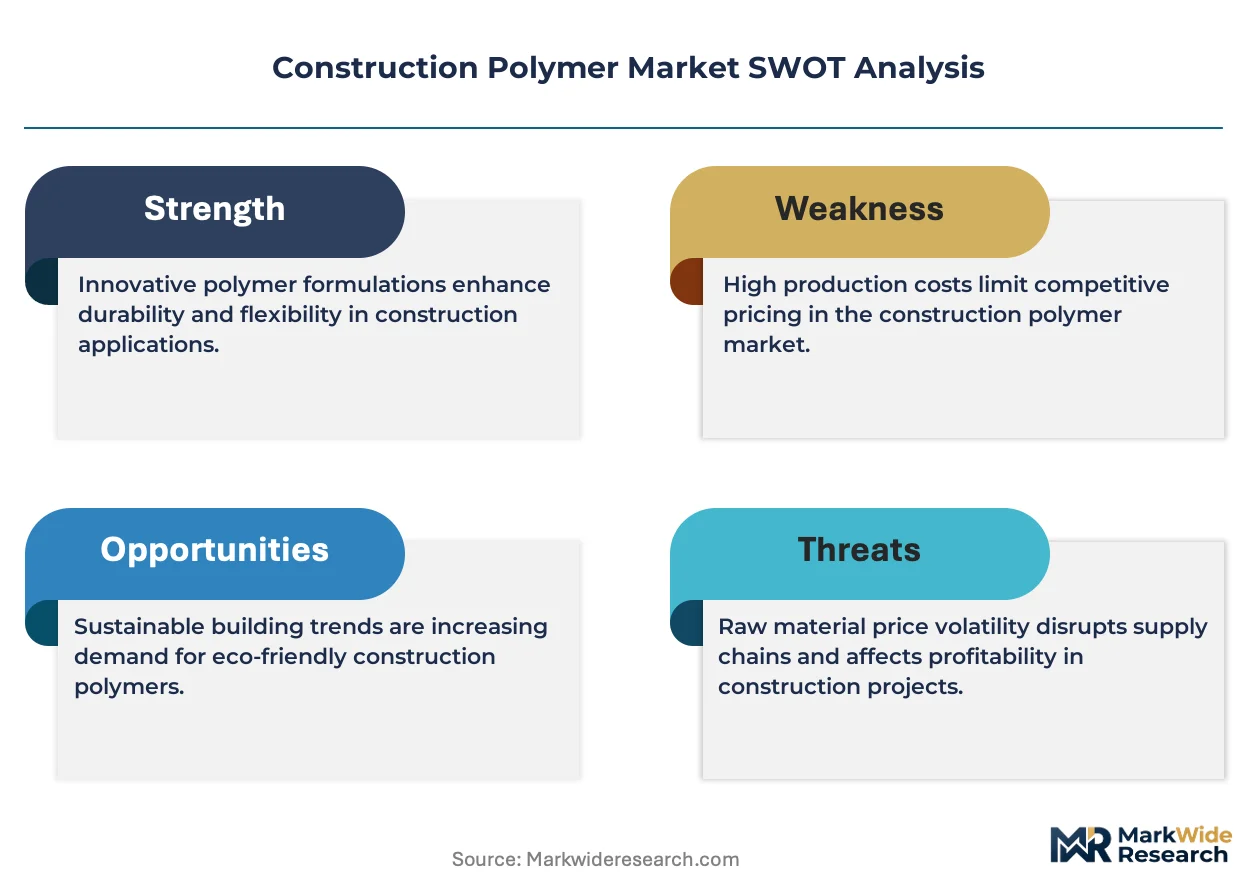
Energy-efficiency mandates across residential and commercial building codes are compressing specification cycles for thermal insulation systems and forcing rapid reformulation of legacy polymer chemistries.
Growth Catalysts
- REACH compliance deadlines in Europe:Phased restrictions on phthalate plasticizers are compelling building material suppliers to qualify bio-based alternatives ahead of enforcement windows.
- Spray-foam insulation contractors:Tightening envelope-performance standards in cold-climate jurisdictions are accelerating polyurethane system adoption for retrofit and new-build applications.
- Composite reinforcement in industrial infrastructure:Thermosetting polymer demand is concentrating in corrosion-resistant piping and structural members for chemical processing facilities.
Market Restraints
- Propylene and benzene feedstock volatility:Crude oil price swings transmit directly to aromatic polymer input costs, compressing margin visibility for compounders without captive cracking capacity.
- Specialty additive supply concentration:Flame-retardant masterbatch production clusters in China and Germany, creating single-source exposure for North American extrusion compounders.
- Cure-cycle limitations of thermosets:Extended setting times for epoxy and polyurethane systems restrict on-site productivity versus thermoplastic welding or mechanical fastening.
Strategic Opportunities
- India's commercial construction acceleration:BIS certification requirements for fire-rated interior materials are creating first-mover advantage for compounders with established testing infrastructure.
- Building-integrated photovoltaic mounting systems:Polymer composite frames and junction-box housings are penetrating solar rooftop installations as metal fatigue and corrosion costs mount.
- EU Green Deal renovation wave incentives:Member-state subsidy programs for deep-energy retrofits are expanding addressable demand for high-R-value insulation systems.
Industry Challenges
- Polymer compounding talent scarcity:Formulation chemistry expertise in reactive extrusion and additive synergies is concentrating at a handful of specialized technical institutes.
- Multi-jurisdiction certification timelines:Simultaneous EPA TSCA pre-manufacture notices, REACH dossier submissions, and BIS factory audits extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Polymer Market |
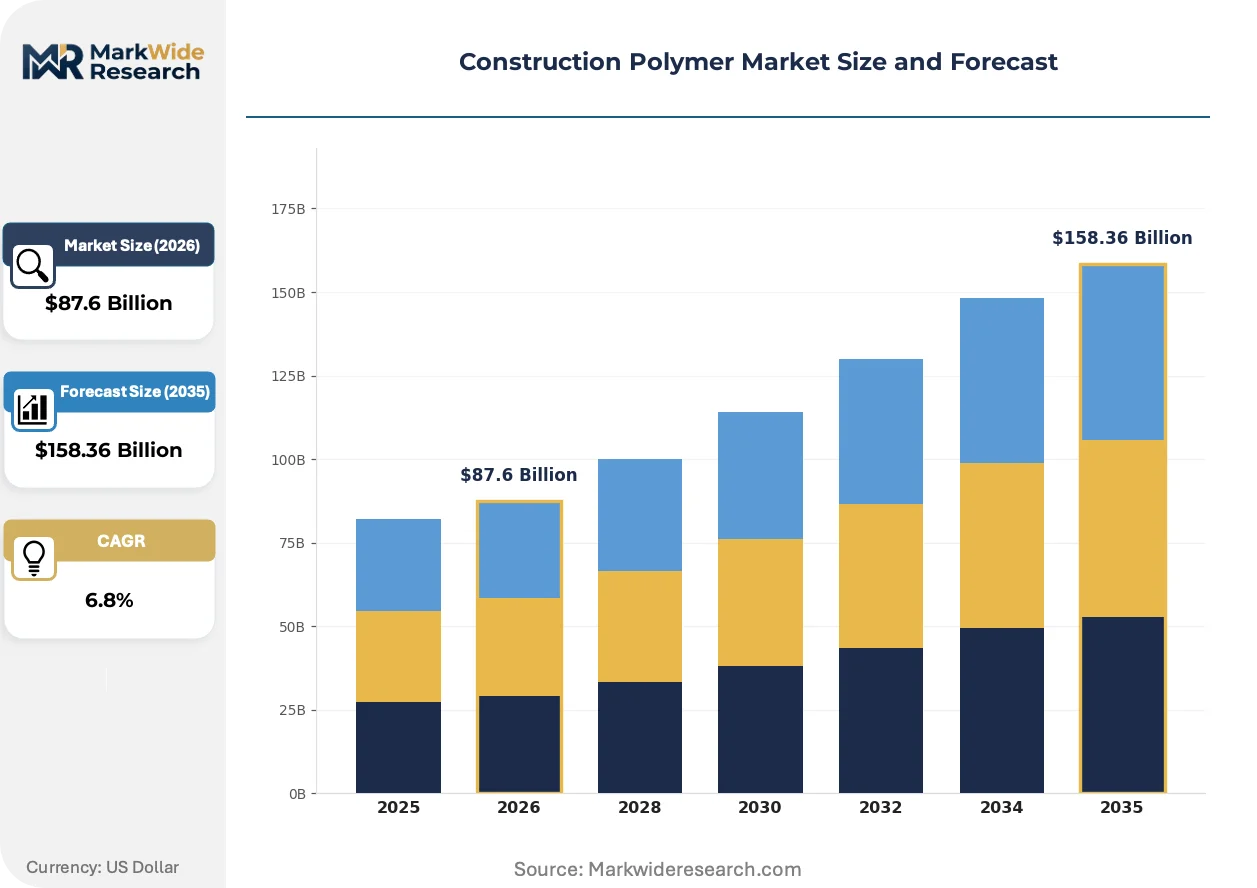
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Polyethylene, Polyurethane, Polystyrene Application: Sealants, Adhesives, Coatings, Insulation End User: Residential, Commercial, Industrial, Infrastructure Material Type: Thermoplastics, Thermosetting Polymers, Blends, Composites |
| Companies Covered | LyondellBasell Industries, Solvay S.A., BASF SE, Borealis AG, INEOS Group AG, Dow Inc., Arkema S.A., Evonik Industries AG, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Polymer Market Emerging Trajectories
Bio-based feedstock qualification and circular-material traceability systems are redefining polymer specification criteria across institutional procurement channels.
Recycled-content polyethylene terephthalate is displacing virgin polyvinyl chloride in non-pressure piping applications. Municipal water authorities in Germany and California are mandating minimum recycled thresholds for storm-drain and conduit specifications. This displacement is compressing demand for legacy extrusion-grade PVC compounds and forcing integrated producers to reallocate chlor-alkali capacity.
EPA enforcement discretion on per- and polyfluoroalkyl substances is narrowing ahead of anticipated drinking-water maximum contaminant levels. Fluoropolymer membrane and coating suppliers are accelerating fluorine-free alternative qualification for roofing and geotextile applications. Commercial roofing contractors in the US Northeast are piloting silicone-modified acrylic systems as substitution hedges.
Consolidated general-contractor procurement desks are unbundling material specification from installation labor. Large-scale multifamily developers in China and the United Kingdom are issuing master supply agreements directly to polymer compounders, bypassing traditional distributor networks. This disintermediation is compressing channel margins and forcing formulation houses to build captive logistics capabilities for jobsite delivery.
Construction Polymer Market Segmentation
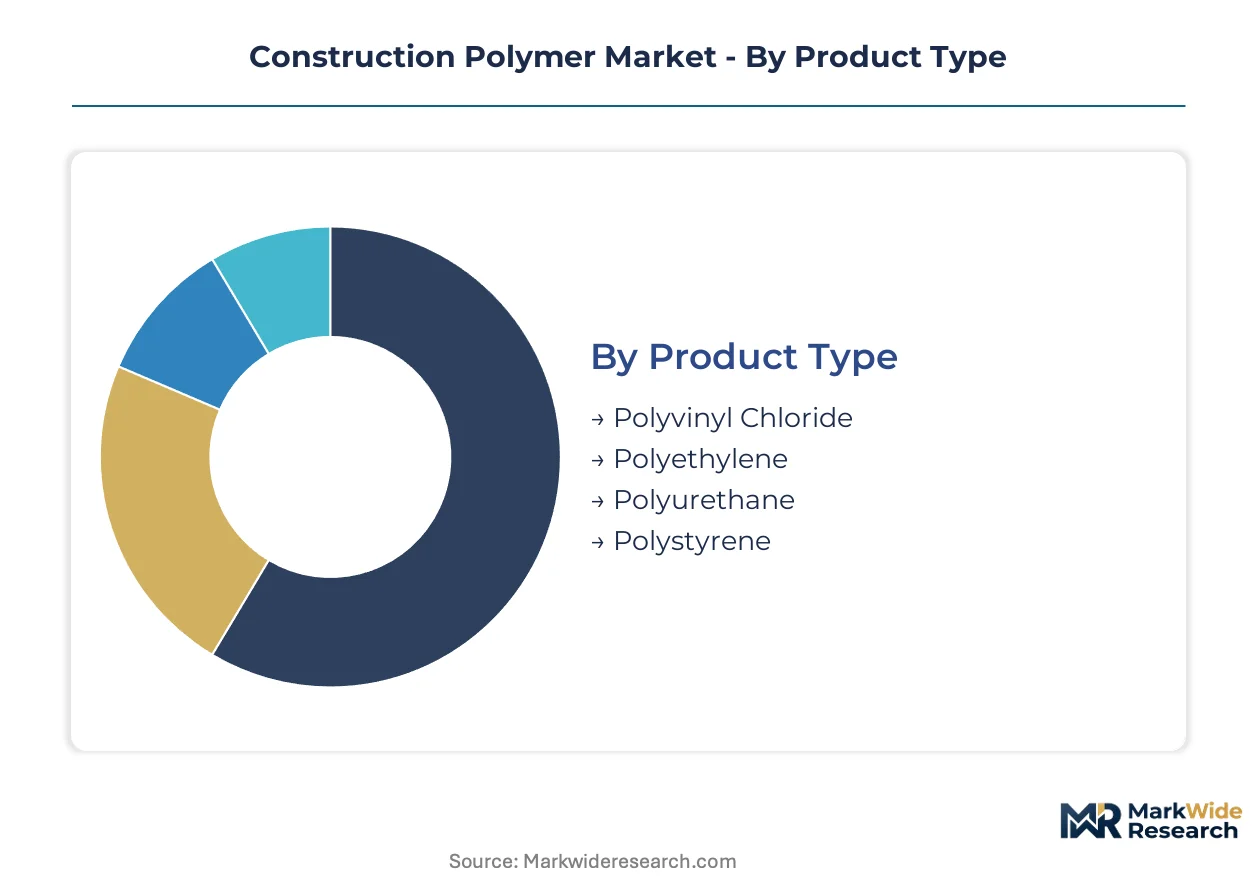
Construction polymer procurement decisions bifurcate along performance specifications versus cost thresholds, with material chemistry and end-use liability exposure determining specification authority across project types. Segmentation clarity enables compounders to align formulation investments with code-mandated performance tiers and regional certification requirements.
Product Type:
Substitution pressure concentrates in commodity thermoplastics where recycled-content polyethylene terephthalate challenges legacy polyvinyl chloride in non-pressure piping specifications across Germany and California municipal procurement.
- Polyvinyl Chloride:Chlorinated hydrocarbon backbone delivers flame-retardant performance and decades of building code entrenchment in window profiles and pressure piping. Demand concentrates in North American residential fenestration and Indian municipal water infrastructure as cost-efficient extrusion processing sustains specification dominance despite bio-based challenger compounds.
- Polyurethane:Isocyanate-polyol reactive systems capture expanding specification share in spray-foam insulation and structural adhesives as energy-efficiency mandates tighten envelope-performance standards in cold-climate jurisdictions across Canada and Scandinavia.
- Polyethylene:Linear low-density grades serve geomembrane and conduit applications with superior chemical resistance versus PVC in aggressive soil environments.
- Polystyrene:Expandable bead and extruded foam formats dominate rigid board insulation for below-grade and cavity-wall applications where compressive strength requirements are moderate.
Polyvinyl chloride anchors the volume base while polyurethane gains share at the steepest rate.
Application:
Margin tiering separates specification-grade systems with certified fire performance from commodity formulations serving non-structural fill applications.
- Insulation:Closed-cell polyurethane and extruded polystyrene systems deliver thermal resistance values critical to deep-energy retrofit economics and net-zero building code compliance. Demand concentrates in EU member-state renovation wave subsidies and Canadian cold-climate residential construction as R-value-per-inch performance dictates material selection.
- Sealants:Moisture-cure polyurethane and silicone formulations accommodate joint movement in curtainwall and expansion joint applications. Specification authority rests with facade engineering consultants in high-rise commercial towers across Singapore and Dubai where wind-load and thermal-cycling performance carry liability exposure.
- Adhesives:Reactive polyurethane and epoxy systems bond engineered wood products and composite structural members in prefabricated construction modules.
- Coatings:Fluoropolymer and polyurethane membrane systems protect roofing and waterproofing substrates with elastomeric recovery and UV stability.
Insulation commands the highest formulation complexity premium while sealants expand most quickly with facade performance standard escalation.
End User:
Customer-type concentration determines certification burden intensity, with infrastructure and commercial segments imposing multi-jurisdiction testing requirements that commodity residential suppliers cannot absorb.
- Infrastructure:Corrosion-resistant piping, geosynthetics, and composite structural members serve chemical processing facilities and transportation assets with 50-year design life requirements. Demand concentrates in China's petrochemical corridor and German water utility networks as asset-owner engineering standards specify thermosetting polymer composites over metallic alternatives.
- Commercial:High-performance envelope systems and interior finish materials face stringent fire-rating and VOC-emission protocols in institutional and high-occupancy buildings. BIS certification requirements in India and EPA TSCA pre-manufacture notices in the United States extend qualification timelines for compounders serving this segment.
- Residential:Cost-optimized insulation and fenestration materials compete on installed cost per thermal performance unit in single-family and multifamily construction.
- Industrial:Chemical-resistant tank linings, flooring systems, and secondary containment structures serve manufacturing facilities with aggressive process chemistries.
Infrastructure anchors specification-grade volume while commercial climbs the fastest with green building code proliferation.
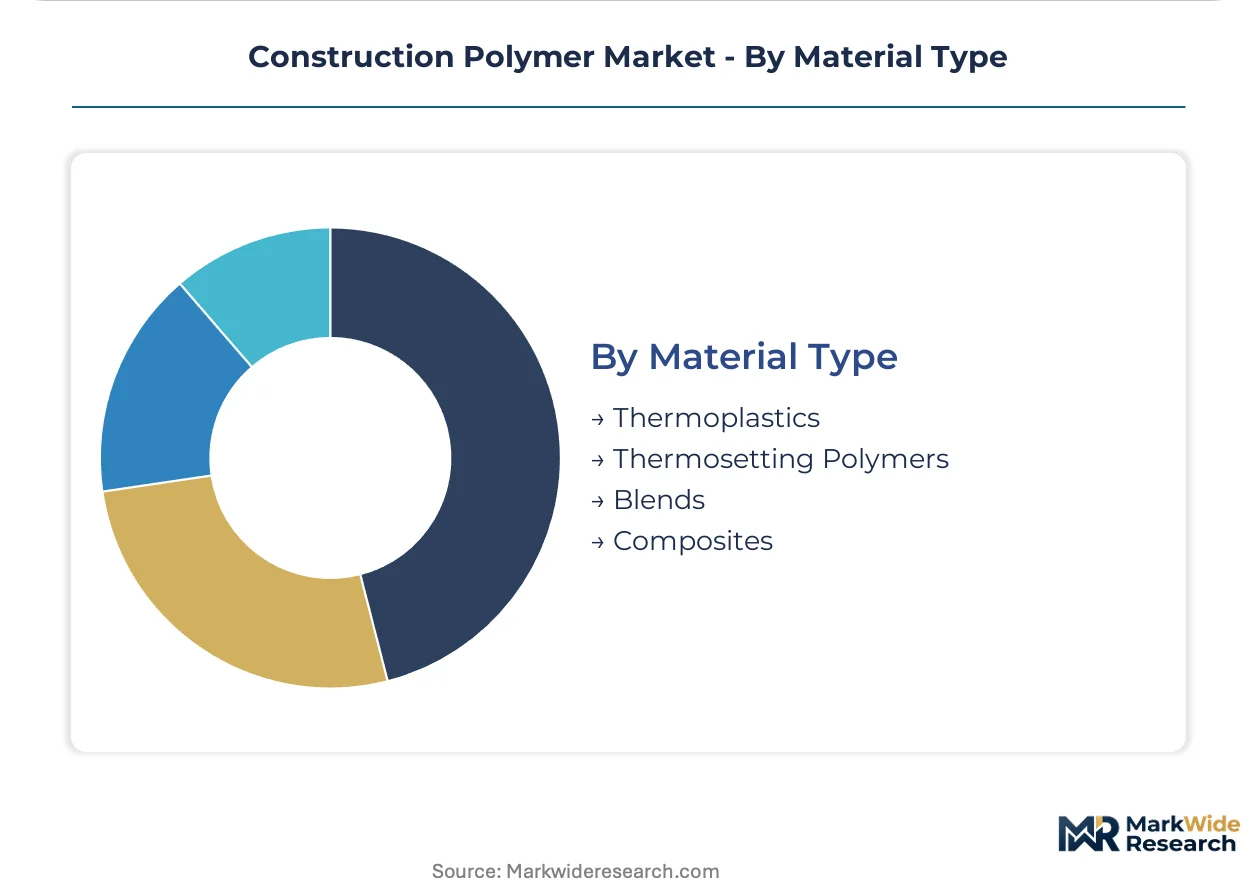
Material Type:
Processing economics and structural performance requirements segment the market between reprocessable thermoplastics and dimensionally stable thermosetting systems.
- Thermoplastics:Melt-processable polymers including PVC, polyethylene, and polystyrene enable extrusion, injection molding, and thermoforming with scrap recycling and reprocessing. Demand concentrates in high-volume piping and profile extrusion across Chinese manufacturing clusters and US Gulf Coast compounders with captive resin supply.
- Thermosetting Polymers:Cross-linked epoxy, polyurethane, and unsaturated polyester systems deliver structural rigidity and chemical resistance for composite reinforcement and high-performance coatings. Cure-cycle limitations restrict on-site productivity but sustain specification in corrosion-critical infrastructure across Saudi petrochemical facilities and Singapore marine terminals.
- Blends:Alloyed polymer systems combine processability and performance characteristics for specialized applications requiring intermediate properties.
- Composites:Fiber-reinforced thermoset and thermoplastic matrices serve structural members with high strength-to-weight ratios in bridge decks and building-integrated photovoltaic mounting systems.
Thermoplastics dominate production tonnage while thermosetting polymers capture the steepest specification premium escalation with infrastructure durability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH enforcement timelines anchor European reformulation investments while BIS certification requirements and China's dual carbon goals reshape procurement patterns across Asia-Pacific manufacturing clusters.
China
Dual carbon targets accelerate polyurethane system adoption for high-performance building envelopes in cold-climate provinces. MIIT guidelines on green building materials mandate recycled-content thresholds for municipal infrastructure tenders. Manufacturing gravity concentrates in Yangtze River Delta extrusion clusters serving domestic fenestration and export piping markets.
Germany
EU Green Deal renovation wave subsidies expand addressable demand for spray-foam insulation in deep-energy retrofits of post-war residential stock. ECHA phased restrictions on phthalate plasticizers compel compounders to qualify bio-based alternatives ahead of enforcement windows. Industrial demand clusters in North Rhine-Westphalia chemical processing corridors specifying thermosetting composites for corrosion-resistant infrastructure.
India
Commercial construction acceleration in Mumbai and Delhi-NCR drives specification-grade polymer procurement for high-occupancy buildings. BIS fire-rating certification requirements for interior materials create compliance moats for compounders with established testing infrastructure. Manufacturing capacity concentrates in Gujarat petrochemical complexes feeding piping and profile extrusion for municipal water networks.
United States
EPA TSCA pre-manufacture notice requirements extend qualification timelines for commercial building material suppliers. Tightening envelope-performance standards in Minnesota and Wisconsin accelerate closed-cell polyurethane adoption for residential retrofit contractors. Gulf Coast ethylene production anchors captive supply chains for downstream construction polymer derivatives.
Saudi Arabia
NEOM construction timelines drive demand for corrosion-resistant thermosetting composites in chemical processing and marine terminal infrastructure. The country's national industrial regulator mandates flame-retardant performance thresholds for high-occupancy institutional buildings. Eastern Province petrochemical facilities supply specialized epoxy and unsaturated polyester formulations for infrastructure durability specifications.
Construction Polymer Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive feedstock capacity and regulatory affairs infrastructure determining competitive position. Integrated petrochemical majors leverage backward integration into ethylene and propylene production to secure margin visibility against aromatic feedstock volatility. Specialist compounders concentrate formulation expertise in reactive extrusion and additive synergies. Dominant competitive moves include capacity expansion in high-growth geographies and strategic partnerships with spray-foam insulation contractors for specification capture.
Among European-headquartered chemical conglomerates, BASF SE, Solvay S.A., and Evonik Industries AG exemplify distinct strategic archetypes. BASF SE occupies a position anchored by integrated R&D pipelines across polyurethane systems. Solvay S.A. represents specialty thermosetting formulation capabilities serving high-temperature infrastructure environments. Evonik Industries AG sits within the performance materials tier with additive and specialty resin expertise. These three entities collectively illustrate how regulatory compliance infrastructure and captive technology platforms separate premium-tier compounders from commodity resin suppliers.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Solvay S.A. |
| BASF SE |
| Borealis AG |
| INEOS Group AG |
| Dow Inc. |
| Arkema S.A. |
| Evonik Industries AG |
| SABIC |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for aromatic feedstock lock in margin visibility for integrated compounders while exposing non-integrated processors to benzene and propylene volatility. This contract structure concentrates pricing power with Gulf Coast and Middle Eastern producers possessing captive cracking capacity.
Pricing Analysis
Regional price spreads between Asia-Pacific manufacturing clusters and European formulation houses exceed transport-adjusted differentials due to REACH compliance cost absorption. Three-tier pricing structure across specification-grade, certified-standard, and commodity-economy levels segments procurement desks by liability exposure. Pricing pressure stems from recycled-content polyethylene terephthalate displacement of virgin PVC in German and Californian municipal piping tenders. Residential fenestration contractors exhibit highest price sensitivity while infrastructure asset owners prioritize 50-year lifecycle cost over unit pricing.
Supply Chain Analysis
Strait of Malacca transit underwrites feedstock delivery schedules for Southeast Asian polyurethane system houses serving Chinese fenestration manufacturers. Manufacturing gravity centers on China, Germany, and the United States for extrusion-grade compounds. Formulation chemistry draws from Saudi Arabian ethylene derivatives, German specialty additive masterbatches, and Indian phthalate-alternative plasticizers. Single-source vulnerability concentrates in Chinese flame-retardant masterbatch production. Distribution runs through consolidated general-contractor procurement desks in China and the United Kingdom that disintermediate traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent compounders face substitution defense imperatives as bio-based challengers and recycled-content mandates erode specification authority in legacy thermoplastic segments.
For Market Incumbents: Compound formulation expertise in reactive extrusion and additive synergies to sustain technology leadership against bio-based challenger compounds. Deepen backward integration into ethylene and propylene production to secure margin visibility against aromatic feedstock volatility. Prioritize captive regulatory affairs infrastructure to compress multi-jurisdiction certification timelines that currently extend product launches.
For New Entrants and Emerging Players: BIS certification fast-track investments in India create first-mover positioning in commercial construction acceleration corridors around Mumbai and Delhi-NCR. White-space concentration exists in spray-foam insulation contractor partnerships across Canadian cold-climate jurisdictions where envelope-performance standards tighten. Target building-integrated photovoltaic mounting system specifications as metal fatigue costs drive polymer composite adoption in solar rooftop installations.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compounders with established testing infrastructure and regulatory affairs capabilities serving infrastructure and commercial end users. Long-term viability favors specialists with formulation chemistry expertise concentrated at technical institutes rather than commodity resin suppliers. Acquisition target archetype: mid-cap compounders with REACH dossier submission track records and captive additive blending capacity. Monitor ECHA phased restriction enforcement timelines as inflection indicator for bio-based alternative qualification urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Production | Gulf Coast producers secure margin visibility against benzene and propylene feedstock volatility. |
| REACH Dossier Submission Investment | European compounders build compliance moats ahead of phthalate plasticizer enforcement windows. |
| Spray-Foam Insulation Contractor Partnership | Polyurethane system houses capture specification authority in Canadian cold-climate retrofit markets. |
| BIS Certification Infrastructure Buildout | Compounders establish testing capabilities for Indian commercial construction fire-rating requirements. |
| Recycled-Content PET Capacity Expansion | Producers displace virgin PVC in German and Californian municipal non-pressure piping tenders. |
Methodological Framework
Initial hypotheses were tested against primary input from polymer compounding technical directors, procurement leads at downstream construction OEMs, spray-foam insulation contractors, and regulatory affairs specialists at multinational chemical conglomerates and refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA REACH dossier submissions. Bottom-up volume estimates from segment-level demand modeling were triangulated against top-down macroeconomic construction spending projections.
Variance decomposition across product type, application, end user, material type, and regional production hub dimensions anchored the analytical framework. CAGRs were derived from slope estimates fitted to segment-level volume trajectories across the projection horizon. Industry-specific forecast inputs included energy-efficiency mandate adoption curves by jurisdiction and dual carbon target implementation timelines for Chinese provincial building codes.
Decision-makers should treat outputs as directional under assumptions of sustained infrastructure investment intensity and regulatory enforcement continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as per- and polyfluoroalkyl substance restrictions and bio-based feedstock qualification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Smart Polymers Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Middle East Polycarbonate (PC) Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
North America Engineering Plastics Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
C5 Resin Market