
 Global Silicone Surfactants Market | 2026-2036
Global Silicone Surfactants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Silicone Surfactants Market Foresight
Specialized polymer chemist availability is unwinding as a bottleneck across European and North American manufacturing bases. Dow Inc. sustains broad silicone surfactant capacity through backward integration into siloxane feedstocks. Wacker Chemie AG anchors German production with dedicated facilities supplying personal care and textile formulators. Evonik Industries AG differentiates through modified silicone architectures targeting high-performance coatings applications.
Silicone surfactants are amphiphilic compounds built on siloxane backbones with hydrophilic grafts, typically exhibiting surface tensions below 25 mN/m and thermal stability past 150°C; manufacturers graft polyethylene oxide or polypropylene oxide chains onto polydimethylsiloxane cores via hydrosilylation to achieve controlled hydrophilic-lipophilic balance for wetting, foaming, or defoaming functions. Silicone copolymers occupy the largest product-type position due to their versatility across emulsion stabilization and pigment dispersion tasks. Wetting agents represent the fastest-growing application category as waterborne coatings and ink formulations displace solvent-based systems in automotive and architectural end uses.
EPA toxicity screening protocols and REACH substance evaluation under ECHA are elevating analytical and registration costs for silicone surfactant importers into the United States and European Union. China's MEE enforces discharge standards that favor biodegradable silicone glycol variants in textile processing hubs along the Yangtze River basin. Formulators and raw material procurement teams must track evolving substance restriction timelines to anticipate reformulation mandates and qualify alternative chemistries ahead of compliance deadlines.
Market Dynamics
REACH substance evaluation under ECHA and EPA toxicity screening protocols are compressing product approval timelines, forcing formulators to pre-qualify alternative silicone architectures before existing chemistries face restriction.
Growth Catalysts
- Waterborne coatings transition:Automotive and architectural formulators in Germany and the United States are substituting solvent-based systems with silicone-stabilized aqueous dispersions to meet volatile organic compound limits.
- REACH compliance preparation:European personal care manufacturers are stockpiling high-purity silicone surfactants ahead of anticipated substance restriction timelines, creating pull-through for certified grades.
- Siloxane feedstock security:Backward integration into methylchlorosilane precursors is insulating major producers from chlorosilane price volatility that disrupts specialty surfactant availability.
Market Restraints
- Siloxane monomer concentration:Four producers control over three-quarters of dimethylsiloxane capacity, concentrating price-setting power for surfactant manufacturers dependent on merchant supply.
- Fluorosurfactant substitution in high-performance coatings:Perfluorinated wetting agents retain performance advantages in critical aerospace and semiconductor cleaning applications where silicone alternatives fail thermal stability thresholds.
- ECHA evaluation costs:REACH registration dossier updates for silicone glycol copolymers are consuming technical resources that smaller formulators cannot absorb without consortium participation.
Strategic Opportunities
- India textile processing expansion:Surat and Tiruppur dyeing clusters are adopting silicone-based fiber lubricants as water efficiency mandates intensify under the country's zero liquid discharge framework.
- Biodegradable silicone glycol variants:China's MEE discharge standards along the Yangtze River basin are creating preferential procurement terms for surfactants demonstrating enhanced aquatic biodegradation profiles.
- Personal care clean-label convergence:Formulators combining silicone conditioning performance with natural-derived emulsifier claims are capturing shelf space in Sephora and Ulta Beauty retail channels.
Industry Challenges
- Specialized polymer chemist scarcity:Hydrosilylation expertise required for controlled HLB silicone synthesis is concentrating at German and Swiss technical universities, constraining R&D expansion elsewhere.
- Multinational certification synchronization:Divergent EPA, ECHA, and NMPA substance notification timelines are forcing parallel track development programs that duplicate toxicology study expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Silicone Surfactants Market |
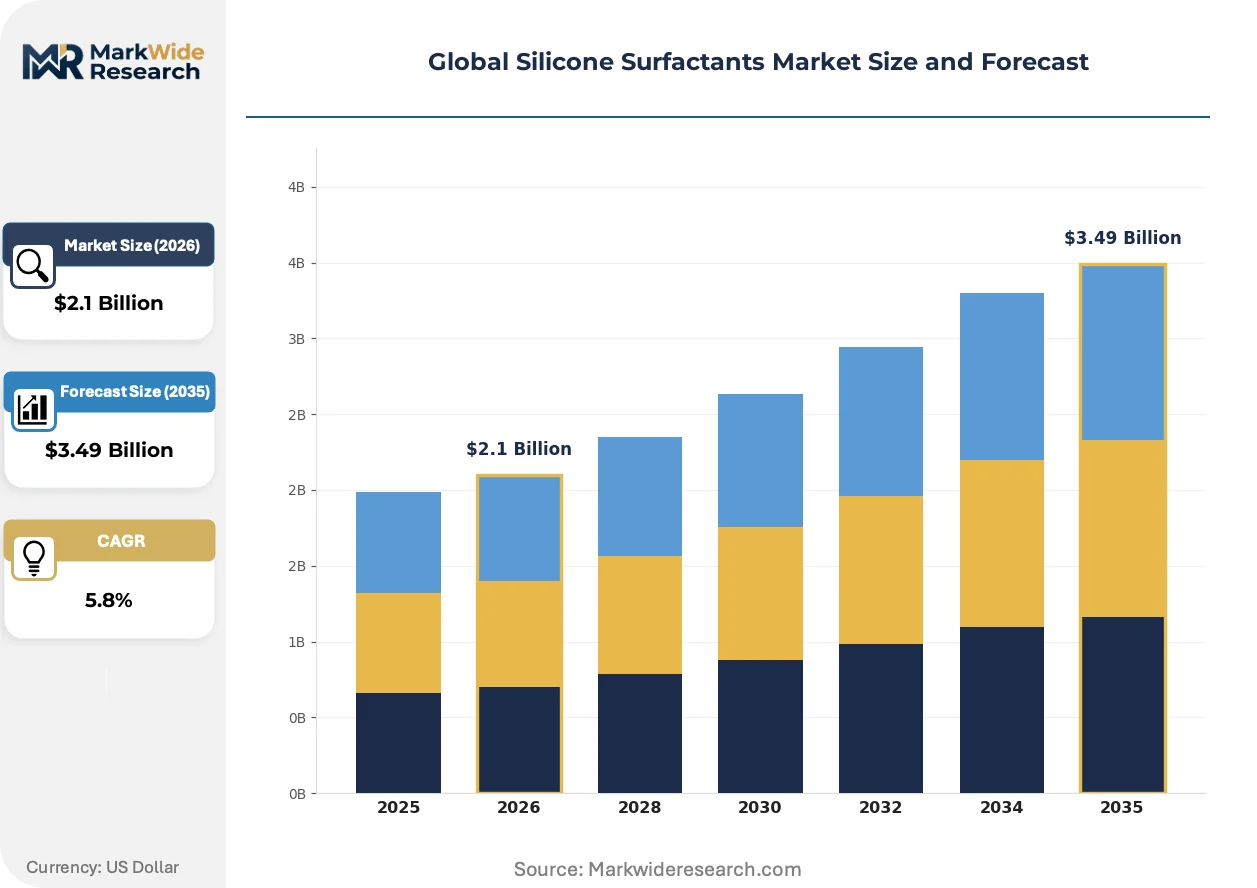
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.49 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Emulsions, Silicone Copolymers, Silicone Quaternary Ammonium Compounds, Silicone Glycols, Modified Silicones End Use Industry: Personal Care, Textile Processing, Agriculture, Paints & Coatings, Paper Production Application: Emulsifying Agents, Anti-Foaming Agents, Dispersing Agents, Wetting Agents, Conditioning Agents Distribution Channel: Direct Sales, Third-Party Distributors, Online Platforms, Industrial Suppliers, Specialty Chemical Retailers |
| Companies Covered | Elkem Silicones, Wacker Chemie AG, Dow Inc., Siltech Corporation, Innospec, Momentive, Shin-Etsu Chemical Co., Ltd., Supreme Silicones, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Silicone Surfactants Market Shifts & Advancements
Silicone surfactant architecture is fragmenting into performance-optimized variants as end-use specifications diverge, while regulatory pressure accelerates substitution chemistry development.
Modified polydimethylsiloxane copolymers with precisely grafted polyethylene oxide chain lengths are bifurcating the market between premium wetting agents for inkjet inks and economy emulsifiers for industrial lubricants. Japanese automotive coating formulators at Kansai Paint and Nippon Paint are specifying narrow molecular weight distributions for robotic spray applications. This technology is compressing margins for undifferentiated silicone glycol producers while expanding addressable value for precision polymer architects.
EPA's expanded TSCA Section 6 authority over persistent, bioaccumulative, and toxic substances is elevating analytical burden for silicone surfactant importers into the United States. Industrial chemical distributors are demanding pre-certified inventory from European suppliers to avoid customs detention risk. Waterborne architectural coatings segments are most affected, with formulators in California and New York accelerating qualification of alternative silicone-free wetting systems.
Direct procurement relationships between agrochemical multinationals and silicone surfactant producers are displacing traditional distributor intermediaries in crop protection formulation. Bayer CropScience and Syngenta are negotiating multi-year supply agreements specifying active ingredient compatibility testing protocols. This pattern is most visible in Brazil's Mato Grosso soybean belt, where local formulators now source silicone adjuvants through parent-company global tenders rather than regional chemical distributors.
Global Silicone Surfactants Market Segmentation
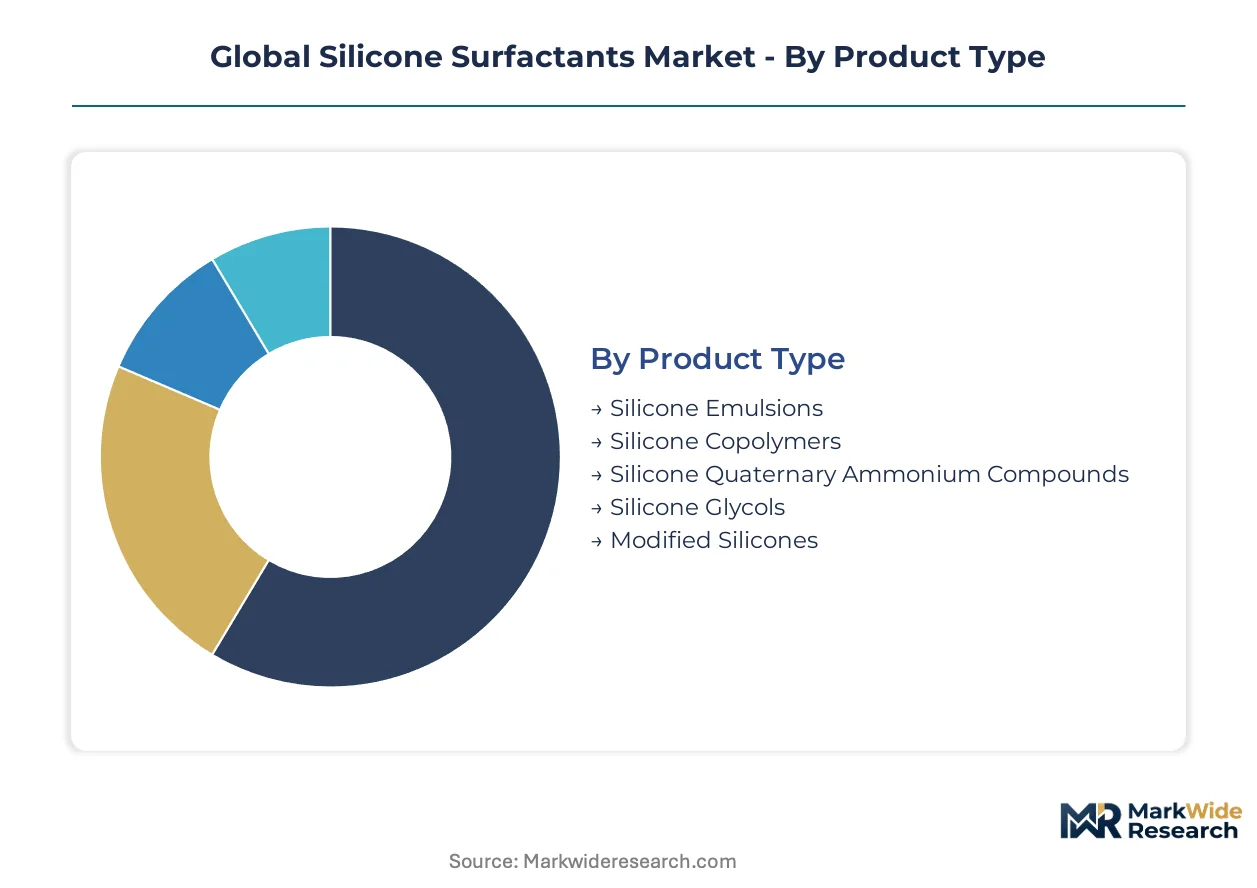
Silicone surfactant segmentation reflects divergent purity benchmarks across regulatory jurisdictions. Formulators select product architectures based on REACH dossier status, EPA TSCA Section 6 screening outcomes, and MEE discharge compliance requirements in China.
Product Type:
REACH substance evaluation under ECHA and EPA toxicity screening protocols are elevating analytical requirements for silicone surfactant architectures, compressing approval timelines for novel chemistries.
- Silicone Copolymers:Polydimethylsiloxane cores grafted with polyethylene oxide or polypropylene oxide chains via hydrosilylation deliver controlled hydrophilic-lipophilic balance. Demand concentrates in waterborne automotive coatings at Kansai Paint and Nippon Paint as robotic spray applications require narrow molecular weight distributions.
- Silicone Glycols:Amphiphilic compounds exhibiting surface tensions below 25 mN/m and thermal stability past 150°C. China's MEE enforces discharge standards along the Yangtze River basin that favor biodegradable silicone glycol variants in textile processing hubs.
- Silicone Emulsions:Aqueous dispersions stabilizing active ingredients in personal care formulations.
- Silicone Quaternary Ammonium Compounds:Cationic surfactants providing conditioning performance in hair care applications.
- Modified Silicones:Architectures targeting high-performance coatings with specialized wetting or defoaming functions.
Established volume favors silicone copolymers; emerging adoption favors silicone glycols.
End Use Industry:
Cost tier differentiation separates premium personal care grades from economy industrial lubricant variants.
- Paints & Coatings:Waterborne architectural and automotive formulators in Germany and the United States substitute solvent-based systems with silicone-stabilized aqueous dispersions to meet volatile organic compound limits. California and New York formulators accelerate qualification of alternative wetting systems under expanded EPA authority.
- Personal Care:European manufacturers stockpile high-purity silicone surfactants ahead of anticipated REACH substance restriction timelines, creating pull-through for certified grades. Sephora and Ulta Beauty retail channels favor formulators combining silicone conditioning with natural-derived emulsifier claims.
- Textile Processing:Surat and Tiruppur dyeing clusters in India adopt silicone-based fiber lubricants as water efficiency mandates intensify under zero liquid discharge frameworks.
- Agriculture:Bayer CropScience and Syngenta negotiate multi-year supply agreements specifying active ingredient compatibility testing protocols for silicone adjuvants.
- Paper Production:Anti-foaming applications in pulp processing operations.
Margin concentration sits with personal care; volume expansion is climbing the fastest in paints and coatings.
Application:
Customer type bifurcation separates precision formulators specifying narrow molecular distributions from commodity buyers accepting broader specifications.
- Wetting Agents:Fastest-expanding category as waterborne coatings and ink formulations displace solvent-based systems. Automotive and architectural end uses in Germany and the United States drive specification of premium grades with controlled HLB values.
- Emulsifying Agents:Versatile stabilization across pigment dispersion and active ingredient delivery. Demand concentrates in personal care and agrochemical formulation where multi-year supply agreements now specify performance protocols.
- Anti-Foaming Agents:Industrial processing applications in pulp and textile operations.
- Dispersing Agents:Pigment stabilization in coatings and inkjet ink formulations.
- Conditioning Agents:Hair care and skin care applications in clean-label personal care products.
Specification intensity favors wetting agents; procurement scale favors emulsifying agents.
Distribution Channel:
Supply concentration among four dimethylsiloxane producers is restructuring how specialty surfactants reach end-users.
- Direct Sales:Agrochemical multinationals negotiate supply agreements specifying testing protocols, displacing traditional distributor intermediaries. Brazil's Mato Grosso soybean belt formulators now source through parent-company global tenders.
- Third-Party Distributors:Industrial chemical distributors demand pre-certified inventory from European suppliers to avoid U.S. customs detention risk under expanded TSCA authority.
- Online Platforms:Specialty chemical procurement for small-volume formulators.
- Industrial Suppliers:Bulk supply relationships with coatings and textile processors.
- Specialty Chemical Retailers:Niche distribution for personal care ingredient sourcing.
Relationship value favors direct sales; geographic coverage favors third-party distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE discharge standards along the Yangtze River basin anchor the regulatory framework driving silicone surfactant procurement patterns. Formulators in Germany and the United States track parallel EPA and ECHA substance evaluation timelines. India's zero liquid discharge mandates reshape textile processing chemistry selection.
United States
California and New York formulators accelerate qualification of alternative wetting systems as EPA expands TSCA Section 6 authority over persistent substances. Industrial chemical distributors demand pre-certified inventory from European suppliers to avoid customs detention risk at West Coast ports. Waterborne architectural coatings segments in Los Angeles and New York City metro areas drive specification shifts.
Germany
Automotive coating formulators at Kansai Paint and Nippon Paint specify narrow molecular weight distributions for robotic spray applications. ECHA substance evaluation under REACH compresses approval timelines for novel silicone architectures. The Rhine-Ruhr industrial corridor concentrates backward-integrated siloxane production serving personal care and textile formulators.
China
Domestic agrochemical and coatings producers scale specialty silicone additive procurement as MEE enforces discharge standards favoring biodegradable variants. Textile processing hubs along the Yangtze River basin convert to silicone glycol chemistries. Shanghai and Jiangsu province formulators stockpile certified grades ahead of anticipated restriction timelines.
India
Surat and Tiruppur dyeing clusters adopt silicone-based fiber lubricants as water efficiency mandates intensify under zero liquid discharge frameworks. The country's national environmental regulator tightens effluent standards for textile processing. Maharashtra and Gujarat chemical distributors expand inventory of REACH-compliant surfactant grades for export-oriented manufacturers.
Brazil
Bayer CropScience and Syngenta negotiate multi-year supply agreements specifying active ingredient compatibility testing protocols for silicone adjuvants. Mato Grosso soybean belt formulators source through parent-company global tenders rather than regional distributors. ANVISA notification requirements elevate analytical documentation burdens for imported surfactant chemistries.
Global Silicone Surfactants Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in silicone surfactant supply. Four producers control over three-quarters of dimethylsiloxane capacity, concentrating upstream price-setting power. The competitive terrain separates backward-integrated siloxane manufacturers from formulation-focused compounders. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure feedstock access and qualify alternative architectures ahead of regulatory deadlines.
Within the integrated tier, Dow Inc. and Wacker Chemie AG exemplify producers with captive siloxane supply. Evonik Industries AG occupies a position among modified silicone specialists targeting high-performance coatings applications. Shin-Etsu Chemical Co., Ltd. anchors Japanese production capacity. These entities represent distinct strategic postures: feedstock security versus architectural precision versus regional manufacturing concentration.
| Leading Market Players |
|---|
| Elkem Silicones |
| Wacker Chemie AG |
| Dow Inc. |
| Siltech Corporation |
| Innospec |
| Momentive |
| Shin-Etsu Chemical Co., Ltd. |
| Supreme Silicones |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day lead times for REACH-certified silicone glycol grades signal how regulatory documentation requirements concentrate pricing power with backward-integrated German and Chinese producers while compressing margins for merchant-dependent compounders. Inventory carrying costs for pre-certified stockpiles ahead of ECHA restriction timelines now constitute a structural cost layer that smaller formulators cannot absorb without consortium participation.
Pricing Analysis
Geographic price spreads between Rhine-Ruhr and Yangtze River basin production hubs reflect divergent energy input costs and regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels separates narrow molecular weight distribution grades for robotic automotive coatings from commodity emulsifier variants. Cost compression in economy tiers intensifies because chlorosilane feedstock volatility transfers downstream to non-integrated surfactant manufacturers. Agrochemical multinationals exhibit lowest price sensitivity due to multi-year supply agreement structures, while small-volume textile formulators in India face acute margin pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for specialty silicone surfactant imports into German automotive coating clusters. Supply concentrates in China, Germany, and the United States, with dimethylsiloxane capacity anchored by four producers controlling upstream methylchlorosilane precursors. Raw material dependencies rest on chlorosilane monomers, polyethylene oxide graft stocks, and hydrosilylation catalysts. Single-source vulnerability concentrates around hydrosilylation expertise at German and Swiss technical universities. Distribution runs through direct procurement relationships displacing traditional chemical distributors in agrochemical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone surfactant incumbents face a substitution defense against fluorosurfactant retention in aerospace and semiconductor cleaning applications where thermal stability thresholds exclude silicone alternatives. Fluorinated wetting agents maintain performance advantages that threaten volume erosion in premium coatings segments.
For Market Incumbents: Shield market position by deepening backward integration into siloxane feedstocks to insulate margin structures from chlorosilane price volatility. Prioritize certification investment for REACH dossier updates ahead of ECHA substance evaluation timelines to capture stockpiling demand from European personal care manufacturers. Channel control through direct sales agreements with agrochemical multinationals displaces distributor intermediaries and locks in volume commitments.
For New Entrants and Emerging Players: Anchor in biodegradable silicone glycol variants for China's Yangtze River textile processing hubs where MEE discharge standards create preferential procurement terms. Target Surat and Tiruppur dyeing clusters in India under zero liquid discharge mandates as the most penetrable geography. Pursue white-label supply relationships with European distributors seeking pre-certified inventory to avoid U.S. customs detention risk.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized polymer chemist scarcity constrains R&D expansion outside German and Swiss technical centers. Acquisition target archetype: mid-scale compounders with captive hydrosilylation expertise and established REACH dossier status. Signal to watch: divergence between EPA TSCA Section 6 screening outcomes and ECHA substance evaluation timelines forcing parallel toxicology study expenditures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive siloxane production insulates margin structures from chlorosilane price volatility at Dow and Wacker facilities. |
| REACH Dossier Certification | Pre-qualified silicone architectures capture stockpiling demand from European personal care manufacturers ahead of restriction timelines. |
| Long-term Supply Agreement | Multi-year contracts with Bayer CropScience and Syngenta displace distributor intermediaries in Brazil's Mato Grosso soybean belt. |
| Biodegradable Variant Development | Enhanced aquatic biodegradation profiles unlock preferential procurement terms under China's MEE Yangtze River discharge standards. |
| Direct Sales Channel Expansion | Parent-company global tenders replace regional distributor relationships for agrochemical silicone adjuvant procurement. |
Research Methodology
Desk research of customs trade data, SEC 10-K filings, and ECHA registration dossiers preceded structured interviews with silicone surfactant plant managers, procurement leads at coatings OEMs, distribution channel partners, and technical R&D directors. Primary fieldwork with downstream formulators in automotive coatings, personal care, and agrochemical segments combined with secondary validation from ACC and Cefic industry reports. Bottom-up volume modeling triangulated against top-down value estimates across product type, end-use industry, application, and regional production hub segmentation.
Variance decomposition across the projection horizon isolates drivers by segment dimension: grade tier purity benchmarks, end-use regulatory compliance requirements, packaging format scale economies, and regional production hub energy input costs. CAGRs derived from historical elasticity analysis applied to forward-looking demand curves for waterborne coatings substitution, REACH restriction anticipation effects, and zero liquid discharge mandate adoption. Industry-specific forecast inputs include chlorosilane capacity utilization rates and hydrosilylation catalyst cost trajectories.
Underlying assumptions cover sustained EPA TSCA Section 6 enforcement trajectory, ECHA substance evaluation timeline adherence, and MEE discharge standard implementation pace, with deviation risk concentrated in regulatory acceleration or delay scenarios. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Sodium Cocoyl Isethionate Market
Surfactants
Fatty Methyl Ester Sulfonate Market
Surfactants
Alkylamines Market
Surfactants
Cyclopentasiloxane Market
Surfactants
Global Sodium Lauryl Ether Sulfate [SLES] Market
Surfactants
Global Sodium Cocoyl Glutamate Market
Surfactants
Sodium Methyl Cocoyl Taurate Market
Surfactants
MDEA Esterquats Market
Surfactants
Chlorooctane Market
Surfactants
Anionic Surfactants Market
Surfactants
Sodium Lauryl Sulphate Market
Surfactants
North America Non-Ionic Surfactants Market
Surfactants
Cyclotetrasiloxane Market
Surfactants
Sugar-Based Surfactants Market
Surfactants
Cocamide Monoethanolamine Market
Surfactants
Natural Wax Emulsion Market