
 Zinc Ricinoleate Market | 2026-2036
Zinc Ricinoleate Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Ricinoleate Market Analytics
Capital-intensity divergence between integrated castor oil processors and merchant chemical blenders is unwinding traditional supply hierarchies. Evonik Industries leverages backward integration into bio-based feedstock refining to sustain margin stability across European personal care accounts. Clariant anchors its position through specialized bead-grade formulations that dominate premium deodorant pipelines. BASF competes on manufacturing scale, operating multi-ton reactors that supply commodity-grade powder to mass-market household brands.
Zinc ricinoleate is the zinc salt of ricinoleic acid, typically produced at 95-98% purity through saponification of castor oil followed by zinc salt precipitation, functioning primarily as an odor-absorbing agent in cosmetic and hygiene formulations. Powder formulations currently occupy the largest volume share in deodorant manufacturing, while bead grades command superior margins in premium personal care lines. The household products end-use segment is expanding fastest as sprayable solutions gain traction in fabric and air-care applications. Distribution through specialty chemical distributors retains dominance in B2B channels, though direct online procurement is capturing smaller formulator accounts.
REACH registration requirements and the EU Cosmetics Regulation govern ingredient disclosure and safety dossier standards for zinc ricinoleate entering European formulations, while the FDA's cosmetic ingredient review process shapes acceptable use concentrations in United States markets. ISO 16128 guidelines on natural and organic cosmetic ingredients are influencing raw material sourcing specifications across multiple geographies. Stakeholders must monitor evolving biodegradability certifications and castor oil supply chain traceability mandates as these criteria increasingly determine supplier qualification and contract renewal terms.
Market Dynamics
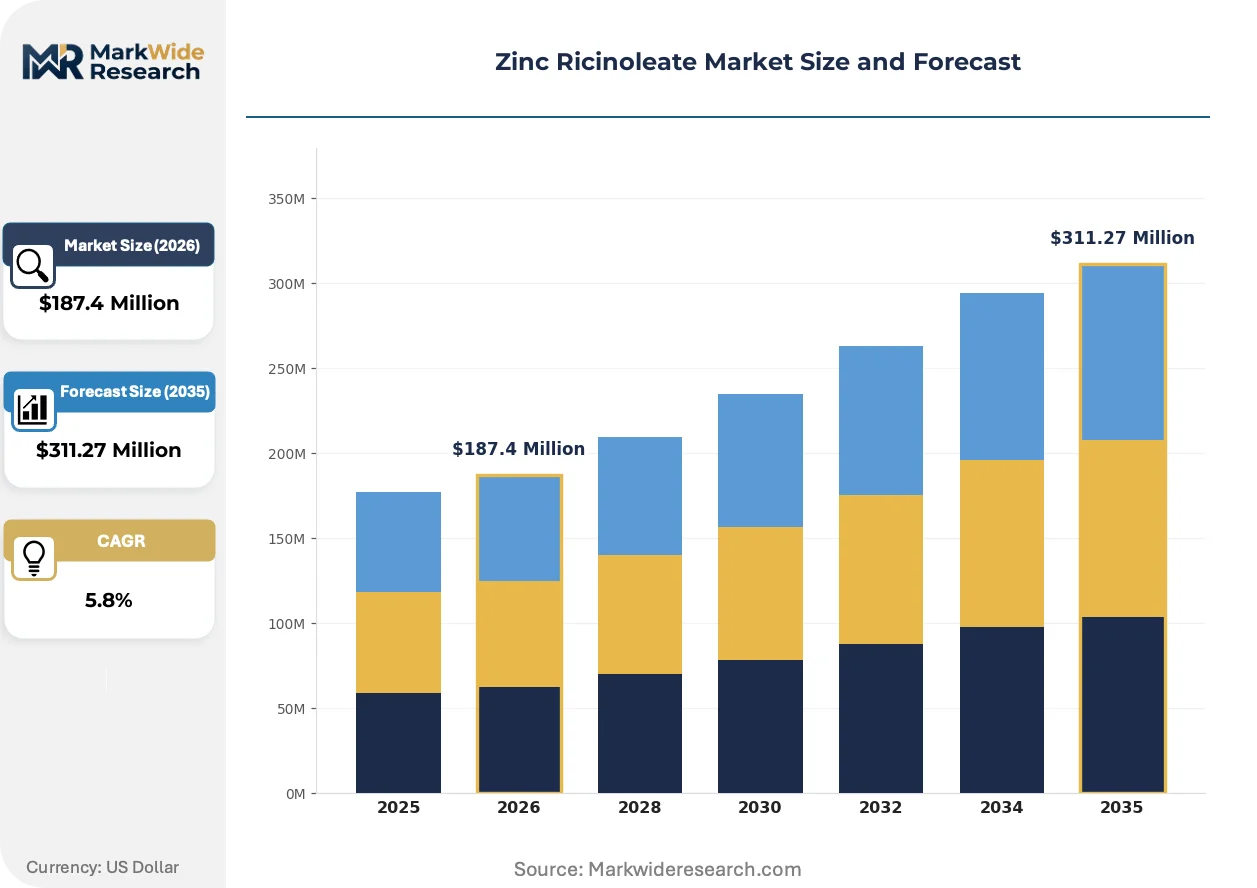
Aluminum-free deodorant formulation mandates from personal care brands are compressing traditional antiperspirant supply chains while elevating zinc ricinoleate from niche additive to primary odor-control active. This demand pivot is restructuring procurement relationships between castor oil refiners and cosmetic formulators.
Growth Catalysts
- REACH registration thresholds:ECHA's tightened substance volume reporting for cosmetic actives is filtering out non-compliant suppliers, concentrating qualified zinc ricinoleate supply among dossier-holding manufacturers.
- Sprayable household formulations:Fabric refresher and air-care brands are adopting zinc ricinoleate in pump-dispensed solutions, expanding addressable volume beyond stick and roll-on deodorant formats.
- ISO 16128 natural origin certification:Formulators seeking organic cosmetic labeling are specifying bio-based zinc ricinoleate to meet minimum natural content thresholds.
Market Restraints
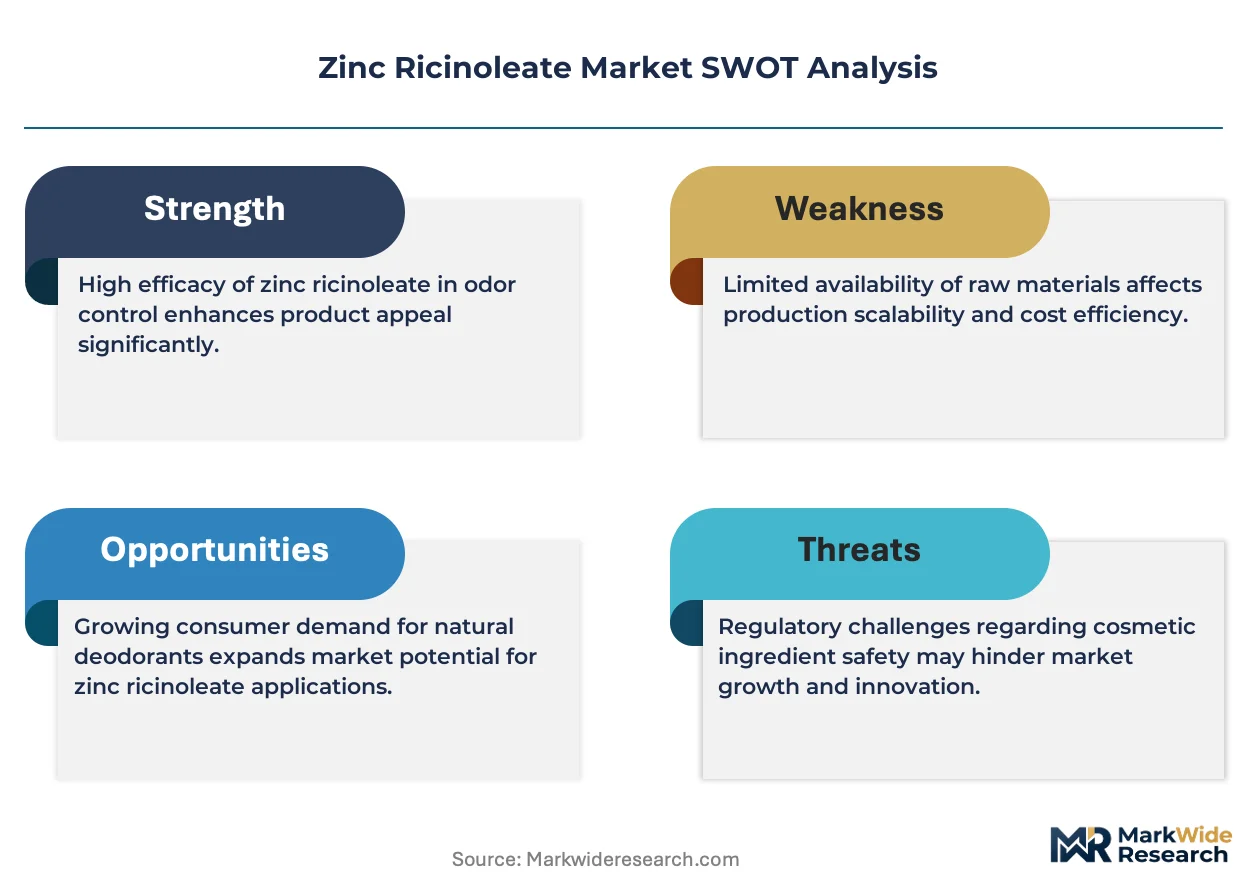
- Castor oil supply concentration:Over 85% of global castor seed cultivation clusters in India, exposing European and North American zinc ricinoleate producers to monsoon-dependent harvest volatility and export duty fluctuations.
- Precipitation purity ceilings:Conventional saponification methods struggle to consistently exceed 98% zinc ricinoleate purity without prohibitively expensive recrystallization stages.
- Aluminum zirconium substitution inertia:Mass-market antiperspirant brands retain aluminum salt formulations due to established consumer efficacy expectations and lower active ingredient costs.
Strategic Opportunities
- India domestic formulation growth:Indian personal care brands are localizing deodorant production, creating captive demand for indigenous zinc ricinoleate manufacturing.
- Biodegradability certification alignment:OECD 301B ready biodegradability testing is becoming a contract qualification criterion for suppliers to European household product brands.
- Direct e-procurement channels:Specialty chemical marketplaces are enabling mid-sized cosmetic formulators to bypass distributor markups and source zinc ricinoleate in sub-ton quantities.
Industry Challenges
- Analytical chemistry talent scarcity:Ricinoleic acid isomer ratio verification and heavy metal impurity testing require specialized chromatography expertise that commands premium compensation in tight labor markets.
- Castor oil traceability system integration:Blockchain-enabled seed-to-salt documentation demands IT infrastructure investments that smaller chemical processors struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Ricinoleate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Beads, Solutions End User: Personal Care, Household Products, Food Additives, Pharmaceuticals Application: Deodorants, Creams, Lotions, Antiperspirants Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Hejian Jinnan Chemical Auxiliaries, MakingCosmetics, Evonik Industries, Clariant, BASF, Novaphene Specialities, Parchem, Kao Corporation, Acme Synthetic Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Ricinoleate Market Evolving Landscape
Process intensification in castor oil refining and formulation-grade particle engineering are compressing cost structures while enabling new application formats. These technical advances are redrawing competitive boundaries between commodity suppliers and performance-specialized manufacturers.
Bead-grade zinc ricinoleate with controlled dissolution kinetics is displacing conventional powder in premium deodorant pipelines. Premium personal care brands specify spherical particle morphologies between 200-400 microns for aesthetic suspension stability and reduced dusting during manufacturing. This particle engineering shift is compressing margins for undifferentiated powder suppliers while rewarding specialized milling and spray-drying capabilities.
ECHA's 2024 updated REACH guidance on cosmetic ingredient safety dossiers is extending toxicological study requirements for zinc salts used in leave-on products. Manufacturers must now submit enhanced dermal absorption data and reproductive toxicity endpoints to maintain substance volume registrations above 100 tons annually. German and French formulators are responding by consolidating supplier relationships with dossier-complete producers.
Certification-driven procurement is fragmenting supplier qualification criteria across end-use verticals. Household product brands now require OECD biodegradability documentation alongside ISO 16128 natural origin claims, whereas cosmetic formulators prioritize COSMOS or NATRUE certification compatibility. This bifurcation is most visible in Netherlands and Belgium, where contract manufacturers serve both personal care and home care brands from shared facilities.
Zinc Ricinoleate Market Segmentation
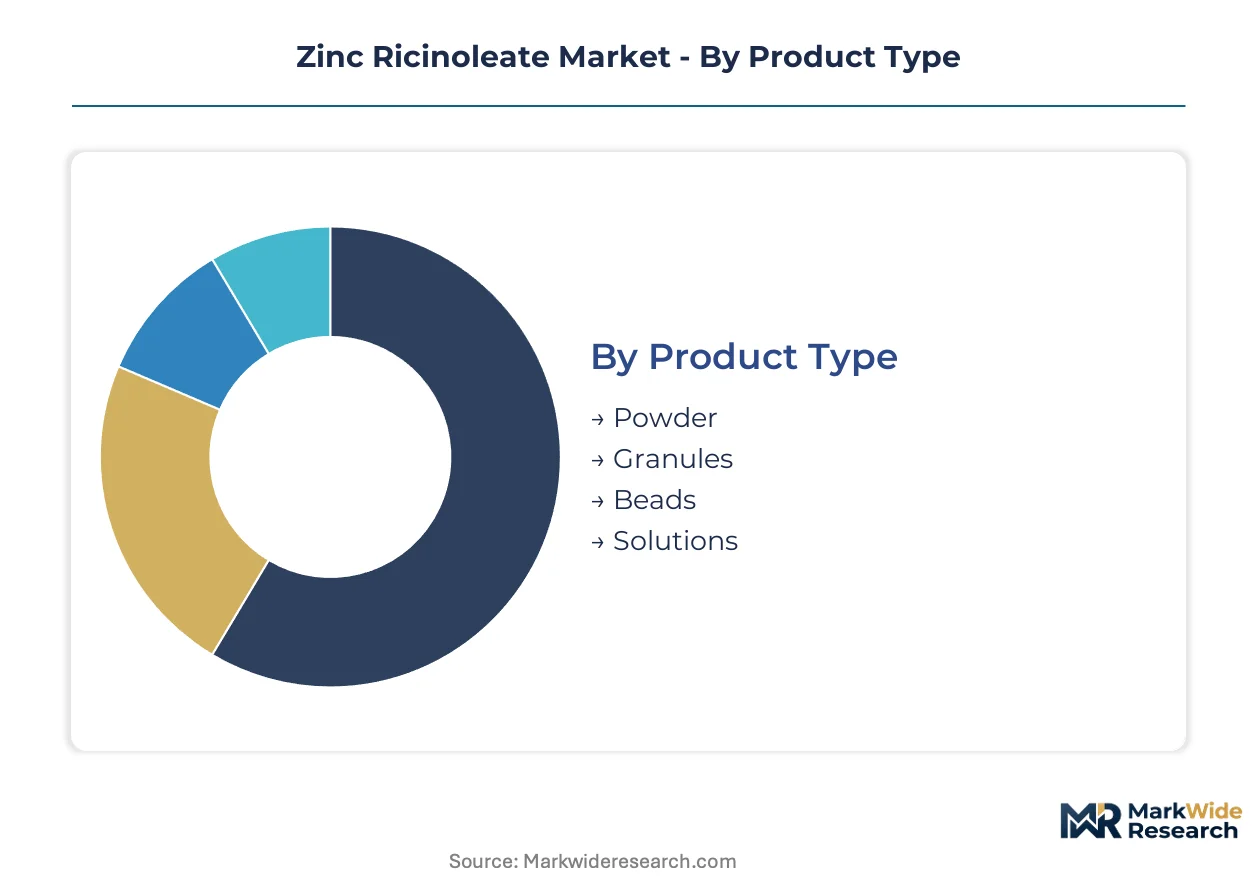
Segmentation in zinc ricinoleate markets tracks how formulation requirements diverge across deodorant, household, and pharmaceutical channels. Each product grade and distribution pathway carries distinct purity specifications, certification burdens, and margin structures that reshape supplier positioning.
Product Type:
Powder and bead grades dominate export flows to European cosmetic formulators, while granules and solutions serve regional household product manufacturers closer to castor oil refining clusters.
- Powder:Conventional spray-dried particles at 95-98% purity constitute the workhorse grade for mass-market deodorant stick production. Demand concentrates in Germany and France where aluminum-free formulation mandates from personal care brands have elevated powder volumes in contract manufacturing facilities.
- Beads:Spherical particles engineered to 200-400 micron diameters with controlled dissolution kinetics command premium positioning in prestige personal care pipelines. Momentum sits with bead specifications as premium deodorant brands prioritize aesthetic suspension stability and reduced dusting during compounding operations.
- Granules:Intermediate particle size grades serve regional household product blenders seeking pourable flow characteristics without bead-grade milling costs.
- Solutions:Pre-dispersed aqueous or glycolic preparations enable sprayable household formulations in fabric refresher and air-care applications.
Powder holds the largest share; momentum sits with beads.
End User:
Cost tier stratification separates premium-certified personal care grades from commodity household and food additive specifications.
- Personal Care:Deodorant and antiperspirant formulators specify COSMOS or NATRUE-compatible zinc ricinoleate with full REACH dossier documentation. ISO 16128 natural origin certification drives procurement decisions in German and French premium cosmetic pipelines.
- Household Products:Fabric refresher and air-care brands adopt sprayable zinc ricinoleate solutions, expanding addressable volume beyond traditional stick and roll-on formats. OECD 301B biodegradability documentation is becoming a contract qualification criterion for European household product suppliers.
- Food Additives:Limited regulatory approval scope constrains this segment to specific flavor masking applications under strict purity protocols.
- Pharmaceuticals:Excipient-grade specifications require enhanced heavy metal impurity testing and ricinoleic acid isomer ratio verification that commands specialized chromatography expertise.
Personal care commands the dominant revenue position; household products are climbing the fastest.
Application:
Volume concentration tracks aluminum-free deodorant substitution patterns, with creams and lotions representing adjacent expansion opportunities.
- Deodorants:Stick and roll-on formats absorb the majority of zinc ricinoleate powder and bead grades. Aluminum-free formulation mandates from personal care brands in Germany and France have compressed traditional antiperspirant supply chains while elevating zinc ricinoleate from niche additive to primary odor-control active.
- Creams:Leave-on body care applications require enhanced dermal absorption data under ECHA's updated REACH guidance for cosmetic ingredients.
- Lotions:Pump-dispensed formats in personal care lines favor solution-grade zinc ricinoleate for uniform dispersion.
- Antiperspirants:Aluminum zirconium formulations retain dominance in mass-market channels, constraining zinc ricinoleate penetration to aluminum-free positioning.
Deodorants represent the volume anchor; creams show the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates bulk B2B procurement through specialty chemical distributors from direct online capture of mid-sized formulator accounts.
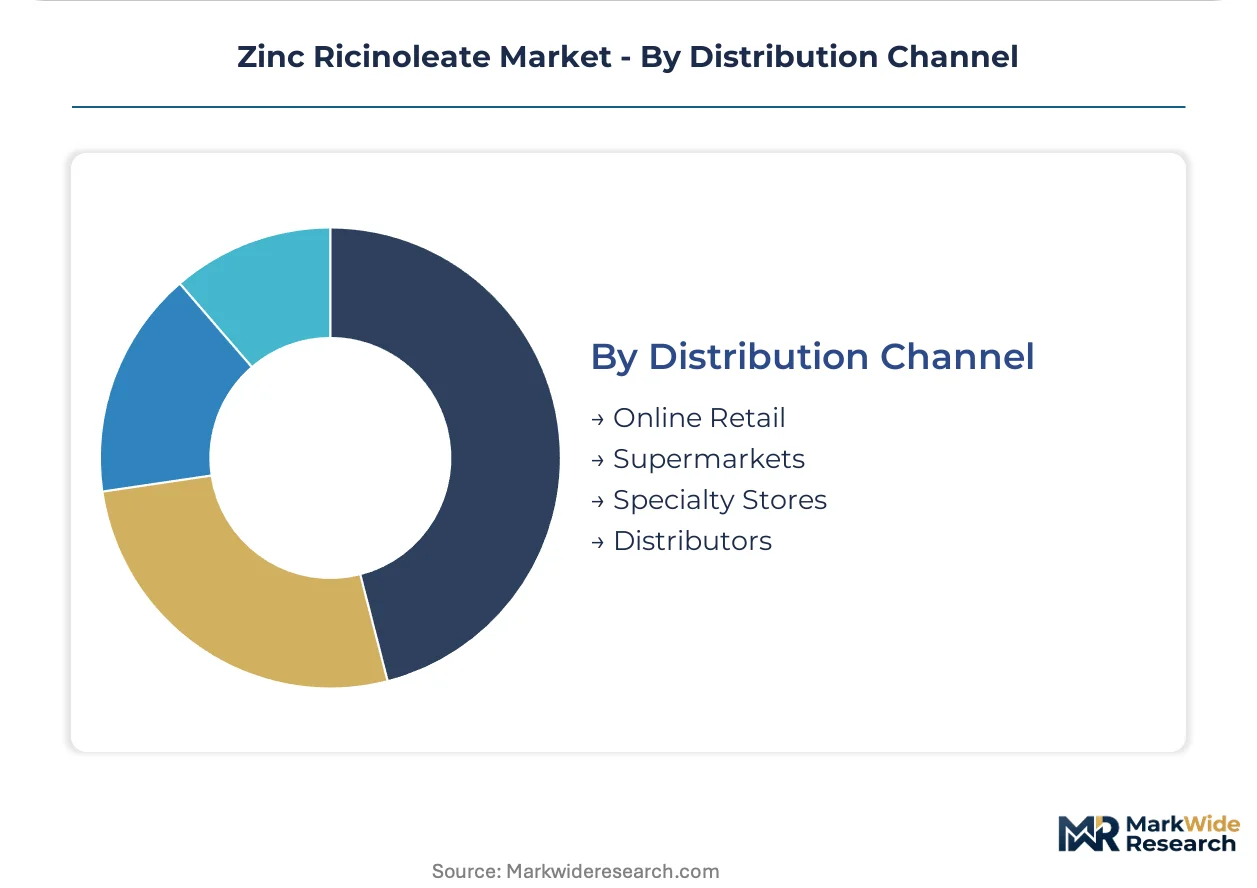
- Online Retail:Specialty chemical marketplaces enable mid-sized cosmetic formulators to bypass distributor markups and source zinc ricinoleate in sub-ton quantities. E-procurement channels are capturing smaller accounts in Netherlands and Belgium where contract manufacturers serve both personal care and home care brands.
- Supermarkets:Indirect channel serving finished consumer goods rather than raw material distribution.
- Specialty Stores:Niche positioning for small-batch cosmetic ingredient suppliers.
- Distributors:Retain dominance in B2B channels for volume procurement by multinational personal care and household product manufacturers.
Distributors retain the largest share; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb premium pricing for certified grades with minimal elasticity, while mass-market formulators in India and the United States negotiate aggressively on commodity specifications. This divergence concentrates margin capture in Western European personal care clusters while compressing returns in volume-driven Asian supply chains.
Germany
Premium deodorant brands in Hamburg and Cologne mandate COSMOS-compatible zinc ricinoleate with full REACH dossier documentation. ECHA's 2024 updated guidance on cosmetic ingredient safety dossiers extends toxicological study requirements for leave-on products. The North Rhine-Westphalia chemical corridor hosts contract manufacturers consolidating supplier relationships with dossier-complete producers.
France
Paris-based luxury personal care houses specify bead-grade formulations with NATRUE certification compatibility. ANSM enforces enhanced dermal absorption data submission under EU Cosmetics Regulation amendments. The Île-de-France region concentrates formulation R&D facilities driving particle engineering specifications for aesthetic suspension stability.
United States
Mass-market household brands in New Jersey and Ohio procure commodity-grade powder for sprayable fabric refresher applications. FDA cosmetic ingredient review processes shape acceptable use concentrations in leave-on formulations. The Mid-Atlantic chemical processing belt accommodates multi-ton reactor operations supplying aluminum-free deodorant pipelines.
India
Domestic personal care brands in Maharashtra and Gujarat localize deodorant production, creating captive demand for indigenous zinc ricinoleate manufacturing. BIS standards govern cosmetic ingredient purity benchmarks alongside state-level pollution control mandates. The Mumbai-Pune industrial corridor integrates castor oil refining with downstream salt precipitation capabilities.
Japan
Specialty cosmetic formulators in Osaka and Tokyo specify excipient-grade zinc ricinoleate with enhanced heavy metal impurity testing. PMDA oversight of quasi-drug classifications constrains deodorant active ingredient sourcing to documented suppliers. The Kansai region maintains precision milling capabilities for controlled particle size distribution in premium applications.
Zinc Ricinoleate Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into castor oil refining separating margin-stable producers from price-taken blenders. The upper tier commands premium positioning through dossier-complete REACH registrations and ISO 16128 certification alignment. Three archetypes populate the competitive terrain: integrated bio-refiners with captive feedstock control, performance-specialized particle engineers, and scale-driven commodity powder suppliers. Consolidation pressure operates through selective supplier qualification by multinational formulators and capacity expansion in Indian domestic supply chains.
Among European-integrated chemical groups, Evonik Industries and BASF exemplify divergent strategic positions within the same geography. Evonik anchors the bio-refiner archetype through upstream control over feedstock refining. BASF occupies the scale-driven position with multi-ton reactor operations. Clariant represents the performance-specialized tier through formulated bead-grade capabilities. Kao Corporation sits within the Asia-Pacific specialist cluster serving regional cosmetic formulators.
| Leading Market Players |
|---|
| Hejian Jinnan Chemical Auxiliaries |
| MakingCosmetics |
| Evonik Industries |
| Clariant |
| BASF |
| Novaphene Specialities |
| Parchem |
| Kao Corporation |
| Acme Synthetic Chemicals |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day castor oil inventory buffers at European formulators compress pricing power upstream while amplifying margin capture for REACH-registered producers with backward integration into bio-based feedstock refining. This lead-time structure concentrates premium pricing among dossier-holding manufacturers in Germany and France while exposing merchant blenders to volatile raw material pass-through costs.
Pricing Analysis
After-sales technical service contracts for particle engineering customization drive lifetime value for bead-grade suppliers serving premium deodorant pipelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and volume scale, with COSMOS-compatible grades commanding substantial premiums over commodity powder. Cost compression in standard-grade powder is intensifying because Indian domestic capacity additions are expanding supply availability. Mass-market household brands in the United States exhibit the highest price sensitivity, while Paris-based luxury personal care houses demonstrate minimal elasticity for NATRUE-certified specifications.
Supply Chain Analysis
India anchors global castor seed cultivation and primary oil extraction, with downstream salt precipitation capabilities concentrating in Gujarat and Maharashtra industrial corridors. European and North American zinc ricinoleate production draws from Indian castor oil feedstock, refined intermediates from Germany, and specialized milling equipment from Japan. Single-source vulnerability in Indian monsoon-dependent harvests exposes formulators to export duty fluctuations and crop volatility. Distribution runs through specialty chemical distributors for multinational accounts, while direct e-procurement channels capture mid-sized cosmetic formulators in Netherlands and Belgium.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH dossier interoperability is transforming supplier qualification into a platform-economics inflection, where ecosystem participation rights determine contract access more than unit pricing.
For Market Incumbents: Compound REACH registration advantages by extending toxicological study coverage into reproductive toxicity endpoints before ECHA's volume thresholds tighten further. Deepen backward integration into castor oil refining to defend margin stability against Indian domestic capacity growth and merchant blender price competition. For New Entrants and Emerging Players: ISO 16128 fast-track certification for natural origin claims opens procurement doors at mid-sized German and French formulators seeking secondary suppliers. Target sprayable household solution grades in fabric refresher applications, where OECD 301B biodegradability documentation serves as the primary go-to-market credential rather than cosmetic-grade purity thresholds. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because supplier qualification concentration and certification burden escalation favor scaled dossier-holding producers over fragmented merchant blenders. Acquisition targets should display integrated castor oil refining capabilities or specialized particle engineering competencies. The signal to watch is ECHA substance volume registration surrender rates among sub-scale producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Oil Refining | Captures margin stability for Evonik and integrated European producers against Indian supply volatility. |
| REACH Dossier Extension for Leave-On Products | Meets ECHA's enhanced toxicological requirements for cosmetic ingredient registrations above volume thresholds. |
| Bead-Grade Particle Engineering Investment | Enables Clariant's premium positioning in prestige deodorant pipelines with controlled dissolution kinetics. |
| OECD 301B Biodegradability Certification | Qualifies suppliers to European household product brands requiring documented environmental fate testing. |
| Direct E-Procurement Channel Development | Bypasses distributor markups for mid-sized cosmetic formulators in Netherlands and Belgium contract manufacturing. |
Research Methodology
Desk research of customs trade data, chemical industry association reports, and regulatory filing databases preceded structured interviews with plant managers at castor oil refiners, procurement leads at downstream cosmetic OEMs, distribution channel partners, and technical R&D directors specializing in particle engineering. Primary fieldwork across Germany, France, India, and the United States captured formulation specification evolution and supplier qualification criteria. Bottom-up volume modeling triangulated against top-down market sizing from trade flow analysis.
Variance decomposition across product grade, end-use industry, and regional production hub dimensions structured the analytical framework over the projection horizon. CAGRs derived from segmented volume trajectory modeling incorporated aluminum-free deodorant substitution rates, sprayable household formulation adoption curves, and certification-driven procurement fragmentation. Castor oil supply elasticity and REACH registration concentration thresholds served as industry-specific forecast inputs.
Underlying assumptions cover sustained aluminum-free formulation mandates, stable Indian monsoon patterns, and ECHA enforcement continuity, with deviation risk concentrated in castor seed harvest volatility and regulatory timeline acceleration. Recalibration cycles align with material shifts in ECHA guidance updates, Indian export policy revisions, and biodegradability certification mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Organometallics Market
Specialty Chemicals
Photo Emulsion Market
Specialty Chemicals
Bismuth Oxychloride Market
Specialty Chemicals
Europe Aerosol Cans Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Betanin Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Immunochemistry Products Market
Specialty Chemicals
Global Lactobionic Acid Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Specialty Biocides Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Marula Oil Market