
 Esterquats Market | 2026-2036
Esterquats Market Size, Share, and Industry Trends Forecast 2026-2036
Esterquats Market Analysis
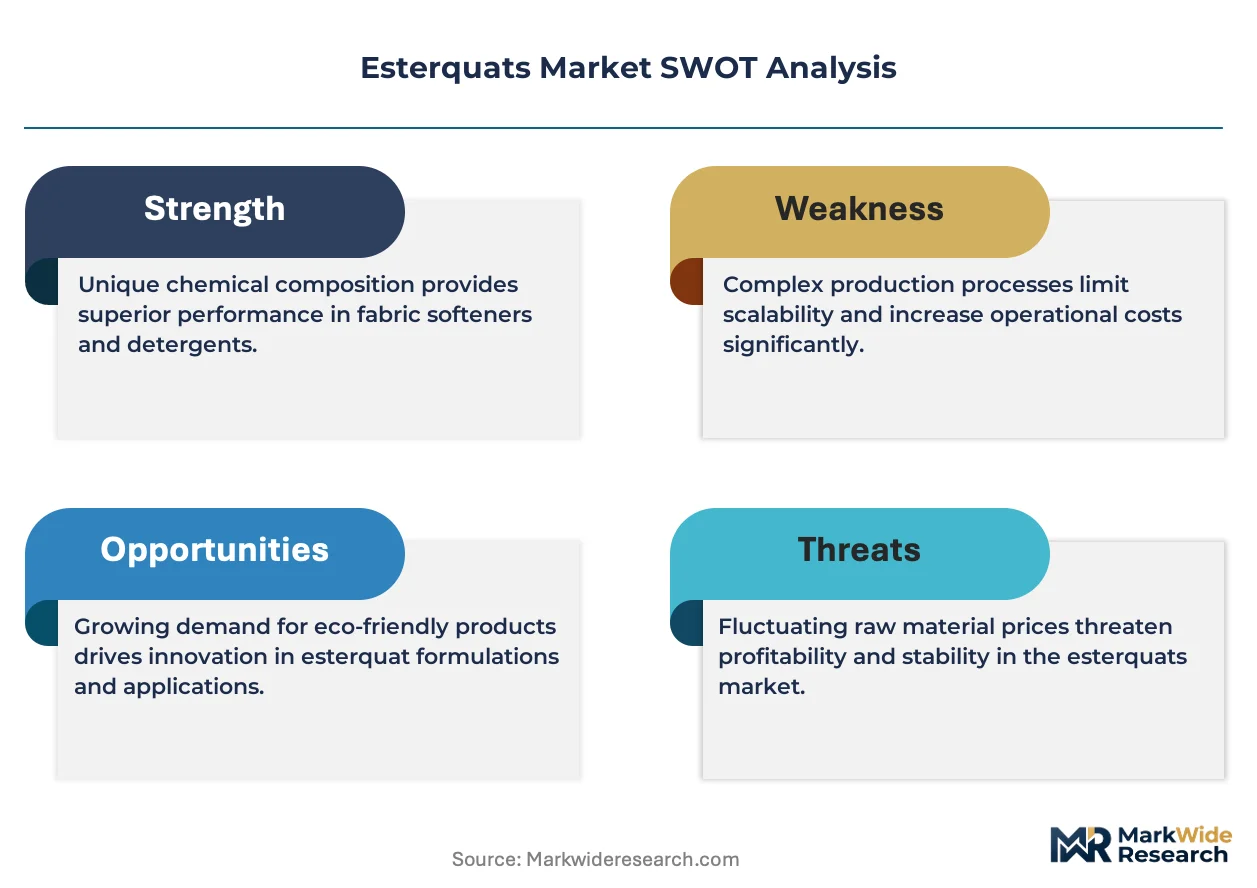
Asset-light toll manufacturing and third-party leasing of alkoxylation capacity is tilting competitive dynamics toward firms that can secure feedstock contracts without owning fixed assets. Stepan Company leverages its North American surfactant infrastructure to sustain backward integration into fatty acid methyl esters. Evonik Industries anchors European supply through specialized quaternization technology at its German sites. BASF SE competes via integrated oleochemical networks that extend from palm kernel oil to finished esterquat dispersions.
Esterquats are quaternary ammonium compounds synthesized by esterifying triethanolamine or similar amines with fatty acids, then quaternizing with methyl chloride or dimethyl sulfate to yield cationic surfactants with biodegradability profiles superior to dialkyl dimethyl ammonium chloride. These compounds function primarily as fabric softening agents, hair conditioners, and anti-static additives through electrostatic interaction with anionic substrates. Primary Esterquats dominate volume in fabric softener applications where cold-water dispersibility commands premium positioning, while Hair Care represents the fastest-growing application as sulfate-free and silicone-free formulations drive cationic conditioning demand. The liquid form occupies the largest share of industrial and institutional procurement due to ease of dilution and dosing compatibility.
EPA Safer Choice criteria and EU REACH restrictions on persistent quaternary ammonium compounds are reshaping product registration pathways and reformulation timelines for suppliers serving North American and European customers. FDA oversight of cosmetic ingredient safety and state-level Proposition 65 litigation in California create additional compliance layers for esterquats entering personal care formulations. BIS certification requirements and CDSCO cosmetic ingredient standards in India add complexity for multinational suppliers expanding into regulated Asian markets. Stakeholders must monitor pending amendments to EU Detergent Regulation biodegradability thresholds and assess cold-water performance claims against emerging Blue Angel and Nordic Swan ecolabel criteria.
Market Dynamics
The Esterquats Market pivots on regulatory mandates for biodegradable cationic surfactants, with EU REACH and EPA Safer Choice criteria forcing simultaneous reformulation of legacy fabric softener chemistries and expansion of cold-water dispersible grades.
Growth Catalysts
- Fabric Softener Reformulation:Home care manufacturers accelerate substitution of dialkyl dimethyl ammonium chloride with esterquats to meet EU Detergent Regulation biodegradability thresholds.
- REACH Compliance Deadlines:The European Chemicals Agency's escalating restrictions on persistent quaternary ammonium compounds create mandatory upgrade cycles across industrial and institutional laundry segments.
- Hair Care Cationic Demand:Sulfate-free and silicone-free conditioning formulations in personal care pull esterquat volumes as primary conditioning agents replace silicones.
Market Restraints
- Palm Kernel Oil Volatility:Feedstock concentration in Southeast Asian oleochemical supply exposes esterquat producers to price swings in fatty acid methyl ester precursors.
- Quaternization Technology Concentration:Specialized German and North American manufacturing sites control critical quaternization capacity, creating geographic supply risk.
- Dimethyl Sulfate Substitution:Methyl chloride quaternization routes face displacement pressure from alternative cationic technologies in cost-sensitive Asian markets.
Strategic Opportunities
- Indian Cosmetic Ingredient Standards:CDSCO and BIS certification requirements for personal care create first-mover advantage for suppliers establishing local technical dossiers.
- Cold-Water Ecolabel Positioning:Blue Angel and Nordic Swan criteria for low-temperature laundry performance enable premium pricing for specialized esterquat dispersions.
- Asset-Light Alkoxylation Leasing:Toll manufacturing partnerships allow new entrants to bypass fixed capital requirements in esterquat synthesis.
Industry Challenges
- Multi-Jurisdiction Registration Burden:Simultaneous EPA, ECHA, and CDSCO compliance timelines stretch regulatory affairs capacity without harmonized data requirements.
- Quaternization Process Scale-Up:Lab-validated cold-water dispersible grades require capital-intensive pilot-to-commercial validation for methyl chloride handling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esterquats Market |
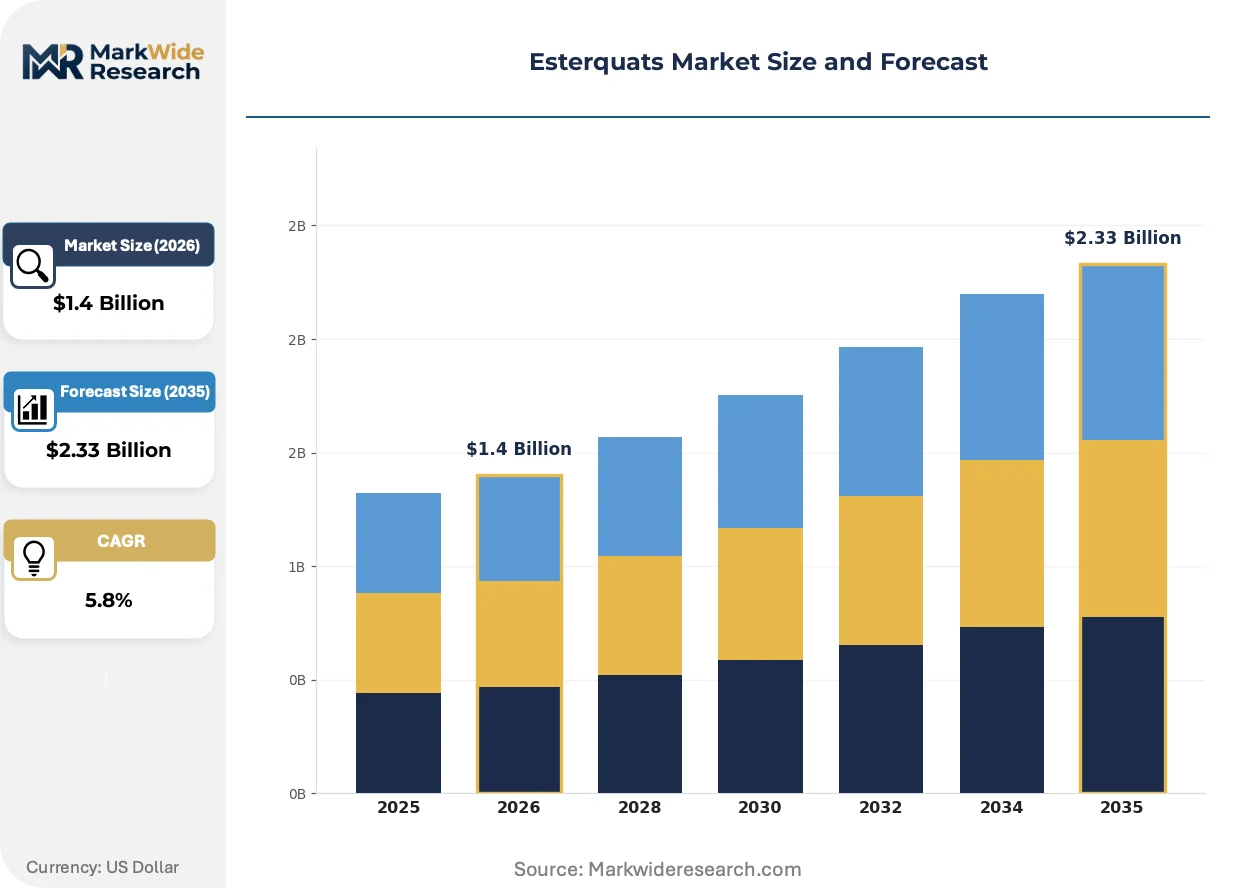
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Esterquats, Secondary Esterquats, Tertiary Esterquats, Quaternary Esterquats Application: Personal Care, Home Care, Industrial Cleaning, Hair Care End User: Consumer Goods, Professional Cleaning Services, Pharmaceutical Companies, Cosmetics Manufacturers Form: Liquid, Powder, Granular, Paste |
| Companies Covered | Stepan Company, Evonik Industries, BASF SE, Kao Corporation, Akzo Nobel N.V., Clariant AG, The Lubrizol Corporation, Italmatch Chemicals S.p.A., Chemelco International B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esterquats Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to redefine competitive advantage in cationic surfactants, with performance claims now inseparable from biodegradability verification and cold-water efficacy demonstration.
Esterquat dispersions synthesized from triethanolamine and C16-C18 fatty acid cuts are rendering obsolete traditional dialkyl quaternary ammonium compounds in European fabric softener formulations. Industrial laundries in Germany and household brands across Northern Europe have completed formulation transitions, compressing demand for legacy quaternary ammonium chlorides and elevating price premiums for esterquats with verified cold-water dispersibility.
EU REACH annex amendments restricting non-biodegradable quaternary ammonium compounds are mandating full supply chain requalification for fabric softener and hair care ingredients. Registration dossier updates for existing substances now require enhanced biodegradation data, forcing raw material suppliers to reformulate or withdraw from the European market. Personal care manufacturers face compressed timelines to validate esterquat alternatives ahead of sunset dates for restricted chemistries.
Direct procurement relationships between home care brands and specialized esterquat manufacturers are displacing traditional surfactant distributor networks in North America and Europe. Large formulators now require technical collaboration on cold-water performance claims and regulatory documentation, bypassing intermediaries unable to provide formulation support. This pattern concentrates most visibly in German industrial laundry supply chains and California-based natural home care brands subject to Proposition 65 litigation exposure.
Esterquats Market Segmentation
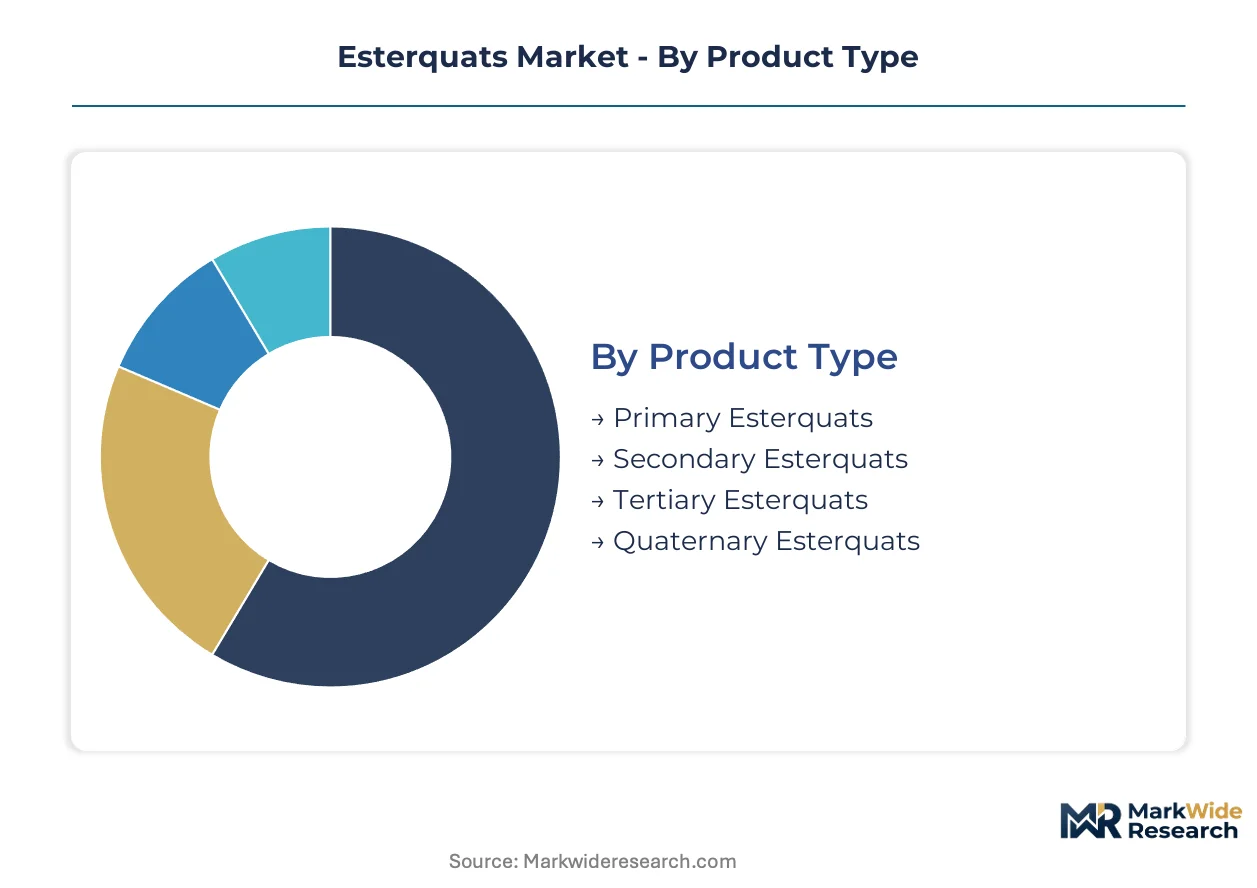
Segmentation in the Esterquats Market reveals how cationic surfactant chemistry aligns with distinct performance requirements across fabric conditioning, hair care, and industrial cleaning. Manufacturers configure product portfolios around biodegradability mandates, cold-water dispersibility, and formulation compatibility rather than volume scale alone.
Product Type:
Mature quaternary ammonium architectures coexist with emerging tertiary and secondary structures as formulators balance biodegradability against conditioning efficacy.
- Primary Esterquats:Synthesized from triethanolamine and C16-C18 fatty acid cuts through methyl chloride quaternization, these compounds deliver superior cold-water dispersibility. German industrial laundries and Northern European household brands source specialized grades for low-temperature fabric softener formulations under EU Detergent Regulation compliance deadlines.
- Secondary Esterquats:Partially esterified amine structures offer intermediate biodegradability profiles with reduced cationic charge density. Demand concentrates in sulfate-free hair care formulations where silicone replacement drives cationic conditioning agent procurement from cosmetics manufacturers in California and European natural personal care clusters.
- Tertiary Esterquats:Single-ester quaternaries with modified hydrophilic-lipophilic balance for specialized emulsion stability.
- Quaternary Esterquats:Fully substituted ammonium structures with maximum cationic activity for heavy-duty industrial cleaning applications.
Primary Esterquats handles the majority of throughput; Secondary Esterquats is the fastest mover on share.
Application:
Cost tier stratification separates premium personal care grades from commodity fabric softener volumes and specialized industrial formulations.
- Personal Care:Skin conditioning and emulsification applications in lotions and creams leverage esterquat biocompatibility. CDSCO cosmetic ingredient standards in India and FDA oversight in the US create multi-jurisdiction registration burdens for suppliers targeting multinational cosmetics manufacturers.
- Home Care:Fabric softener formulations represent the volume anchor as manufacturers reformulate around biodegradable cationic surfactants. EPA Safer Choice criteria and state-level chemical disclosure rules in the US compress timelines for dialkyl dimethyl ammonium chloride substitution.
- Industrial Cleaning:Hard surface disinfection and food processing equipment sanitation require quaternary ammonium stability against organic soil loading.
- Hair Care:Cationic conditioning in sulfate-free and silicone-free shampoos exploits esterquat deposition on anionic hair surfaces.
Home Care commands the largest procurement volumes; Hair Care is expanding most quickly as silicone-free formulations proliferate.
End User:
Customer type fragmentation distinguishes mass-market consumer goods from specification-driven professional and pharmaceutical procurement.
- Consumer Goods:Mass-market fabric softener and hair care brands procure standardized esterquat dispersions through direct manufacturer relationships. Large formulators in Germany and California now bypass traditional surfactant distributors to secure technical collaboration on cold-water performance claims and regulatory documentation.
- Professional Cleaning Services:Industrial laundries and institutional facilities demand concentrated liquid formulations with verified low-temperature efficacy. Blue Angel and Nordic Swan ecolabel criteria enable premium pricing for specialized grades in Northern European commercial laundry operations.
- Pharmaceutical Companies:Excipient-grade esterquats for topical drug delivery require enhanced purity certification and GMP manufacturing documentation.
- Cosmetics Manufacturers:Niche and premium personal care brands drive specification diversity for natural-positioned conditioning products.
Consumer Goods absorbs the dominant share of esterquat production; Professional Cleaning Services is climbing the fastest as institutional sustainability mandates tighten.
Form:
Supply concentration in liquid manufacturing reflects dosing infrastructure compatibility across industrial and institutional end users.
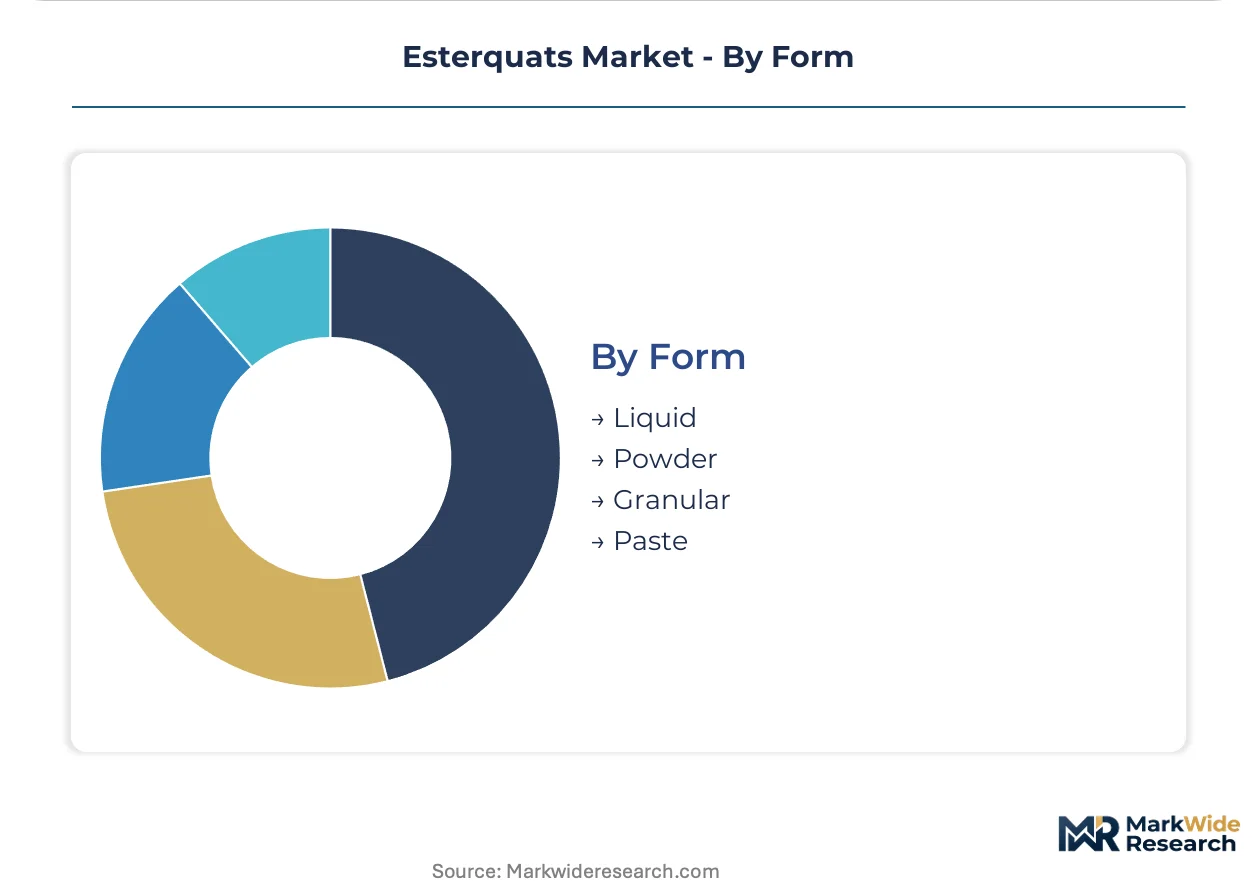
- Liquid:Aqueous dispersions dominate industrial and institutional procurement due to ease of dilution and automated dosing system compatibility. Asset-light toll manufacturing partnerships allow suppliers to lease alkoxylation capacity without fixed capital commitment.
- Powder:Spray-dried formulations serve geographic markets with limited cold-chain logistics infrastructure.
- Granular:Free-flowing solid grades for household laundry detergent co-formulation with controlled release characteristics.
- Paste:High-active concentrates for specialized compounding operations in cosmetics manufacturing.
Liquid holds the preponderance of commercial volume; Powder is gaining share fastest in emerging market detergent applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH restrictions on persistent quaternary ammonium compounds are accelerating esterquat adoption across industrial and household cleaning segments. Germany anchors European demand through specialized cold-water grades, while regulatory pressure in North America and certification requirements in India reshape procurement patterns.
Germany
Industrial laundries and household brands drive demand for cold-water dispersible esterquat grades. ECHA restrictions on legacy quaternary ammonium compounds mandate full supply chain requalification. The Rhineland chemical cluster concentrates quaternization technology and specialized manufacturing capacity for premium fabric softener formulations.
United States
California-based natural home care brands and institutional cleaning operations procure esterquats for Proposition 65 compliance. EPA Safer Choice criteria compress reformulation timelines for dialkyl dimethyl ammonium chloride substitution. The Gulf Coast oleochemical corridor supplies fatty acid methyl ester precursors to domestic surfactant manufacturers.
India
Multinational cosmetics manufacturers establish local technical dossiers for CDSCO cosmetic ingredient standards. BIS certification requirements for personal care create first-mover barriers for imported esterquat suppliers. The Mumbai-Pune industrial belt concentrates contract manufacturing for sulfate-free and silicone-free hair care formulations.
China
Domestic detergent manufacturers source esterquat alternatives amid tightening environmental enforcement. GB standards for biodegradability in cleaning products elevate technical specifications for cationic surfactants. The Yangtze River Delta hosts integrated oleochemical networks extending from palm kernel oil processing to finished surfactant production.
Brazil
Household fabric softener brands reformulate around biodegradable cationic surfactants for export compliance. ANVISA oversight of cosmetic ingredient safety adds registration complexity for personal care applications. The São Paulo metropolitan area concentrates formulation laboratories and distributor networks serving South American markets.
Esterquats Market Vendor Landscape
On the supply side, the industry is consolidating around integrated oleochemical players and specialized quaternization technology holders. Tiered competitive dynamics separate backward-integrated multinationals from asset-light toll manufacturers leasing alkoxylation capacity. Three archetypes dominate: integrated chemical conglomerates with captive palm kernel oil supply, mid-cap surfactant specialists with German quaternization expertise, and regional distributors building technical service capabilities. Capacity expansion in Southeast Asian oleochemical feedstocks and strategic partnerships for cold-water grade development represent the dominant competitive moves.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries exemplify European supply anchoring through specialized quaternization infrastructure and oleochemical network control. Among North American surfactant specialists, Stepan Company occupies a position representing backward integration into fatty acid methyl esters and toll manufacturing partnerships. These three entities collectively illustrate how geographic concentration of quaternization technology and feedstock procurement advantages define competitive positioning in biodegradable cationic surfactants.
| Leading Market Players |
|---|
| Stepan Company |
| Evonik Industries |
| BASF SE |
| Kao Corporation |
| Akzo Nobel N.V. |
| Clariant AG |
| The Lubrizol Corporation |
| Italmatch Chemicals S.p.A. |
| Chemelco International B.V. |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Rhineland barge corridor moves fatty acid methyl ester precursors from Dutch oleochemical terminals to German quaternization sites, with freight cost volatility amplifying price spreads between cold-water certified grades and commodity fabric softener formulations. This logistics chokepoint concentrates pricing power among integrated producers with captive Rhineland manufacturing capacity, while toll manufacturers leasing third-party alkoxylation assets face margin compression from feedstock passthrough clauses.
Pricing Analysis
Cold-water dispersibility certification under Blue Angel and Nordic Swan ecolabels creates the primary spread between premium and standard esterquat grades. Three-tier pricing structure across premium certified, standard industrial, and economy commodity levels reflects quaternization technology access and biodegradability verification depth. Cost compression in economy grades is intensifying because Southeast Asian methyl chloride quaternization routes face displacement from alternative cationic surfactants. Professional cleaning services in Northern Europe exhibit lowest price sensitivity due to mandatory EU Detergent Regulation compliance deadlines, while Asian detergent manufacturers remain most cost-responsive.
Supply Chain Analysis
Tariff exposure between Southeast Asian palm kernel oil producers and European oleochemical processors dominates supply chain risk assessment for esterquat manufacturers. Production gravity centers on Germany, Malaysia, and the United States, with German sites controlling specialized quaternization capacity for cold-water grades. Feedstock supply draws from palm kernel oil methyl esters, triethanolamine, and methyl chloride quaternizing agents. Single-source vulnerability concentrates in Rhineland quaternization infrastructure. Distribution runs through direct procurement relationships between home care brands and specialized manufacturers, displacing traditional surfactant distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized quaternization expertise and verified cold-water formulation capabilities represent scarce assets that concentrate competitive advantage among incumbent producers with German manufacturing footprints. This capability gap widens as EU REACH deadlines compress reformulation timelines for downstream fabric softener and hair care brands.
For Market Incumbents: Build regulatory dossier depth as the primary moat against emerging Asian methyl ester suppliers. Secure backward integration into fatty acid methyl ester supply through long-term offtake agreements with Malaysian oleochemical producers. Expand quaternization capacity at existing German sites to capture premium positioning for Blue Angel-certified cold-water grades ahead of EU Detergent Regulation sunset dates for legacy quaternary ammonium compounds. For New Entrants and Emerging Players: Toll manufacturing partnerships with underutilized alkoxylation assets in India represent the most penetrable entry point for CDSCO-certified cosmetic ingredient supply. CDSCO and BIS certification requirements for personal care applications create first-mover barriers that favor technical dossier investment over capacity buildout. Target sulfate-free hair care formulators in the Mumbai-Pune industrial belt with specialized secondary esterquat grades for silicone-free conditioning applications. For Investors and Strategic Acquirers: Mid-cap surfactant specialists with captive quaternization technology and established EPA Safer Choice registrations present the most attractive acquisition profile for North American market access. Long-term viability hinges on feedstock security and regulatory compliance infrastructure rather than volume scale alone. Monitor pending EU REACH annex amendments for non-biodegradable quaternary ammonium compounds as the critical inflection signal for accelerated esterquat substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fatty Acid Methyl Esters | Captive palm kernel oil supply from Malaysian oleochemical networks secures feedstock cost stability against price volatility. |
| Cold-Water Ecolabel Certification Investment | Blue Angel and Nordic Swan verification enables premium pricing for specialized esterquat dispersions in German industrial laundries. |
| Toll Manufacturing Partnership Expansion | Asset-light alkoxylation leasing allows new entrants to bypass capital-intensive quaternization infrastructure requirements. |
| CDSCO Technical Dossier Development | Local certification for Indian cosmetic ingredient standards creates defensive positioning against multinational supplier competition. |
| Direct Procurement Relationship Cultivation | Bypassing distributor networks captures margin from California natural home care brands facing Proposition 65 litigation exposure. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at European quaternization facilities, procurement leads at home care manufacturers, technical R&D directors at surfactant specialists, and regulatory affairs officers navigating ECHA registration pathways, then refined against secondary validation from customs trade data, Cefic surfactant industry reports, SEC 10-K filings of listed chemical producers, and EPA Safer Choice certified product listings. Bottom-up segmentation modeling triangulated with top-down macroeconomic drivers.
Demand-supply balance dynamics across the analysis window were modeled through reconciliation of fabric softener reformulation timelines, hair care cationic conditioning substitution rates, and industrial laundry procurement patterns against German quaternization capacity utilization and Southeast Asian oleochemical feedstock availability. Segmentation dimensions included esterquat architecture type, application end-use, form factor, and regional regulatory cluster. CAGRs were derived from slope analysis of validated annual progression rates. Industry-specific forecast inputs incorporated EU REACH sunset date schedules and CDSCO certification processing timelines.
Practitioners should monitor palm kernel oil price volatility, ECHA restriction amendment announcements, and Indian BIS standard implementation progress for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Ethyl Polysilicate Market
Specialty Chemicals
Dimethyl Silicone Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Microcrystalline Wax Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
Biocides Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Contouring Products Market
Specialty Chemicals
Prils Market
Specialty Chemicals
Ursolic Acid Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Xanthene Derivatives Market
Specialty Chemicals
Sialic Acid Market
Specialty Chemicals
Diisononyl Adipate (DINA) Market