
 India Prussian Blue Market | 2026-2036
India Prussian Blue Market Size, Share, and Industry Trends Forecast 2026-2036
India Prussian Blue Market Foresight
Automotive coatings demand is realigning the India Prussian Blue Market as OEMs shift toward waterborne paint systems. Colour India leverages its western India manufacturing base to serve this transition. Bhavna Industries anchors supply for construction-grade pigments through direct mill relationships. Anupam Colours & Chemicals Industries specializes in liquid dispersions for ink formulators seeking batch consistency.
Prussian Blue is a coordination compound of iron(III) hexacyanoferrate(II) with the formula Fe4[Fe(CN)6]3, synthesized via precipitation of ferric salts with potassium ferrocyanide to yield pigments with particle sizes between 0.1 and 10 micrometers. It serves primarily as an intense blue colorant in protective and decorative coatings, printing substrates, and polymer masterbatches where lightfastness and chemical stability matter. Powder grades dominate volume shipments to paint manufacturers, while liquid formulations capture margin pools from inkjet and flexographic printers demanding ready-to-use dispersions. The Plastics application segment is expanding fastest as compounders adopt Prussian Blue for PVC siding and automotive interior trim to replace organic pigments with inferior thermal stability.
BIS pigment standards and CDSCO pharmaceutical-grade specifications shape product certification pathways for domestic manufacturers. The PLI scheme for specialty chemicals is channeling capital toward backward integration into ferrocyanide precursors. Stakeholders must monitor how sodium-ion battery research at Indian Institutes of Technology translates into commercial-grade Prussian Blue demand for cathode active materials.
Market Dynamics
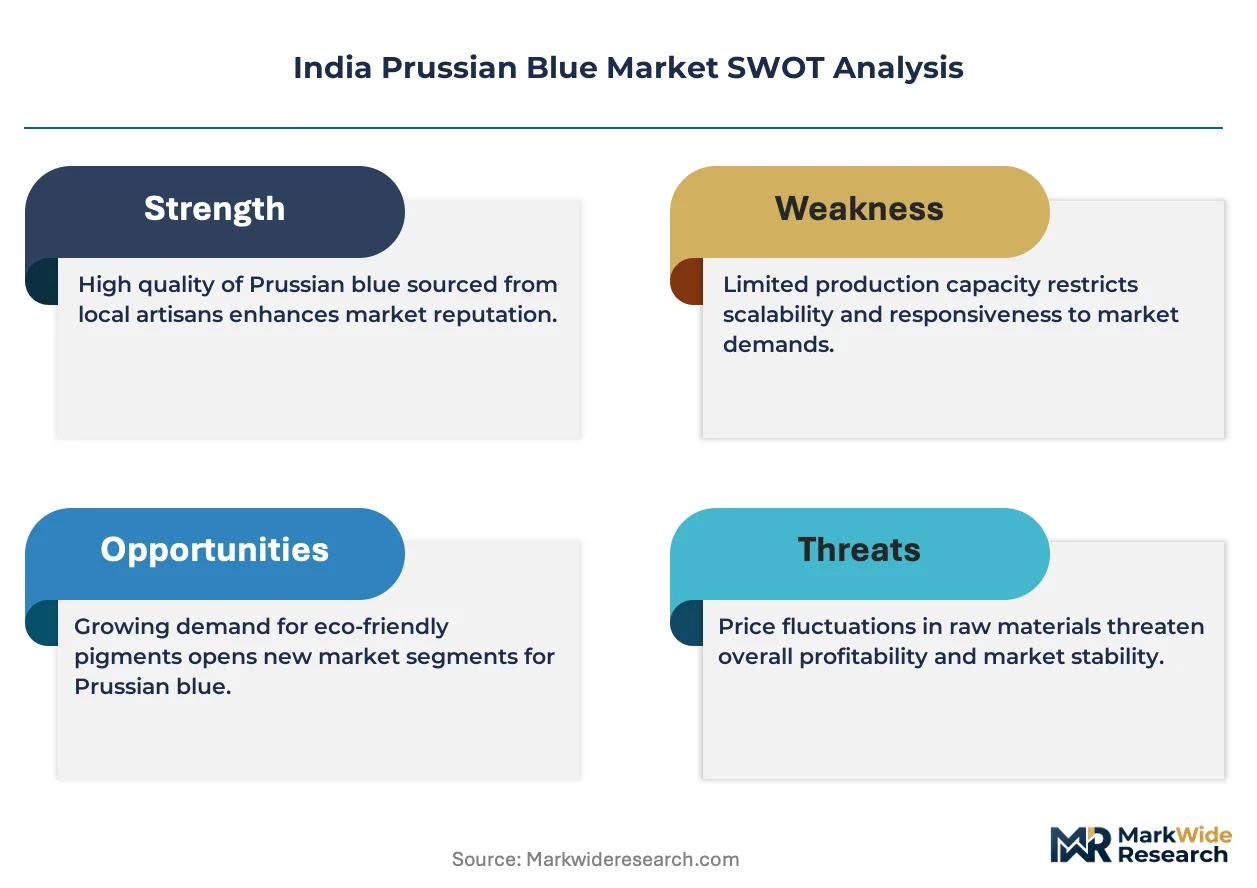
Sodium-ion battery research at Indian Institutes of Technology is redirecting Prussian Blue demand from pigment applications toward cathode active materials, forcing manufacturers to recalibrate capacity allocation between established coatings markets and emerging energy storage supply chains.
Growth Catalysts
- PLI scheme for specialty chemicals:Capital subsidies are accelerating backward integration into ferrocyanide precursors, reducing import dependence for battery-grade feedstock.
- Maharashtra-Gujarat chemical clusters:Concentrated specialty chemical infrastructure enables rapid scale-up of high-purity grades for sodium-ion cathode production.
- BIS pigment purity standards:Tightening certification requirements are filtering out low-grade imports and consolidating domestic manufacturer market presence.
Market Restraints
- Potassium ferrocyanide price volatility:Dependence on imported cyanide salts exposes margins to currency fluctuation and international supply shocks.
- Single-source precursor risk:Domestic ferrocyanide production remains concentrated among three established chemical complexes, creating bottleneck vulnerability.
- Lithium iron phosphate substitution:Competing cathode chemistry is capturing early sodium-ion commercial deployments, delaying Prussian Blue cathode qualification timelines.
Strategic Opportunities
- CDSCO pharmaceutical-grade pathway:Radioprotective and thallium poisoning treatment applications offer premium pricing outside commodity pigment markets.
- Tamil Nadu electronics manufacturing corridor:Underpenetrated southern region presents greenfield demand for inkjet dispersion facilities serving packaging printers.
- Waterborne coatings mandate convergence:Automotive OEM paint system transitions are aligning with Prussian Blue's compatibility with low-VOC formulations.
Industry Challenges
- Battery-grade qualification timelines:Extended cycling data requirements from cell manufacturers are stretching working capital cycles for purity upgrades.
- Dual-certification complexity:Simultaneous BIS pigment and CDSCO pharmaceutical compliance demands parallel quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Prussian Blue Market |
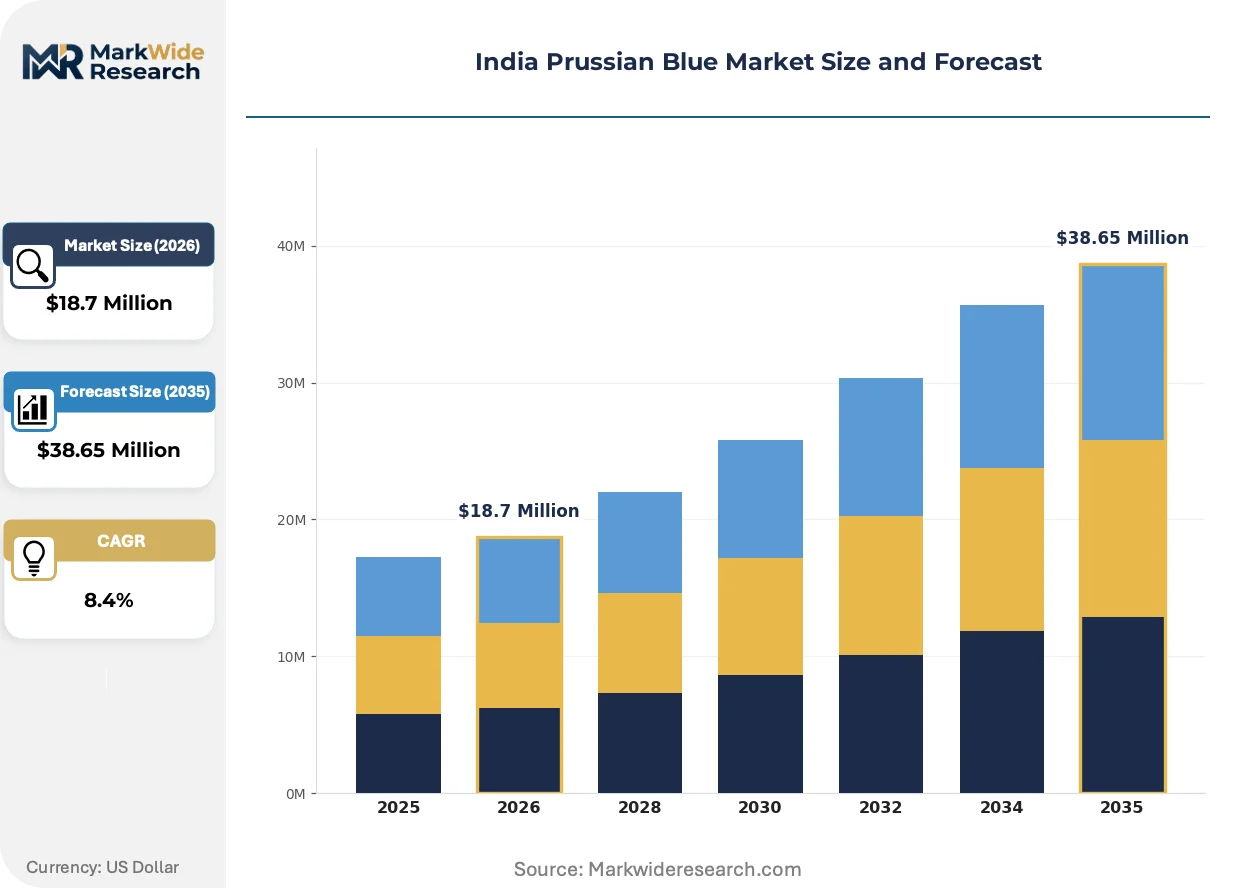
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granule, Paste Application: Paints, Coatings, Plastics, Inks End User: Construction, Automotive, Consumer Goods, Textiles Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Colour India, Bhavna Industries, Sona Synthetics Products, Anupam Colours & Chemicals Industries, Dycon Chemicals, Gaurav Chemicals, Pushp Colours, PD Chemicals, Kunder Chemicals Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Prussian Blue Market Shifts & Advancements
Process intensification and application-specific purification are reshaping how Indian manufacturers compete across pigment, pharmaceutical, and battery material segments simultaneously.
Spray-dried microgranule technology is consolidating particle size distribution control for battery-grade Prussian Blue. Sodium-ion cathode developers at IIT-Madras and IIT-Bombay are specifying sub-micron spherical morphologies that legacy precipitation methods cannot achieve. This specification pressure is compressing the supplier base toward reactor-engineering specialists capable of continuous crystallization.
BIS certification timelines for pigment purity grades are extending qualification periods for new market entrants. The standards body has introduced sequential heavy metal testing protocols that add four to six months to product approval cycles. Maharashtra-based manufacturers with established laboratory relationships are accelerating recertification, while smaller Gujarat producers face backlog-induced market access delays.
Direct mill relationships are displacing distributor networks in construction-grade pigment procurement. Bhavna Industries and comparable buyers are consolidating purchase volumes through annual framework contracts with penalty clauses for batch inconsistency. This concentration is most visible in Gujarat's industrial paint corridor, where compounders now specify particle surface area rather than generic colour index ratings.
India Prussian Blue Market Segmentation
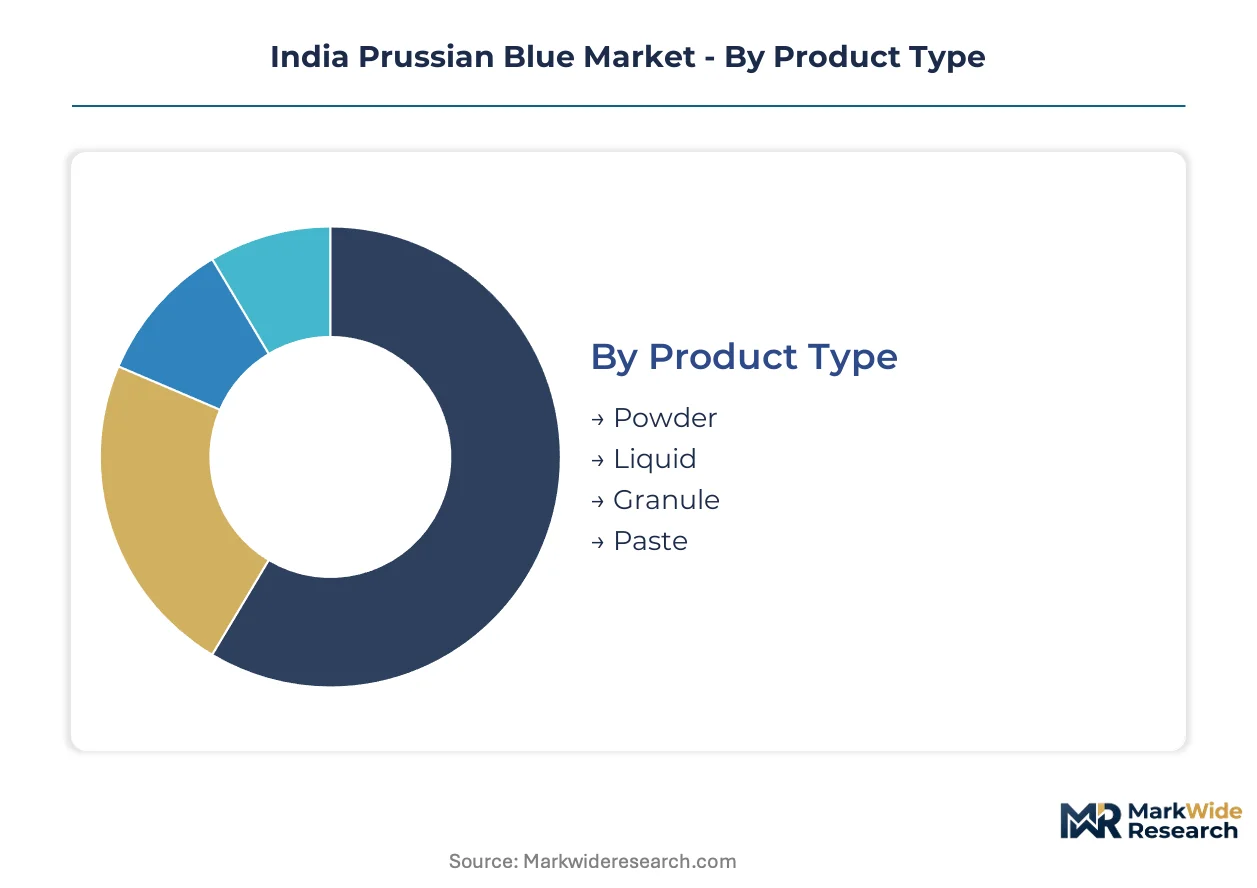
Prussian Blue demand fragments sharply across physical forms and customer workflows. Battery-grade qualification pressures and coatings reformulation mandates are compressing the viable supplier base within each segment.
Product Type:
Customization intensity varies from commodity powder to engineered microgranules for sodium-ion cathodes.
- Powder:Precipitated pigment with particle sizes spanning 0.1 to 10 micrometers serves protective coatings and polymer masterbatches. Maharashtra paint compounders specify surface area metrics rather than generic colour index ratings.
- Liquid:Ready-to-use dispersions eliminate milling steps for flexographic and inkjet printers. Tamil Nadu packaging corridors underpenetrated by dispersion facilities present greenfield capacity opportunities.
- Granule:Spray-dried spherical morphologies meet IIT-Madras battery research specifications for cathode active materials.
- Paste:Pre-dispersed concentrates target small-batch ink formulators seeking batch consistency without capital investment.
Leading the category by volume: Powder. Growing fastest: Granule.
Application:
Margin pools concentrate where thermal stability requirements exclude organic pigment substitutes.
- Paints:Waterborne automotive OEM systems drive reformulation demand compatible with Prussian Blue's chemical stability. Gujarat industrial paint corridors anchor procurement concentration.
- Coatings:Protective applications for infrastructure specify lightfastness under UV exposure. Construction-grade procurement shifts toward direct mill relationships with penalty clauses for inconsistency.
- Plastics:PVC siding and automotive interior trim applications replace thermally unstable organic alternatives. Compounders across Maharashtra-Gujarat clusters specify sub-micron grades for extrusion compatibility.
- Inks:Flexographic and inkjet substrates demand liquid dispersions with controlled rheology. Southern India electronics packaging growth outpaces northern supply infrastructure.
Plastics climbs fastest as thermal stability requirements tighten. Paints maintains volume leadership through automotive transition volumes.
End User:
Customer sophistication spans from specification-driven OEMs to price-sensitive commodity buyers.
- Construction:Industrial paint procurement for infrastructure protection emphasizes batch consistency over premium pricing. Gujarat mill relationships dominate supply access.
- Automotive:OEM waterborne paint mandates align with Prussian Blue compatibility for low-VOC formulations. Western India manufacturing clusters serve this transition.
- Consumer Goods:Packaging ink demand from food and personal care sectors requires regulatory compliance flexibility across pigment and pharmaceutical grades.
- Textiles:Dyeing applications represent legacy demand with limited growth trajectory relative to battery and coatings segments.
Construction commands current volume. Automotive posts steepest expansion trajectory through OEM reformulation cycles.
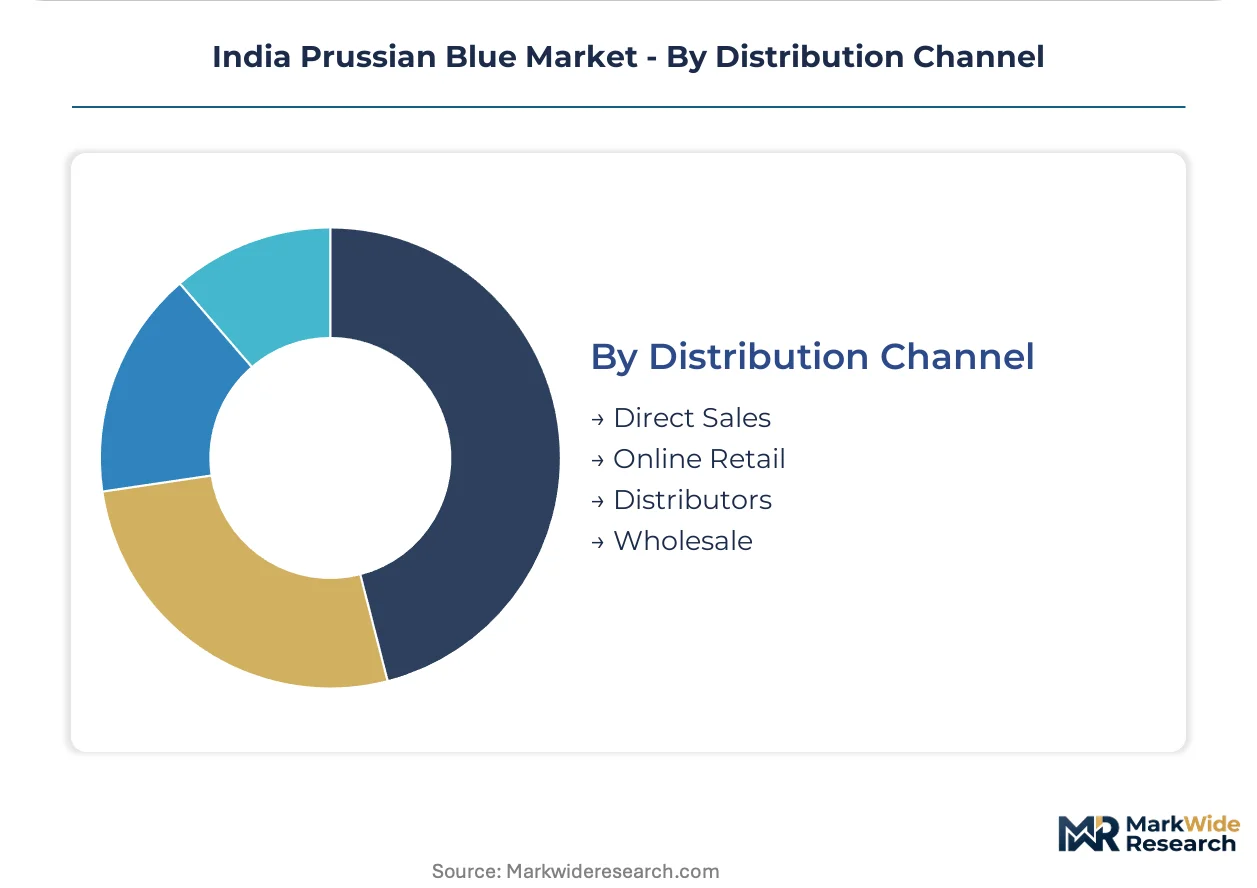
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and certification documentation needs.
- Direct Sales:Annual framework contracts with penalty clauses consolidate construction-grade pigment procurement. Bhavna Industries and comparable buyers displace distributor networks.
- Distributors:Technical service and logistics support remain essential for small-batch ink formulators and regional compounders.
- Wholesale:Bulk powder shipments to paint manufacturers leverage Maharashtra-Gujarat chemical cluster infrastructure.
- Online Retail:Emerging channel for laboratory-scale quantities and specialty dispersion samples.
Direct sales captures margin concentration. Distributors defend position through technical service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PCPIR zones in Gujarat and Maharashtra concentrate specialty chemical capacity through tax holidays and duty exemptions. These designated corridors anchor domestic Prussian Blue production for pigment and emerging battery-grade applications. State-level industrial policies channel investment toward backward integration into ferrocyanide precursors.
Maharashtra
Mumbai-Pune chemical belt hosts precipitation reactors serving paint compounders with sub-micron pigment grades. The state's industrial infrastructure development scheme subsidizes laboratory certification for BIS compliance. Thane district manufacturers supply waterborne automotive coatings to OEM paint shops in Chakan and Talegaon.
Gujarat
Dahej and Vadodara chemical complexes produce construction-grade pigments through direct mill relationships with industrial paint buyers. The state's single-window clearance mechanism accelerates environmental permits for ferrocyanide precursor expansion. Ankleshwar cluster compounders specify particle surface area metrics for PVC siding applications.
Tamil Nadu
Sriperumbudur electronics corridor generates packaging ink demand outpacing northern dispersion infrastructure. The state's advanced manufacturing policy offers capital subsidies for specialty chemical greenfield investments. Chennai-based inkjet formulators import liquid dispersions due to local supply gaps.
Karnataka
Bengaluru-Tumkur industrial zone supports pharmaceutical-grade qualification for radioprotective applications under CDSCO oversight. The state's biotechnology policy incentivizes high-purity chemical manufacturing for medical device supply chains. Peenya industrial estate laboratories facilitate heavy metal testing protocols for dual certification pathways.
Telangana
Hyderabad pharma cluster creates ancillary demand for pharmaceutical-grade Prussian Blue in thallium poisoning treatment formulations. The state's life sciences policy extends fast-track approvals for active pharmaceutical ingredient precursors. Genome Valley contract manufacturers source specification-grade materials from western Indian suppliers.
India Prussian Blue Market Competitive Landscape
Top-tier vendors anchor pigment purity certification, while mid-scale specialists occupy battery-grade development niches. The supplier base stratifies across precipitation-engineering capability and regulatory compliance depth. Three archetypes dominate: western India chemical conglomerates with BIS-accredited laboratories, regional pigment specialists serving construction coatings, and emerging cathode material developers partnering with IIT research programs. Competitive intensity concentrates on backward integration into ferrocyanide precursors and spray-dried granule technology licensing.
Among western India-based manufacturers, Colour India, Bhavna Industries, and Anupam Colours & Chemicals Industries occupy distinct tier positions. Colour India exemplifies the integrated chemical complex archetype with precipitation capacity serving automotive OEM reformulation cycles. Bhavna Industries represents the construction-grade procurement consolidation pattern through direct mill relationships. Anupam Colours & Chemicals Industries anchors the liquid dispersion specialist segment for ink formulators seeking batch consistency without capital investment.
| Leading Market Players |
|---|
| Colour India |
| Bhavna Industries |
| Sona Synthetics Products |
| Anupam Colours & Chemicals Industries |
| Dycon Chemicals |
| Gaurav Chemicals |
| Pushp Colours |
| PD Chemicals |
| Kunder Chemicals Pvt Ltd |
| Others |
Supply & Pricing Matrix
Potassium ferrocyanide import price volatility cascades through Maharashtra-Gujarat chemical corridors into three distinct pricing tiers. Battery-grade granules command premium positioning against construction-grade powders, while pharmaceutical certification adds a further cost stratum tied to CDSCO compliance overhead.
Pricing Analysis
Lead-time compression drives premium capture for battery-grade Prussian Blue with sub-micron spherical morphology specifications. A three-tier pricing structure separates pharmaceutical-grade CDSCO-certified material from BIS pigment grades and uncertified commodity powder, with differentiation anchored in heavy metal testing protocols and particle surface area metrics. Pricing pressure stems from lithium iron phosphate substitution delaying sodium-ion cathode commercialization timelines. Construction-grade buyers in Gujarat industrial paint corridors exhibit highest price sensitivity through consolidated annual framework contracts, while IIT-partnered battery developers accept extended lead times for qualified material.
Supply Chain Analysis
Regional distribution centers in Thane and Ankleshwar operate hub-and-spoke patterns serving Tamil Nadu and Karnataka demand through third-party logistics networks. Geographic supply concentration rests on China and Germany for potassium ferrocyanide precursor salts, with domestic production limited to Dahej, Vadodara, and Mumbai-Pune chemical belts. Raw material dependencies include potassium ferrocyanide, ferric chloride, and sodium ferrocyanide for battery-grade variants. Single-source precursor vulnerability concentrates among three established chemical complexes. Distribution runs through direct mill relationships displacing traditional distributor networks in construction-grade segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ferrocyanide precursor capacity constraints prop pricing across all qualification tiers, with domestic backward integration lagging sodium-ion cathode demand timelines by several production cycles.
For Market Incumbents: Deepen captive ferrocyanide production at Dahej and Vadodara complexes to offset potassium salt import exposure. Secure dual BIS-CDSCO laboratory accreditation ahead of competitor recertification backlogs. Lithium iron phosphate substitution threatens cathode-grade volume realization; prioritize spray-dried granule reactor engineering partnerships with IIT-Madras research programs. For New Entrants and Emerging Players: Capture Tamil Nadu packaging ink dispersion gaps through greenfield liquid formulation facilities in Sriperumbudur corridor. Target pharmaceutical-grade radioprotective applications under CDSCO oversight where incumbent capacity allocation favors pigment and battery segments. A technical service bundling go-to-market model penetrates small-batch ink formulator accounts resistant to capital investment in milling infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor precipitation-engineering specialists with existing BIS laboratory relationships in Maharashtra over greenfield certification plays. Long-term viability hinges on sodium-ion battery cathode qualification converting research demand into commercial offtake. Monitor IIT-Bombay and IIT-Madras pilot line announcements as inflection indicators for battery-grade pricing tier expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrocyanide Precursors | Reduces import dependence and stabilizes input costs for battery-grade production. |
| Spray-Dried Granule Capacity Expansion | Meets IIT-Madras cathode specifications and compresses qualified supplier base. |
| Dual BIS-CDSCO Certification Investment | Unlocks pharmaceutical-grade premium pricing outside commodity pigment markets. |
| Tamil Nadu Dispersion Facility Greenfield | Closes supply gap for Sriperumbudur electronics packaging ink demand. |
| Direct Mill Relationship Consolidation | Replaces distributor networks with penalty-clad annual framework contracts in Gujarat. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with plant managers at Maharashtra-Gujarat chemical complexes, procurement leads at automotive OEM paint shops, technical R&D directors at specialty chemical firms, and CDSCO regulatory affairs specialists validated demand assumptions. Secondary sources included BIS certification databases, CDSCO pharmaceutical-grade specifications, PLI scheme disbursement records, and IIT research program disclosures. Bottom-up volume estimates from end-use consumption patterns triangulated against top-down production capacity assessments across PCPIR zones.
Granularity-level modeling addressed product type, application segment, end-user industry, and distribution channel dimensions across the analysis window. Grade-tier segmentation captured powder, liquid, granule, and paste variants with distinct pricing and margin structures. Regional production hub clustering reflected PCPIR tax incentive zones and state-level industrial policy differentiation. CAGRs derived from fitted growth curves applied to qualified demand segments, with battery-grade qualification timelines and automotive OEM reformulation cycles as industry-specific forecast inputs.
The model holds under stable potassium ferrocyanide import availability and continued PLI scheme disbursement; deviation in currency volatility or sodium-ion battery chemistry substitution would shift volume allocation across segments. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Magnesium Gluconate Market
Specialty Chemicals
Cellulose Ether and Derivatives Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
L-Ergothioneine Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Bemotrizinol Market
Specialty Chemicals
Natural Ingredient Insect Repellent Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
UV/IR Blocker Market
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Global Sodium Hyaluronate-Based Products Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Stable Isotopes Market