
 Sailcloth Market | 2026-2036
Sailcloth Market Size, Share, and Industry Trends Forecast 2026-2036
Sailcloth Market Analysis
High-performance laminate construction is reconfiguring how racing and cruising sails are engineered for durability and shape retention. Dimension-Polyant GmbH leverages its German manufacturing base to dominate premium laminate supply for Grand Prix racing circuits. Challenge Sailcloth anchors its position through deep specialization in aramid-based woven fabrics for military and superyacht segments. Doyle Sailmakers competes by sustaining an integrated design-to-fabrication model that tightens feedback loops between sail designers and looms.
Sailcloth denotes engineered textile fabrics designed to convert wind energy into propulsive force, typically constructed from high-tenacity polyester, aramid, or carbon-fiber composite yarns with denier ratings exceeding 1,000D and finished through lamination or coating processes to resist UV degradation and salt corrosion. Polyester laminates command the largest volume share across recreational boating due to cost-performance balance, while aramid segments capture disproportionate margin pools in racing and military applications where weight reduction justifies premium positioning. Woven manufacturing retains dominance in cruising and cargo vessel supply chains, whereas laminated processes are displacing legacy constructions in performance racing as film-adhesive technologies mature.
FDA oversight of marine-grade adhesive chemistries, EPA regulations on perfluorinated water-repellent coatings, and ISO 9001 maritime equipment certification collectively constrain material selection and surface treatment options for suppliers accessing North American and European waters. ECHA REACH restrictions on persistent organic pollutants in textile finishing directly impact coated sailcloth formulations sold into EU member states. Stakeholders must monitor evolving chemical compliance thresholds while calibrating R&D investment between bio-based fiber alternatives and incremental laminate performance gains.
Market Dynamics
Film-adhesive lamination technologies are compressing the performance gap between woven and laminated sail constructions, forcing suppliers to recalibrate R&D allocation between incremental laminate gains and bio-based fiber alternatives.
Growth Catalysts
- Grand Prix Racing Circuits:Competitive sailing programs in Germany and the United States drive specification of ultra-high-modulus laminates with integrated carbon-fiber load paths.
- ECHA REACH Phase-Down:Persistent organic pollutant restrictions in EU member states accelerate reformulation of coated sailcloth toward fluorine-free water-repellent chemistries.
- Aramid Fiber Maturation:Military and superyacht segments absorb premium-priced woven aramid constructions for blast-resistant and heavy-weather applications.
Market Restraints
- Petrochemical Feedstock Volatility:High-tenacity polyester and aramid yarn production remains tethered to benzene and para-aramid precursor pricing swings.
- German Manufacturing Concentration:Premium laminate supply chains cluster in Baden-Württemberg and Bavaria, creating single-point vulnerability for Grand Prix racing procurement.
- UV Degradation Ceiling:Current film-adhesive formulations face hard limits on tropical exposure hours before delamination risk escalates.
Strategic Opportunities
- Chinese Coastal Manufacturing:Qingdao and Zhoushan clusters offer underutilized laminating capacity for mid-tier cruising sail production.
- US Military Specification Contracts:Department of Defense procurement for expeditionary sailing vessels mandates domestic-source aramid woven supply.
- ISO 9001 Maritime Certification Convergence:Harmonized equipment standards across North American and European waters reduce duplicate testing burdens for cross-Atlantic suppliers.
Industry Challenges
- Adhesive Chemistry Expertise Gap:Marine-grade polyurethane and thermoplastic elastomer formulation requires polymer scientists with sail-specific film-bonding experience.
- Loom-to-Laminate Capital Intensity:Integrated design-to-fabrication models demand simultaneous investment in CAD-driven cutting tables and multi-axis laminating presses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sailcloth Market |
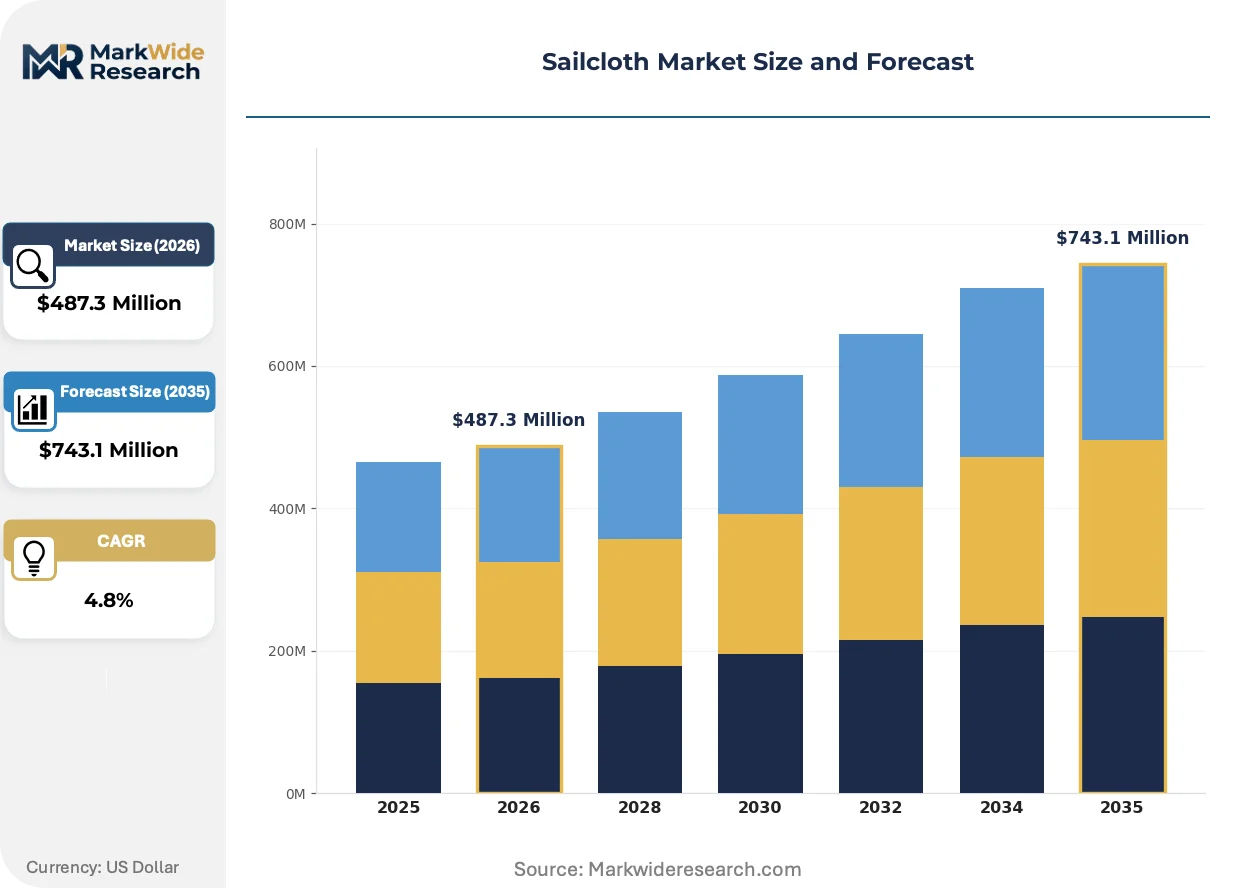
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polyester, Nylon, Cotton, Aramid Application: Sailing Yachts, Racing Boats, Cargo Vessels, Recreational Boats Manufacturing Process: Woven, Laminated, Coated, Non-Woven End User: Commercial, Recreational, Military, Government |
| Companies Covered | Dimension-Polyant GmbH, Bainbridge International, Contender Sailcloth, Challenge Sailcloth, North Sails, Quantum Sails, Doyle Sailmakers, Powerplast, Ullman Sails, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sailcloth Market Emerging Trajectories
Active reshaping of the sailcloth market centers on three vectors: material hybridization breaking the woven-versus-laminated binary, regulatory chemistry phase-outs forcing formulation pivots, and procurement consolidation among superyacht builders compressing supplier margins.
Carbon-polyester hybrid yarns are hybridizing load-bearing sail constructions by embedding discontinuous carbon fiber within continuous polyester matrices. Grand Prix racing teams in Germany and the United States specify these hybrids for headsails requiring both shape retention and controlled stretch. The technology is hybridizing competitive positioning between pure carbon laminates and legacy polyester weaves, compressing the premium tier into a narrower performance band.
ECHA REACH restrictions on perfluorinated compounds in textile finishing are forcing European suppliers to validate bio-based water-repellent alternatives through accelerated salt-spray testing protocols. Industrial consequence includes extended certification timelines for coated sailcloth entering EU waters. Cruising segments with shorter replacement cycles absorb compliance costs more readily than military contractors locked into decade-long specification cycles.
Superyacht builders are consolidating sail procurement under single-source agreements with integrated design-to-fabrication houses, displacing the traditional model of independent sailmakers competing per-vessel. This channel compression concentrates volume with looms possessing captive design studios. The shift is most visible in Mediterranean and Caribbean refit hubs where 80-meter-plus vessels demand synchronized sail replacement across multiple rigs.
Sailcloth Market Segmentation
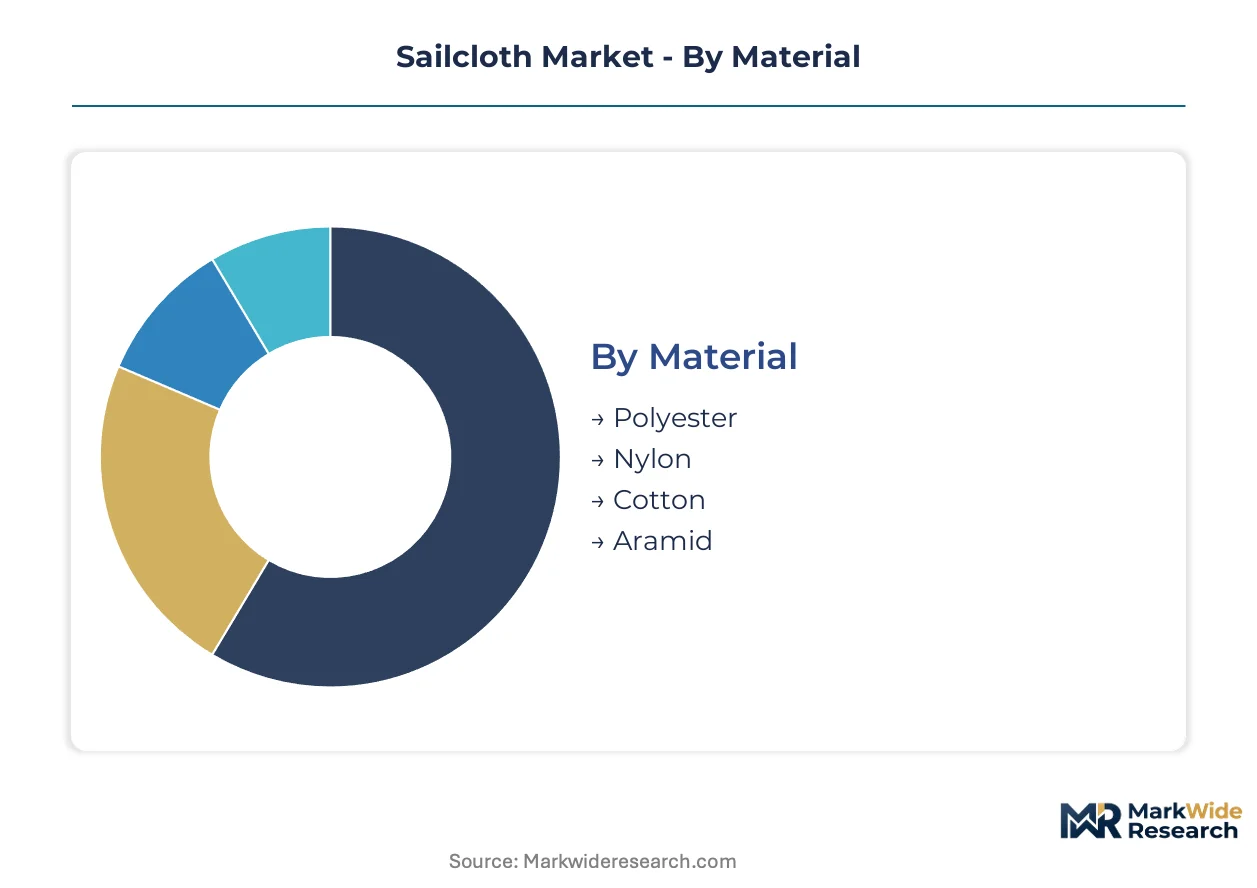
Sailcloth segmentation reveals how material chemistry, construction method, and end-use severity create distinct procurement channels with incompatible certification requirements. Suppliers must maintain parallel production lines serving Grand Prix racing specifications alongside military blast-resistance standards.
Material:
Mature commodity fibers dominate volume while emerging high-modulus alternatives capture margin concentration in performance segments.
- Polyester:High-tenacity polyethylene terephthalate yarns with denier ratings exceeding 1,000D form the backbone of recreational cruising inventory. German and United States coastal manufacturers consume the largest polyester volumes for charter fleet replacement cycles where cost-performance balance outweighs extreme weight reduction.
- Aramid:Para-aramid and meta-aramid constructions deliver specific strength five times greater than steel by weight. Military specification contracts from the United States Department of Defense and superyacht blast-protection requirements in Germany absorb premium-priced woven aramid output despite extended procurement timelines.
- Nylon:Elastic recovery properties suit spinnaker and downwind sail applications where controlled stretch improves gust response.
- Cotton:Heritage craft and museum vessel restoration sustain niche demand for traditional duck canvas construction.
Polyester retains volume leadership; aramid holds the steepest expansion curve.
Application:
Cost tier stratification separates hand-built racing inventory from standardized cargo vessel supply.
- Sailing Yachts:Cruising yachts between 12 and 24 meters drive specification of durable woven polyester for mainsails and genoas. Mediterranean and Caribbean refit hubs concentrate demand for complete sail wardrobes on vessels requiring synchronized multi-rig replacement.
- Racing Boats:Grand Prix circuits in Germany and the United States mandate carbon-reinforced laminates with integrated load-path engineering. Film-adhesive construction with ultra-high-modulus fiber placement dominates this segment where shape retention under dynamic loading determines competitive outcome.
- Cargo Vessels:Auxiliary sail propulsion on wind-assisted shipping routes sustains heavy-duty woven polyester demand.
- Recreational Boats:Day-sailing and coastal cruising fleets absorb mid-tier laminated constructions from Chinese manufacturing clusters.
Sailing yachts retain volume leadership; racing boats hold the steepest expansion curve.
Manufacturing Process:
Geography of supply concentration shapes which construction methods dominate regional procurement patterns.
- Woven:Interlaced warp and weft construction using traditional loom technology produces durable sails for cruising and cargo applications. Baden-Württemberg and Bavaria clusters in Germany maintain specialized capacity for military-grade woven aramid.
- Laminated:Film-adhesive bonding of fiber layers with oriented load paths enables precise engineering of stretch characteristics. Grand Prix racing procurement concentrates demand for this process where CAD-driven cutting tables integrate with multi-axis laminating presses.
- Coated:Surface treatment with water-repellent chemistries extends UV resistance and salt corrosion protection.
- Non-Woven:Random fiber orientation through needle-punch or thermal bonding serves specialty industrial applications.
Woven retains volume leadership; laminated holds the steepest expansion curve.
End User:
Customer type determines certification burden and replacement cycle length.
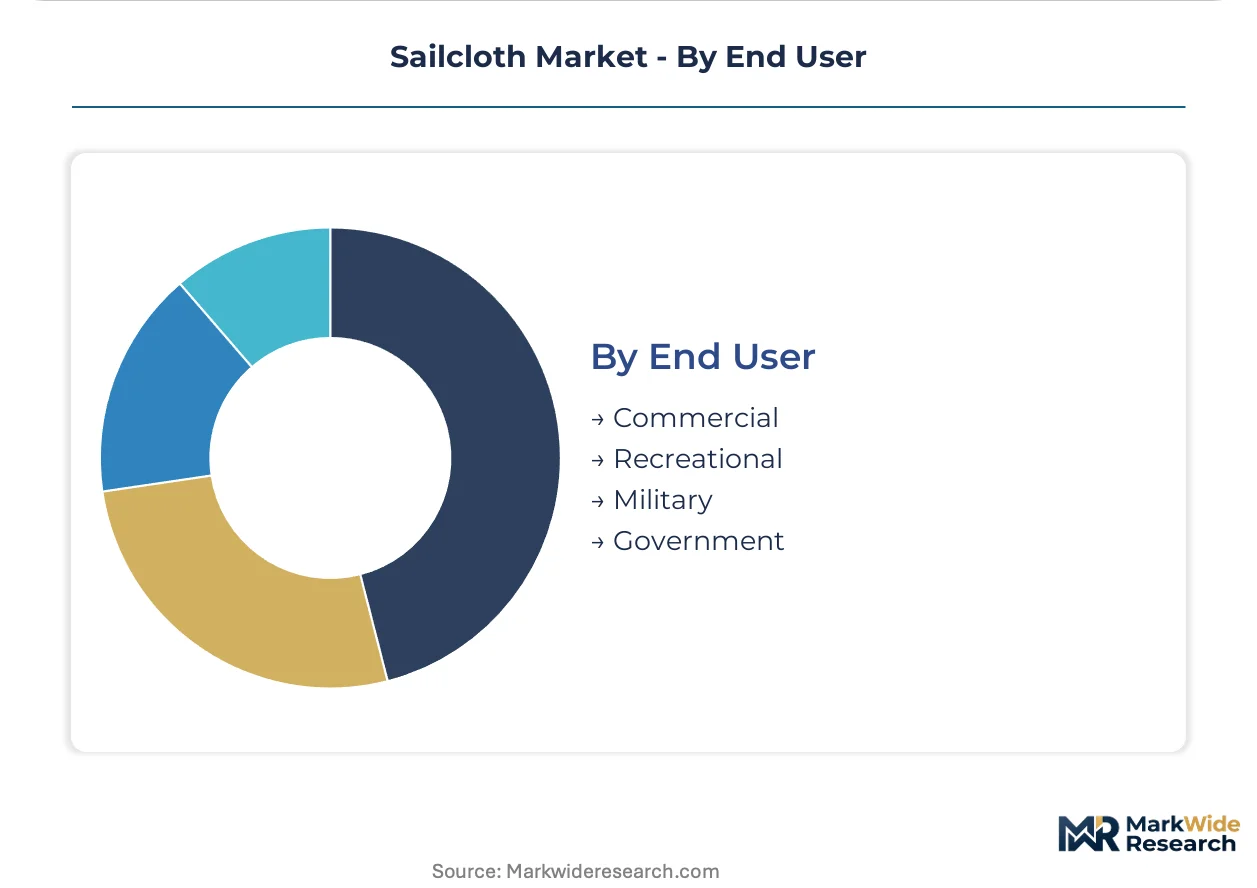
- Commercial:Charter operators and wind-assisted shipping lines prioritize durability and predictable replacement scheduling over extreme performance. ECHA REACH compliance for EU-flagged vessels adds formulation validation costs absorbed through longer contract terms.
- Recreational:Individual boat owners and sailing clubs represent fragmented demand with seasonal purchasing patterns concentrated in pre-season refit windows.
- Military:Blast-resistant and expeditionary sailing specifications from the United States Department of Defense mandate domestic-source aramid woven supply with decade-long certification cycles.
- Government:Coast guard and maritime patrol vessel procurement follows military-adjacent standards with modified volume requirements.
Recreational retains volume leadership; military holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grand Prix racing syndicates and military procurement offices concentrate purchasing power across four distinct national markets. Each geography exhibits unique regulatory friction and manufacturing specialization that shapes supplier access and product certification pathways.
United States
Department of Defense expeditionary sailing contracts and competitive one-design racing circuits absorb premium aramid woven output. EPA regulations on perfluorinated water-repellent coatings constrain surface treatment options for coated sailcloth entering domestic waters. Newport and Annapolis clusters anchor design-to-fabrication houses serving Atlantic Coast racing fleets.
Germany
Baden-Württemberg laminate specialists supply Grand Prix racing teams with ultra-high-modulus carbon-reinforced constructions. ECHA REACH persistent organic pollutant restrictions mandate fluorine-free chemistry validation for EU-flagged vessel applications. Bavarian military-grade woven aramid capacity serves blast-resistant specifications for superyacht and defense segments.
China
Qingdao and Zhoushan coastal manufacturing clusters offer underutilized laminating capacity for mid-tier cruising sail production. GB standards for maritime equipment certification create parallel compliance pathways distinct from ISO frameworks. Domestic yacht charter fleet expansion drives specification of cost-optimized polyester laminates for recreational cruising.
United Kingdom
Solent-based racing sail looms and Mediterranean refit brokers coordinate multi-rig replacement schedules for superyacht fleets. Maritime and Coastguard Agency equipment safety notices influence material selection for commercial passenger vessels under Red Ensign registry. Southampton manufacturing retains specialized capacity for traditional woven cotton restoration on heritage craft.
Australia
Sydney and Melbourne sailing clubs sustain replacement demand for cruising polyester inventories across Tasman Sea charter operations. Australian Maritime Safety Authority domestic commercial vessel standards impose equipment certification burdens distinct from ISO harmonization efforts. Queensland coastal repair facilities concentrate spinnaker and downwind sail fabrication using nylon elastic recovery constructions.
Sailcloth Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Integrated design-to-fabrication houses with captive looms and CAD-driven cutting infrastructure occupy the premium tier. Specialized laminate suppliers with film-adhesive expertise and military certification access form a distinct middle tier. Volume-oriented woven polyester producers serving charter fleet replacement cycles populate the commodity tier. Competitive moves center on geographic expansion into Chinese coastal manufacturing clusters and backward integration into fiber precursor supply.
Within the German-engineered laminate tier, Dimension-Polyant GmbH exemplifies the integrated production model, while Challenge Sailcloth occupies a position among aramid woven specialists. Doyle Sailmakers represents the design-to-fabrication house archetype with captive manufacturing integration. These three entities anchor distinct competitive vectors without exhaustive market coverage.
| Leading Market Players |
|---|
| Dimension-Polyant GmbH |
| Bainbridge International |
| Contender Sailcloth |
| Challenge Sailcloth |
| North Sails |
| Quantum Sails |
| Doyle Sailmakers |
| Powerplast |
| Ullman Sails |
| Others |
Supply Flow & Price Mechanics
Baden-Württemberg laminate specialists command pricing power through captive film-adhesive capacity serving Grand Prix racing procurement, while Chinese coastal clusters compress margins for mid-tier cruising polyester through underutilized laminating presses. This geographic bifurcation creates divergent pricing regimes where German engineered laminates sustain premium positioning against Asian volume competition.
Pricing Analysis
Cost-plus contracts with benzene and para-aramid precursor indexation dominate raw material pass-through structures for high-tenacity polyester and aramid yarn supply. Price differentiation rests on ISO 9001 maritime certification tier and Grand Prix racing specification grade, with military blast-resistant woven aramid commanding the least price sensitivity. Pricing pressure intensifies in recreational cruising segments as Chinese manufacturing clusters absorb ECHA REACH compliance costs more efficiently than European coated sailcloth suppliers.
Supply Chain Analysis
Extended payment terms from superyacht builders and supply-chain finance facilities from German laminate houses lubricate working capital through multi-rig replacement cycles. Raw material supply draws from petrochemical feedstocks in Germany, high-tenacity polyester precursors in the United States, and aramid fiber from domestic military specification mills. Single-source vulnerability concentrates in Bavarian woven aramid capacity for Department of Defense procurement. Distribution runs through integrated design-to-fabrication houses with captive looms and Mediterranean refit brokers coordinating synchronized sail wardrobes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sailcloth demand tracks the replacement cycle of competitive sailing programs and superyacht refit schedules, positioning the market for cyclical recovery as Grand Prix syndicates refresh inventory ahead of upcoming racing seasons.
For Market Incumbents:Harden film-adhesive chemistry expertise against adhesive formulation talent scarcity by securing polymer scientists with sail-specific film-bonding experience through targeted recruitment from German technical universities. Consolidate backward integration into carbon-fiber precursor supply to defend margin position against petrochemical feedstock volatility, while expanding captive laminating capacity in Qingdao clusters to capture mid-tier cruising volume without diluting premium German brand positioning.
For New Entrants and Emerging Players:Australian coastal repair facilities and Queensland spinnaker fabrication shops present underpenetrated white-space for nylon elastic recovery constructions serving Tasman Sea charter operations. Target recreational sailing clubs in Sydney and Melbourne with cost-optimized polyester laminates sourced from Zhoushan manufacturing clusters, leveraging domestic commercial vessel standards from the Australian Maritime Safety Authority as a compliance pathway distinct from ISO harmonization burdens facing established European suppliers.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors integrated design-to-fabrication houses with captive CAD-driven cutting infrastructure and military certification access over standalone woven polyester producers facing channel compression from superyacht builder consolidation. Long-term viability across the projection horizon rests on adhesive chemistry R&D pipelines and bio-based fiber alternative portfolios rather than legacy loom capacity. Monitor ECHA REACH phase-down timelines for perfluorinated compound restrictions as the inflection indicator for formulation pivot costs and extended certification timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Film-Adhesive Capacity Expansion | Multi-axis laminating presses in Baden-Württemberg capture Grand Prix racing specification demand. |
| Backward Integration into Fiber Precursors | Captive para-aramid supply hedges against benzene pricing volatility for military contracts. |
| Fluorine-Free Chemistry Validation | ECHA REACH compliance for EU-flagged vessels extends certification timelines for coated sailcloth. |
| Chinese Coastal Manufacturing Partnership | Qingdao and Zhoushan clusters absorb mid-tier cruising volume with cost-optimized polyester laminates. |
| Military Specification Certification Investment | Department of Defense procurement mandates domestic-source aramid woven supply with decade-long cycles. |
Methodological Framework
Desk research of customs and trade data, SEC filings from publicly listed marine equipment suppliers, and ISO maritime equipment certification databases preceded structured interviews with sail designers at Grand Prix racing syndicates, procurement officers at superyacht builders, polymer scientists at German laminate houses, and distribution channel partners in Mediterranean refit hubs. Bottom-up triangulation across material volume flows and top-down validation against end-use replacement cycles anchored market sizing.
Assumptions held fixed include ECHA REACH regulatory phase-down timelines, petrochemical feedstock pricing corridors, and competitive sailing program investment levels; variables tested included Chinese manufacturing cluster utilization rates and military specification contract award timing. Segmentation modeling spanned material chemistry, construction method, and end-use severity across the analysis window. CAGRs derived from regression analysis of historical replacement cycles projected against fleet age distributions and refit scheduling patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese laminate specialists or accelerated bio-based fiber commercialization by European suppliers would shift outcomes. Macroeconomic deviation in charter fleet investment, regulatory acceleration of perfluorinated compound restrictions, or breakthrough film-adhesive durability improvements would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Yarn and Fabric Manufacturing
Cotton Bags Market
Yarn and Fabric Manufacturing
Printed Tissue Paper Market
Yarn and Fabric Manufacturing
Global Cashmere Yarn Market
Yarn and Fabric Manufacturing
Canvas Roll Market
Yarn and Fabric Manufacturing
Poly Cotton Fabric Market
Yarn and Fabric Manufacturing
Linen Fabric Market
Yarn and Fabric Manufacturing
Poly Cotton Market
Yarn and Fabric Manufacturing
Egypt Textile Manufacturing Market
Yarn and Fabric Manufacturing
Europe Textile Market
Yarn and Fabric Manufacturing
Wool Worsted Yarn Market
Yarn and Fabric Manufacturing
Knitted Fabric Market
Yarn and Fabric Manufacturing
South America Cotton Market
Yarn and Fabric Manufacturing
Textile Fabrics Market
Yarn and Fabric Manufacturing
Fancy Yarn Market
Yarn and Fabric Manufacturing
Tire Yarn Market
Yarn and Fabric Manufacturing
Denim Fabric Market