
 ISO Cylinder Market | 2026-2036
ISO Cylinder Market Size, Share, and Industry Trends Forecast 2026-2036
ISO Cylinder Market Foresight
Aftermarket service revenue is tilting toward predictive maintenance contracts as OEMs seek recurring income beyond hardware sales. SMC Corporation leverages its Japanese manufacturing base to dominate high-precision pneumatic supply chains across Asia. Parker Hannifin anchors North American demand through extensive distribution networks serving hydraulic infrastructure. Bosch Rexroth differentiates via integrated motion control platforms that bundle ISO cylinders with servo drives and linear guides.
An ISO cylinder is a standardized linear actuator conforming to dimensional and mounting specifications set by the International Organization for Standardization, typically constructed from aluminum or stainless steel barrels with chrome-plated piston rods operating at pressures up to 10 bar. These devices convert compressed air or hydraulic fluid energy into controlled mechanical motion for positioning, clamping, and lifting tasks across industrial equipment. Pneumatic cylinders occupy the largest share of product type demand due to their cost efficiency in clean environments, while electric cylinders represent the fastest-growing category as servo motor costs decline and precision requirements intensify. Among end users, automotive manufacturing sustains the highest volume consumption, though robotics applications are capturing expanding margin pools through integration with collaborative automation platforms.
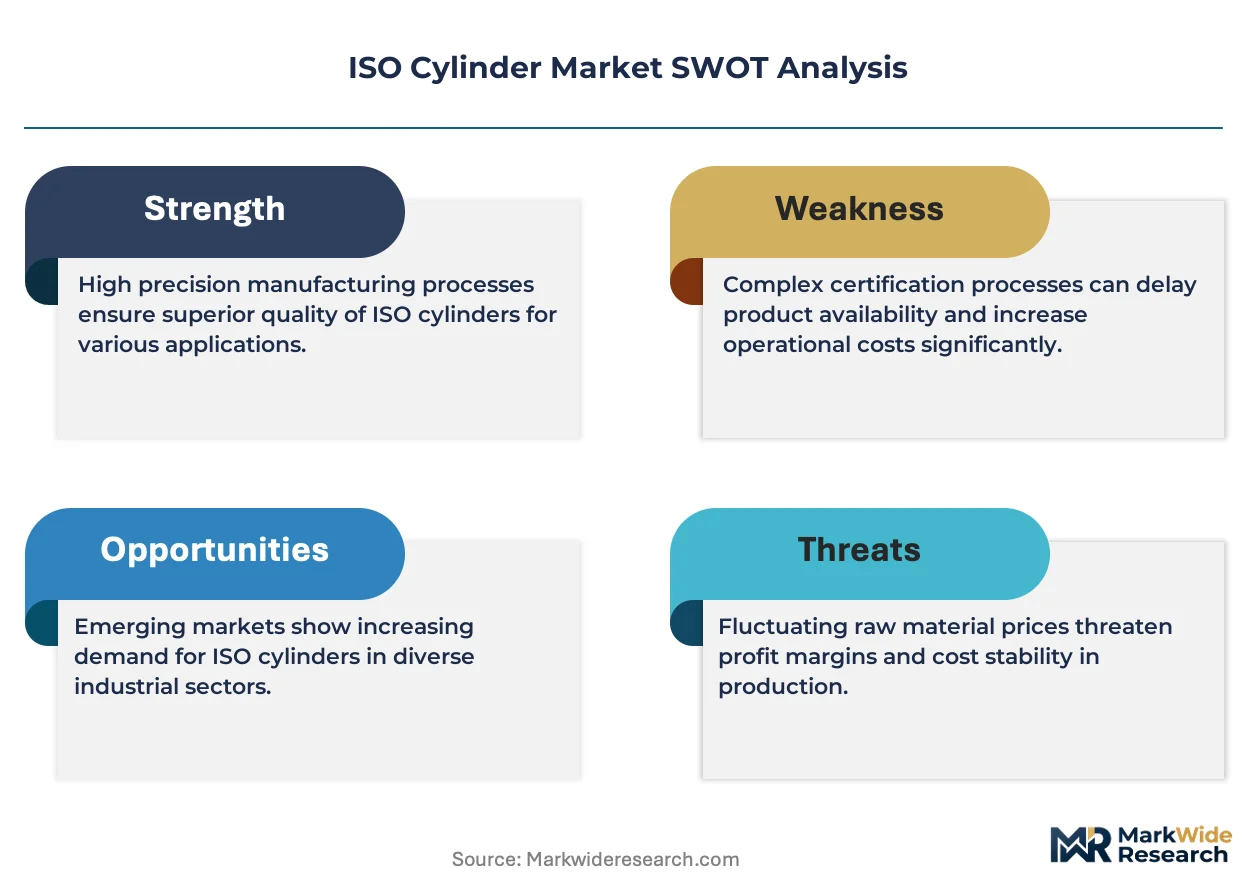
The ISO framework itself governs interchangeability dimensions, while regional regulators including the EPA in the United States enforce emissions standards that affect pneumatic system compressor efficiency and leak-rate thresholds. China's SAMR administers GB standards that mandate cylinder testing protocols for pressure vessels, creating compliance barriers for non-certified imports. Stakeholders must monitor evolving energy-efficiency regulations that increasingly factor total cost of ownership into procurement specifications rather than unit price alone.
Market Dynamics
Factory automation upgrades across China's eastern manufacturing belt are compressing replacement cycles for pneumatic actuators while REACH compliance and GB standards force material specification changes that ripple through supplier qualification processes.
Growth Catalysts
- Automotive assembly automation:Tier-1 suppliers in Germany, Japan, and the United States are expanding cylinder procurement to support electric vehicle retooling and battery pack positioning systems.
- REACH material mandates:ECHA restrictions on chrome plating and seal elastomers are accelerating hardware replacement across European industrial fleets as legacy inventory phases out.
- Servo motor cost curves:Declining prices for precision electric drives are pulling demand toward electromechanical cylinders in robotics and semiconductor handling equipment.
Market Restraints
- Aluminum alloy supply concentration:Primary billet sourcing clusters in specific smelter regions expose cylinder barrel producers to energy-price volatility and export quota fluctuations.
- Chrome rod plating limitations:Environmental restrictions on hexavalent chromium processes constrain surface treatment capacity and extend lead times for corrosion-resistant piston rods.
- Electric actuator substitution:Ball-screw and linear motor systems are capturing positioning applications above 500mm stroke lengths where pneumatic precision falls short.
Strategic Opportunities
- Predictive maintenance contracts:Sensor-integrated cylinders with IoT connectivity enable OEMs to monetize recurring service revenue beyond initial hardware sales.
- Collaborative robotics integration:Force-compliant pneumatic actuators are penetrating collaborative automation platforms requiring inherent safety and cost-efficient power density.
- India PLI manufacturing incentives:Production-linked incentive schemes for industrial machinery are attracting cylinder assembly investments to serve domestic automation demand.
Industry Challenges
- Cross-functional automation engineering:System integrators face scarcity of technicians fluent in both pneumatic circuit design and servo control programming.
- Multi-standard certification timelines:Simultaneous pursuit of ISO 15552, ATEX, and China's TS pressure vessel approvals extends product launch schedules by 8-14 months.
- Legacy equipment integration:Retrofitting smart cylinders into existing PLC architectures requires protocol bridging hardware that complicates commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISO Cylinder Market |
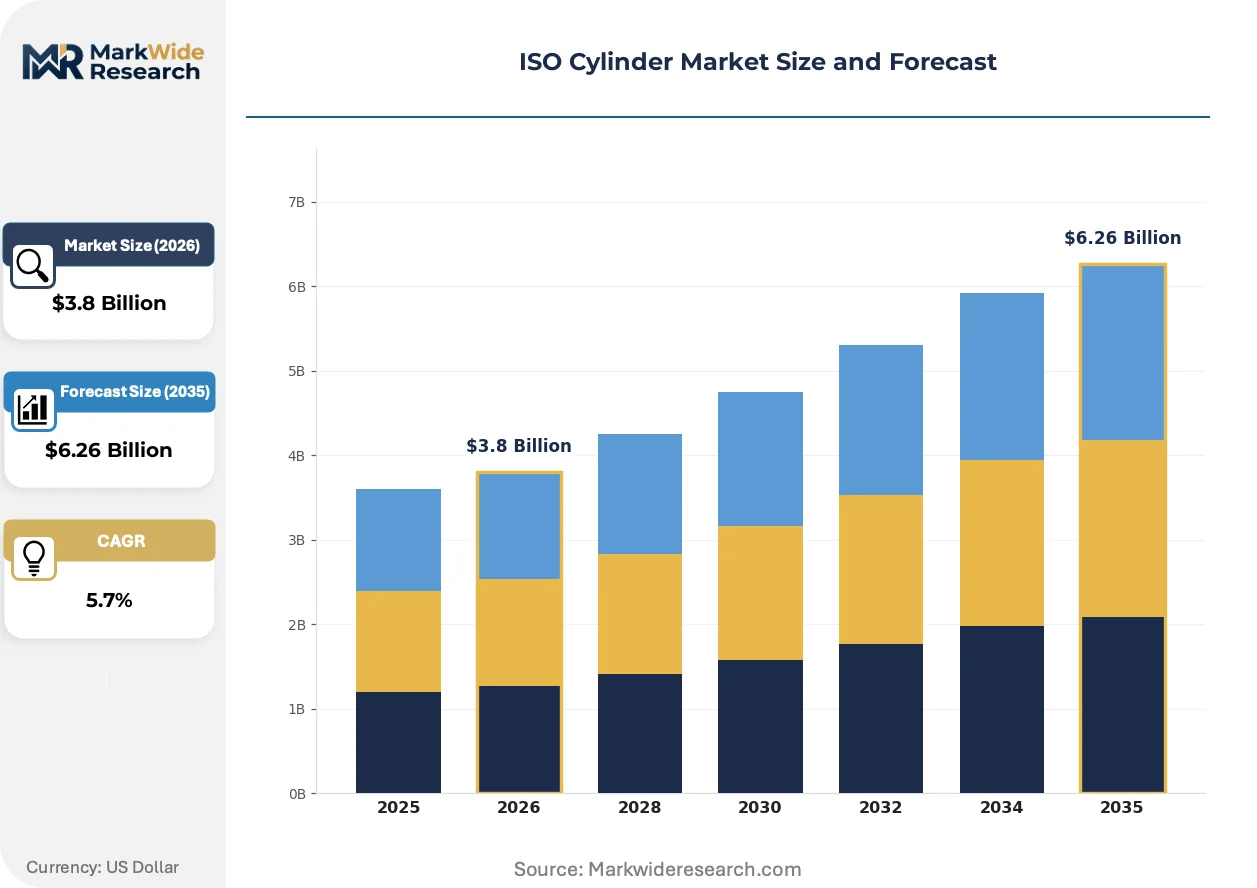
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
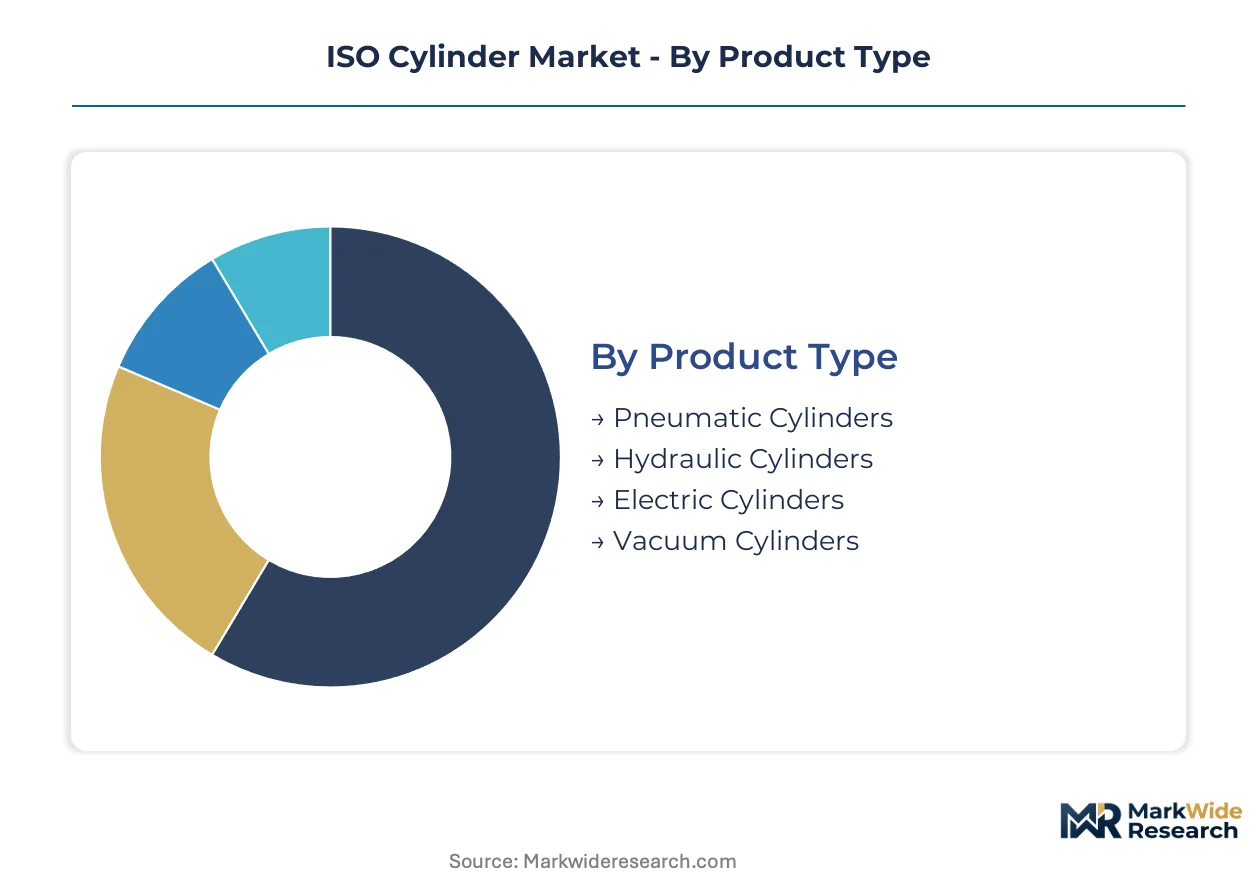
| Segmentation | Product Type: Pneumatic Cylinders, Hydraulic Cylinders, Electric Cylinders, Vacuum Cylinders End User: Manufacturing, Automotive, Aerospace, Packaging Technology: Single-acting, Double-acting, Rodless, Telescopic Application: Material Handling, Robotics, Assembly Line, Automation |
| Companies Covered | SMC Corporation, Festo, Parker Hannifin, IMI, Bosch Rexroth, Eaton, Aventics, Enerpac Tool Group, CKD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISO Cylinder Market Shifts & Advancements
Compressed air systems are undergoing sensorization and edge-computing integration that transforms cylinders from commodity hardware into data-generating nodes within factory digital architectures.
Smart pneumatic cylinders equipped with integrated position sensors and IO-Link connectivity are digitizing maintenance workflows across automotive stamping lines. Tier-1 suppliers in Stuttgart and Detroit are deploying these actuators to capture real-time rod-position data and cycle-count metrics. The technology is digitizing traditional time-based maintenance schedules into condition-triggered interventions that reduce unplanned downtime.
China's SAMR enforcement of updated GB/T pressure vessel testing protocols is tightening import barriers for uncertified pneumatic equipment. The regulations mandate burst-testing documentation and traceable material certificates for cylinders above 50mm bore diameter. European and Japanese manufacturers are responding by establishing localized testing laboratories in Shanghai and Suzhou to accelerate compliance verification.
Buying committees are unbundling aftermarket service contracts from hardware procurement, forcing distributors to compete on spare-parts logistics rather than bundled maintenance packages. Machine builders in Japan's Kansai industrial corridor are separating cylinder purchases from installation support, sourcing actuators through direct channels while retaining system integrators for commissioning. This pattern is most pronounced in high-volume automotive applications where procurement teams negotiate component costs independently from engineering services.
ISO Cylinder Market Segmentation
ISO cylinder procurement patterns diverge sharply across product architectures and end-use environments, with aftermarket service intensity varying by actuator complexity and duty-cycle severity. Understanding these segment boundaries enables suppliers to calibrate inventory depth, field service staffing, and pricing architectures to specific technical requirements.
Product Type:
After-sales service intensity escalates from pneumatic to electric architectures, with predictive maintenance contracts commanding premium attach rates on sensor-integrated electromechanical units.
- Pneumatic Cylinders:Compressed air actuators constructed from aluminum or stainless steel barrels with chrome-plated piston rods, operating at pressures up to 10 bar. Demand concentrates in China's eastern manufacturing belt where factory automation upgrades compress replacement cycles for cost-efficient clean-environment applications.
- Electric Cylinders:Servo-motor-driven linear actuators delivering programmable positioning with sub-millimeter repeatability. Robotics applications in Germany and Japan are capturing expanding margin pools as servo motor cost curves decline and precision requirements intensify.
- Hydraulic Cylinders:High-force fluid power actuators for heavy-duty pressing and lifting operations.
- Vacuum Cylinders:Specialized actuators integrating suction generation for pick-and-place handling in packaging environments.
Pneumatic cylinders hold the largest share; momentum sits with electric cylinders as electromechanical positioning gains share in precision automation.
End User:
Cost tier stratification separates premium-specification aerospace procurement from high-volume automotive contracts, with margin structures inversely correlated to volume scale.
- Automotive:Tier-1 suppliers in Germany, Japan, and the United States are expanding cylinder procurement to support electric vehicle retooling and battery pack positioning systems. REACH compliance and GB standards are tightening material specifications and accelerating hardware replacement cycles across European and Chinese assembly fleets.
- Manufacturing:General industrial automation spanning metal fabrication, food processing, and textile machinery. China's SAMR enforcement of updated GB/T pressure vessel testing protocols is tightening import barriers for uncertified pneumatic equipment above 50mm bore diameter.
- Aerospace:Precision actuation for landing gear, flight control surfaces, and cargo handling systems requiring ATEX and specialized material certifications.
- Packaging:High-speed carton forming, filling, and palletizing operations demanding rapid cycle rates and washdown-compatible construction.
Automotive sustains the highest volume consumption; robotics applications are climbing the fastest as collaborative automation platforms expand actuator integration.
Technology:
Application context dictates actuator configuration selection, with double-acting architectures dominating continuous-motion environments and single-acting units reserved for clamping and ejection tasks.
- Double-acting:Pressure-actuated extension and retraction delivering controlled bidirectional motion. Automotive stamping lines in Stuttgart and Detroit are deploying sensor-integrated variants with IO-Link connectivity to digitize maintenance workflows.
- Rodless:Magnetically coupled or cable-driven designs eliminating exposed piston rods for space-constrained linear motion. Semiconductor handling equipment in Japan's Kansai industrial corridor is adopting these for cleanroom-compatible positioning.
- Single-acting:Spring-return or gravity-dependent actuation for simple clamping and holding operations.
- Telescopic:Nested multi-stage cylinders achieving extended stroke lengths from compact retracted dimensions for dump trucks and material handling lifts.
Double-acting configurations hold the largest share; rodless designs are gaining share fastest in space-constrained precision automation.
Application:
Customer type fragmentation separates OEM machine builders from retrofit integrators, with procurement autonomy expanding as buying committees unbundle hardware from engineering services.
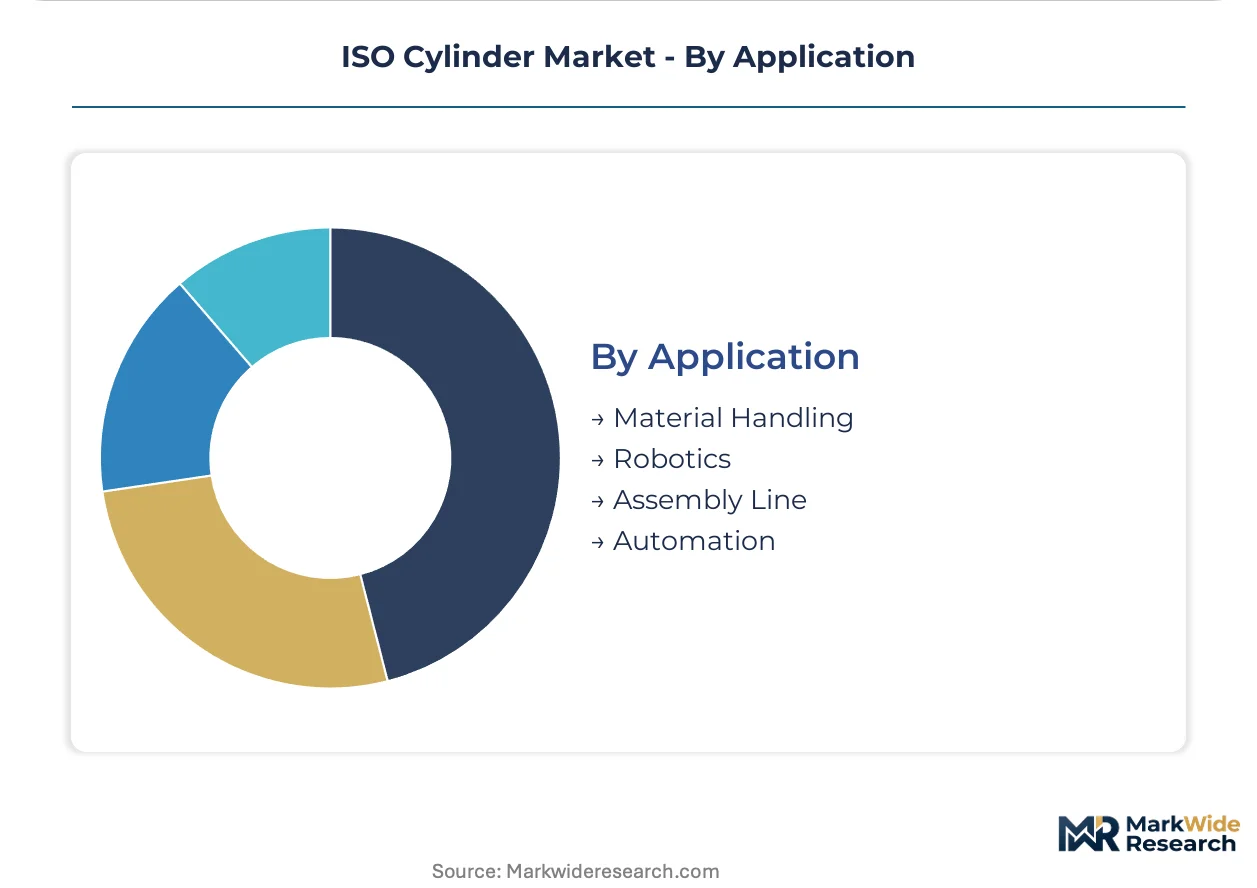
- Assembly Line:Synchronized multi-axis positioning for component insertion, fastening, and quality verification. Machine builders are separating cylinder purchases from installation support, sourcing actuators through direct channels while retaining system integrators for commissioning.
- Robotics:Force-compliant actuation for collaborative platforms requiring inherent safety and cost-efficient power density. Predictive maintenance contracts enable OEMs to monetize recurring service revenue beyond initial hardware sales on sensor-integrated units.
- Material Handling:Lifting, tilting, and conveying operations across warehousing and distribution facilities.
- Automation:General-purpose programmable motion systems spanning test equipment and process machinery.
Assembly line applications hold the largest share; robotics is expanding most quickly through collaborative automation platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ISO cylinders primarily for high-volume factory automation, while Germany and Japan concentrate procurement on precision electromechanical systems for automotive and robotics integration. The United States splits demand between hydraulic infrastructure maintenance and electric actuator adoption in advanced manufacturing.
China
SAMR enforcement of updated GB/T pressure vessel testing protocols is accelerating replacement cycles for pneumatic equipment above 50mm bore diameter. The country's dual carbon goals are compressing energy-efficiency requirements for compressed air systems in industrial facilities. Factory automation upgrades across the Yangtze River Delta are outpacing other manufacturing clusters, with Suzhou and Shanghai hosting localized testing laboratories for compliance verification.
Germany
ECHA restrictions on chrome plating and seal elastomers are phasing legacy cylinder inventory from European industrial fleets. REACH compliance mandates are tightening material specifications for automotive Tier-1 suppliers retooling for electric vehicle production. Stuttgart's automotive stamping lines are deploying sensor-integrated actuators with IO-Link connectivity to digitize maintenance workflows.
Japan
METI industrial automation incentives are pulling demand toward precision electromechanical cylinders as servo motor costs decline. JIS standards interoperability requirements are shaping procurement specifications for collaborative robotics platforms. The Kansai industrial corridor is separating cylinder purchases from installation support, with Osaka-based machine builders sourcing actuators through direct channels.
United States
EPA emissions standards affecting pneumatic compressor efficiency are influencing cylinder system specifications in heavy manufacturing. OSHA safety protocols for collaborative automation are driving force-compliant actuator adoption in automotive assembly. Detroit's battery pack positioning systems are expanding procurement for electric vehicle retooling alongside traditional hydraulic infrastructure maintenance.
India
PLI scheme incentives for industrial machinery are attracting cylinder assembly investments to serve domestic automation demand. BIS certification requirements for pressure equipment are creating compliance barriers for non-certified imports. Maharashtra and Gujarat manufacturing belts are consolidating factory automation upgrades faster than other industrial states.
ISO Cylinder Market Competitive Landscape
Capability concentration sits with precision electromechanical specialists; scale advantage sits with pneumatic volume manufacturers serving high-turnover replacement markets. The vendor base organizes around three strategic archetypes: Japanese precision conglomerates with integrated motion control portfolios, European engineering groups bundling cylinders with servo systems, and North American distribution-heavy suppliers anchoring hydraulic aftermarket service. Dominant competitive moves include backward integration into aluminum billet sourcing and predictive maintenance contract attach-rate expansion.
Among Japanese manufacturers, SMC Corporation and CKD Corporation occupy positions within the precision pneumatic tier, leveraging domestic manufacturing bases to supply high-repeatability actuators across Asian automation clusters. Festo exemplifies the European engineering archetype, sitting within the integrated systems tier where motion control platforms bundle ISO cylinders with linear guides and servo drives. These three anchors represent distinct geographic and technical positioning strategies without overlapping core competence claims.
| Leading Market Players |
|---|
| SMC Corporation |
| Festo |
| Parker Hannifin |
| IMI |
| Bosch Rexroth |
| Eaton |
| Aventics |
| Enerpac Tool Group |
| CKD Corporation |
| Others |
Supply & Pricing Matrix
Primary aluminum billet sourcing clusters in Chinese smelter regions and Japanese specialty alloy foundries concentrate upstream margin capture, forcing cylinder barrel producers to absorb energy-price volatility while downstream pricing power pools with predictive maintenance-integrated OEMs. This upstream-downstream tension reshapes how procurement committees evaluate total cost of ownership against unit price.
Pricing Analysis
Long-term offtake agreements dominate high-volume automotive contracts, while spot procurement persists for replacement parts and project-based systems integration. Three-tier pricing structure across premium sensor-integrated, standard pneumatic, and economy non-certified levels separates ATEX-compliant aerospace units from uncertified industrial commodities. Cost compression in economy tiers intensifies because Chinese domestic manufacturers expand capacity. Tier-1 automotive buyers exhibit lowest price sensitivity; small machine builders in India's emerging manufacturing belt show highest.
Supply Chain Analysis
Export-control regimes limiting precision servo motor and linear encoder flows from Japan and Germany constrain electric cylinder assembly capacity in non-aligned manufacturing zones. Barrel production draws from aluminum smelters in China, specialty steel mills in Germany, and stainless foundries in Japan. Single-source vulnerability concentrates in chrome-plated piston rod surface treatment, where environmental restrictions on hexavalent chromium processes have shuttered European plating capacity. Distribution runs through authorized distributor networks for pneumatics and direct OEM channels for electromechanical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as factory automation upgrades across China's eastern manufacturing belt and India's PLI-supported industrial corridors accelerate replacement demand beyond historical maintenance schedules.
For Market Incumbents: Entrench predictive maintenance contract attach rates on sensor-integrated units to lock recurring revenue against electric actuator substitution. Deepen backward integration into aluminum billet sourcing to buffer energy-price volatility. Prioritize GB/T certification investments in localized Shanghai testing laboratories to defend position against REACH-compliant European imports.
For New Entrants and Emerging Players: Build out rodless cylinder assembly capacity targeting Japan's Kansai semiconductor handling equipment sector, where space-constrained cleanroom demand outpaces incumbent supply. Target India's Maharashtra and Gujarat manufacturing belts with BIS-certified pneumatic units priced below Japanese import parity. Pursue direct channel partnerships with unbundled procurement committees separating hardware from engineering services.
For Investors and Strategic Acquirers: Capital is best deployed toward precision electromechanical specialists with captive servo motor supply agreements and collaborative robotics integration capabilities. Long-term viability hinges on defensible positioning above 500mm stroke lengths where pneumatic precision falls short. Watch for inflection when China's SAMR tightens GB standards on bore diameters below current thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contract Expansion | Sensor-integrated cylinders with IO-Link connectivity enable OEMs to capture recurring service revenue from Stuttgart automotive stamping lines. |
| Backward Integration into Aluminum Billet | Captive supply of barrel raw materials buffers margin compression from energy-price volatility in Chinese smelter regions. |
| Localized GB/T Certification Laboratories | Shanghai and Suzhou testing facilities accelerate compliance verification for cylinders above 50mm bore diameter under SAMR protocols. |
| Rodless Cylinder Capacity Addition | Magnetically coupled designs address space-constrained positioning demand from Japan's Kansai semiconductor handling equipment sector. |
| Direct Channel Partnership Development | Unbundled procurement patterns in high-volume automotive applications favor component suppliers bypassing traditional distributor markups. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at automotive Tier-1 suppliers, maintenance directors at Chinese manufacturing facilities, OEM procurement teams in Germany and Japan, aftermarket service heads at North American distributors, and technical R&D directors at pneumatic component manufacturers. Secondary validation drew from SAMR GB standard filings, ECHA REACH restriction updates, EPA emissions compliance records, customs trade data for aluminum alloy and chrome rod imports, and SEC 10-K disclosures from listed industrial equipment suppliers. Bottom-up unit demand estimates were triangulated against top-down market value reconstruction.
Calibration anchored volume and value outputs across the analysis window to segment-level growth trajectories, with pneumatic, electric, and hydraulic cylinder architectures modeled separately alongside double-acting, rodless, single-acting, and telescopic technology configurations. CAGRs were derived from regression analysis of replacement cycle compression rates, automation capital expenditure trends, and regulatory-driven hardware obsolescence patterns. Industry-specific forecast inputs included servo motor cost curve trajectories and chrome plating capacity constraints under environmental restrictions.
Stress conditions across aluminum alloy price volatility, REACH material phase-out timelines, and electric actuator substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about factory automation adoption curves and regulatory enforcement intensity. Material shifts in China's dual carbon policy implementation or ECHA restrictions on additional seal elastomers would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Internet of Things Testing Market
Others
Fluid Bed Systems Market
Others
Nanomedicine for Drug Delivery Market
Others
Nutricosmetics Market
Others
Spain Automotive LED Lighting Market
Others
Gesture Recognition for Smart TV Market
Others
LAMEA Astrology Market
Others
Photo Booth/Kiosk Market
Others
Connected Wearable Patches Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Radiation Detection Monitoring and Safety Market
Others
Global Pumpkin Candles Market
Others
Liposomes Market
Others
Asia-Pacific Legal Services Market
Others
Architectural Fabrics Market
Others
Ambient Assisted Living and Smart Home Market