
 Global Cryogenic Tanks Market | 2026-2036
Global Cryogenic Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cryogenic Tanks Market Foresight
Aftermarket service revenue is rewriting value capture in the cryogenic tanks industry. Chart Industries leverages its integrated repair and refurbishment network across North America and Europe to sustain recurring income streams. Linde plc anchors its position through captive maintenance contracts tied to long-term industrial gas supply agreements. INOX India competes aggressively on localized field service density across South Asian manufacturing corridors.
Cryogenic tanks are double-walled pressure vessels designed to store liquefied gases below minus 150 degrees Celsius, typically constructed from austenitic stainless steel or aluminum alloys with multi-layer insulation systems that minimize boil-off losses. Vacuum insulated tanks dominate high-value applications where thermal performance directly determines operating economics, while perlite-insulated stationary tanks occupy the bulk infrastructure segment for LNG peak-shaving facilities. Transportable tanks and ISO tanks represent the fastest-expanding category as modular liquefaction and regasification projects proliferate.
The US DOT and Transport Canada enforce stringent pressure vessel codes through 49 CFR and CSA B51 standards that govern tank design, fabrication, and periodic inspection intervals. Ecodesign requirements under the EU F-Gas Regulation and CE marking under the Pressure Equipment Directive shape product certification pathways for European market access. Stakeholders must monitor evolving hydrogen storage standards from ISO TC 197 and national hydrogen strategies in Germany, Japan, and South Korea that will redefine tank material specifications and insulation performance thresholds.
Market Dynamics
The maritime sector's pivot to LNG bunkering is compressing tank procurement cycles as port operators race to install shoreside storage ahead of IMO 2020 enforcement deadlines and EU F-Gas Regulation phase-down mandates.
Growth Catalysts
- IMO 2020 Sulfur Caps:Vessel operators in Rotterdam, Singapore, and Houston are retrofitting engines to run on LNG, requiring cryogenic bunker tanks at terminal facilities.
- German Hydrogen Strategy:National targets for hydrogen import terminals are accelerating demand for large-scale liquid hydrogen storage with specialized insulation systems.
- Aluminum-lithium Alloys:Advanced metallurgy is reducing tank weight by fifteen to twenty percent for transportable applications, enabling longer-haul LNG trucking routes.
Market Restraints
- Nickel Price Volatility:Austenitic stainless steel feedstock costs fluctuate with Indonesian and Philippine mining output, squeezing fabrication margins.
- South Korean Supply Concentration:Three domestic fabricators control over sixty percent of LNG carrier cargo tank production, creating bottleneck risk for new vessel orders.
- Hydrogen Embrittlement:Existing carbon steel infrastructure cannot handle liquid hydrogen without material replacement, limiting retrofit economics.
Strategic Opportunities
- India LNG Import Buildout:Dahej and Kochi terminal expansions require additional peak-shaving storage, opening procurement windows for modular tank systems.
- ISO Tank Leasing Pools:Asset-light operators are aggregating small-scale LNG delivery capacity through shared container fleets rather than dedicated vessel ownership.
- EU F-Gas Phase-Down:Refrigerant restrictions are pushing cold chain operators toward liquid nitrogen backup systems, creating auxiliary tank demand.
Industry Challenges
- Welding Certification Backlogs:Qualified ASME Section IX welders for cryogenic service command twelve-week lead times, delaying fabrication schedules.
- Multi-jurisdiction Approval:Tanks destined for cross-border rail must satisfy US DOT 49 CFR, Transport Canada CSA B51, and RID regulations simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cryogenic Tanks Market |
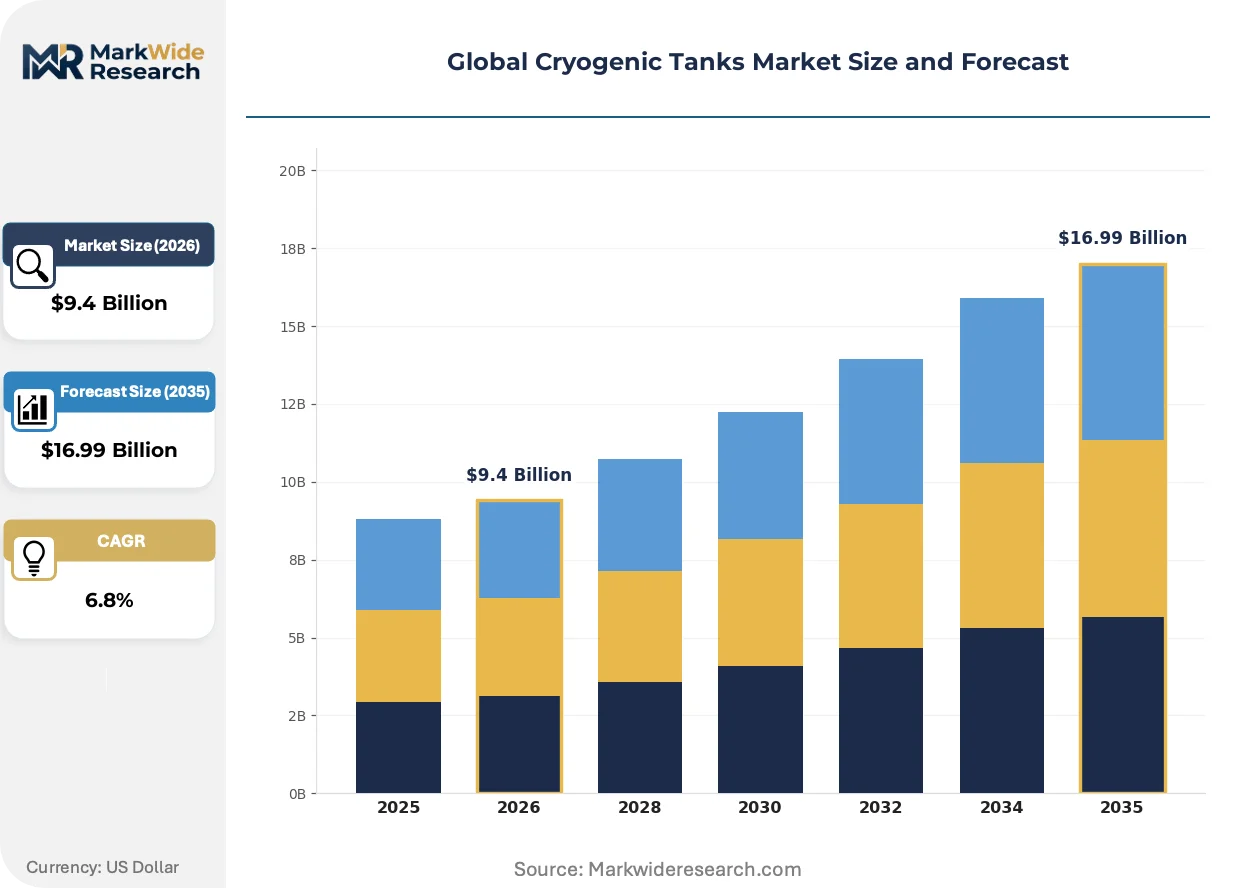
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Tanks, Transportable Tanks, ISO Tanks, Vacuum Insulated Tanks Technology: Vacuum Insulation, Perlite Insulation, Foam Insulation, Aerogel Insulation Application: LNG Storage, Liquid Oxygen Storage, Liquid Nitrogen Storage, Liquid Argon Storage End User: Oil & Gas Producers, Industrial Gas Suppliers, Aerospace Manufacturers, Food & Beverage Processors |
| Companies Covered | Chart Industries, Linde plc, INOX India, Cryofab, FIBA Technologies, Wessington Cryogenics, Air Products, Cryolor, SURETANK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cryogenic Tanks Market Shifts & Advancements
Material science breakthroughs and regulatory convergence are rewriting tank design specifications, with composite insulation systems and hydrogen-ready certifications becoming baseline requirements for new orders.
Multi-layer vacuum insulation is hybridizing with aerogel interlayers to achieve thermal performance below 0.1% daily boil-off for liquid hydrogen storage. Japanese hydrogen refueling station operators are specifying these systems for 10,000-hour maintenance intervals. The technology is hybridizing stationary tank economics with transportable tank mobility, collapsing the traditional performance gap between permanent infrastructure and mobile assets.
The EU F-Gas Regulation's 2030 phase-down targets are forcing cold storage operators to replace fluorinated refrigerants with liquid nitrogen systems. Industrial gas suppliers are bundling tank leases with nitrogen supply contracts to lock in decade-long revenue streams. Food processing clusters in northern Italy and the Netherlands are converting fastest, driven by supermarket chain sustainability mandates.
After-sales service unbundling is separating tank ownership from maintenance liability. Chemical producers in the US Gulf Coast are signing outcome-based contracts where vendors guarantee thermal performance rather than equipment uptime. This shifts capital deployment toward operating expenditure models, compressing initial procurement values while extending vendor revenue horizons through predictive monitoring subscriptions.
Global Cryogenic Tanks Market Segmentation
Cryogenic tank procurement cycles vary dramatically by segment, with transportable assets turning over in three to five years while stationary infrastructure depreciates across two decades. Understanding these velocity differentials helps suppliers align fabrication capacity with actual replacement demand rather than headline installation figures.
Product Type:
Replacement cycles stretch from months for leased ISO containers to decades for buried LNG peak-shaving tanks, creating fundamentally different revenue recognition patterns for fabricators.
- Stationary Tanks:Permanent installations at LNG import terminals and industrial gas production sites feature perlite-insulated double-wall construction with fifty-year design lives. German hydrogen import terminal projects are specifying liquid hydrogen-compatible variants with specialized stainless steel inner vessels.
- Transportable Tanks:Road-rail intermodal units with aluminum-lithium alloy shells dominate small-scale LNG distribution to off-grid industrial consumers. South Korean manufacturers are extending maximum allowable working pressure ratings to enable longer-haul trucking routes from coastal liquefaction plants.
- ISO Tanks:Standardized twenty-foot and forty-foot container frames enable asset pooling across leasing networks serving fragmented chemical and food processing demand.
- Vacuum Insulated Tanks:Multi-layer superinsulation systems achieve boil-off rates below 0.1 percent daily for liquid hydrogen and high-purity electronic gases.
Stationary tanks anchor the volume base while transportable tanks gain share at the steepest rate.
Technology:
Material cost tiers separate commodity insulation from performance-engineered systems, with aerogel commanding five to eight times perlite pricing per cubic meter.
- Vacuum Insulation:Evacuated multi-layer reflective shields with fiberglass or polyester spacer materials deliver the lowest thermal conductivity for liquid hydrogen and helium storage. Japanese hydrogen refueling station operators are mandating ten-thousand-hour maintenance intervals for these systems.
- Perlite Insulation:Expanded volcanic glass fill dominates bulk LNG storage economics where absolute thermal performance matters less than capital cost minimization.
- Foam Insulation:Polyurethane and polyisocyanurate systems occupy mid-range applications in food freezing and pharmaceutical cold chain logistics.
- Aerogel Insulation:Silica-based nanoporous materials are hybridizing with vacuum layers to collapse the performance gap between stationary and transportable tank categories.
Perlite insulation captures the highest shipment volumes while aerogel hybrid systems expand most quickly in premium hydrogen storage applications.
Application:
End-use thermal requirements dictate insulation specification, with LNG tolerating higher boil-off than electronic-grade liquid argon.
- LNG Storage:Accounts for the majority of installed capacity across marine bunkering terminals, peak-shaving facilities, and vehicle fueling stations. Port operators in Rotterdam and Singapore are racing to install shoreside storage ahead of IMO enforcement deadlines.
- Liquid Oxygen Storage:Medical and steelmaking demand requires aluminum or stainless steel construction with stringent cleanliness protocols.
- Liquid Nitrogen Storage:Food freezing, cryopreservation, and electronics manufacturing drive modular tank demand with faster replacement cycles than industrial gas bulk storage.
- Liquid Argon Storage:Welding shielding and semiconductor crystal pulling require the highest purity maintenance, favoring vacuum-insulated vessel construction.
LNG storage dominates absolute capacity additions while liquid hydrogen storage climbs fastest as national hydrogen strategies activate import terminal construction.
End User:
Procurement sophistication varies from commodity spot purchasing by food processors to integrated service contracts by industrial gas majors.
- Oil & Gas Producers:Integrated majors and national oil companies specify large-diameter storage for LNG liquefaction trains and regasification terminals. US Gulf Coast exporters are contracting for tanks with dual LNG-liquid hydrogen compatibility to preserve optionality.
- Industrial Gas Suppliers:Linde, Air Liquide, and Air Products deploy captive maintenance networks to lock in decade-long service revenue alongside tank sales.
- Aerospace Manufacturers:Rocket propellant storage for launch facilities requires specialized aluminum-lithium construction with extreme reliability margins.
- Food & Beverage Processors:Flash freezing and modified atmosphere packaging drive distributed liquid nitrogen tank demand with shorter asset lives than industrial applications.
Oil and gas producers anchor capital deployment while industrial gas suppliers capture recurring service revenue at the most attractive margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Germany demonstrate the lowest price elasticity, prioritizing certification pedigree and integrated service contracts over procurement cost, while Indian port operators and US Gulf Coast chemical producers exhibit acute sensitivity to capital expenditure compression.
United States
LNG export terminal construction along the Gulf Coast and hydrogen hub designations under the IRA are accelerating demand for dual-compatibility storage systems. The US DOT enforces 49 CFR pressure vessel standards that govern cross-border rail shipments into Canada and Mexico. Houston and Corpus Christi anchor the largest concentration of import-export infrastructure investment.
Germany
The national hydrogen strategy targets ten gigawatts of electrolysis capacity by 2030, requiring liquid hydrogen import terminals at Wilhelmshaven and Brunsbüttel. The EU F-Gas Regulation phase-down mandates are pushing cold chain operators toward liquid nitrogen backup systems. Industrial gas clusters in the Ruhr and Bavaria are converting fastest to maintain supermarket supply chain compliance.
South Korea
Three domestic fabricators dominate LNG carrier cargo tank production, creating supply bottleneck risk for new vessel orders. The MFDS and Korea Gas Corporation coordinate safety standards for bunkering infrastructure at Busan and Ulsan. The Daegu-Gyeongbuk manufacturing corridor is expanding field service density to support regional hydrogen refueling networks.
India
Dahej and Kochi LNG terminal expansions require modular peak-shaving storage systems with shorter deployment timelines than permanent infrastructure. The Petroleum and Natural Gas Regulatory Board oversees city gas distribution mandates that extend cryogenic logistics into secondary cities. Gujarat and Maharashtra industrial corridors are absorbing the majority of new liquid nitrogen capacity for food processing and pharmaceuticals.
Japan
Hydrogen refueling station operators are specifying ten-thousand-hour maintenance intervals for vacuum-insulated systems serving fuel cell vehicle fleets. METI coordinates national hydrogen roadmap implementation with prefectural governments. The Chubu-Nagoya industrial zone is concentrating demand for high-purity electronic gases in semiconductor fabrication facilities.
Global Cryogenic Tanks Market Competitive Landscape
Capability concentration sits with specialized fabricators possessing ASME Section IX welding certification and multi-jurisdiction approval expertise; scale advantage sits with integrated industrial gas majors leveraging captive maintenance networks. The market structures around three tiers: premium specialists commanding certification premiums, mid-scale regional players competing on lead time compression, and asset-light ISO tank lessors aggregating fragmented demand. Dominant competitive moves include backward integration into aluminum-lithium alloy supply and geographic expansion through localized field service density.
Among US-based fabricators, Chart Industries exemplifies the integrated service archetype through its North American and European repair network. Linde plc anchors the industrial gas major tier with decade-long captive maintenance contracts. INOX India occupies a position within the high-growth South Asian specialist segment. These three represent divergent strategic postures: service bundling, long-term supply integration, and regional manufacturing density respectively.
| Leading Market Players |
|---|
| Chart Industries |
| Linde plc |
| INOX India |
| Cryofab |
| FIBA Technologies |
| Wessington Cryogenics |
| Air Products |
| Cryolor |
| SURETANK |
| Others |
Supply & Pricing Matrix
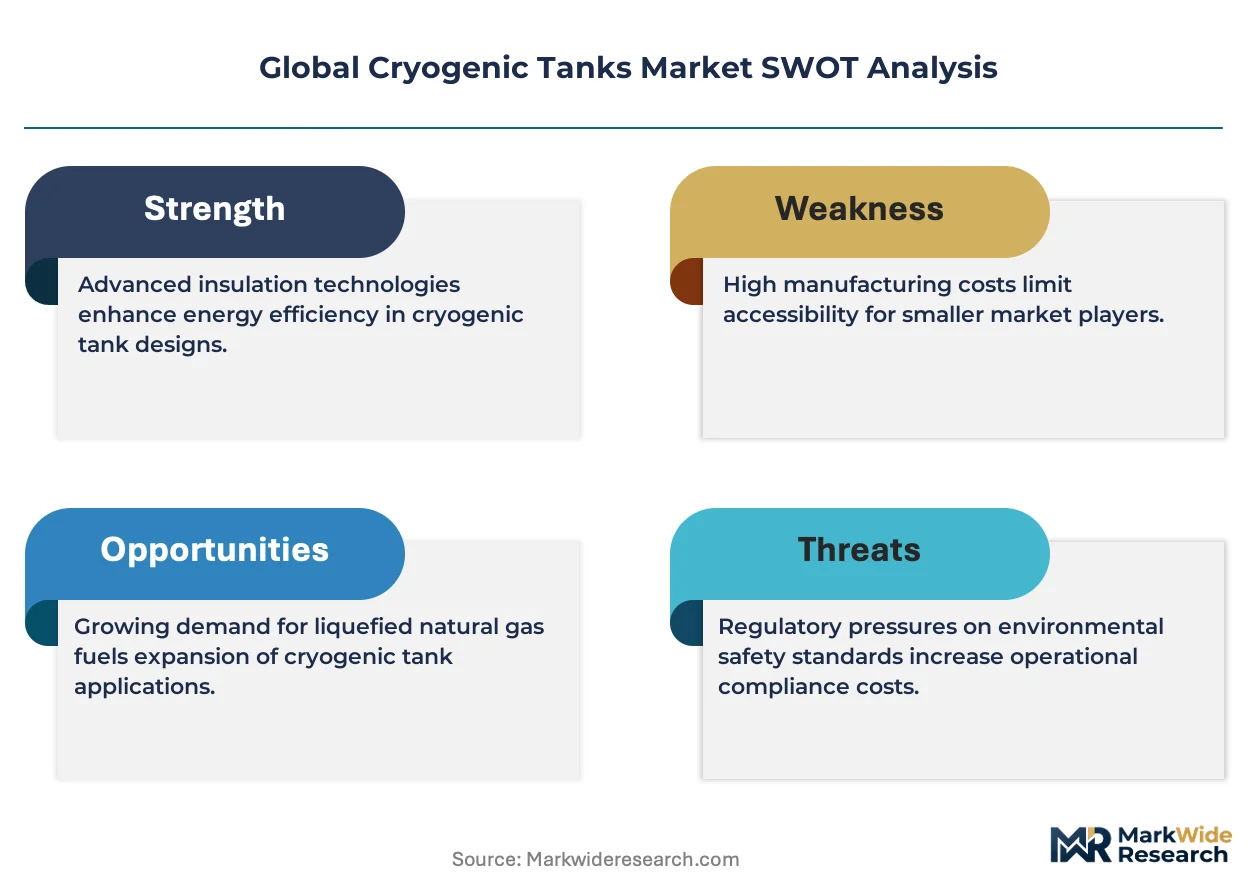
Indonesian and Philippine nickel mining output concentration directly determines where fabrication margin pools accumulate downstream, with austenitic stainless steel feedstock volatility cascading through tank pricing structures to concentrate profitability in captive maintenance networks rather than equipment sales.
Pricing Analysis
After-sales service contracts now drive lifetime value capture, with predictive maintenance subscriptions and thermal performance guarantees commanding premium positioning over standalone equipment sales. Pricing stratifies across certification grade, volume scale, and after-sales bundling, with ASME Section IX-certified fabricators extracting margin premiums from LNG terminal operators. Cost compression in transportable tank tiers is intensifying because aluminum-lithium alloy adoption is democratizing weight-reduction benefits. Food and beverage processors exhibit acute price sensitivity, while German hydrogen import terminal developers prioritize certification pedigree over procurement cost.
Supply Chain Analysis
Upstream nickel ore extraction centers on Indonesia, the Philippines, and Russia, with austenitic stainless steel production anchored in China, Japan, and South Korea. Fabrication draws from aluminum-lithium alloy feedstocks, multi-layer vacuum insulation materials, and perlite fill sources. Single-source vulnerability concentrates in South Korean LNG carrier cargo tank production, where three domestic fabricators control majority capacity. Distribution runs through integrated industrial gas majors with captive maintenance networks, regional specialists competing on lead time compression, and asset-light ISO tank lessors aggregating fragmented chemical demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic tank procurement is shifting toward platform-economics logic as interoperability standards for hydrogen-ready certifications create ecosystem lock-in effects, with vendors bundling equipment, fuel supply, and maintenance into unified service contracts.
For Market Incumbents: Entrench position through backward integration into aluminum-lithium alloy supply and geographic expansion of localized field service density. Threats from emerging hydrogen storage specialists with aerogel hybrid insulation expertise require defensive certification investment in ISO TC 197 compliance. Capacity addition in South Asian manufacturing corridors anchors channel control against regional specialist encroachment.
For New Entrants and Emerging Players: Indian secondary city gas distribution networks represent the most penetrable white-space opportunity, with Dahej and Kochi terminal expansions requiring modular peak-shaving systems on compressed timelines. Liquid nitrogen backup systems for EU F-Gas Regulation compliance offer a second entry vector. A leasing-plus-service bundled go-to-market angle bypasses capital expenditure barriers among price-sensitive food processors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabricators possessing ASME Section IX welding certification but lacking integrated service network scale. Long-term viability hinges on hydrogen infrastructure buildout execution across national strategy timelines. Acquisition targets should demonstrate multi-jurisdiction approval expertise spanning US DOT 49 CFR, Transport Canada CSA B51, and EU Pressure Equipment Directive pathways. The signal to watch is liquid hydrogen import terminal FID momentum in Germany and Japan.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum-Lithium Supply | Secures weight-reduction alloy feedstock for transportable tank production against South Korean concentration. |
| Hydrogen-Ready Certification Investment | Positions fabricators for German and Japanese liquid hydrogen import terminal procurement windows. |
| Localized Field Service Density Expansion | Captures recurring maintenance revenue from industrial gas majors and chemical producers. |
| ISO Tank Leasing Pool Aggregation | Enables asset-light operators to serve fragmented small-scale LNG demand without dedicated vessel ownership. |
| Aerogel Hybrid Insulation Development | Collapses performance gaps between stationary and transportable categories for premium hydrogen storage. |
Research Methodology
Initial hypotheses were tested against primary input from LNG terminal procurement directors, industrial gas supply contract managers, ASME-certified welding supervisors, and aftermarket service heads, then refined through secondary validation against SEC 10-K filings, customs and trade data, national hydrogen strategy documents, and pressure equipment regulatory filings. Bottom-up tank fabrication capacity estimates triangulated with top-down LNG infrastructure investment forecasts.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product type, insulation technology, cryogenic application, and end-user procurement sophistication. CAGRs were derived from installation base turnover velocity differentials and replacement cycle compression in transportable categories. Forecast inputs incorporated IMO 2020 enforcement timelines, EU F-Gas Regulation phase-down mandates, and national hydrogen electrolysis capacity targets without year-specific assumptions.
Practitioners should monitor nickel price volatility, South Korean fabrication bottleneck resolution, and hydrogen storage standard finalization for early signals of forecast revision. Cross-checking against IEA hydrogen project databases and Lloyd's Register vessel order books is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Webinar and Webcast Market
Others
Global Hair Loss Treatment Products Market
Others
Belt Loader Market
Others
North America Automotive LED Lighting Market
Others
Japan Coal Market
Others
Latin America Video Conferencing Hardware Market
Others
Smartphone Gimbal Market
Others
Global Hardware Acceleration Market
Others
Roasted Wheat Market
Others
Solar Animal Repellent Market
Others
France 3D Printing Construction Market
Others
Hydrostatic Testing Market
Others
Sandbags Market
Others
Light Meter Market
Others
Evidence Management Market
Others
North America Compressor Oil Market