
 Content Experience Platforms Market | 2026-2036
Content Experience Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Content Experience Platforms Market Outlook
Subscription-based SaaS financing is reconfiguring competitive entry barriers, allowing mid-market vendors to challenge incumbents without heavy infrastructure spend. Sitecore leverages its hybrid deployment architecture to sustain enterprise loyalty across regulated industries. Contentstack anchors its position through API-first composability that appeals to developer-led procurement teams. Bloomreach competes by embedding commerce search intelligence directly into content workflows, narrowing the gap between discovery and conversion.
Content experience platforms are software systems that orchestrate the creation, management, personalization, and delivery of digital assets across touchpoints through headless architectures, real-time customer data activation, and adaptive rendering engines; they serve the commercial purpose of reducing content fragmentation while accelerating time-to-market for brand experiences. Cloud-based deployments now capture the majority of new bookings as enterprises exit data center obligations, while on-premises solutions retain footholds in banking and healthcare where data residency rules apply strict geographic constraints. Personalization modules within the solution layer command premium pricing because they tie directly to revenue attribution, whereas basic content management functions have commoditized into bundled table stakes.
The EU AI Act, GDPR, and HIPAA shape product roadmaps by mandating explainable personalization logic, consent-aware data handling, and audit trails for automated content decisions. The Federal Trade Commission in the United States has signaled closer scrutiny of dark pattern design in personalized experiences, adding compliance cost to algorithmic recommendation engines. Stakeholders must weigh whether to build governance natively or absorb third-party compliance middleware as regulatory fragmentation deepens across jurisdictions.
Market Dynamics
Enterprise migration from monolithic CMS architectures to API-first composable stacks is fragmenting vendor lock-in patterns and redistributing procurement power toward developer-led evaluation committees. This structural shift compresses implementation timelines while expanding integration surface areas.
Growth Catalysts
- EU AI Act compliance mandates:Automated content personalization engines now require explainable decision logic and audit trails, creating replacement demand for legacy black-box recommendation systems across European enterprise deployments.
- Headless architecture adoption:Developer teams in retail and financial services are decoupling content repositories from presentation layers, enabling simultaneous deployment across mobile apps, kiosks, and emerging spatial computing interfaces.
- Real-time customer data platforms:CDP-CEP integration is compressing activation latency from hours to milliseconds, allowing behavioral triggers to propagate across touchpoints before session abandonment occurs.
Market Restraints
- Specialized talent scarcity:Full-stack engineers proficient in both GraphQL schema design and martech stack orchestration command premium compensation, inflating implementation costs for mid-market adopters.
- Data residency fragmentation:Brazil's LGPD and China's PIPL impose conflicting geographic storage requirements, forcing vendors to maintain redundant infrastructure footprints that erode SaaS margin structures.
- Legacy system entrenchment:Decades-old on-premises content repositories in regulated industries resist API abstraction, requiring costly middleware layers that delay ROI realization.
Strategic Opportunities
- India's digital public infrastructure:The country's Account Aggregator framework and expanding UPI rails create conditions for embedded financial content experiences that bypass traditional banking portal development cycles.
- Generative AI content synthesis:Convergence of large language models with structured content APIs enables dynamic variant generation at scale, reducing manual localization overhead for multinational brand deployments.
- Vertical-specific compliance templates:Pre-configured HIPAA and FDA 21 CFR Part 11 modules for healthcare and life sciences segments command pricing premiums unavailable in horizontal horizontal solutions.
Industry Challenges
- Cross-functional alignment friction:Marketing operations and platform engineering teams operate under conflicting KPIs and sprint cadences, producing scope disputes during implementation phases.
- Third-party cookie deprecation:Identifier instability across Safari, Firefox, and Chrome is degrading attribution precision for personalized content triggers, forcing investment in first-party data infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Content Experience Platforms Market |
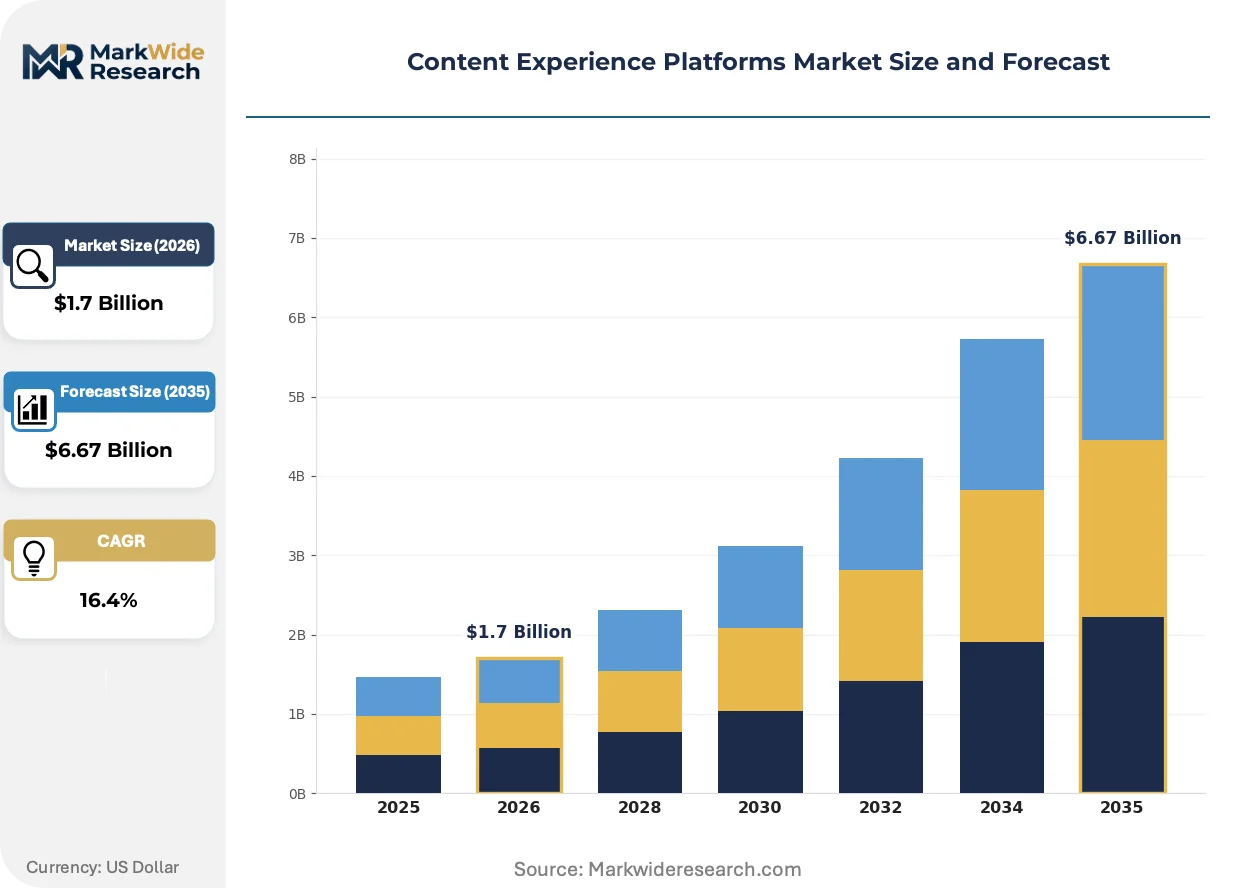
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $6.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Retail, Education, Media, Healthcare Solution: Content Management, Personalization, Analytics, Integrations Industry Vertical: Publishing, E-Commerce, Banking, Travel |
| Companies Covered | Adobe Experience Manager, Sitecore, HubSpot CMS Hub, Bloomreach, Contentstack, CoreMedia, Storyblok, Showpad, Kentico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Content Experience Platforms Market Strategic Shifts
Edge computing deployment is collapsing content delivery latency to sub-50 millisecond thresholds, enabling experiences that respond to physical context rather than historical profiles alone. This infrastructure shift is redrawing competitive boundaries between CDN providers and traditional CEP vendors.
Composable DAM architectures are digitizing asset lifecycle management by treating media files as API-addressable microservices rather than static repository objects. Retailers operating flash-sale models are adopting these structures to automate variant generation across regional storefronts. The compression of creative production cycles is digitizing the traditional agency-client relationship into continuous optimization partnerships.
Germany's BSI IT-Grundschutz certification requirements are mandating formal security assessments for cloud-hosted content platforms processing government data. Federal procurement frameworks now exclude vendors lacking documented penetration testing and encryption key escrow protocols. Public-sector RFPs in Berlin and Munich are explicitly weighting compliance documentation above feature breadth in evaluation matrices.
Enterprise buyers are consolidating vendor relationships through multi-year platform commitments that bundle content management, personalization, and analytics under single contracts. Systems integrators are displacing point-solution specialists as primary implementation partners, capturing margin that previously flowed to boutique agencies. This concentration is most visible in United States Fortune 500 procurement patterns, where procurement teams prioritize vendor financial stability over niche functional superiority.
Content Experience Platforms Market Segmentation
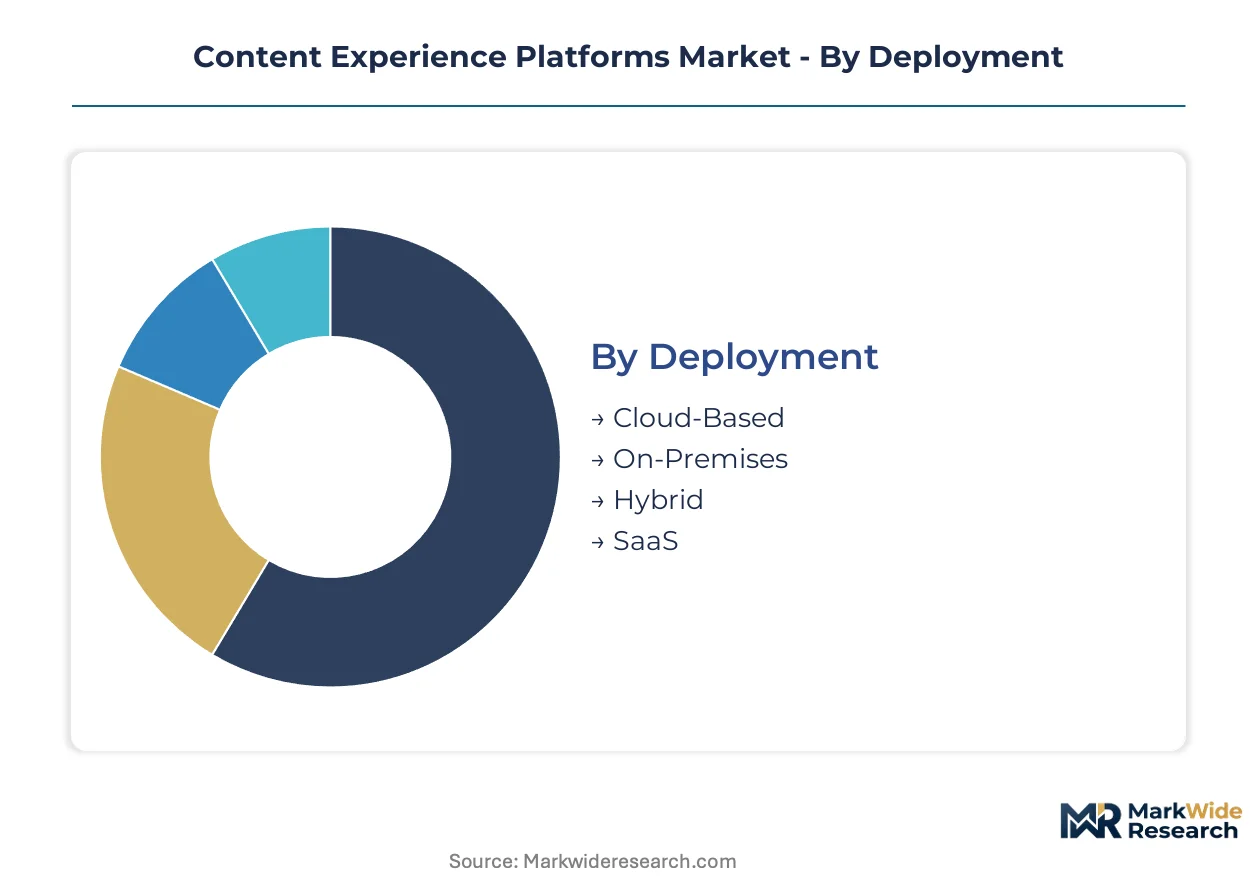
Content experience platforms fragment across four structural dimensions that determine procurement priorities and vendor positioning. Deployment mode dictates infrastructure obligations and compliance posture. End-user concentration shapes feature roadmaps toward sector-specific workflows.
Deployment:
Cost tier determines infrastructure ownership, operational overhead, and regulatory flexibility for enterprise buyers.
- Cloud-Based:Multi-tenant architectures eliminate data center capital expenditure while enabling elastic scaling during traffic spikes. Retailers running seasonal campaigns in the United States concentrate procurement here to avoid capacity planning delays. GDPR and EU AI Act compliance requirements are pushing European enterprises toward EU-sovereign cloud regions with localized encryption key management.
- Hybrid:Split-stack configurations isolate sensitive customer data on-premises while pushing presentation-layer rendering to edge nodes. Banking institutions in Germany and France anchor demand here to satisfy BSI IT-Grundschutz and national financial regulator data residency mandates without sacrificing omnichannel delivery speed.
- On-Premises:Single-tenant installations serve healthcare networks where HIPAA audit trails require physical infrastructure control.
- SaaS:Subscription pricing models compress procurement cycles for mid-market marketing teams seeking predictable operational expenditure.
Cloud-Based deployments command the established base. The steepest expansion runs through Hybrid configurations as regulated industries seek architectural compromise.
End User:
Application context drives divergent requirements for content velocity, personalization depth, and integration complexity.
- Retail:Flash-sale operations and omnichannel inventory synchronization demand millisecond-latency content activation across mobile apps, in-store kiosks, and web storefronts. United States Fortune 500 merchants are consolidating vendor relationships through multi-year platform commitments that bundle personalization engines with commerce search.
- Healthcare:Patient portal content must navigate HIPAA consent management, FDA 21 CFR Part 11 audit trails for promotional materials, and state-level privacy fragmentation. Hospital systems in Texas, California, and New York are replacing legacy CMS installations with platforms embedding native compliance documentation.
- Media:Breaking-news workflows and multi-platform syndication require real-time editorial collaboration tools with broadcast system integration.
- Education:Learning management system interoperability and accessibility compliance (WCAG 2.1) shape procurement evaluations for university IT departments.
Retail anchors current revenue concentration. Healthcare is climbing the fastest as compliance automation becomes a board-level priority.
Solution:
Functional maturity determines margin capture, with advanced modules commanding pricing premiums over commoditized table stakes.
- Personalization:Real-time decision engines activate behavioral triggers across touchpoints before session abandonment occurs. CDP-CEP integration is compressing activation latency from hours to milliseconds in United States and United Kingdom retail deployments. The FTC's scrutiny of dark pattern design is adding compliance engineering cost to algorithmic recommendation development.
- Content Management:Headless repository architectures decouple content storage from presentation layers, enabling simultaneous deployment across emerging spatial computing interfaces and traditional web channels. Developer-led procurement teams in financial services prioritize GraphQL schema flexibility and API versioning stability.
- Analytics:Attribution modeling connects content exposure to revenue outcomes, justifying platform investment to CFO-led evaluation committees.
- Integrations:Pre-built connectors to commerce, CRM, and marketing automation stacks compress implementation timelines for mid-market adopters facing specialized talent scarcity.
Content Management retains the largest installed base. Personalization is gaining share fastest as revenue attribution capabilities become procurement prerequisites.
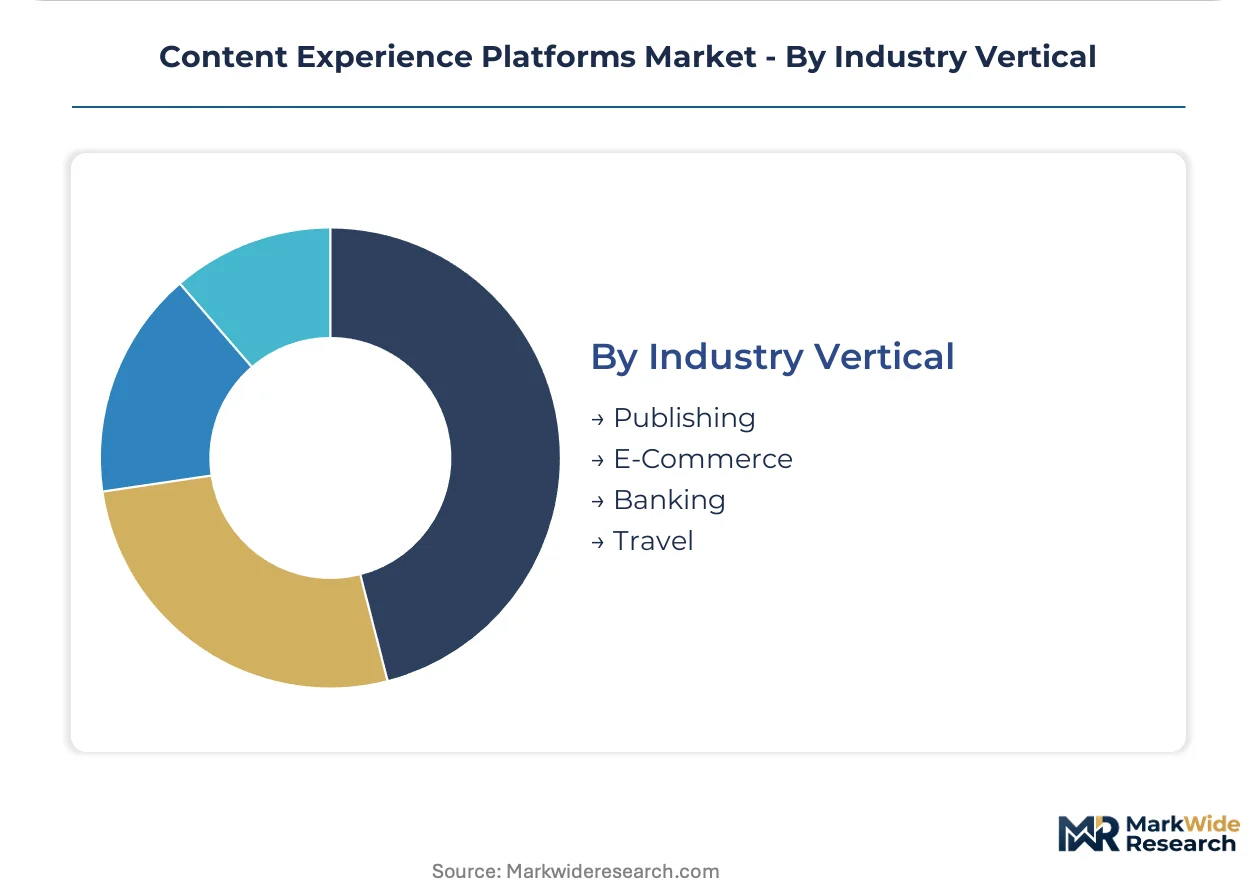
Industry Vertical:
Customer type determines compliance burden, content velocity requirements, and competitive differentiation strategies.
- E-Commerce:Product content syndication across marketplace channels requires automated variant generation and regional localization at scale. India's expanding UPI rails and Account Aggregator framework are creating conditions for embedded financial content experiences that bypass traditional banking portal development.
- Banking:Regulatory documentation, rate disclosure accuracy, and multi-jurisdiction consent management dominate procurement criteria. Brazil's LGPD and China's PIPL impose conflicting geographic storage requirements that favor vendors with redundant infrastructure footprints.
- Publishing:Subscription conversion optimization and paywall personalization drive platform selection for digital-native and legacy media houses.
- Travel:Dynamic packaging content and real-time inventory availability require integration with global distribution systems and property management platforms.
E-Commerce holds the dominant position. Banking is expanding most quickly as compliance automation becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balance in digital services tilts toward net importers in emerging economies while established SaaS hubs generate surplus. Platform procurement flows concentrate where enterprise marketing spend and regulatory complexity intersect.
United States
Fortune 500 content operations in New York and San Francisco drive platform procurement through multi-year vendor consolidations. The FTC scrutinizes dark pattern design in personalized experiences, adding compliance engineering cost to algorithmic recommendation development. Texas and California hospital systems replace legacy CMS installations with platforms embedding native HIPAA documentation.
Germany
Banking institutions in Frankfurt and Munich anchor hybrid deployment demand to satisfy BSI IT-Grundschutz and BaFin data residency mandates. Federal procurement frameworks exclude vendors lacking documented penetration testing and encryption key escrow protocols. Berlin public-sector RFPs weight compliance documentation above feature breadth in evaluation matrices.
United Kingdom
Retail and financial services in London prioritize CDP-CEP integration compressing activation latency from hours to milliseconds. The Information Commissioner's Office enforces GDPR consent-aware data handling requirements for automated content decisions. Manchester and Birmingham marketing teams expand API-first composable stack evaluations to reduce implementation timelines.
India
The Account Aggregator framework and expanding UPI rails create conditions for embedded financial content experiences in Mumbai and Bangalore. RBI guidelines on data localization influence vendor selection for banking portal modernization. Hyderabad and Pune developer-led procurement teams prioritize GraphQL schema flexibility in platform assessments.
Japan
Enterprise buyers in Tokyo consolidate vendor relationships through bundled content management, personalization, and analytics contracts. METI guidelines on digital transformation accelerate migration from monolithic CMS architectures to headless repositories. Osaka manufacturing conglomerates evaluate platforms for simultaneous deployment across emerging spatial computing interfaces.
Content Experience Platforms Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the API and microservices layer. The vendor base fragments across three tiers: enterprise suites with hybrid deployment capabilities, mid-market SaaS providers with subscription financing, and developer-centric headless specialists. Strategic archetypes include compliance-forward incumbents serving regulated industries, API-first challengers capturing developer-led procurement, and commerce-embedded platforms narrowing discovery-to-conversion gaps. Competitive moves concentrate on multi-year enterprise commitments bundling adjacent capabilities and systems integrator partnerships displacing boutique agency relationships.
Within the enterprise suite tier, Adobe Experience Manager and Sitecore occupy positions anchored to hybrid deployment architectures sustaining loyalty across regulated verticals. Contentstack exemplifies the API-first challenger archetype appealing to developer-led evaluation committees through composable infrastructure. Bloomreach sits within the commerce-embedded segment, representing platforms that integrate search intelligence directly into content workflows.
| Leading Market Players |
|---|
| Adobe Experience Manager |
| Sitecore |
| HubSpot CMS Hub |
| Bloomreach |
| Contentstack |
| CoreMedia |
| Storyblok |
| Showpad |
| Kentico |
| Others |
Value Chain & Pricing Dynamics
San Francisco Bay Area hyperscaler infrastructure anchors capacity dynamics for cloud-native content experience platforms, concentrating compute and storage provisioning power among AWS, Azure, and Google Cloud regions that downstream SaaS vendors must negotiate. This geographic supply concentration translates directly into pricing leverage for enterprise buyers committing to multi-year platform contracts, while mid-market adopters face margin compression from elastic scaling premiums during traffic spikes.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS financing as the dominant pricing model, with three-tier pricing structure across premium, standard, and economy levels differentiating by personalization engine sophistication and compliance certification tier. Price differentiation stems from GDPR/EU AI Act audit documentation and real-time CDP integration depth. Pricing pressure intensifies as generative AI content synthesis commoditizes basic variant generation, forcing vendors to bundle premium analytics for margin defense. Mid-market retail marketing teams exhibit highest price sensitivity, while regulated healthcare and banking buyers prioritize compliance documentation over cost.
Supply Chain Analysis
Contract manufacturing concentration rests with hyperscale cloud providers—AWS, Microsoft Azure, Google Cloud—holding global data center capacity, supplemented by regional sovereign cloud operators in Germany and India for data residency compliance. Geographic supply concentration centers on United States, Ireland, and Singapore for primary compute infrastructure, with emerging regions in India and Brazil expanding. Raw material dependencies include silicon for edge computing hardware, lithium-ion battery systems for backup power, and specialized cooling equipment. Single-source vulnerability from concentrated hyperscaler dominance poses structural risk. Distribution runs through direct enterprise sales teams and systems integrator partnerships displacing boutique agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against generative AI-native challengers embedding large language models directly into content workflows, bypassing traditional repository architectures entirely. Platform consolidation and compliance automation represent critical bulwarks against this displacement threat.
For Market Incumbents: Entrench hybrid deployment capabilities as the primary defensive moat, doubling down on BSI IT-Grundschutz and HIPAA pre-certification investments that AI-native entrants cannot replicate quickly. Acquire specialized compliance middleware vendors to close governance gaps against the EU AI Act audit trail requirements. Vertical integration into edge computing infrastructure reduces hyperscaler dependency and protects margin from elastic pricing volatility. For New Entrants and Emerging Players: Establish a beachhead in India's Account Aggregator-embedded financial content segment, where UPI rails and regulatory data localization create greenfield demand unaddressed by Western incumbents. Target mid-market German manufacturing exporters seeking BSI-compliant headless architectures without enterprise-suite complexity. Lead with developer-centric GraphQL tooling and localized language support as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors API-first composable specialists with demonstrated CDP-CEP integration traction over monolithic suite vendors facing architectural obsolescence. Long-term viability hinges on first-party data infrastructure ownership as third-party cookie deprecation accelerates. Acquisition target archetype: vertical-specific compliance template developers in healthcare and banking. The signal to watch is FTC enforcement velocity against dark pattern design, which would compress algorithmic personalization valuations and favor explainable AI investments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | CDP-CEP convergence compresses activation latency from hours to milliseconds for retail. |
| Compliance Module Development | Pre-configured HIPAA and FDA 21 CFR Part 11 templates command healthcare pricing premiums. |
| Strategic Partnership | Systems integrator alliances displace boutique agencies in Fortune 500 procurement cycles. |
| Geographic Expansion | EU-sovereign cloud regions with localized encryption satisfy GDPR and EU AI Act mandates. |
| Acquisition of Specialist Firm | Edge computing CDN providers redraw competitive boundaries against traditional CEP vendors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with CTOs, marketing operations directors, platform engineering leads, and systems integrator partners, validated against secondary sources including SEC filings, hyperscaler capex disclosures, and EU regulatory documentation databases. Bottom-up sizing triangulated vendor-reported deployment metrics with top-down macroeconomic calibration across enterprise software spend patterns.
Calibration applied across the analysis window employed multi-dimensional segmentation modeling deployment mode, end-user vertical, solution layer maturity, and regional regulatory cluster complexity. CAGRs derived from historical growth trajectory analysis adjusted for technology substitution effects and compliance-driven replacement cycles. Forecast inputs incorporated real-time CDP integration adoption curves and generative AI content synthesis penetration rates by enterprise size tier.
Macroeconomic conditions sit as an overlay; deviation in enterprise IT budget cycles and cloud infrastructure pricing would shift the trajectory materially. Forecasts reflect documented assumptions about regulatory enforcement timing and technology adoption S-curves. Cross-checking against hyperscaler revenue disclosure trends and systems integrator backlog reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
AI in Home Automation Market
Others
Nanomedicine for Drug Delivery Market
Others
Augmented Reality in BFSI Market
Others
Fire Sprinkler Market
Others
Calendered Polyvinyl Chloride Flexible Films Market
Others
Banknote Printing Machine Market
Others
South Asia Geosynthetics Market
Others
Dried Egg Market
Others
Semiconductor Gas Filters Market
Others
Nyerereite Market
Others
Global Supply Chain Risk Management Software Market
Others
Fresh Durian Market
Others
Global Pumpkin Candles Market
Others
Retail Digital Signage Market
Others
Enterprise Video Content Management Market
Others
Gas Radiators Market