
 East Asia Renewable Energy Market | 2026-2036
East Asia Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
East Asia Renewable Energy Market Foresight
China's dual carbon goals is broadening the addressable market for grid-scale clean power across East Asia. State Power Investment Corporation leverages its nuclear-to-renewables diversification to anchor project pipelines in multiple jurisdictions. Vena Energy competes through offshore wind specialization in Taiwan Strait developments. Gulf Energy Development PCL controls distributed solar deployment across Thai industrial estates.
East Asia renewable energy encompasses electricity generation systems that harness solar irradiance, wind kinetic energy, biomass combustion, or geothermal heat through photovoltaic cells, horizontal-axis turbines, anaerobic digesters, or binary-cycle plants to displace fossil thermal output. Photovoltaic installations dominate capacity additions due to module cost declines and rooftop penetration programs. Wind turbine deployment accelerates fastest in shallow-water zones where fixed-bottom foundations achieve capacity factors above forty percent. Bioenergy systems retain stable margins where agricultural residues provide captive fuel streams to industrial end users.
China's MEE enforces emissions intensity benchmarks that compel provincial grid operators to prioritize renewable dispatch. Japan's METI administers feed-in tariff schedules that determine investor returns for solar and offshore wind assets. Vietnam's CEA implements power purchase agreement frameworks that shape market access for independent producers. Stakeholders must monitor tariff renegotiation timelines and localization requirements that determine project economics.
Market Dynamics
China's dual carbon goals and Japan's feed-in tariff reforms are compressing project development timelines across East Asia. Provincial grid operators now face binding emissions intensity benchmarks that force renewable dispatch prioritization regardless of spot pricing.
Growth Catalysts
- Feed-in tariff reforms:Japan's METI schedules guarantee investor returns for offshore wind assets. Developers accelerate Taiwan Strait fixed-bottom projects.
- Industrial conglomerate procurement:State-owned enterprises in China anchor multi-gigawatt pipelines. Utility-scale offtake agreements de-risk capital deployment.
- Shallow-water wind zones:Vietnam's Mekong Delta corridors achieve capacity factors above forty percent. Fixed-bottom foundations undercut floating alternatives on levelized cost.
Market Restraints
- Polysilicon supply concentration:Xinjiang-based refining dominates photovoltaic feedstock. Module manufacturers face forced labor compliance scrutiny.
- Grid interconnection queues:Coastal province substations lack transmission headroom. Project sponsors absorb years of delay in dispatch authorization.
- Lithium-ion substitution ceiling:Four-hour battery duration caps renewable firming economics. Long-duration storage chemistries remain pre-commercial.
Strategic Opportunities
- Philippine archipelago distributed solar:Island grids lack baseload thermal alternatives. Industrial estates seek captive generation to offset diesel reliance.
- Green hydrogen offtake:Steel and ammonia producers in South Korea pilot electrolyzer integration. Renewable curtailment creates feedstock cost advantage.
- Agrivoltaic convergence:Taiwan's agricultural land constraints drive dual-use permitting. Elevated panel arrays preserve rice cultivation underneath.
Industry Challenges
- Offshore construction vessel scarcity:Heavy-lift jack-up fleets concentrate in European North Sea. East Asian turbine installation windows compress to seasonal weather gaps.
- Power purchase agreement renegotiation:Vietnam's CEA retroactively adjusts tariff terms for operational assets. Investor confidence in regulatory stability erodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Asia Renewable Energy Market |
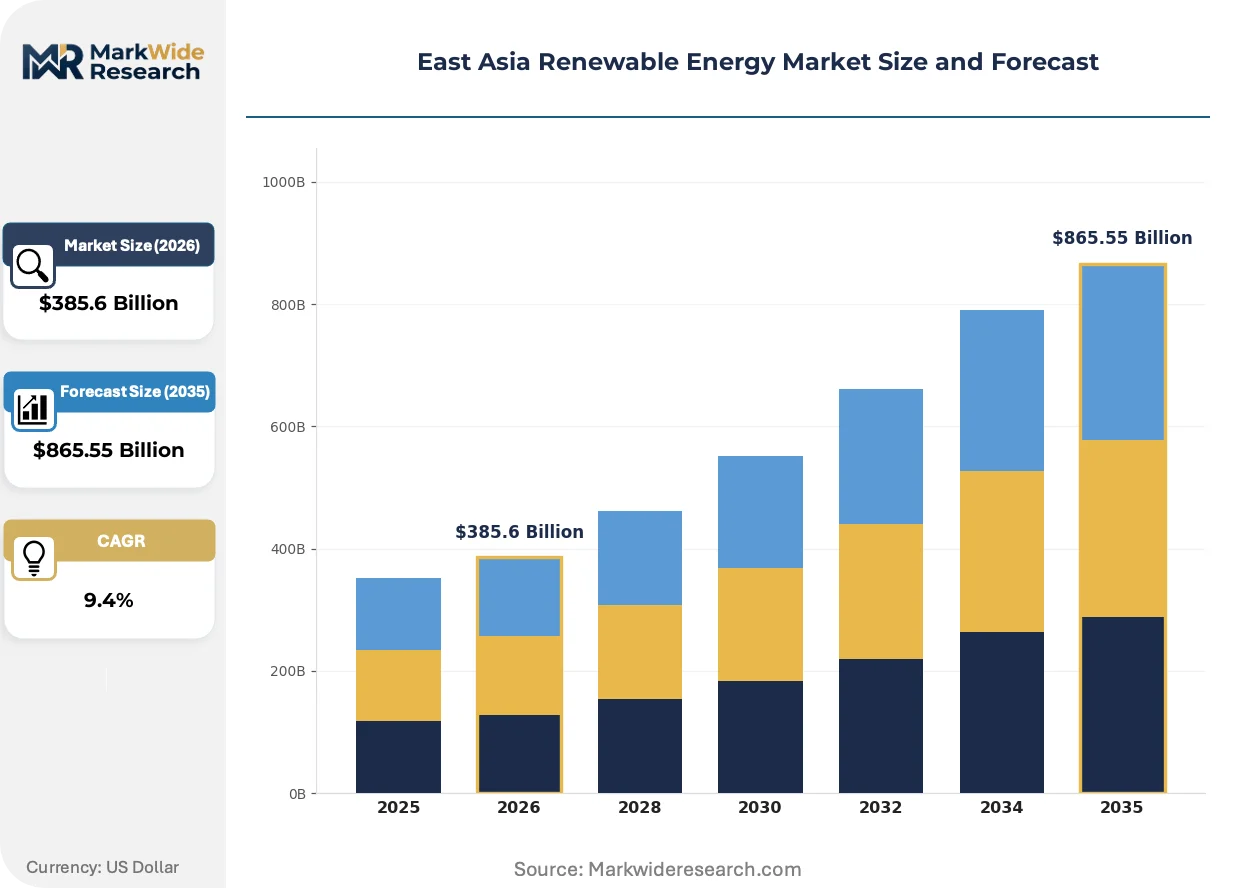
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $865.55 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Wind, Biomass, Geothermal End User: Residential, Commercial, Industrial, Government Installation Type: On-grid, Off-grid, Hybrid, Floating Technology: Photovoltaic, Concentrated Solar Power, Wind Turbines, Bioenergy Systems |
| Companies Covered | State Power Investment Corporation (SPIC), Adani Green Energy Limited, ReNew Power Ventures, Vena Energy, B.Grimm Power PCL, Gulf Energy Development PCL, ACEN Corp, BCPG PCL, WindPower Asia, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Asia Renewable Energy Market Shifts & Advancements
Technology convergence between floating solar and offshore wind is reshaping East Asian project economics. Developers exploit shared marine infrastructure and permitting frameworks to compress capital intensity.
Topcon cell architecture is overtaking PERC dominance in utility-scale photovoltaic procurement. Chinese module manufacturers scale tunnel oxide passivated contact production for coastal humidity resistance. Independent power producers in Guangdong and Fujian provinces specify Topcon for twenty-five-year degradation warranties.
Japan's METI revised its feed-in tariff degression schedule to accelerate offshore wind allocation. Developers must commit to domestic content ratios to qualify for premium pricing. Taiwanese project sponsors respond by contracting local jacket foundation fabrication.
Corporate renewable energy certificates now displace traditional utility offtake in South Korean industrial procurement. Electronics manufacturers direct bilateral contracts to specific solar and wind assets. This behavior concentrates most visibly in Gyeonggi Province manufacturing clusters seeking supply chain emissions disclosure.
East Asia Renewable Energy Market Segmentation
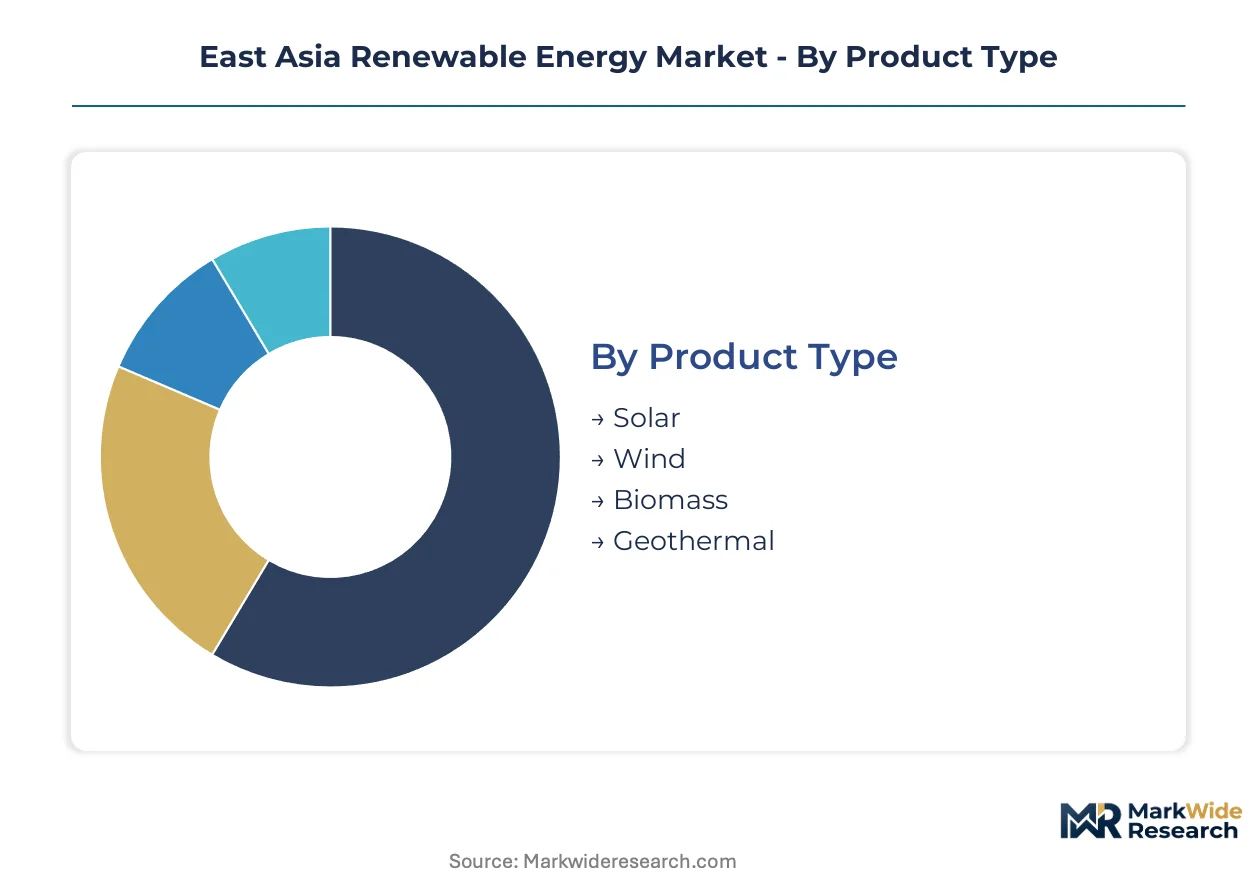
Technology heterogeneity across East Asia's renewable energy sector demands precise segmentation to align capital allocation with regulatory pathways. Each product type and installation configuration carries distinct permitting burdens, grid access protocols, and localization requirements that reshape project returns.
Product Type:
Solar arrays require GB standard certification from China's SAMR and JIS compliance for Japanese utility-scale deployments. Wind turbine installations face marine construction permits from Vietnam's CEA and offshore environmental reviews from Taiwan's regulatory authorities. Biomass facilities need emissions verification under China's MEE protocols. Geothermal developers secure resource exploration licenses from Japan's METI.
- Solar:Photovoltaic modules dominate capacity additions through tunnel oxide passivated contact cell architectures. Guangdong and Fujian provinces specify Topcon technology for coastal humidity resistance, with twenty-five-year degradation warranties becoming standard procurement terms.
- Wind:Horizontal-axis turbines in shallow-water zones achieve capacity factors above forty percent. Fixed-bottom foundations undercut floating alternatives on levelized cost, concentrating development in Vietnam's Mekong Delta corridors and Taiwan Strait lease blocks.
- Biomass:Anaerobic digester systems retain stable margins where agricultural residues provide captive fuel streams to industrial end users in China's interior provinces.
- Geothermal:Binary-cycle plants extract heat from low-enthalpy resources, with Japan's Kyushu island hosting the region's most mature development pipeline.
Solar sits at the top of the volume ranking, with wind climbing the fastest.
End User:
Cost tier stratification separates premium industrial offtake from economy residential programs. Large power consumers negotiate bilateral contracts while households rely on standardized feed-in tariffs.
- Residential:Rooftop penetration programs in China's coastal provinces and South Korea's Gyeonggi region drive distributed deployment, with net metering policies determining payback periods.
- Commercial:Electronics manufacturers in South Korea and Taiwan direct corporate renewable energy certificates to specific solar and wind assets for supply chain emissions disclosure.
- Industrial:Steel and ammonia producers pilot electrolyzer integration for green hydrogen offtake, converting renewable curtailment into feedstock cost advantage.
- Government:State-owned enterprises in China anchor multi-gigawatt pipelines through utility-scale procurement mandates tied to dual carbon goal compliance.
Industrial offtake commands the highest revenue per megawatt, with commercial segment expanding most quickly.
Installation Type:
Application context dictates foundation engineering and grid interconnection architecture. Marine installations require heavy-lift vessel contracting while remote systems need storage integration.
- On-grid:Utility-scale projects connect to provincial substations, though coastal province transmission headroom constraints absorb years of delay in dispatch authorization.
- Off-grid:Island grids in the Philippine archipelago lack baseload thermal alternatives, driving industrial estates toward captive diesel displacement through distributed solar.
- Hybrid:Four-hour lithium-ion battery duration caps renewable firming economics, with long-duration storage chemistries remaining pre-commercial for grid-scale deployment.
- Floating:Technology convergence between floating solar and offshore wind exploits shared marine infrastructure, compressing capital intensity through unified permitting frameworks.
On-grid installations retain dominant share, with floating configurations gaining share fastest.
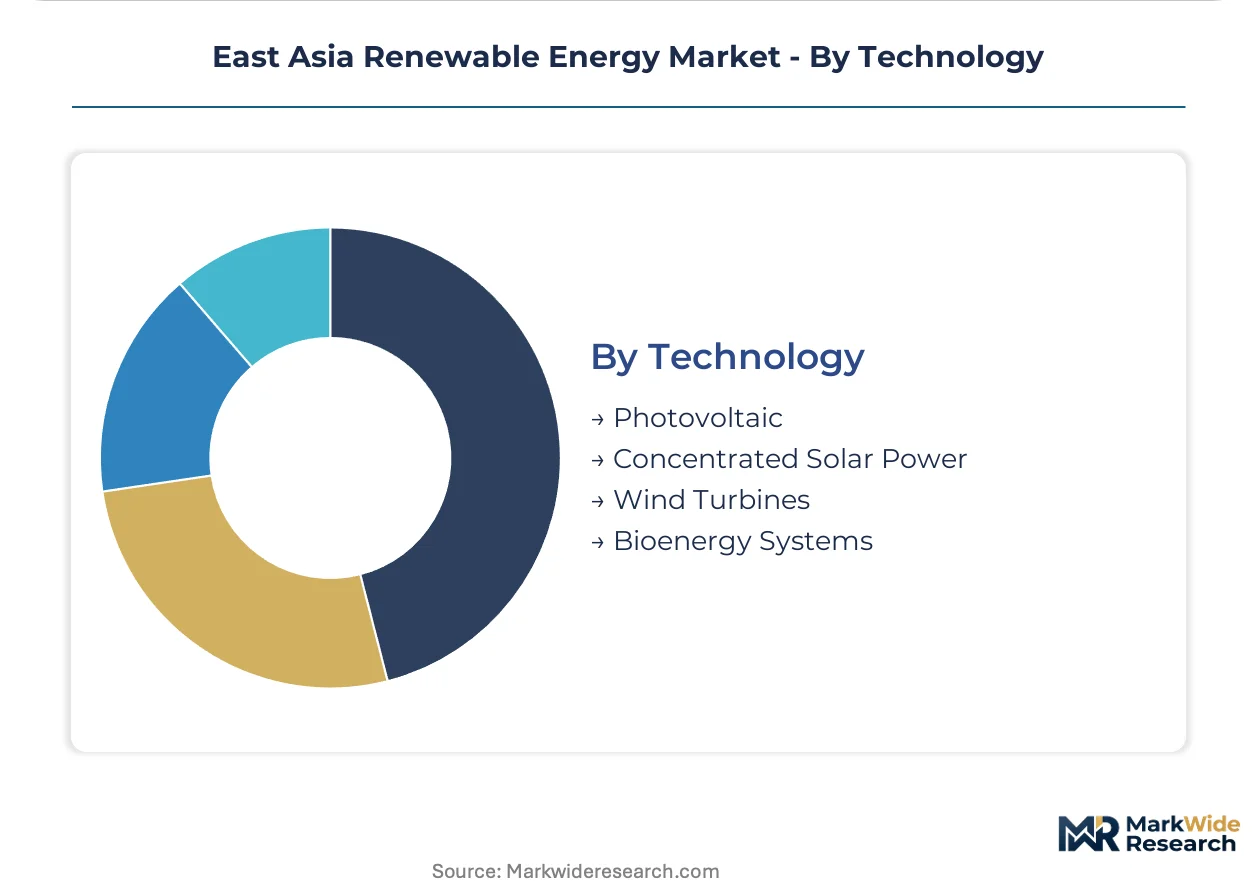
Technology:
Supply concentration shapes manufacturing scale and module cost trajectories. Chinese producers control photovoltaic cell output while European and Japanese vendors lead specialized turbine components.
- Photovoltaic:Topcon cell architecture overtakes PERC dominance in utility-scale procurement, with Chinese manufacturers scaling production for twenty-five-year warranties.
- Concentrated Solar Power:Thermal storage integration enables dispatchable renewable output, though high capital intensity limits deployment to demonstration projects.
- Wind Turbines:Fixed-bottom foundations in shallow-water zones achieve capacity factors above forty percent, with domestic content ratios qualifying Japanese projects for premium METI tariffs.
- Bioenergy Systems:Agricultural residue supply chains provide captive fuel streams to industrial end users, with anaerobic digesters processing waste streams for combined heat and power output.
Photovoltaic technology anchors installed capacity, with wind turbines showing steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asia's renewable energy industry traces its modern scale to China's state-led industrialization of photovoltaic manufacturing in the early 2000s. Japan's post-Fukushima feed-in tariff framework and South Korea's green growth initiatives subsequently layered demand-side architecture atop this supply base. Vietnam and Thailand later emerged as procurement hotspots through competitive auction mechanisms.
China
Coastal provinces in Guangdong and Fujian drive utility-scale solar procurement through dual carbon goal compliance mandates. The MEE enforces emissions intensity benchmarks that compel provincial grid operators to prioritize renewable dispatch. Yangtze River Delta manufacturing clusters anchor module production for twenty-five-year warranty Topcon cell deployments.
Japan
Offshore wind development accelerates in Kyushu island waters and Tokyo Bay lease blocks under revised METI feed-in tariff schedules. Domestic content ratios determine premium pricing eligibility for fixed-bottom foundation projects. Kansai industrial corridors around Osaka host binary-cycle geothermal pipelines extracting low-enthalpy resources.
South Korea
Steel and ammonia producers in Gyeonggi Province pilot electrolyzer integration for green hydrogen offtake from renewable curtailment. Corporate renewable energy certificates now displace traditional utility procurement for electronics manufacturing supply chain disclosure. Seoul Capital Area grid operators face storage duration constraints from four-hour lithium-ion battery caps.
Vietnam
Mekong Delta shallow-water wind corridors achieve capacity factors above forty percent through fixed-bottom foundation deployments. The CEA implements power purchase agreement frameworks that shape market access for independent producers, though retroactive tariff adjustments erode investor confidence. Southern industrial zones absorb distributed solar to offset coal import dependence.
Taiwan
Taiwan Strait lease blocks concentrate offshore wind specialization where heavy-lift vessel scarcity compresses installation windows to seasonal weather gaps. Agrivoltaic dual-use permitting preserves rice cultivation beneath elevated panel arrays in agricultural land-constrained western plains. Local jacket foundation fabrication responds to Japanese domestic content ratio requirements.
East Asia Renewable Energy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology specialization and offtake contract duration. State-backed conglomerates anchor multi-gigawatt pipelines through utility-scale procurement mandates, while independent power producers compete on offshore wind execution and distributed solar estate control. Three archetypes dominate: nuclear-to-renewables diversifiers, marine infrastructure specialists, and captive industrial estate operators. Consolidation moves center on pipeline acquisitions and joint venture structuring for shared marine construction assets.
Among state-backed diversifiers, State Power Investment Corporation exemplifies the nuclear-to-renewables pivot across multiple East Asian jurisdictions. Vena Energy occupies a position within the offshore wind specialization tier focused on Taiwan Strait developments. Gulf Energy Development PCL anchors the distributed solar estate control archetype through Thai industrial estate deployment. These three represent distinct capital allocation strategies responding to divergent regulatory pathways.
| Leading Market Players |
|---|
| State Power Investment Corporation (SPIC) |
| Adani Green Energy Limited |
| ReNew Power Ventures |
| Vena Energy |
| B.Grimm Power PCL |
| Gulf Energy Development PCL |
| ACEN Corp |
| BCPG PCL |
| WindPower Asia |
| Others |
Supply & Pricing Matrix
Captive polysilicon refining in Xinjiang anchors photovoltaic module economics and pricing power for Chinese manufacturers serving East Asian utility-scale procurement. This upstream integration insulates domestic producers from feedstock volatility while forcing non-integrated developers to absorb margin compression through long-term offtake renegotiation.
Pricing Analysis
Project-based long-term offtake contracting dominates East Asian renewable energy transactions, with pricing stratifying across premium, standard, and economy tiers based on technology certification grade and volume scale. Premium tiers command JIS-compliant Japanese offshore wind assets with domestic content ratios, while economy segments absorb unsubsidized distributed solar in Vietnamese industrial zones. Cost compression in standard-tier photovoltaic modules intensifies as tunnel oxide passivated contact cell production scales across Yangtze River Delta manufacturing clusters. Industrial conglomerates exhibit lowest price sensitivity due to dual carbon goal compliance mandates, whereas residential rooftop programs in South Korea's Gyeonggi region face payback period scrutiny.
Supply Chain Analysis
Maritime freight costs from Shanghai Port to Taiwan Strait installation sites constrain offshore wind project economics, with heavy-lift jack-up vessel charter rates feeding directly into capital intensity calculations. Polysilicon refining concentrates in Xinjiang and Inner Mongolia, while lithium-ion cell production centers on South Korea and Japan, and nacelle assembly feeds from European component suppliers. Raw material dependencies span high-purity silicon metal, rare earth permanent magnets, and biaxially oriented polyester film for module encapsulation. Single-source vulnerability in jack-up vessel availability creates seasonal installation bottlenecks. Distribution runs through state-backed procurement frameworks in China, competitive auction mechanisms in Vietnam, and corporate renewable energy certificate markets in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
East Asia's renewable energy market compounds steadily through state-mandated procurement volumes that de-risk capital deployment regardless of spot electricity pricing.
For Market Incumbents: Acquire shallow-water wind development rights in Vietnam's Mekong Delta corridors to preempt emerging marine infrastructure specialists. State Power Investment Corporation and Vena Energy should deepen backward integration into jacket foundation fabrication to satisfy Japanese METI domestic content requirements and defend margin position against tariff renegotiation risk from Vietnam's CEA. For New Entrants and Emerging Players: The mid-tier pricing gap between premium Japanese offshore wind and economy Vietnamese distributed solar creates entry space for hybrid floating solar-offshore wind developers. Philippine archipelago island grids present the most penetrable geography, with industrial estates seeking captive diesel displacement through distributed solar deployment paired with four-hour battery storage integration. For Investors and Strategic Acquirers: Consolidation pressure builds where project pipeline scarcity meets construction vessel bottlenecks in Taiwan Strait lease blocks. Long-term viability favors developers with multi-jurisdiction permitting expertise and state-backed offtake relationships. The signal to monitor is METI feed-in tariff degression schedules, which determine investor return thresholds for premium-tier asset allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Taiwan Strait fixed-bottom projects leverage Vietnam's Mekong Delta construction experience for METI tariff qualification. |
| Power Purchase Agreement Restructuring | Vietnam's CEA framework revisions force sponsors to renegotiate operational asset terms with industrial offtakers. |
| Technology Licensing for Topcon Cells | Chinese manufacturers license tunnel oxide passivated contact architecture to Southeast Asian module assembly partners. |
| Vertical Integration into Storage | South Korean developers integrate four-hour lithium-ion systems to firm renewable output for Gyeonggi industrial clusters. |
| Green Certification Program | Corporate renewable energy certificates in South Korea displace traditional utility procurement for electronics supply chain disclosure. |
Research Methodology
Multiple input streams — regulatory filing analysis, project development database tracking, and equipment procurement records — were reconciled to construct market estimates. Primary interviews with utility planning officers, independent power project developers, EPC contractors, and grid operators informed capacity addition timelines and interconnection queue dynamics. Secondary validation drew from IEA renewable energy reports, FERC-equivalent filings in Japan and South Korea, and customs data for module and turbine component trade flows. Bottom-up project-level aggregation was cross-checked against top-down national target reconciliation.
Data-stream reconciliation across technology type, installation configuration, end-use segment, and regulatory framework produced volume and value estimates across the projection horizon. Segmentation dimensions modeled include generation technology, project scale tier, grid connection type, and regional procurement mechanism. CAGRs were derived from fitted growth curves anchored to disclosed capacity targets and historical deployment trajectories. Forecast inputs incorporated METI tariff schedule revisions, MEE emissions intensity benchmark enforcement timelines, and CEA power purchase agreement renegotiation patterns.
Caveats apply where retroactive tariff adjustments, polysilicon supply chain disruptions, or long-duration storage technology breakthroughs could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Showers Market
Renewable Energy
Renewable Heating Market
Renewable Energy
Zimbabwe Renewable Energy Market
Renewable Energy
Tidal Turbines Market
Renewable Energy
Solar Panel Mounting Structure Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
New Zealand Renewable Energy Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
Renewable Energy Consulting Service Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Japan Renewable Energy Market
Renewable Energy
Ethiopia Renewable Energy Market
Renewable Energy
Europe Solar Tracker Market
Renewable Energy
Renewable Energy Sources Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Nigeria Renewable Energy Market