
 Poland POS Terminal Market | 2026-2036
Poland POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Poland POS Terminal Market Analytics
Market Context
PSD2 is recalibrating the cost-of-entry calculus for terminal vendors seeking Polish market access. Ingenico Group (Worldline) leverages its European certification depth to sustain deployment momentum across Polish banking channels. Verifone Systems anchors its position through channel control over independent software vendor partnerships. Elzab S.A. competes on manufacturing scale from its domestic production base.
Technical Definition and Segment Structure
A POS terminal is an electronic device that captures payment card data through integrated chip readers, NFC antennas, and PIN entry interfaces, processing transactions via encrypted communication with acquiring banks. Its primary commercial purpose is to finalize consumer purchases while ensuring PCI-DSS compliant data handling. Mobile POS leads volume growth among product types as Polish micro-merchants abandon fixed counter installations. Contactless payments dominate transaction modality expansion, with NFC-enabled terminals now standard in retail and hospitality verticals. Cloud-based POS systems capture margin pools through recurring software fees rather than one-time hardware sales.
Regulatory Framework and Outlook
The Polish Financial Supervision Authority enforces PSD2 strong customer authentication mandates that directly shape terminal firmware requirements. BIS certification for electromagnetic compatibility and EU RoHS directives constrain hardware material selection and import pathways. The EU AI Act introduces emerging compliance dimensions for terminals deploying biometric payment verification. Stakeholders must monitor whether Polish transposition of EU digital wallet regulations accelerates hardware refresh cycles or extends replacement timelines.
Market Dynamics
PSD2 strong customer authentication mandates are compressing hardware refresh cycles across Polish retail banking channels, forcing acquirers to replace legacy terminals before planned end-of-life dates.
Growth Catalysts
- Contactless transaction thresholds:The Polish Financial Supervision Authority's elevated contactless limits without PIN verification accelerate NFC terminal deployment across convenience retail and quick-service food verticals.
- Mobile POS penetration:Micro-merchants in Warsaw and Krakow metropolitan corridors abandon fixed countertop installations in favor of smartphone-connected card readers.
- Cloud software attachment:Recurring SaaS fees from inventory management and analytics modules transform hardware vendors into platform providers.
Market Restraints
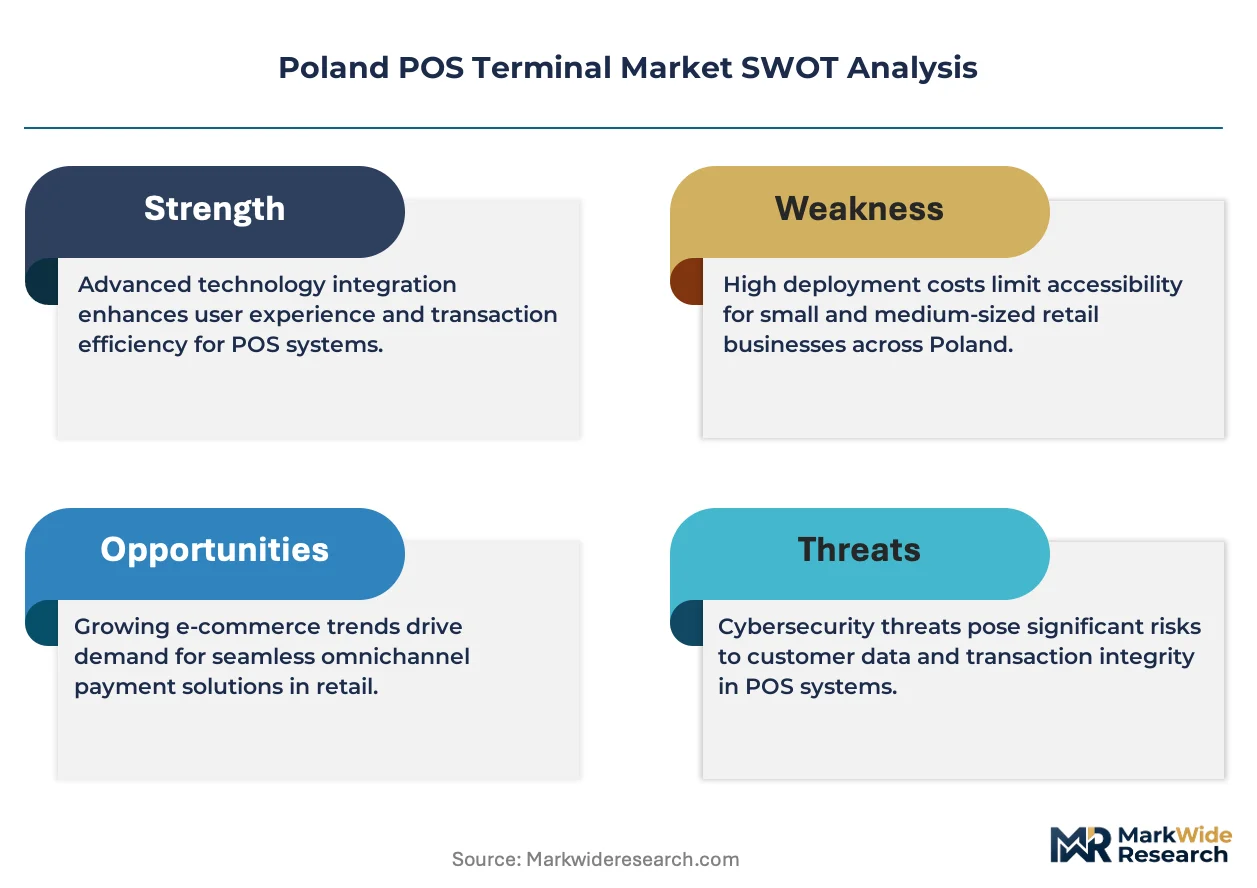
- EMV certification bottlenecks:Polish acquirer-specific certification requirements extend terminal approval timelines by four to six months versus pan-European schemes.
- Semiconductor supply concentration:Secure element chip sourcing depends on a concentrated Asian supplier base, creating vulnerability to allocation constraints.
- Fixed infrastructure substitution:SoftPOS solutions running on standard Android devices threaten dedicated hardware demand among low-volume merchants.
Strategic Opportunities
- Biometric payment verification:The EU AI Act's emerging compliance framework for facial recognition authentication creates first-mover advantage for terminal vendors with embedded camera modules.
- Independent software vendor channel:Polish hospitality and specialty retail sectors seek integrated vertical solutions combining payment hardware with sector-specific software.
- Suburban and secondary city expansion:Terminal density in Łódź, Wrocław, and Poznań lags Warsaw-Krakow corridors by approximately half the merchant penetration rate.
Industry Challenges
- Firmware engineering scarcity:Polish labor markets lack sufficient embedded systems developers capable of implementing PSD2-compliant cryptographic modules.
- PCI-DSS audit compression:Annual compliance recertification timelines squeeze engineering resources across multiple concurrent hardware platforms.
- Multi-acquirer integration complexity:Poland's fragmented acquiring landscape requires terminal vendors to maintain separate certification tracks for each major bank.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland POS Terminal Market |
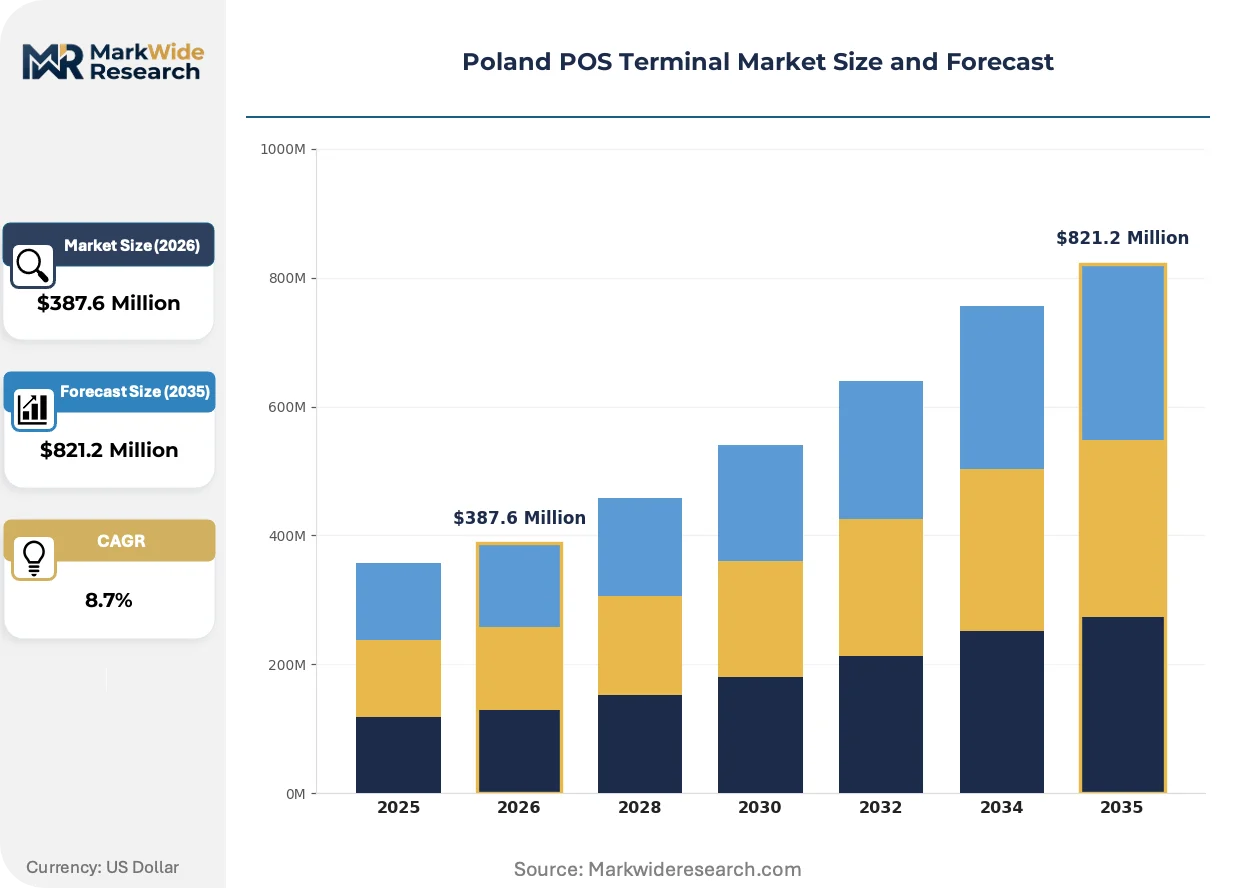
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Fixed POS, Self-service Kiosks, Cloud-based POS Industry Vertical: Retail, Hospitality, Transportation, Healthcare Payment Mode: Card Payments, Contactless Payments, Mobile Wallets, QR Code Payments Service Type: Installation, Maintenance, Technical Support, Upgrades |
| Companies Covered | Samsung Electronics, Ingenico Group (Worldline), HP Development Company, Verifone Systems, PAX Technology, Panasonic Corporation, NEC Corporation, Elzab S.A., NCR Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland POS Terminal Market Evolving Landscape
Payment terminal architecture is converging around software-defined platforms where hardware becomes a commodity shell for cloud-orchestrated transaction processing and value-added service delivery.
Tap-on-phone technology is electrifying merchant acquisition economics by eliminating dedicated hardware costs entirely. Polish payment facilitators deploy smartphone-based acceptance to sole proprietors and market vendors previously priced out of electronic payments. This capability is compressing addressable market definitions for traditional terminal manufacturers.
The EU AI Act introduces biometric authentication compliance obligations that reshape terminal design specifications. Hardware vendors must now embed liveness detection and template protection capabilities for facial recognition payment flows. Polish banks piloting palm-vein authentication face eighteen-month certification horizons with domestic regulators.
Merchant procurement preferences are fragmenting across ownership models. Large Polish retail chains favor terminal-as-a-service contracts bundling hardware, software, and support into per-transaction fees. Independent merchants increasingly purchase devices outright through distributor channels, unbundling after-sales service relationships. This bifurcation is most visible in Warsaw's competitive retail corridor where both models operate at comparable scale.
Poland POS Terminal Market Segmentation
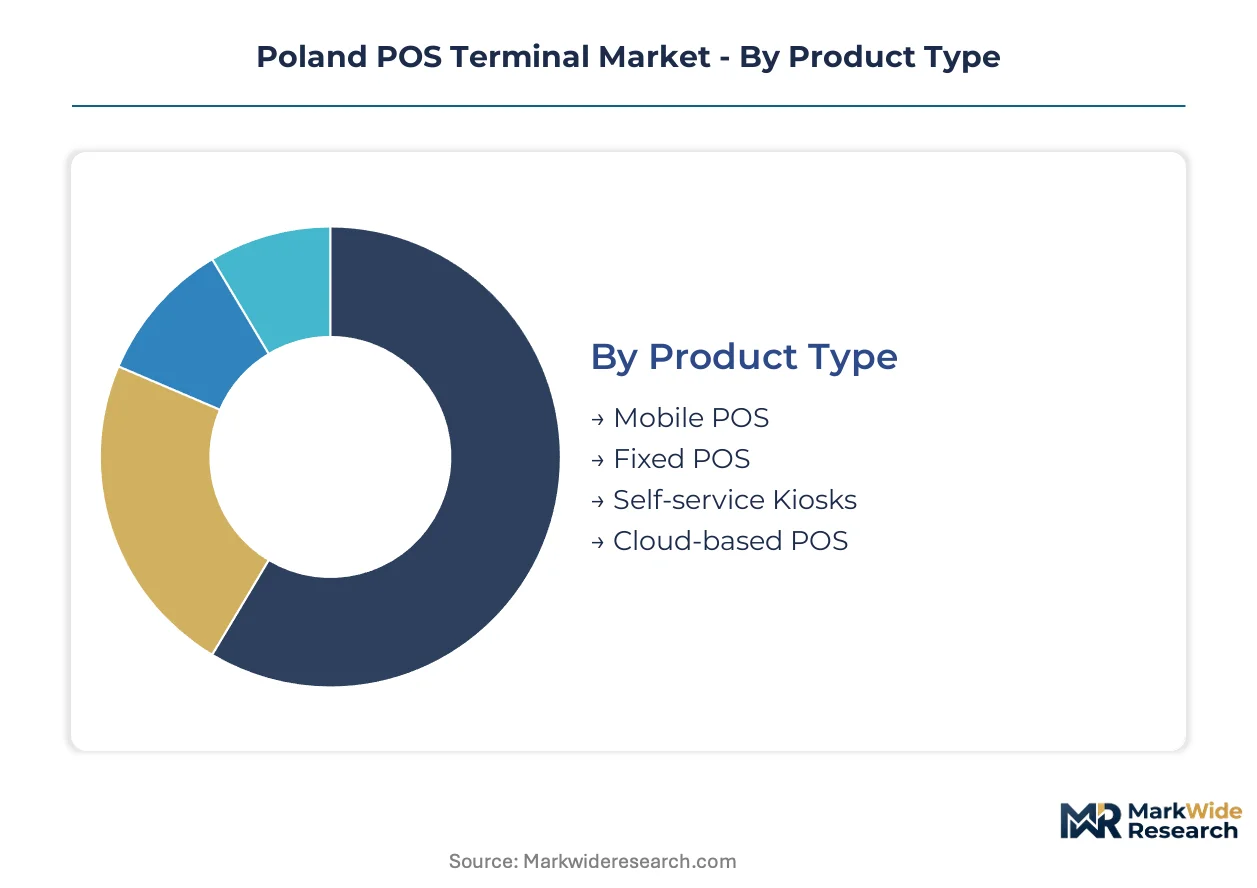
Segmentation reveals how Polish merchants prioritize flexibility over fixed infrastructure. Warsaw micro-merchants drive volume in portable solutions while Krakow retail chains anchor premium fixed installations. The PSD2 compliance burden reshapes procurement patterns across every category.
Product Type:
Volume concentrates in smartphone-connected readers. Premium deployments favor countertop units with integrated receipt printers.
- Mobile POS:Compact card readers pair with Android or iOS devices via Bluetooth or audio jack connections. Warsaw sole proprietors and market vendors in Łódź adopt these for street commerce and pop-up retail, driven by zero upfront hardware cost and instant onboarding through payment facilitator apps. This segment gains share fastest among Polish micro-merchants abandoning cash.
- Fixed POS:Countertop terminals with Ethernet or WiFi connectivity, integrated thermal printers, and PIN pads. Krakow shopping malls and Poznań department stores standardize on these for checkout lane throughput, constrained by PSD2 firmware recertification cycles that compress replacement timelines.
- Self-service Kiosks:Unattended payment terminals with touchscreen interfaces for ordering and checkout. Quick-service food chains in Wrocław deploy these for labor cost reduction.
- Cloud-based POS:Software-defined platforms running on generic tablets with payment attachments. Polish hospitality operators favor these for SaaS inventory modules.
Mature deployment sits with Fixed POS. Newer deployment is concentrated in Mobile POS.
Industry Vertical:
Application intensity varies by transaction velocity and regulatory exposure.
- Retail:Supermarkets, convenience stores, and specialty merchants processing high-frequency card transactions. Warsaw convenience chains accelerate NFC terminal refresh to capture elevated contactless limits without PIN verification, while Biedronka and Żabka franchisees drive standardization across formats.
- Hospitality:Restaurants, bars, and hotels requiring tableside payment and tip adjustment workflows. Krakow's tourism corridor demands multilingual interfaces and split-bill functionality.
- Transportation:Ticketing systems for public transit and parking enforcement. Warsaw municipal operators pilot tap-on-phone for bus fare collection.
- Healthcare:Clinics and pharmacies handling patient co-payments and prescription transactions. Polish pharmacy chains face PCI-DSS audit compression for prescription data co-mingling.
Procurement scale peaks in Retail. Feature complexity concentrates in Hospitality.
Payment Mode:
Margin pools shift toward authentication-light transaction types.
- Card Payments:Traditional magnetic stripe and EMV chip transactions requiring physical card insertion. Legacy infrastructure in secondary Polish cities maintains this modality, though declining as NFC penetration advances.
- Contactless Payments:NFC tap-to-pay transactions under Polish Financial Supervision Authority thresholds. This modality dominates Warsaw and Krakow metropolitan corridors, with Polish acquirers mandating NFC capability for all new terminal deployments.
- Mobile Wallets:Apple Pay, Google Pay, and Blik integration through host card emulation. Polish banks promote Blik wallet acceptance to reduce interchange costs.
- QR Code Payments:Static and dynamic QR codes for merchant-presented or customer-presented flows. Limited Polish adoption outside Alipay tourist corridors.
Transaction volume concentrates in Contactless Payments. Infrastructure investment targets Mobile Wallets.
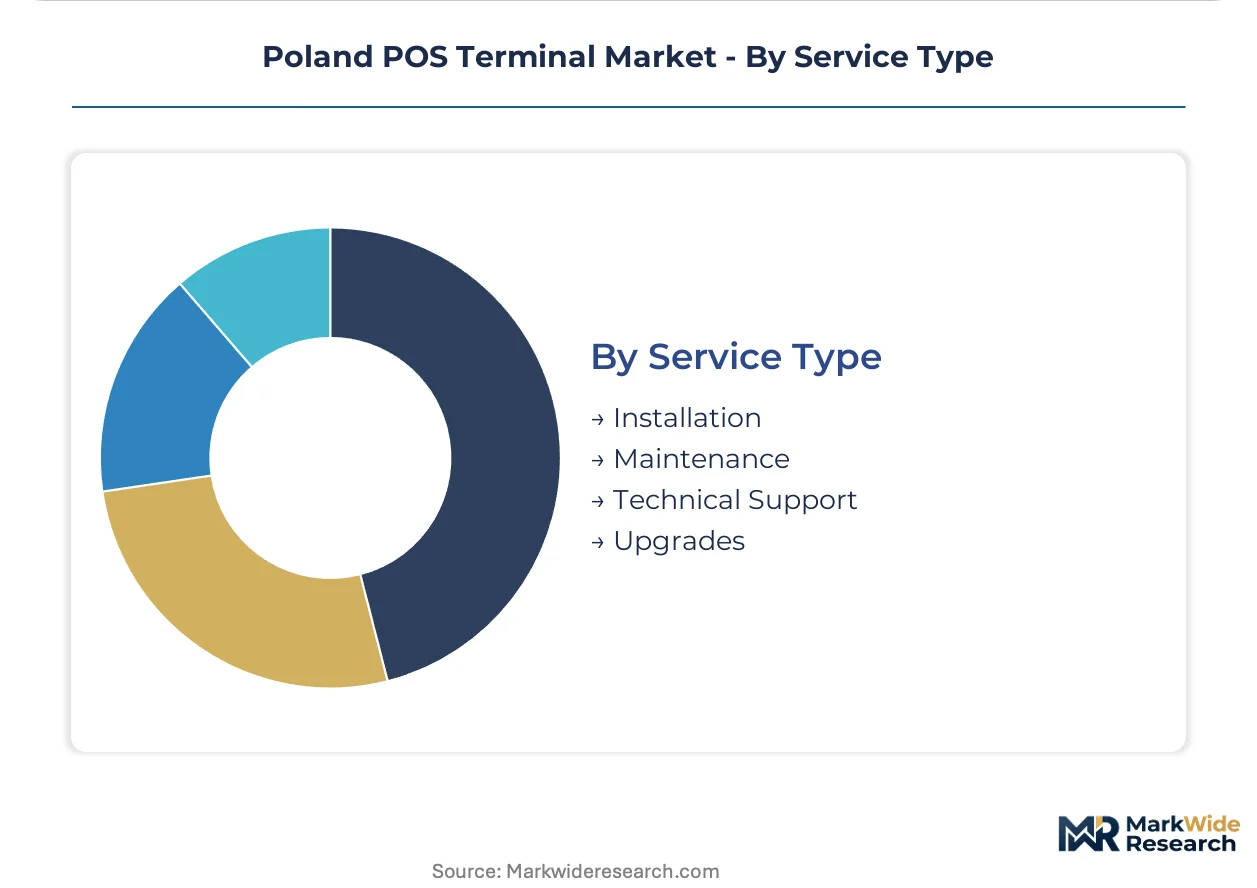
Service Type:
Recurring revenue attachment separates platform vendors from hardware sellers.
- Installation:Physical deployment, network configuration, and merchant training. Polish acquirers bundle this with hardware leases to lock in multi-year relationships.
- Maintenance:Preventive servicing, component replacement, and hardware failure response. Terminal density in Warsaw demands 24-hour SLA commitments.
- Technical Support:Helpdesk operations for transaction failures, reconciliation disputes, and firmware updates. Polish micro-merchants rely on payment facilitator chat support rather than vendor direct channels.
- Upgrades:Firmware refreshes for regulatory compliance and security patches. PSD2 strong customer authentication mandates force accelerated upgrade cycles across Polish banking channels.
Contracted revenue concentrates in Maintenance. Discretionary spending flows to Upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polish terminal demand concentrates in metropolitan corridors where retail density and banking infrastructure intersect. Warsaw and Krakow anchor deployment volumes, while secondary cities lag in merchant penetration rates.
Masovian Voivodeship
Warsaw's convenience retail chains and quick-service food operators drive NFC terminal refresh cycles to capture elevated contactless limits. The Polish Financial Supervision Authority mandates PSD2 strong customer authentication compliance for all new deployments. Biedronka and Żabka franchisees cluster in Warsaw's retail corridors, standardizing hardware specifications across formats.
Lesser Poland Voivodeship
Krakow's tourism corridor demands multilingual interfaces and split-bill functionality from hospitality-focused terminals. EU RoHS directives constrain hardware material selection for imports entering through southern logistics routes. Shopping malls in Krakow's city center anchor premium fixed POS installations with integrated receipt printers.
Silesian Voivodeship
Katowice's industrial restructuring creates demand from emerging service sector micro-merchants adopting mobile POS solutions. BIS certification requirements for electromagnetic compatibility extend approval timelines for terminal vendors. Former mining towns in the region show accelerated cash-to-card conversion among sole proprietors.
Greater Poland Voivodeship
Poznań's retail terminal density trails Warsaw-Krakow corridors by approximately half the merchant penetration rate. The EU AI Act introduces emerging compliance dimensions for biometric payment verification pilots. Logistics hubs around Poznań attract payment facilitator operations serving cross-border e-commerce merchants.
Lower Silesian Voivodeship
Wrocław's quick-service food chains deploy self-service kiosks for labor cost reduction at scale. PCI-DSS audit compression squeezes engineering resources for pharmacy chains handling prescription data co-mingling. Technology parks in Wrocław host software-defined POS platform development for hospitality verticals.
Poland POS Terminal Market Competitive Landscape
European producers anchor one tier; Asian specialists hold manufacturing scale advantages in component supply. The vendor base structures around certification depth versus cost engineering trade-offs. Three archetypes dominate: pan-European payment technology platforms, domestic manufacturing specialists with regulatory proximity, and diversified electronics conglomerates with component integration capabilities. Strategic moves concentrate on ISV partnership channel control and accelerated firmware certification tracks.
Within the European platform tier, Ingenico Group (Worldline) and Verifone Systems occupy positions defined by acquirer relationship depth and certification breadth. Elzab S.A. represents the domestic specialist archetype, leveraging manufacturing proximity to Polish banking channels. Samsung Electronics exemplifies the diversified conglomerate model, anchoring terminal hardware within broader device ecosystems.
| Leading Market Players |
|---|
| Samsung Electronics |
| Ingenico Group (Worldline) |
| HP Development Company |
| Verifone Systems |
| PAX Technology |
| Panasonic Corporation |
| NEC Corporation |
| Elzab S.A. |
| NCR Corporation |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap Polish distributors with deep banking channel relationships anchor procurement behavior, translating acquirer consolidation into volume-based pricing discipline while squeezing margin pools for hardware vendors without certification depth.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent deployment premiums from standard-cycle discounts in Polish terminal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification grade and after-sales bundling intensity. Price erosion runs through economy-tier mobile readers as payment facilitators absorb hardware costs to capture transaction volume. Micro-merchants in Warsaw street commerce exhibit highest price sensitivity, while Krakow retail chains prioritize certification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands feed hub-and-spoke patterns into Polish metropolitan corridors. Secure element chip sourcing draws from Taiwan and South Korea, while final assembly concentrates in China and Vietnam. Single-source vulnerability in semiconductor allocation creates bottleneck exposure during supply shocks. Distribution runs through authorized banking channel partners rather than open distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PSD2 strong customer authentication mandates construct a cost-of-compliance moat that favors incumbent terminal vendors with pre-certified firmware libraries, erecting barriers that strain new entrant capital deployment.
For Market Incumbents: Lock in multi-year terminal-as-a-service contracts with Polish banking channels to preempt SoftPOS substitution threats. Deepen backward integration into secure element procurement to buffer semiconductor allocation volatility. Prioritize firmware engineering capacity expansion to compress PSD2 recertification timelines. For New Entrants and Emerging Players: Enter via biometric payment verification pilots in hospitality verticals where AI Act compliance complexity deters incumbent speed. Target Łódź and Poznań secondary corridors where terminal density lags Warsaw-Krakow penetration. Deploy ISV partnership models bundling vertical software with payment hardware. For Investors and Strategic Acquirers: Polish bank announcements of palm-vein authentication pilots are the leading indicator that biometric terminal refresh cycles will accelerate. Position for platform consolidation plays where SaaS attachment rates transform hardware vendors into recurring revenue generators. Monitor EU AI Act transposition timelines as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| PSD2 Firmware Certification Acceleration | Compresses approval timelines with Polish Financial Supervision Authority to capture replacement cycle demand. |
| ISV Channel Partnership Expansion | Integrates payment hardware with hospitality inventory systems to lock in vertical-specific merchant relationships. |
| Biometric Module Integration | Positions vendors for EU AI Act compliance in facial recognition and palm-vein authentication pilots. |
| Secondary City Distribution Buildout | Captures underpenetrated merchant bases in Łódź, Wrocław, and Poznań corridors. |
| SoftPOS Capability Development | Defends against smartphone-based substitution threatening dedicated terminal demand among micro-merchants. |
Research Methodology
Multi-period observation of terminal deployment volumes, certification timelines, and merchant acquisition patterns anchored the trend analysis, supplemented by interviews with Polish acquirer procurement directors, payment facilitator operations managers, terminal vendor sales executives, and independent software vendor integration specialists. Secondary validation drew from Polish Financial Supervision Authority regulatory filings, EU RoHS compliance databases, PCI-DSS certification registries, and customs import records. Bottom-up merchant penetration modeling triangulated against top-down banking channel volume disclosures.
Segment-weighting across product type, industry vertical, payment mode, and service type dimensions structured the analytical framework across the projection horizon. CAGRs derived from logistic diffusion curves fitted to contactless payment adoption rates, hardware replacement cycle compression, and SaaS attachment trajectories. Terminal density benchmarks by metropolitan corridor and acquirer market share shifts informed regional allocation assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or accelerated SoftPOS regulatory approval scenarios. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Denmark POS Terminals Market
Payments
Bulgaria POS Terminals Market
Payments
Accelerator Card Market
Payments
Mobile Payment Security Market
Payments
Japan Prepaid Cards Market
Payments
Germany Mobile Payments Market
Payments
Global Gift Card Market
Payments
Vietnam Mobile Payments Market
Payments
Italy Payments Market
Payments
Norway POS Terminals Market
Payments
Retail Cash Management Market
Payments
United Arab Emirates Mobile Payments Market
Payments
Payment Security Market
Payments
Smart Bands Payments Market
Payments
Biometric Payment Cards Market
Payments
North America POS Terminal Market