
 Japan Prepaid Cards Market | 2026-2036
Japan Prepaid Cards Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Prepaid Cards Market Intelligence
The Payment Services Act is shifting compliance burdens onto smaller fintech entrants while reinforcing the structural advantages of incumbent issuers. East Japan Railway Corp. leverages its Suica transit network to anchor prepaid card circulation across Kantō, with platform ubiquity sustaining transaction density even as mobile wallets proliferate. Rakuten Card Co., Ltd. competes through ecosystem lock-in, bundling prepaid instruments with e-commerce and loyalty point architectures. Seven & I Holdings Co. Ltd. dominates convenience-store reload infrastructure, controlling physical access points that remain critical for cash-preferred demographics.
Japan prepaid cards are stored-value instruments issued by regulated entities, typically bearing IC chip or magnetic stripe interfaces, pre-funded by cardholders or third-party purchasers, and redeemable for goods, services, or transit access within defined acceptance networks. Their primary commercial purpose centers on substituting cash in high-frequency, low-value transactions while enabling issuer float revenue and consumer spending control. Closed-loop transit-integrated products occupy the mature volume core, whereas open-loop general-purpose instruments represent the fastest-expanding margin pool as interoperability standards advance. Gift cards concentrate seasonal revenue spikes, while corporate client segments sustain predictable reload velocities through payroll and incentive program integrations.
METI oversees electronic payment infrastructure standards, the FSA enforces Payment Services Act prudential rules on issuer capitalization and fund segregation, and JIS standards govern IC chip interoperability across competing platforms. These frameworks collectively elevate consumer trust thresholds, constrain unlicensed market entry, and perpetuate incumbent network effects through technical compliance barriers. Stakeholders must monitor whether forthcoming FSA guidelines on prepaid fund safeguarding will force structural separation of float management from core issuing operations.
Market Dynamics
Japan's prepaid card ecosystem is undergoing platform consolidation as transit-integrated IC chip networks extend into general-purpose commerce, compressing the addressable market for standalone open-loop products while elevating technical compliance barriers for new entrants.
Growth Catalysts
- Corporate expense digitization:Large enterprises are migrating employee benefits and travel allowances onto reloadable prepaid instruments, creating predictable reload velocities and reducing payroll administrative overhead.
- METI interoperability mandates:Standardization of IC chip protocols across competing transit and retail networks is dissolving closed-loop boundaries and enabling cross-platform redemption.
- Kantō metropolitan density:Greater Tokyo's concentrated population and commuter rail dependency sustain transaction density that subsidizes infrastructure investment across peripheral regions.
Market Restraints
- FSA capital requirements:The Payment Services Act mandates minimum capitalization thresholds and fund segregation protocols that disproportionately burden non-bank fintech issuers.
- Cash preference inertia:Demographic segments outside major metropolitan areas maintain strong physical currency habits, limiting reload network utilization in rural prefectures.
- Mobile wallet substitution:Smartphone-based payment applications linked directly to bank accounts are capturing transaction volume that previously cycled through prepaid float.
Strategic Opportunities
- Tourism inbound recovery:Foreign visitor reloadable cards with multi-currency capabilities and transit integration address unmet demand at Narita and Haneda airport corridors.
- Elderly financial inclusion:Simplified interface prepaid products with caregiver reload permissions serve aging rural populations in Hokkaido and Tohoku sub-regions.
- JIS standard convergence:Chip interoperability specifications are enabling issuer partnerships that previously required proprietary infrastructure duplication.
Industry Challenges
- Float management complexity:Issuers must maintain segregated asset pools for outstanding stored value while generating yield in negative interest rate environments.
- Legacy system integration:Corporate clients demand API connectivity with existing ERP and payroll platforms, requiring substantial middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Prepaid Cards Market |
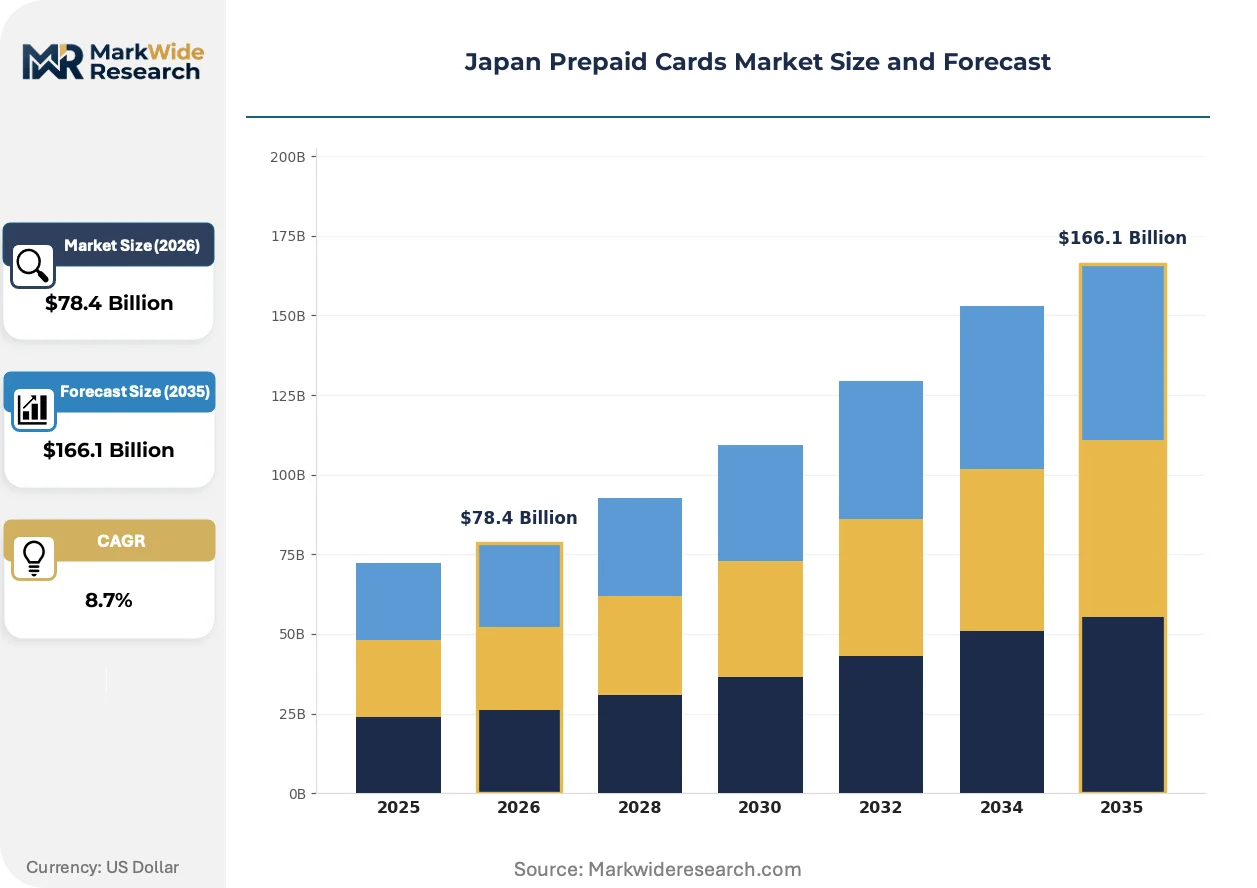
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $166.1 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Loop, Open Loop, Multi-Purpose, Gift Cards Customer Type: Retail Consumers, Corporate Clients, Students, Tourists Distribution Channel: Online, Retail Stores, Financial Institutions, Supermarkets Usage Purpose: E-commerce, Travel, Gift Giving, Daily Expenses |
| Companies Covered | East Japan Railway Corp., SMBC Finance Service Co., Ltd., Rakuten Card Co., Ltd., Orient Corporation, Viewcard Co., Ltd., Seven & I Holdings Co. Ltd., West Japan Railway Co., Rakuten Edy, Aeon Credit Service Co. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Prepaid Cards Market Strategic Shifts & Innovations
Contactless IC chip infrastructure is extending beyond transit gates into retail and service environments, while regulatory pressure on fund safeguarding is forcing operational restructuring among established issuers.
Felica-based contactless technology is expanding into vending machines, convenience stores, and hospitality venues throughout the Kantō corridor. Small merchants lacking legacy POS infrastructure are adopting inexpensive NFC readers that accept transit-issued prepaid balances without acquiring bank relationships. This expansion is compressing the historical distinction between closed-loop transit products and open-loop general-purpose cards.
FSA guidelines on prepaid fund safeguarding are compelling issuers to separate float management from core operations. The prudential framework requires independent custody arrangements and enhanced disclosure protocols. Large transit operators with existing trust banking relationships are absorbing compliance costs more efficiently than mid-tier competitors.
Corporate procurement departments are unbundling incentive and expense programs from traditional banking relationships. Manufacturing and logistics firms in Osaka and Nagoya industrial zones are issuing branded prepaid instruments for supplier payments and contractor settlements. This behavioral shift concentrates demand among B2B service providers capable of bulk issuance and custom program administration.
Japan Prepaid Cards Market Segmentation
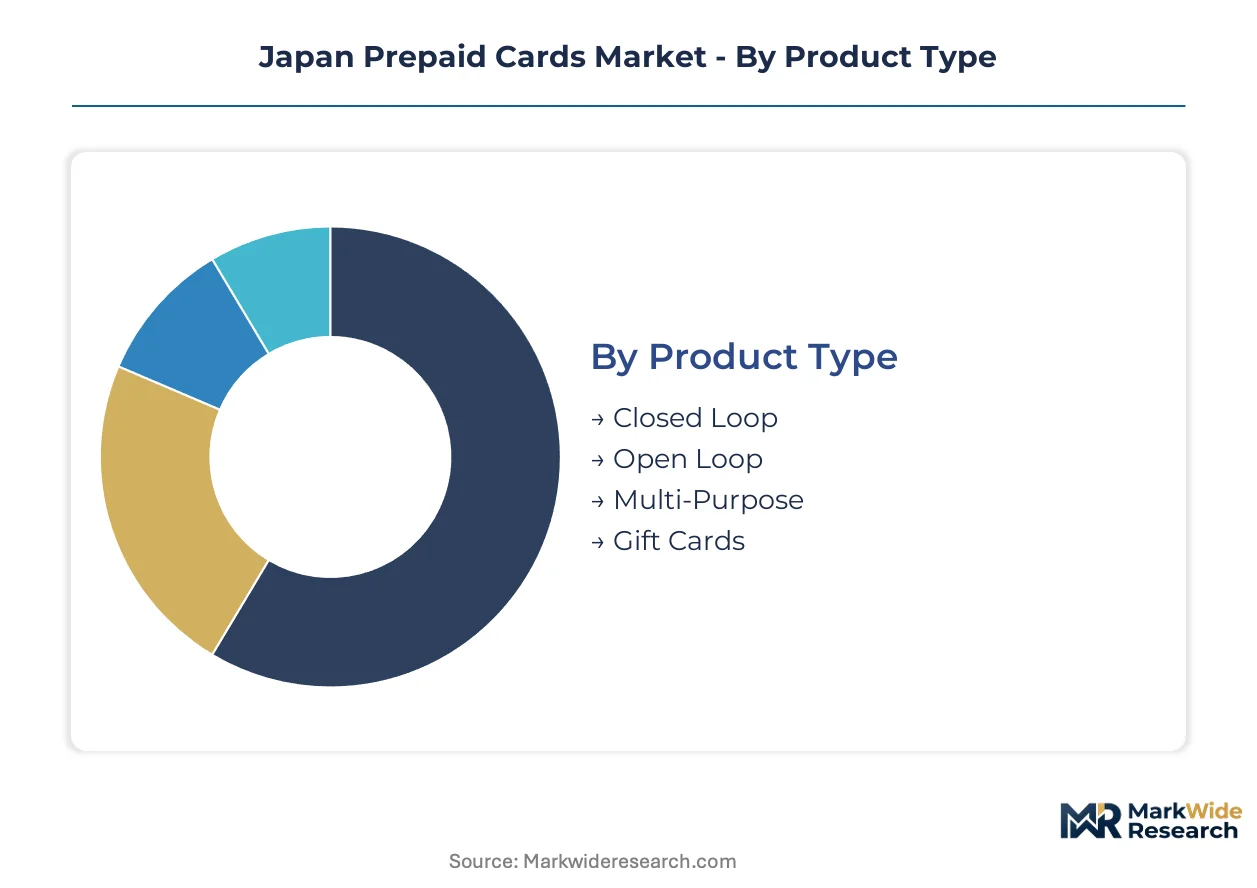
Prepaid card segmentation in Japan reflects divergent technical architectures and purchasing behaviors across consumer demographics. Product type distinctions determine interoperability scope, while distribution channel selection reveals persistent cash-reload dependencies in aging prefectures.
Product Type:
Upgrade cycles favor chip-enabled instruments replacing magnetic stripe legacy products, with transit-integrated platforms driving replacement velocity.
- Closed Loop:Proprietary IC chip systems restrict redemption to issuer-defined merchant networks. Suica and PASMO dominate Greater Tokyo transit corridors, where commuter density sustains transaction volume that subsidizes peripheral infrastructure deployment.
- Open Loop:Interoperable schemes redeemable across multiple acquiring networks. Demand concentrates among corporate procurement departments seeking unified expense instruments for distributed workforces across Osaka and Nagoya industrial zones.
- Multi-Purpose:Hybrid architectures combining transit access with general retail functionality. These products leverage JIS standard convergence to reduce merchant onboarding friction.
- Gift Cards:Seasonal stored-value instruments with fixed denominations. Concentrated revenue spikes align with Japanese fiscal year-end bonus periods and summer gift-giving customs.
Closed Loop sits at the top of the volume ranking, with Open Loop climbing the fastest.
Customer Type:
Cost tier differentiation separates enterprise-grade program administration from self-service retail acquisition.
- Retail Consumers:Individual purchasers seeking spending control alternatives to credit facilities. Demand clusters in Kantō metropolitan households managing discretionary budgets through reloadable float.
- Corporate Clients:Enterprise issuers of employee benefit and expense instruments. Manufacturing and logistics firms in Aichi and Osaka prefectures drive bulk issuance for contractor settlements and supplier payments.
- Students:Campus-oriented products with parental reload permissions and merchant restrictions. University co-op partnerships in Kyoto and Fukuoka anchor distribution.
- Tourists:Foreign visitor instruments with multi-currency capabilities and transit integration. Narita and Haneda airport corridors concentrate activation volume.
Corporate Clients command the highest reload velocity, while Tourists gain share fastest on inbound recovery.
Distribution Channel:
Geography determines channel effectiveness, with urban-rural divides shaping physical versus digital acquisition preferences.
- Online:Direct-to-consumer issuance through issuer portals and mobile applications. Rakuten ecosystem integration drives adoption among existing loyalty program members.
- Retail Stores:Convenience store reload infrastructure remains critical for cash-preferred demographics. Seven-Eleven Japan controls dominant physical access points across Hokkaido through Okinawa.
- Financial Institutions:Bank branch distribution targeting corporate treasury relationships. Trust banking partnerships facilitate FSA-compliant fund segregation.
- Supermarkets:Mass merchant activation kiosks serving family procurement patterns. AEON and Ito-Yokado networks anchor suburban penetration.
Retail Stores maintain the widest geographic coverage, with Online expanding most quickly among metropolitan youth segments.
Usage Purpose:
Application-specific functionality drives product design, with transit-integrated instruments capturing cross-purpose adoption.
- E-commerce:Virtual card numbers and one-time credentials for online merchant checkout. Rakuten and Amazon Japan marketplace integration concentrates demand.
- Travel:Multi-modal transit and hospitality redemption across JR East and private railway networks. Business traveler expense reconciliation drives corporate adoption.
- Gift Giving:Seasonal fixed-value instruments with ceremonial packaging. Department store alliances in Ginza and Shibuya sustain premium positioning.
- Daily Expenses:High-frequency low-value substitution for cash in vending machines and convenience stores. Felica contactless infrastructure enables tap-and-go velocity.
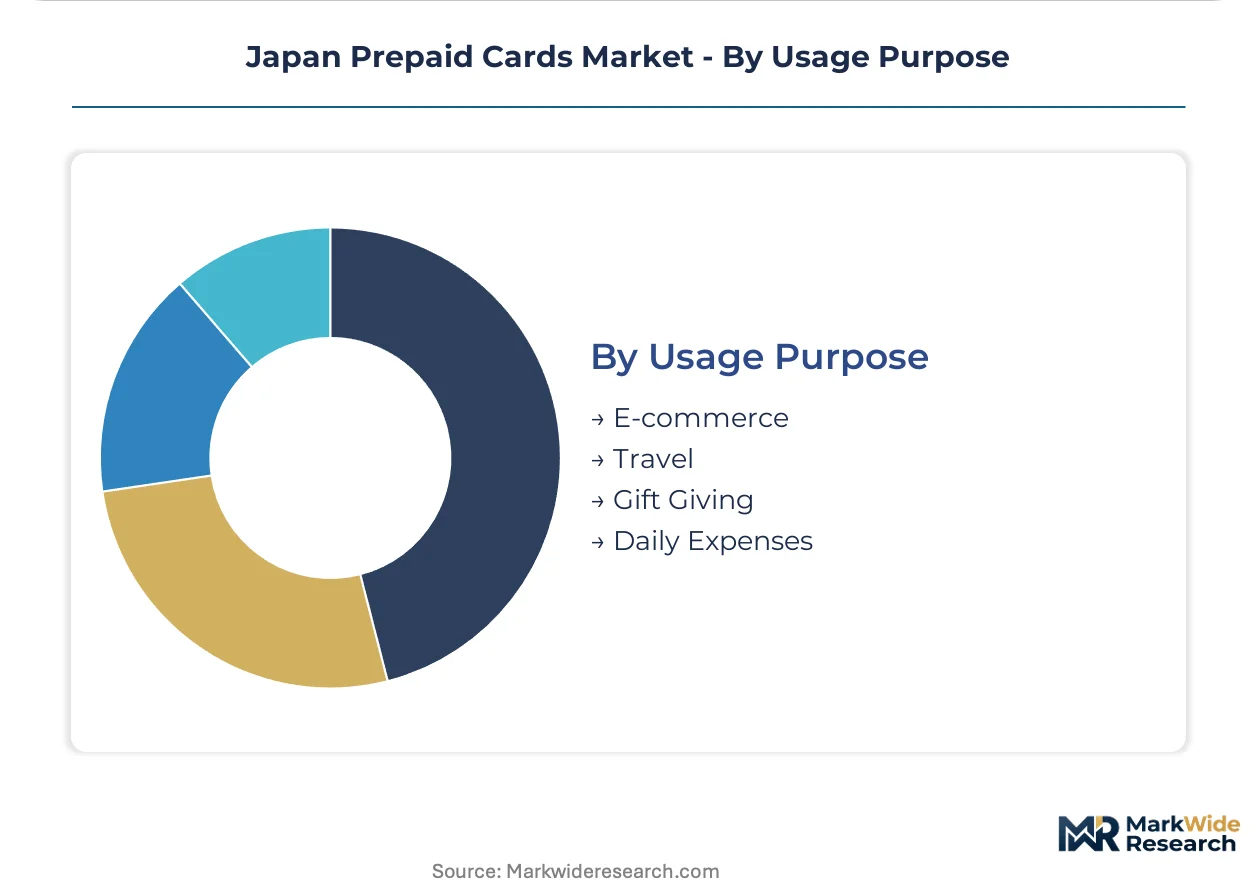
Daily Expenses holds the transaction volume lead, with E-commerce posting the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's prepaid card workforce concentrates in the Greater Tokyo metropolitan area, where transit-integrated IC chip infrastructure anchors national transaction volume and technical talent pools.
Kanto/Tokyo
The Kantō corridor dominates prepaid card circulation through commuter rail dependency and dense retail networks. METI interoperability mandates for Felica-based IC chips standardize acceptance across JR East and private railway systems. Tokyo's Shibuya and Shinjuku districts host the highest concentration of contactless reload points and merchant onboarding activity.
Kansai/Osaka
Osaka's manufacturing and logistics sectors drive corporate prepaid adoption for supplier payments and contractor settlements. The FSA Payment Services Act applies uniform capital requirements across the Kansai financial hub. The Osaka-Nagoya industrial corridor sustains bulk issuance programs for enterprise expense management.
Chubu/Nagoya
Automotive supply chain firms in Aichi Prefecture utilize prepaid instruments for parts procurement and temporary worker compensation. JIS standards for IC chip interoperability reduce technical barriers for merchant acceptance in Nagoya's automotive parts districts. Toyota City and surrounding industrial zones concentrate B2B prepaid program administration.
Kyushu
Fukuoka's startup ecosystem experiments with prepaid-linked fintech services for younger demographics. Regional banks under FSA supervision partner with transit operators to extend IC chip networks beyond metropolitan cores. The Fukuoka City financial district anchors prepaid innovation pilots targeting Southeast Asian inbound tourism.
Hokkaido
Sapporo's aging population sustains demand for caregiver-reloadable prepaid products with simplified interfaces. Cash preference inertia in rural Hokkaido prefectures preserves convenience store reload infrastructure as critical access points. Seven-Eleven Japan's northern distribution network maintains physical prepaid card availability across sparsely populated sub-regions.
Japan Prepaid Cards Market Key Industry Players
The competitive structure tilts toward transit-integrated incumbents with proprietary IC chip networks. East Japan Railway Corp. and West Japan Railway Co. leverage rail infrastructure dominance to anchor prepaid circulation, while retail conglomerates control physical reload access. Three archetypes define positioning: transit operators with captive commuter bases, retail ecosystem bundlers, and trust bank-backed financial service arms. Competitive moves concentrate on API integration for corporate ERP connectivity and JIS standard partnerships to dissolve closed-loop boundaries.
Among transit-based issuers, East Japan Railway Corp. and West Japan Railway Co. exemplify infrastructure-anchored market presence. Rakuten Card Co., Ltd. occupies a position within the ecosystem bundler archetype, linking prepaid instruments to e-commerce and loyalty architectures. Seven & I Holdings Co. Ltd. anchors retail distribution dominance through convenience store reload networks spanning Hokkaido to Okinawa.
| Leading Market Players |
|---|
| East Japan Railway Corp. |
| SMBC Finance Service Co., Ltd. |
| Rakuten Card Co., Ltd. |
| Orient Corporation |
| Viewcard Co., Ltd. |
| Seven & I Holdings Co. Ltd. |
| West Japan Railway Co. |
| Rakuten Edy |
| Aeon Credit Service Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Corporate procurement departments' unbundling of incentive programs from traditional banking relationships is forcing issuers to restructure service packaging and compress margin structures across bulk issuance tiers.
Pricing Analysis
Bundled ecosystem pricing versus unbundled standalone issuance defines the competitive landscape. Three-tier pricing structure across premium corporate administration, standard retail reload, and economy gift card denominations captures divergent buyer willingness-to-pay. Price differentiation hinges on API integration depth and JIS certification tier for chip interoperability. Cost compression in mid-tier corporate products is intensifying because manufacturing and logistics firms in Osaka and Nagoya industrial zones negotiate volume-based rate cards. Corporate procurement departments exhibit lowest price sensitivity due to ERP integration switching costs, while individual retail consumers in rural prefectures demonstrate highest elasticity to reload fees.
Supply Chain Analysis
Workforce availability constraints in Taiwan and South Korea IC foundries are elevating lead times for Felica chip procurement. Japan's prepaid card manufacturing draws from Taiwan semiconductor packaging, South Korea memory components, and domestic JIS-certified assembly facilities. Single-source vulnerability concentrates in transit-integrated chip supply where East Japan Railway Corp. and West Japan Railway Co. maintain captive relationships with specific foundry partners. Distribution runs through Seven-Eleven Japan's convenience store network for physical reload access, complemented by Rakuten's digital ecosystem for online issuance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Japan prepaid card market functions as a regulatory compounder where FSA Payment Services Act capital requirements continuously elevate barriers and consolidate advantage among trust bank-backed incumbents.
For Market Incumbents: To counter mobile wallet substitution eroding float-based revenue, East Japan Railway Corp. and West Japan Railway Co. should deepen API connectivity with corporate ERP platforms to lock in manufacturing sector bulk issuance. Simultaneously, incumbents must extend Felica chip infrastructure into vending and hospitality verticals to capture transaction density that subsidizes peripheral network deployment. For New Entrants and Emerging Players: Simplified interface prepaid products with caregiver reload permissions represent the most penetrable white-space targeting Hokkaido's aging rural populations outside metropolitan transit corridors. Foreign visitor multi-currency instruments at Narita and Haneda airport corridors offer second entry vector. A go-to-market alliance with regional banks under FSA supervision provides compliant fund segregation without proprietary trust banking infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier fintech issuers possessing JIS-certified chip interoperability but lacking capital reserves to absorb forthcoming FSA fund safeguarding mandates. Long-term viability across the analysis window favors acquisition targets with existing corporate program administration capabilities and established reload network partnerships. The signal to watch is FSA guidance publication timing on structural separation requirements for float management operations.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration for Corporate ERP Connectivity | Locks in manufacturing and logistics sector bulk issuance against mobile wallet substitution. |
| Felica Chip Infrastructure Extension | Captures vending and hospitality transaction density across JR East and private railway networks. |
| JIS Standard Partnership Formation | Dissolves closed-loop boundaries and reduces merchant onboarding friction for hybrid products. |
| Trust Banking Relationship Establishment | Enables FSA-compliant fund segregation without structural separation of float management. |
| Regional Bank Alliance Construction | Provides compliant distribution access to aging rural populations in Hokkaido and Tohoku. |
Research Approach
Coverage spans Kantō, Kansai, Chubu, Kyushu, and Hokkaido, with primary inputs from each region's distinct prepaid card ecosystem. The approach combines structured interviews with prepaid program administrators at transit operators, corporate treasury officers at manufacturing firms, convenience store operations managers, and FSA regulatory affairs specialists, validated against secondary sources including METI electronic payment infrastructure standards, FSA Payment Services Act prudential filings, JIS chip interoperability specifications, and JR East and West Japan Railway Co. transit volume disclosures. Bottom-up transaction density modeling and top-down regulatory constraint analysis provide triangulation.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. The analytical framework segments by product type architecture, customer procurement behavior, distribution channel geography, and usage purpose integration depth. CAGRs derive from commuter rail dependency elasticities, corporate expense digitization velocity, and inbound tourism recovery patterns. Forecast inputs include Felica chip deployment trajectories and FSA capital requirement phase-in schedules.
The model holds under stable FSA regulatory implementation timelines; deviation in fund safeguarding guideline severity or METI interoperability mandate acceleration would shift competitive positioning. Forecasts reflect assumptions regarding transit commuter density persistence and corporate procurement unbundling continuity. Material deviation in mobile wallet substitution rates or inbound tourism recovery velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Middle East and Africa Real Time Payments Market
Payments
Payment Instruments Market
Payments
Epayment System Market
Payments
France Payments Market
Payments
Mobile Payment Transaction Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Japan POS Terminals Market
Payments
Third Party Payment Market
Payments
E-Wallet Market
Payments
United Arab Emirates Real Time Payments Market
Payments
Hungary POS Terminal Market
Payments
Vietnam Payments Market
Payments
New Zealand Payments Market
Payments
LAMEA Crypto Payment Gateway Market
Payments
United States POS Terminals Market