
 Retail Cash Management Market | 2026-2036
Retail Cash Management Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Cash Management Market Analytics
The capability gap between hardware-centric incumbents and software-native challengers is unwinding competitive dynamics across retail cash management. Glory Ltd. leverages its manufacturing scale in currency counters and coin sorters to sustain dominance in physical cash handling infrastructure. HighRadius anchors its position through cloud-native treasury automation that competes with traditional vault services. Oracle Corporation differentiates via enterprise-grade cash management software integrated with broader ERP ecosystems.
Retail cash management encompasses the systems, devices, and services that automate cash handling, verification, storage, and reconciliation across commercial environments, typically processing banknotes at speeds exceeding 1,000 notes per minute and maintaining 99.9% authentication accuracy through multi-spectral imaging. Its primary purpose is to reduce labor costs, shrinkage, and cash-in-transit risk while accelerating deposit velocity for high-volume merchants. Cash recyclers command the largest product type share as retailers prioritize closed-loop cash cycles that minimize vault deposits. Cloud solutions within the technology segment represent the fastest-expanding category, displacing on-premise deployments with API-first architectures that integrate POS, treasury, and banking systems. Vault services retain the deepest margin pools in the service type dimension due to insurance requirements and armored transport specialization.
The Federal Reserve's Cash Product Office shapes physical cash infrastructure standards in the United States, while the European Central Bank's framework for euro banknote handling equipment mandates specific fitness sorting thresholds across EU member states. PCI DSS compliance requirements govern how cash management software processes card-present transaction data alongside physical currency flows. Stakeholders must monitor how central bank digital currency pilots alter cash velocity assumptions and hardware depreciation cycles.
Market Dynamics
Cloud-native cash management architectures are compressing hardware replacement cycles as retailers demand API-first integration between point-of-sale systems and treasury platforms. This structural shift forces incumbents to reconfigure product portfolios around software subscription models while maintaining physical device revenue streams.
Growth Catalysts
- PCI DSS compliance mandates:Retailers processing card-present transactions alongside physical currency must deploy certified cash management software, accelerating replacement of non-compliant legacy systems in the United States.
- Supermarket automation:Self-checkout expansion drives demand for intelligent cash recyclers that authenticate banknotes through multi-spectral imaging while reducing labor hours at checkout lanes.
- Federal Reserve Cash Product Office standards:Updated fitness sorting thresholds for banknote handling equipment compel financial institutions to upgrade currency processing infrastructure.
Market Restraints
- Semiconductor supply concentration:Currency authentication sensors and processing chips rely on concentrated Asian foundry capacity, exposing hardware manufacturers to input volatility and extended lead times.
- Central bank digital currency substitution:Pilot programs for CBDCs in major economies threaten long-term cash velocity assumptions, compressing depreciation schedules for physical cash handling equipment.
- Armored transport oligopoly:Vault services depend on specialized insurance and logistics providers concentrated in urban corridors, limiting margin expansion for cash-in-transit operators.
Strategic Opportunities
- European Central Bank framework alignment:Euro banknote handling equipment mandates create standardization tailwinds for manufacturers certifying products across EU member states.
- API-first treasury convergence:Integration between cash recyclers, POS terminals, and banking platforms enables real-time liquidity visibility for mid-market retailers previously served by manual reconciliation.
- India cash-intensive retail:Organized retail expansion and RBI guidelines for cash handling create whitespace for automated solutions in a market with high physical currency dependence.
Industry Challenges
- Multi-spectral imaging expertise scarcity:Currency authentication engineering requires specialized optical and machine-learning talent that hardware manufacturers struggle to retain against software-native competitors.
- Legacy ERP integration complexity:Cloud cash management platforms must bridge on-premise enterprise resource planning systems through custom middleware, extending implementation timelines.
- EU AI Act compliance timelines:Machine-learning components in fraud detection modules face emerging regulatory scrutiny, requiring documentation and audit trails that slow product releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Cash Management Market |
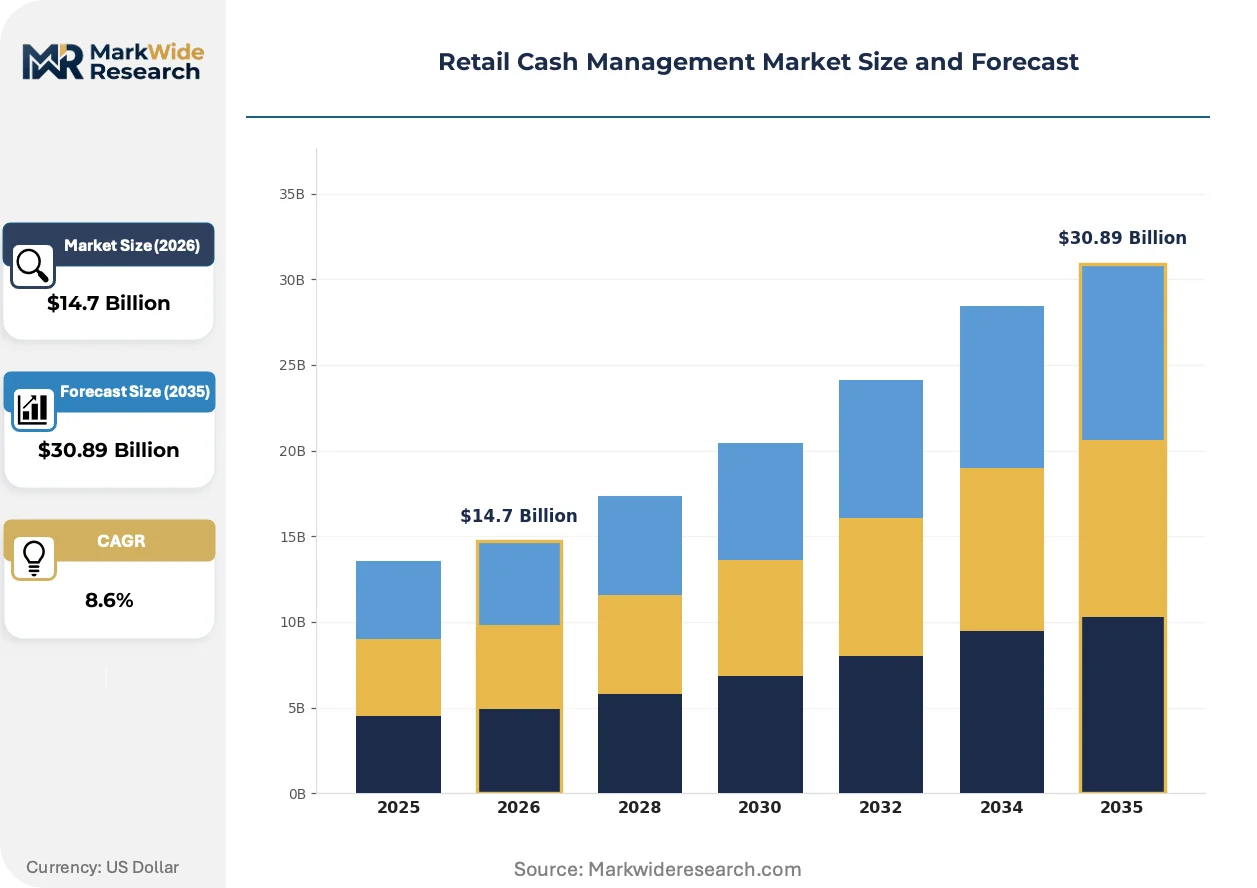
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Recyclers, Currency Counters, Coin Sorters, Cash Drawers Technology: Cash Management Software, Cloud Solutions, Mobile Applications, RFID Technology End User: Supermarkets, Retail Stores, ATMs, Restaurants Service Type: Vault Services, Transport Services, Maintenance, Consulting |
| Companies Covered | Giesecke & Devrient GmbH, Glory Ltd., Oracle Corporation, HighRadius, Kyriba, Infosys Limited, The Sage Group PLC, FIS, NTT Data, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Cash Management Market Evolving Landscape
Intelligent cash recyclers are evolving from standalone authentication devices into networked treasury nodes that stream transaction data directly to banking APIs. This connectivity shift demands new engineering competencies and partnership structures across the value chain.
Multi-spectral imaging technology authenticates banknotes through ultraviolet, infrared, and magnetic sensors while detecting fitness for recirculation. Regional supermarket chains deploy these systems at self-checkout lanes to eliminate manual till counting. The hardware-software interface is bifurcating competitive positioning between manufacturers with captive sensor production and challengers sourcing commodity components.
The European Central Bank's framework for euro banknote handling equipment mandates specific fitness sorting thresholds that equipment must satisfy for recirculation eligibility. Manufacturers must recalibrate sensor arrays and software algorithms to meet these thresholds across multiple denominations. Currency processing service providers in Germany, France, and Italy face accelerated replacement schedules as older equipment falls outside compliance windows.
Mid-market retailers are unbundling after-sales service contracts from hardware purchases, preferring outcome-based maintenance tied to uptime guarantees rather than fixed-term service agreements. Independent service organizations capture this demand through remote diagnostics and predictive parts replacement. This procurement evolution is most visible in the United Kingdom and Netherlands where retailer buying consortia negotiate standardized service level agreements across multiple locations.
Retail Cash Management Market Segmentation
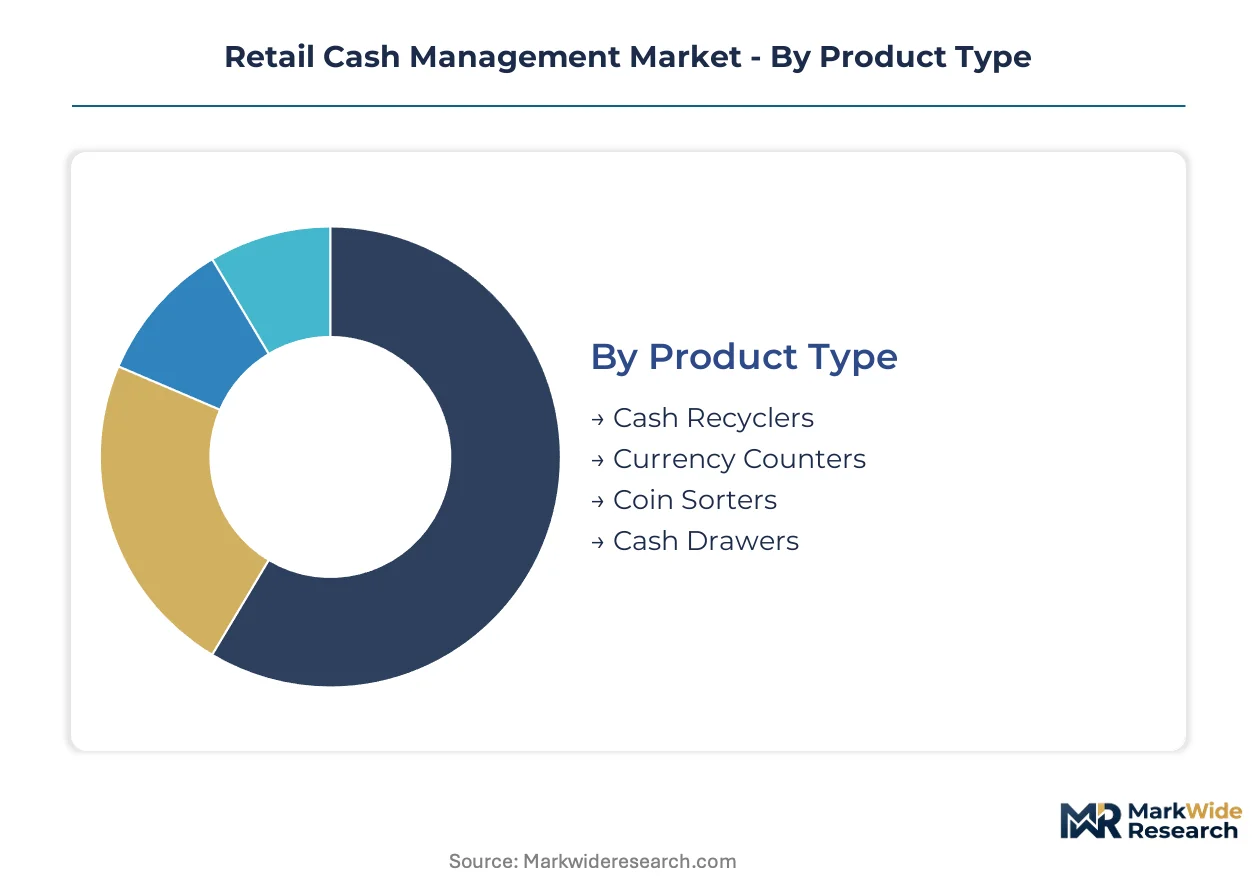
Retail cash management segmentation reveals how hardware durability, software architecture, and service intensity create divergent margin profiles across deployment contexts. Understanding these splits enables vendors to align certification investments with the specific compliance and throughput requirements of each buyer category.
Product Type:
Federal Reserve Cash Product Office fitness standards and ECB recirculation thresholds impose distinct authentication specifications on each hardware category, forcing manufacturers to calibrate sensor arrays and processing speeds to regulatory minimums.
- Cash Recyclers:Closed-loop devices authenticate, store, and redistribute banknotes through multi-spectral imaging at speeds exceeding 1,000 notes per minute. Supermarket self-checkout lanes in the United States drive concentrated demand as retailers eliminate manual till reconciliation and reduce cash-in-transit frequency.
- Currency Counters:Batch-processing machines verify denomination and fitness through ultraviolet and magnetic detection without storage capability. Bank branches and large-format retail stores in Germany deploy these systems for high-volume deposit preparation ahead of vault collection.
- Coin Sorters:Gravity-fed and sensor-based machines classify mixed coinage by denomination and metallic signature.
- Cash Drawers:Lockable till inserts with electronic monitoring for point-of-sale integration.
Cash recyclers handle the majority of throughput; cloud-connected recyclers are gaining share fastest as API integration becomes mandatory.
Technology:
PCI DSS compliance timelines and API maturity differentiate adoption velocity across software architectures, with cloud-native platforms displacing on-premise installations where treasury teams prioritize real-time visibility over data sovereignty.
- Cash Management Software:Enterprise-grade applications reconcile POS transactions, vault deposits, and banking APIs through middleware connectors. Mid-market retailers in the United Kingdom favor subscription models that bundle compliance updates and remote diagnostics.
- Cloud Solutions:API-first architectures stream transaction data directly to banking platforms without local server infrastructure. European supermarket chains accelerate migration as ECB reporting requirements demand centralized audit trails.
- Mobile Applications:Lightweight interfaces for manager-level cash monitoring and exception alerting.
- RFID Technology:Chip-based tracking for cash cassette and till insert inventory management.
Cash management software handles the majority of throughput; cloud solutions are expanding most quickly on share.
End User:
Transaction volume density and labor cost structure determine hardware specification intensity, with high-frequency environments justifying premium authentication equipment that lower-throughput settings cannot amortize.
- Supermarkets:High-velocity checkout environments deploy intelligent recyclers at self-service lanes to compress labor hours and shrinkage simultaneously. Chains across the United States standardize on multi-spectral imaging to meet Federal Reserve fitness sorting thresholds without manual pre-sorting.
- Retail Stores:General merchandise outlets balance authentication capability against capital constraints, often selecting currency counters with basic fitness detection. Franchised operations in France prioritize compact footprints that fit behind existing service counters.
- ATMs:Cash dispensing and deposit-taking terminals with integrated recycling modules.
- Restaurants:Lower-volume cash handling with emphasis on drawer-level accountability and end-of-shift reconciliation speed.
Supermarkets handle the majority of throughput; retail stores are climbing the fastest on automation penetration.
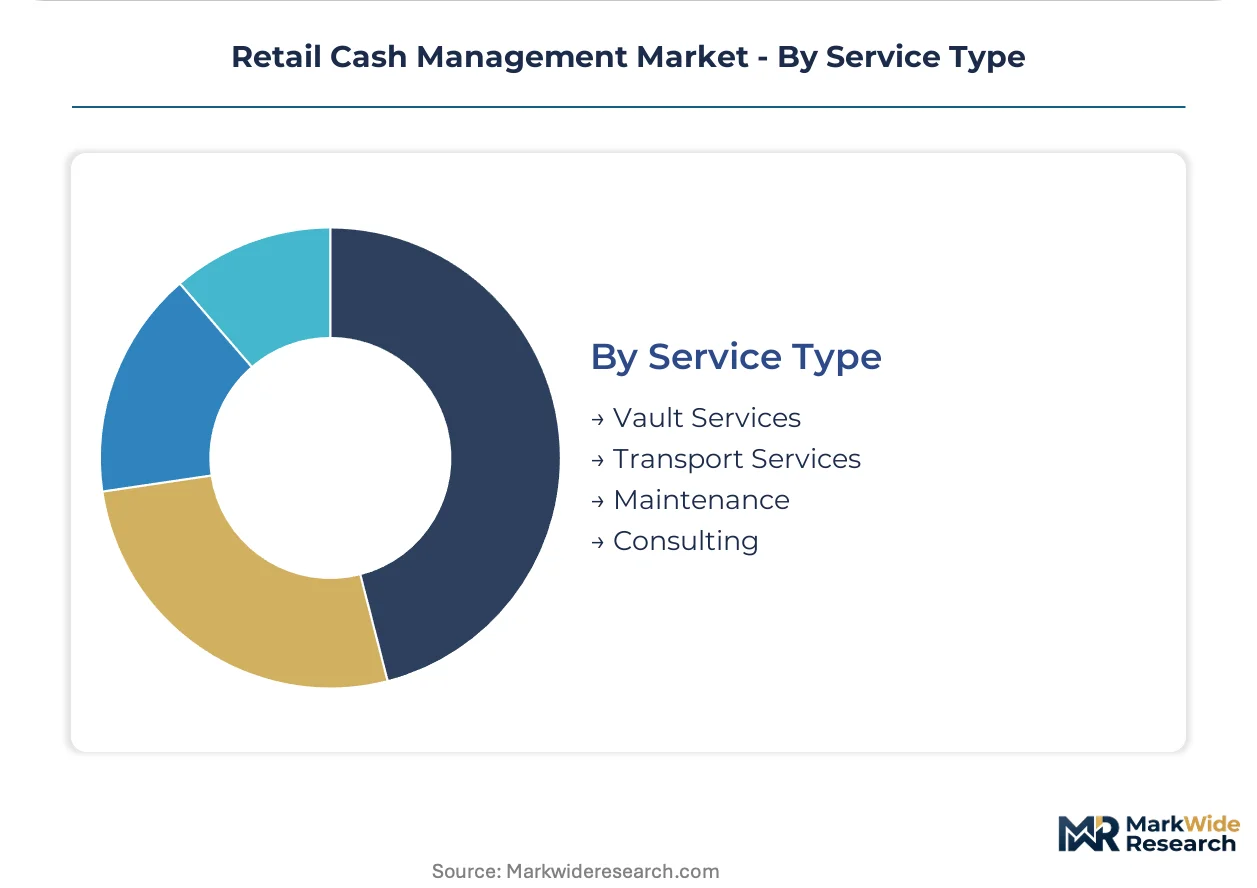
Service Type:
Insurance requirements and armored transport specialization concentrate margin pools in physical custody services, while software maintenance contracts face commoditization pressure from outcome-based pricing models.
- Vault Services:Insured storage with armored collection and deposit preparation, governed by specialized logistics and liability underwriting. Urban corridors in the United States exhibit oligopolistic provider concentration that limits price competition.
- Transport Services:Armored vehicle operations linking retail locations to banking infrastructure or centralized vaults. European operators navigate ECB framework compliance for cross-border cash movements.
- Maintenance:Preventive and corrective service for hardware uptime guarantees.
- Consulting:Workflow optimization and compliance advisory for cash handling procedures.
Vault services handle the majority of throughput; maintenance contracts are shifting fastest toward outcome-based structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States accept premium pricing for cloud-native treasury platforms, while price sensitivity intensifies across European mid-market retailers and Indian organized retail chains where hardware durability drives procurement decisions.
United States
Supermarket chains deploy intelligent cash recyclers at self-checkout lanes to compress labor costs and shrinkage simultaneously. The Federal Reserve's Cash Product Office fitness sorting standards compel financial institutions to upgrade currency processing infrastructure. Chicago and Dallas metropolitan clusters concentrate vault service operations where armored transport providers navigate oligopolistic market structures.
Germany
Bank branches and large-format retailers prioritize currency counters with ECB-compliant fitness detection for high-volume deposit preparation. The European Central Bank's framework for euro banknote handling equipment mandates specific recirculation thresholds across EU member states. Frankfurt and Munich industrial corridors host equipment certification laboratories where manufacturers recalibrate sensor arrays for multi-denominational compliance.
United Kingdom
Mid-market retailers unbundle after-sales service contracts in favor of outcome-based maintenance with uptime guarantees. PCI DSS compliance mandates accelerate replacement of legacy cash management software in card-present transaction environments. London and Birmingham buying consortia negotiate standardized service level agreements across multi-location retail networks.
India
Organized retail expansion drives demand for automated cash handling solutions in a market with high physical currency dependence. Reserve Bank of India guidelines for cash handling create regulatory tailwinds for equipment standardization. Mumbai and Bangalore retail corridors witness accelerated deployment of intelligent recyclers as modern trade formats penetrate tier-two cities.
Japan
ATM networks integrate recycling modules to optimize cash replenishment cycles and reduce armored transport frequency. METI standards govern machine-readable authentication requirements for banknote handling equipment. Tokyo and Osaka metropolitan banking clusters concentrate demand for compact, high-throughput currency processing systems.
Retail Cash Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hardware-centric incumbents competing against cloud-native challengers for treasury automation contracts. The upper tier combines manufacturing scale in physical cash handling with software subscription revenue streams. Three archetypes dominate: integrated hardware-software providers, pure-play cloud treasury platforms, and enterprise ERP extenders. Competitive moves center on API-first architecture development and strategic partnerships with banking networks to embed cash management into broader financial workflows.
Within the integrated hardware tier, Glory Ltd. exemplifies manufacturing-scale dominance in currency counters and coin sorters. HighRadius and Oracle Corporation anchor the cloud-native and enterprise-extender positions respectively, with the former representing API-first treasury automation and the latter embedding cash management within broader ERP ecosystems. These three companies illustrate the capability bifurcation reshaping competitive dynamics across retail cash management.
| Leading Market Players |
|---|
| Giesecke & Devrient GmbH |
| Glory Ltd. |
| Oracle Corporation |
| HighRadius |
| Kyriba |
| Infosys Limited |
| The Sage Group PLC |
| FIS |
| NTT Data |
| Others |
Value Network & Pricing Analysis
Cloud-native software subscriptions displacing perpetual licensing simultaneously redistribute margin pools toward recurring revenue streams and compress hardware procurement cycles as buyers prioritize API integration over capital-intensive device purchases. This substitution dynamic reshapes supply geography by reducing dependence on Asian semiconductor foundries for authentication chips while elevating pricing power for software-native vendors with captive treasury automation platforms.
Pricing Analysis
Outcome-based maintenance contracts with uptime guarantees now drive lifetime value more than upfront hardware margins. Pricing stratifies across premium certification tiers, volume scale commitments, and bundled software subscriptions. Cost compression in mid-market segments intensifies as retailer buying consortia negotiate standardized service level agreements across multi-location networks. Large-format supermarket chains exhibit lowest price sensitivity due to labor cost savings from intelligent recycler deployment, while franchised retail stores in France face acute capital constraints.
Supply Chain Analysis
Strategic stockpiling of multi-spectral imaging sensors and processing chips dominates inventory strategy as lead time volatility from concentrated Asian foundry capacity disrupts production schedules. Hardware manufacturing draws from Taiwan, South Korea, and Japan for semiconductor components, while optical sensor arrays source from German and Japanese precision optics suppliers. Single-source vulnerability in currency authentication chip fabrication exposes equipment manufacturers to input cost volatility. Distribution runs through regional banking equipment distributors and direct enterprise sales teams serving major retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Retail cash management exhibits cyclical recovery characteristics as Federal Reserve fitness standard upgrades and ECB recirculation mandates trigger replacement waves across installed equipment bases. Supermarket automation cycles and central bank digital currency uncertainty create alternating periods of accelerated investment and deferred capital commitment.
For Market Incumbents: Compound software subscription revenue through API-first treasury platform development while maintaining physical device manufacturing scale. Defend against cloud-native challengers by embedding cash recyclers within broader ERP ecosystems through middleware partnerships. Prioritize certification investment for ECB framework compliance across multi-denominational sensor recalibration to lock out unqualified competitors.
For New Entrants and Emerging Players: PCI DSS certification fast-track enables rapid market entry among mid-market retailers replacing non-compliant legacy systems. White-space concentrates in India's organized retail expansion and United Kingdom buying consortia seeking outcome-based maintenance contracts. Go-to-market positioning should emphasize remote diagnostics capability and predictive parts replacement to capture unbundled service demand.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed hardware manufacturers lacking cloud-native software capabilities. Long-term viability over the next decade hinges on successful software transformation and recurring revenue scale. Acquisition targets should demonstrate API integration traction with major banking networks. The signal to watch is central bank digital currency pilot acceleration compressing physical equipment depreciation assumptions.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables real-time treasury visibility between POS terminals and banking systems for mid-market retailers. |
| ECB Certification Investment | Unlocks euro banknote handling equipment mandates across Germany, France, and Italy replacement cycles. |
| Outcome-Based Service Contracts | Captures unbundled maintenance demand from United Kingdom and Netherlands retailer buying consortia. |
| Strategic Banking Partnerships | Embeds cash management within broader financial workflows through direct API integration. |
| India Market Entry | Addresses RBI-guided cash handling standardization in high physical currency dependence markets. |
Research Methodology
Operator-level perspectives from treasury automation directors, retail operations executives, banking technology procurement leads, and armored transport logistics managers anchored the qualitative base. These primary insights combined with secondary validation from Federal Reserve Cash Product Office technical bulletins, European Central Bank equipment framework documentation, PCI DSS compliance guidelines, and SEC filings from publicly traded equipment manufacturers. Bottom-up demand modeling across supermarket chains, retail formats, and banking networks triangulated against top-down market sizing from industry association data.
Sensitivity analysis tested forecast robustness across central bank digital currency adoption scenarios, semiconductor supply disruption durations, and software subscription conversion rates. Segmentation dimensions modeled include product type, technology architecture, end-user format, and service intensity across the projection horizon. CAGRs derived from equipment replacement cycle analysis, cloud migration velocity assumptions, and regulatory compliance timeline enforcement. Industry-specific inputs encompassed Federal Reserve fitness sorting threshold implementation schedules and ECB recirculation mandate phase-in periods.
Decision-makers should treat outputs as directional under assumptions of continued physical cash velocity and stable regulatory compliance timelines; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding supermarket automation penetration and cloud-native platform adoption. Revision becomes warranted when central bank digital currency pilot expansion crosses thresholds that materially alter cash handling equipment depreciation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Bus Card Reader Market
Payments
Credit Card Issuance Services Market
Payments
China POS Terminals Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Global Financial Cards and Payments Market
Payments
Ghana Mobile Money Market
Payments
North America POS Terminal Market
Payments
Crypto Payment Gateway Market
Payments
Norway Mobile Payments Market
Payments
Mexico POS Terminals Market
Payments
Smart Payment Market
Payments
North America Accounts Payable Automation Market
Payments
Japan Payments Market
Payments
Global Payment Gateways Market
Payments
Europe Accounts Payable Automation Market
Payments
Payment Analytics Software Market