
 Vietnam Mobile Payments Market | 2026-2036
Vietnam Mobile Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Mobile Payments Market Analytics
Small business owners is rotating toward integrated payment acceptance tools that bundle inventory tracking with settlement services. MoMo leverages its agent network density to sustain merchant lock-in across provincial Vietnam. ZaloPay competes through social-commerce payment flows embedded within Vietnam's dominant messaging ecosystem. ViettelPay anchors its position via telecommunications subscriber data that streamlines know-your-customer verification for rural users.
Vietnam mobile payments encompass digital fund transfers executed through software applications on connected devices, relying on tokenized credential vaulting, real-time gross settlement integration, and NFC or QR code proximity protocols to replace cash and card instruments. The primary commercial purpose centers on reducing friction in consumer-to-business and peer-to-peer value exchange while generating transaction data for credit scoring and targeted financial services. E-wallets capture the dominant share of transaction volume, though QR code infrastructure is expanding fastest as the National Payment Corporation of Vietnam drives interoperable standardization across banking and non-banking participants. Peer-to-peer transfers remain structurally mature with thin margins, while bill payments concentrate value through utility partnerships that embed recurring revenue streams.
The State Bank of Vietnam governs licensing through circulars that cap foreign ownership in payment intermediaries and mandate interoperability protocols, while the Ministry of Information and Communications enforces cybersecurity standards under the Cybersecurity Law that shape data localization requirements for transaction records. The National Payment Corporation of Vietnam operates the switching infrastructure that determines technical access terms for private wallet providers, creating a regulated utility layer beneath competitive consumer applications. Stakeholders must monitor how forthcoming central bank digital currency pilots alter settlement economics and wallet provider business models.
Market Dynamics
Interoperability mandates from the State Bank of Vietnam are compressing wallet provider margins while forcing consolidation of technical infrastructure around the National Payment Corporation of Vietnam's switching layer.
Growth Catalysts
- SBV Circular 23/2019:Licensing clarity for non-bank payment intermediaries reduced regulatory ambiguity and accelerated e-wallet market entry for fintech ventures.
- QR code standardization:The National Payment Corporation of Vietnam's VietQR protocol unified fragmented acceptance infrastructure, enabling merchant portability across competing wallet applications.
- Provincial merchant digitization:Ho Chi Minh City and Hanoi concentration of smartphone penetration and banked populations creates network effects that pull adjacent provinces into digital payment adoption.
Market Restraints
- Foreign ownership caps:SBV regulations limiting foreign stakes in payment intermediaries to 49% constrain capital inflows and technical partnerships with global payment networks.
- Cash infrastructure persistence:Vietnam's dense network of informal money changers and cash-on-delivery logistics providers sustains transactional friction that digital platforms cannot fully displace.
- Agent network economics:Thin merchant discount rates in peer-to-peer transfers compress commissions available to sustain rural agent liquidity provisioning.
Strategic Opportunities
- Central bank digital currency pilots:The State Bank of Vietnam's planned retail CBDC trials could reposition wallet providers as distribution interfaces rather than settlement counterparties.
- Embedded finance convergence:Integration of payment flows with ride-hailing, food delivery, and e-commerce platforms creates captive transaction ecosystems with higher switching costs.
- Rural KYC streamlining:Telecommunications subscriber data linkage enables simplified identity verification for unbanked populations in Mekong Delta and Central Highlands provinces.
Industry Challenges
- Interoperability implementation:Technical integration with the National Payment Corporation of Vietnam's switching infrastructure demands substantial API development and compliance certification timelines.
- Cybersecurity Law data localization:Ministry of Information and Communications mandates for domestic transaction record storage impose server infrastructure investments that strain lean fintech balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Mobile Payments Market |
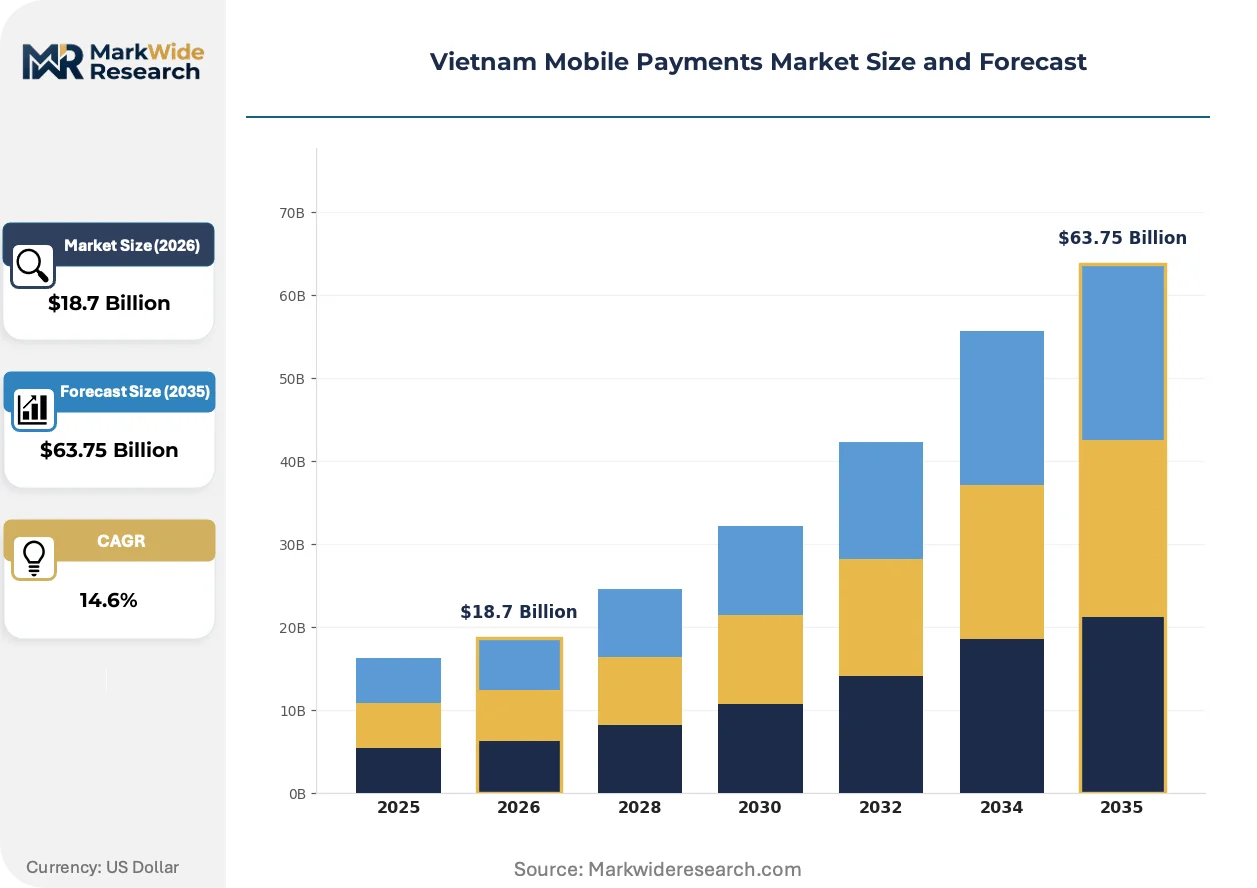
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: QR Code, E-Wallets, Direct Carrier Billing, NFC Transaction Type: Peer-to-Peer, Online Shopping, Bill Payments, In-Store Payments Customer Segment: Millennials, Small Businesses, Large Enterprises, Freelancers Device Type: Smartphones, Tablets, Wearables, Point of Sale Terminals |
| Companies Covered | MoMo, ZaloPay, ViettelPay, ShopeePay, VNPAY, National Payment Corporation of Vietnam, GrabPay, OnePay, AirPay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Mobile Payments Market Evolving Landscape
Tokenized credential vaulting and real-time settlement integration are compressing the functional gap between e-wallets and traditional deposit accounts, reshaping competitive positioning around financial service bundling rather than payment execution alone.
Biometric authentication protocols anchored in facial recognition and fingerprint matching are supplanting SMS one-time passwords as the primary transaction authorization layer. Tier-one banks and dominant wallet providers have deployed these systems across Ho Chi Minh City and Hanoi merchant networks since 2023. This shift is compressing fraud-related chargeback liabilities while raising capital requirements for liveness detection and encrypted template storage infrastructure.
The Cybersecurity Law enforcement by the Ministry of Information and Communications mandates localized data centers for all transaction records exceeding defined thresholds. Payment intermediaries must maintain domestic server capacity with specified encryption standards and audit accessibility. Wallet providers with existing cloud architectures are reconfiguring technical stacks to comply, while new entrants factor these infrastructure costs into licensing applications.
Merchant procurement of payment acceptance tools is fragmenting from standalone terminals toward integrated software platforms combining inventory, payroll, and settlement functions. Small business owners in Vietnam's urban centers now evaluate payment providers on ecosystem breadth rather than transaction fees alone. This pattern concentrates vendor selection authority with platform aggregators in Ho Chi Minh City's retail and food service verticals.
Vietnam Mobile Payments Market Segmentation
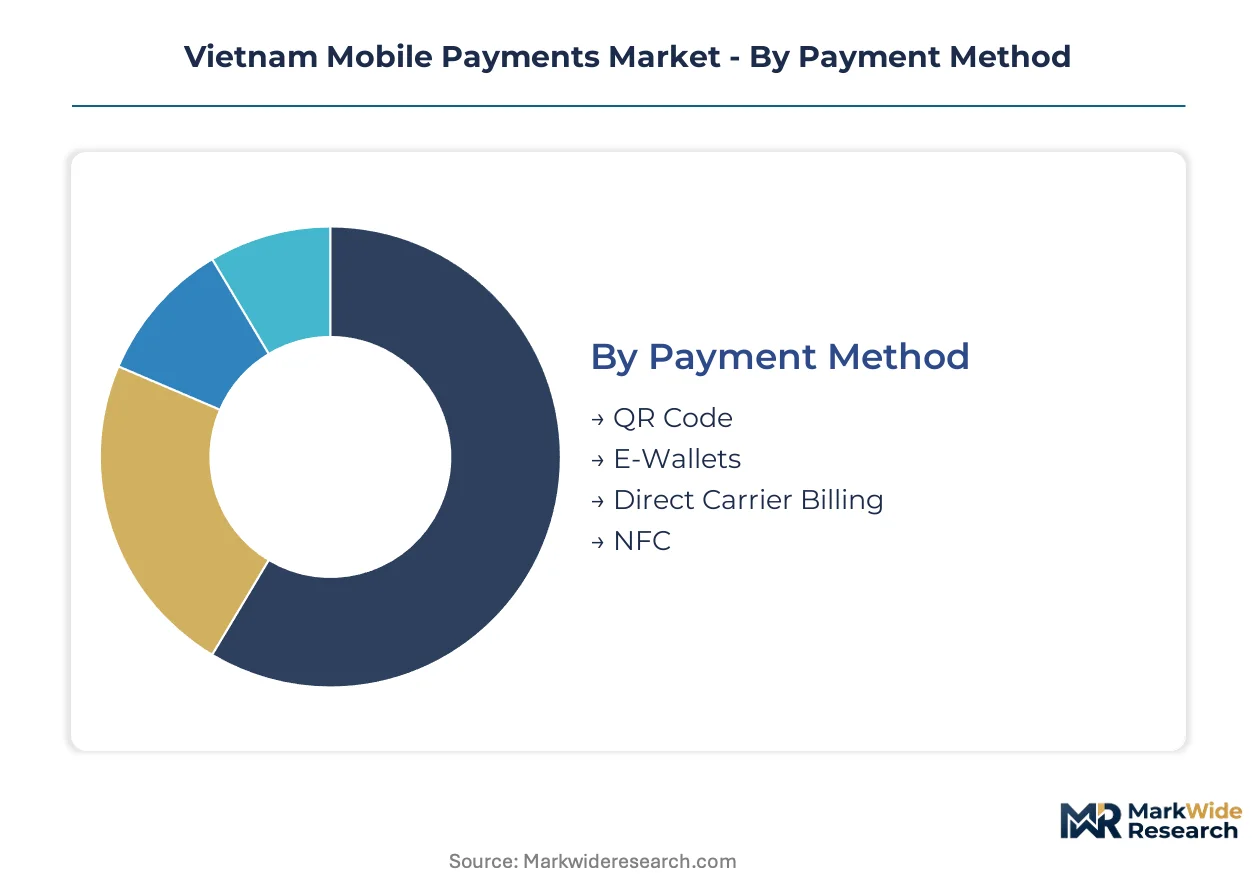
Segmentation in Vietnam's mobile payments landscape reveals how regulatory mandates and infrastructure asymmetries create divergent competitive pressures across transaction modalities. Each dimension exposes distinct substitution vulnerabilities and margin structures that determine provider positioning strategies.
Payment Method:
QR code infrastructure faces the most acute substitution pressure from NFC deployment as smartphone penetration deepens in Ho Chi Minh City and Hanoi merchant corridors.
- QR Code:Optical scan protocols dominate merchant acceptance due to minimal hardware requirements and National Payment Corporation of Vietnam interoperability mandates. Demand concentrates in street-level retail and food service verticals where transaction velocity and cost sensitivity override friction concerns.
- E-Wallets:Software-based credential vaulting captures the majority of consumer-initiated transfers through tokenized account linking. Ho Chi Minh City's dense agent network sustains liquidity provisioning that provincial markets struggle to replicate, compressing rural adoption timelines.
- Direct Carrier Billing:Telco-integrated charging mechanisms address underbanked populations lacking traditional payment credentials. Subscriber data verification streamlines onboarding for Mekong Delta users outside formal banking coverage.
- NFC:Proximity chip protocols remain concentrated in premium retail and transit applications requiring sub-second authorization. Hardware deployment costs limit penetration beyond tier-one urban corridors.
QR code infrastructure anchors the volume base while NFC gains share at the steepest rate among merchant-facing acceptance technologies.
Transaction Type:
Cost tier differentiation separates thin-margin peer transfers from value-rich embedded finance flows.
- Peer-to-Peer:Account-to-account transfers between individuals constitute the most mature transaction category with compressed economics. Network effects in Hanoi and Ho Chi Minh City sustain volume concentration despite minimal revenue per transaction.
- Online Shopping:E-commerce checkout flows generate merchant discount revenue through platform-embedded wallet integrations. Social-commerce marketplaces in Vietnam's urban centers drive checkout preference consolidation around dominant super-app ecosystems.
- Bill Payments:Recurring utility and telecommunications settlements create predictable revenue streams through partnership exclusivity arrangements. State-owned utility providers in Vietnam maintain centralized procurement processes that favor established intermediaries.
- In-Store Payments:Physical merchant acceptance is expanding fastest through VietQR standardization and provincial agent recruitment. Small business digitization in Central Highlands provinces lags the Mekong Delta corridor due to banking infrastructure gaps.
Peer-to-Peer transfers anchor the volume base while in-store payments climb the fastest as merchant digitization accelerates beyond metropolitan cores.
Customer Segment:
Application-specific requirements fragment procurement authority across demographic and entity-type boundaries.
- Millennials:Digital-native consumers aged 25-40 drive feature adoption velocity for biometric authentication and social payment splitting. Concentrated in Ho Chi Minh City and Hanoi employment clusters with highest smartphone replacement rates.
- Small Businesses:Informal sector merchants require integrated inventory-settlement platforms rather than standalone acceptance tools. Agent network density determines provider selection across Vietnam's provincial retail corridors.
- Large Enterprises:Corporate treasury functions demand API-accessible bulk disbursement and collections infrastructure with reconciliation automation. Procurement concentrates among Vietnam's state-linked conglomerates with centralized vendor qualification.
- Freelancers:Gig economy participants need rapid settlement and cross-border remittance capabilities. Platform-embedded wallets in ride-hailing and delivery services capture this segment through captive onboarding.
Millennials anchor the volume base while small businesses expand most quickly as provincial merchant digitization campaigns intensify.
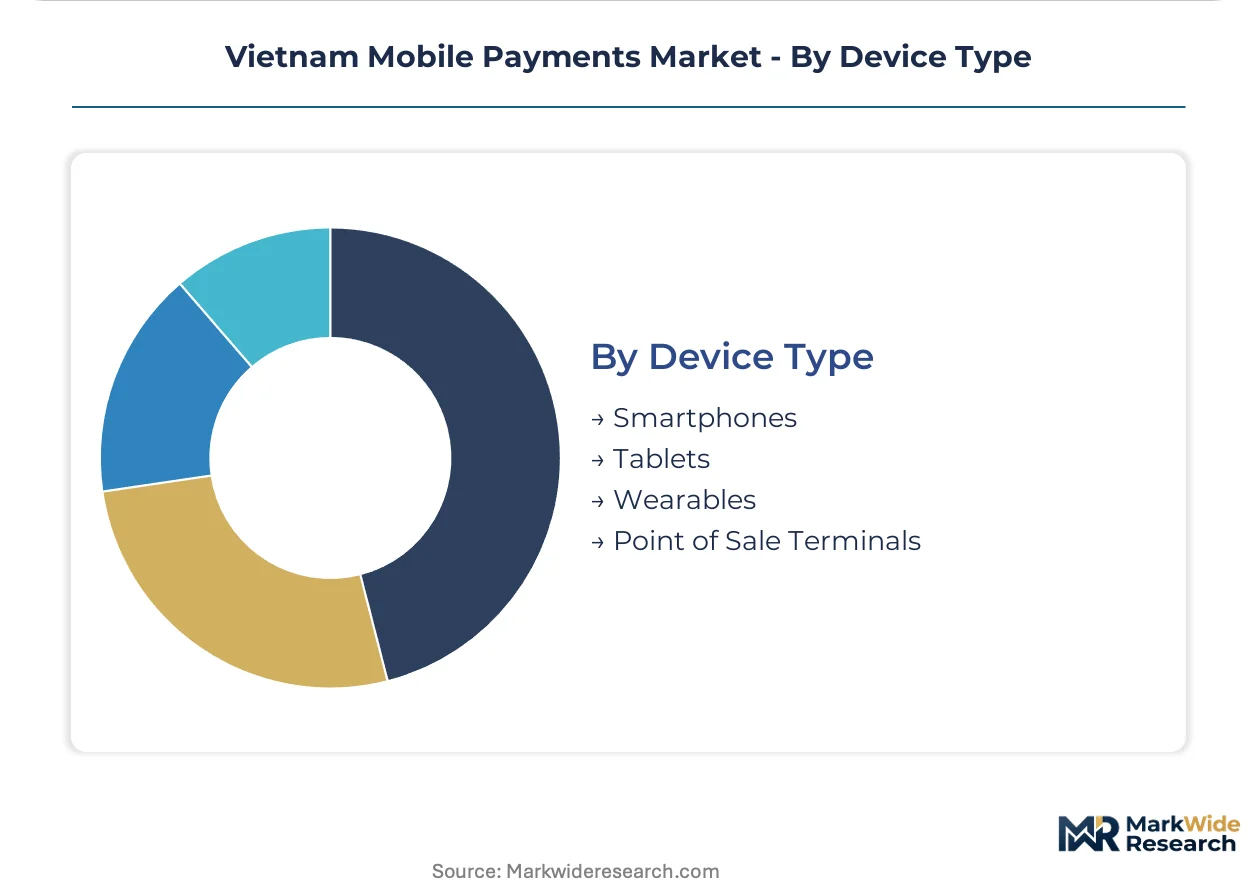
Device Type:
Maturity curves diverge sharply between ubiquitous smartphones and nascent wearable form factors.
- Smartphones:Primary transaction interface for virtually all consumer-initiated payments through app-based wallet access. Device replacement cycles in Vietnam's urban centers accelerate biometric-enabled security adoption.
- Tablets:Merchant-facing acceptance tools in fixed-location retail and hospitality settings with larger screen real estate for inventory integration. Concentrated in Ho Chi Minh City's food service verticals.
- Wearables:Watch and band form factors enable contactless transit and convenience store purchases without phone retrieval. Limited to early adopters in Hanoi and Ho Chi Minh City premium retail corridors.
- Point of Sale Terminals:Dedicated hardware for high-volume merchants requiring printed receipts and multi-tender acceptance. State Bank of Vietnam certification requirements constrain new entrant deployment.
Smartphones anchor the volume base while wearables gain share at the steepest rate among emerging device categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Payment Corporation of Vietnam's VietQR switching infrastructure anchors digital payment penetration across the country's economic corridors. This centralized technical layer enables interoperability mandates that reshape competitive access in metropolitan and provincial markets alike.
Ho Chi Minh City
Smartphone penetration rates exceeding national averages drive merchant digitization velocity in Vietnam's commercial capital. State Bank of Vietnam circulars on e-wallet licensing concentrate operational headquarters and technical development clusters in this southern hub. District 1 and District 7 host dense agent networks that sustain liquidity provisioning for provincial expansion.
Hanoi
Government procurement of digital settlement services concentrates demand among state-linked conglomerates headquartered in the northern capital. Ministry of Information and Communications enforcement of Cybersecurity Law data localization requirements shapes server infrastructure investments by payment intermediaries. Cau Giay and Ba Dinh districts anchor fintech development corridors with proximity to regulatory bodies.
Mekong Delta
Agricultural value chain digitization creates demand for rural-appropriate payment interfaces among farming cooperatives and commodity traders. Telecommunications subscriber data linkage streamlines know-your-customer verification for unbanked populations outside formal banking coverage. Can Tho City emerges as the regional hub for agent network recruitment and merchant onboarding campaigns.
Central Highlands
Banking infrastructure gaps delay merchant digitization timelines relative to coastal corridors with denser branch networks. Provincial People's Committee initiatives promoting cashless tourism payments target Da Lat's hospitality sector for QR code acceptance expansion. Coffee export logistics chains drive corporate treasury demand for API-accessible bulk disbursement infrastructure.
Vietnam Mobile Payments Market Competitive Landscape
Listed leaders compete with private specialists across agent network density and social-commerce integration dimensions. Market structure tilts toward consolidation around three dominant wallet ecosystems, with telecommunications-captive and e-commerce-embedded providers occupying distinct competitive tiers. Strategic archetypes include agent-network heavyweights, messaging-platform integrators, and telecom-data leveraged entrants. Competitive moves concentrate on merchant ecosystem bundling and provincial agent recruitment rather than price-based customer acquisition.
Within the agent-network tier, MoMo exemplifies density-driven merchant lock-in across provincial Vietnam. ZaloPay occupies a position anchored in social-commerce payment flows embedded within dominant messaging infrastructure. ViettelPay represents telecommunications-captive positioning via subscriber data streamlining rural know-your-customer verification. These three archetypes illustrate how divergent parent-company assets reshape competitive positioning around distribution depth rather than transaction pricing alone.
| Leading Market Players |
|---|
| MoMo |
| ZaloPay |
| ViettelPay |
| ShopeePay |
| VNPAY |
| National Payment Corporation of Vietnam |
| GrabPay |
| OnePay |
| AirPay |
| Others |
Value Network & Pricing Analysis
Long-term agent exclusivity contracts lock in both rural liquidity access and merchant discount rate visibility across provincial corridors. State Bank of Vietnam interoperability mandates compress these contract durations while forcing standardization of settlement fees around National Payment Corporation of Vietnam switching tariffs.
Pricing Analysis
Volume-discount tiering structures separate micro-merchants processing under one hundred monthly transactions from enterprise chains negotiating basis-point reductions. Pricing stratifies across premium API-integrated tiers, standard e-wallet acceptance, and economy cash-out services for unbanked agents. Cost compression in the economy tier is intensifying because thin merchant discount rates cannot sustain rural agent commissions. Micro-merchants in Mekong Delta provinces exhibit highest price sensitivity, while state-linked conglomerates in Hanoi prioritize reconciliation automation over transaction fees.
Supply Chain Analysis
National Payment Corporation of Vietnam's switching infrastructure constitutes a technical chokepoint that all private wallet providers must traverse for interoperability compliance. Hardware supply for point-of-sale terminals draws from China, Taiwan, and South Korea, while server infrastructure for data localization mandates sources from domestic Vietnamese facilities and Singaporean cloud regions. Single-source vulnerability concentrates in NFC chip procurement from Taiwanese semiconductor foundries. Distribution runs through tiered agent networks where provincial master agents cascade liquidity to street-level sub-agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's mobile payment sector has reached a platform-economics inflection where National Payment Corporation of Vietnam's VietQR standardization forces wallet providers to compete on ecosystem breadth rather than proprietary infrastructure control.
For Market Incumbents: Secure exclusive utility billing partnerships before state-owned providers consolidate procurement around established intermediaries. Deepen backward integration into agent network technology to defend against telecommunications-captive entrants leveraging subscriber data for rural KYC streamlining. Lock in merchant ecosystem bundling through inventory-settlement platform integration. For New Entrants and Emerging Players: Differentiate on embedded finance convergence with ride-hailing and food delivery platforms where captive transaction ecosystems create defensible switching costs. Target Central Highlands merchant digitization where banking infrastructure gaps delay incumbent penetration. Pursue telecommunications data partnerships as the primary go-to-market angle for unbanked population onboarding. For Investors and Strategic Acquirers: Agent-network infrastructure specialists with proven provincial liquidity provisioning capabilities represent the most viable acquisition target archetype for platform consolidation plays. Long-term viability hinges on positioning ahead of central bank digital currency pilots that could relegate wallet providers to distribution interfaces. Watch State Bank of Vietnam CBDC trial announcements as the critical inflection signal for business model recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Ecosystem Bundling | Integrated inventory-settlement platforms lock in small business switching costs beyond transaction pricing. |
| Provincial Agent Network Expansion | Density-driven liquidity provisioning in Mekong Delta and Central Highlands captures underbanked transaction flows. |
| Biometric Authentication Deployment | Facial recognition and fingerprint protocols reduce fraud liabilities while raising infrastructure capital requirements. |
| Telecommunications Data Partnership | Subscriber verification linkage streamlines rural KYC for populations outside formal banking coverage. |
| CBDC Distribution Interface Positioning | Early alignment with State Bank of Vietnam pilots preserves wallet relevance as settlement economics shift. |
Research Methodology
Initial hypotheses were tested against primary input from payment platform executives, merchant acquiring heads, regulatory affairs specialists at the State Bank of Vietnam, and provincial agent network operators and refined through secondary validation against National Payment Corporation of Vietnam interoperability filings, Ministry of Information and Communications Cybersecurity Law enforcement circulars, and State Bank of Vietnam licensing registries. Bottom-up transaction volume modeling and top-down GDP-correlated payment penetration estimates were triangulated to constrain forecast variance.
Variance decomposition across payment method, transaction type, customer segment, and device type dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from logistic adoption curves fitted to smartphone penetration trajectories and merchant digitization campaign timelines. Forecast inputs incorporated National Payment Corporation of Vietnam switching volume disclosures and provincial banking infrastructure density indices.
The analysis sits within stated boundaries; outcomes outside sustained State Bank of Vietnam interoperability enforcement or accelerated CBDC rollout timelines would require recalibration. Practitioners should keep alternative scenarios live as Cybersecurity Law data localization requirements and foreign ownership cap regulations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Australia Payments Market
Payments
POS Terminals Market
Payments
Global Financial Cards and Payments Market
Payments
Italy Gift Cards Market
Payments
Payment Orchestration Platform Market
Payments
Malta POS Terminal Market
Payments
India Buy Now Pay Later Services Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Transit Cards Market
Payments
France Payments Market
Payments
Portugal POS Terminals Market
Payments
Japan Payments Market
Payments
Europe Digital Transaction Management (DTM) Market
Payments
Portugal Mobile Payments Market
Payments
Global Point of Sale Terminals Market
Payments
Germany Gift Card and Incentive Card Market